
 Desktop Publishing Software Market | 2026-2036
Desktop Publishing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Desktop Publishing Software Market Analysis
EU Green Deal digital sustainability reporting requirements is rebalancing procurement criteria for enterprise publishing suites. Adobe InDesign leverages deep integration with creative cloud ecosystems to sustain enterprise retention. Affinity Publisher anchors its competitive stance through perpetual licensing that appeals to cost-sensitive professional users.
Desktop publishing software encompasses applications for page layout, typography control, and vector-raster integration that enable precise document composition across print and digital outputs; these tools manage resolution-independent graphics, color space conversion, and master page templating to produce marketing collateral, periodicals, and books. Cloud-based deployment leads volume adoption as distributed creative teams demand real-time collaboration, while subscription license models now capture the dominant share of recurring revenue. Magazine layout applications retain higher per-seat pricing due to specialized long-form pagination requirements.
FDA guidelines for promotional materials in pharmaceutical marketing shape template standardization demands within corporate communications segments. EMA medical literature formatting rules and FCC digital accessibility standards for public communications further constrain product design requirements. Stakeholders must monitor how evolving AI disclosure mandates across multiple jurisdictions reshape workflow verification features and content provenance tooling.
Market Dynamics
Cloud-based deployment is compressing license renewal cycles while the EU AI Act forces provenance tracking into automated publishing workflows, restructuring how marketing agencies and corporate communications teams evaluate vendor roadmaps.
Growth Catalysts
- EMA medical literature formatting rules:Pharmaceutical marketing teams require template standardization that drives enterprise suite upgrades across European compliance departments.
- Real-time collaboration demand:Distributed creative teams in marketing agencies now mandate cloud-native architecture as a baseline procurement criterion.
- FCC digital accessibility standards:Public communications mandates in the United States force captioning and alt-text automation features into core product specifications.
Market Restraints
- Perpetual license erosion:Adobe's subscription-only pivot has stranded cost-sensitive professional users who resist recurring payment obligations.
- Color space conversion complexity:Technical limitations in CMYK-RGB translation accuracy create print-production rework costs for magazine publishers.
- Input cost volatility:GPU and cloud storage pricing fluctuations compress margins for browser-based layout tool providers.
Strategic Opportunities
- India freelance designer expansion:Cost-sensitive professional users in Mumbai and Bangalore represent underpenetrated demand for perpetual-licensed alternatives.
- AI disclosure mandate convergence:The EU AI Act and emerging US state-level requirements create regulatory tailwinds for content provenance tooling integration.
- Magazine-to-digital pivot:Long-form pagination specialists are repositioning expertise toward interactive document formats for pharmaceutical detailing.
Industry Challenges
- Typography engineering talent scarcity:OpenType variable font expertise concentrates among a narrow cohort of developers, constraining feature roadmap velocity.
- Legacy InDesign file migration:Corporate communications teams face integration complexity when extracting assets from proprietary format lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desktop Publishing Software Market |
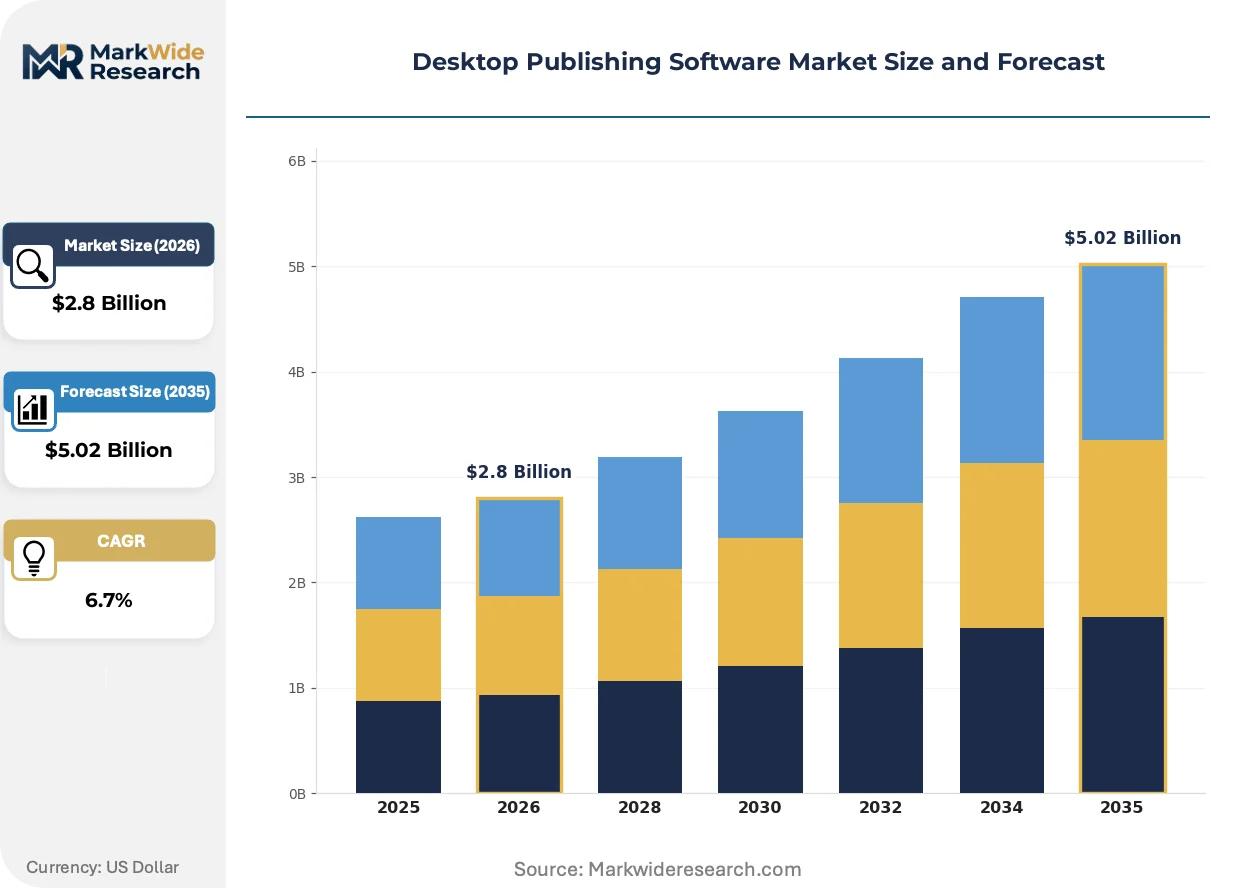
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Application: Graphic Design, Brochure Creation, Magazine Layout, Book Publishing, Newsletter Production End User: Publishing Houses, Educational Institutions, Marketing Agencies, Freelancers, Corporate Communications License Model: Perpetual License, Subscription License, Freemium, Open Source, Volume Licensing |
| Companies Covered | Canva, Affinity Publisher, Adobe InDesign, Lucidpress, Marq, QuarkXPress, Scribus, Venngage, Microsoft Publisher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desktop Publishing Software Market Emerging Trajectories
Automated layout intelligence is redistributing production tasks from specialist operators to generalist marketers, compressing skill premiums while expanding addressable user bases.
Generative fill and automated image extension tools are expanding into marketing collateral production workflows. Mid-market corporate communications teams in the United States adopt these capabilities fastest, cutting photography reshoot costs. The technology is expanding into template libraries that previously required manual asset preparation.
The EU AI Act's content authenticity requirements are reshaping product architecture. Automated publishing workflows must now embed cryptographic provenance metadata by default. Magazine publishers with pharmaceutical advertising contracts face the steepest compliance retrofit costs.
Subscription fatigue among freelance design professionals is fragmenting procurement patterns. Perpetual-license alternatives gain traction in cost-sensitive segments. Germany and France show the strongest preference divergence from cloud-only roadmaps.
Desktop Publishing Software Market Segmentation
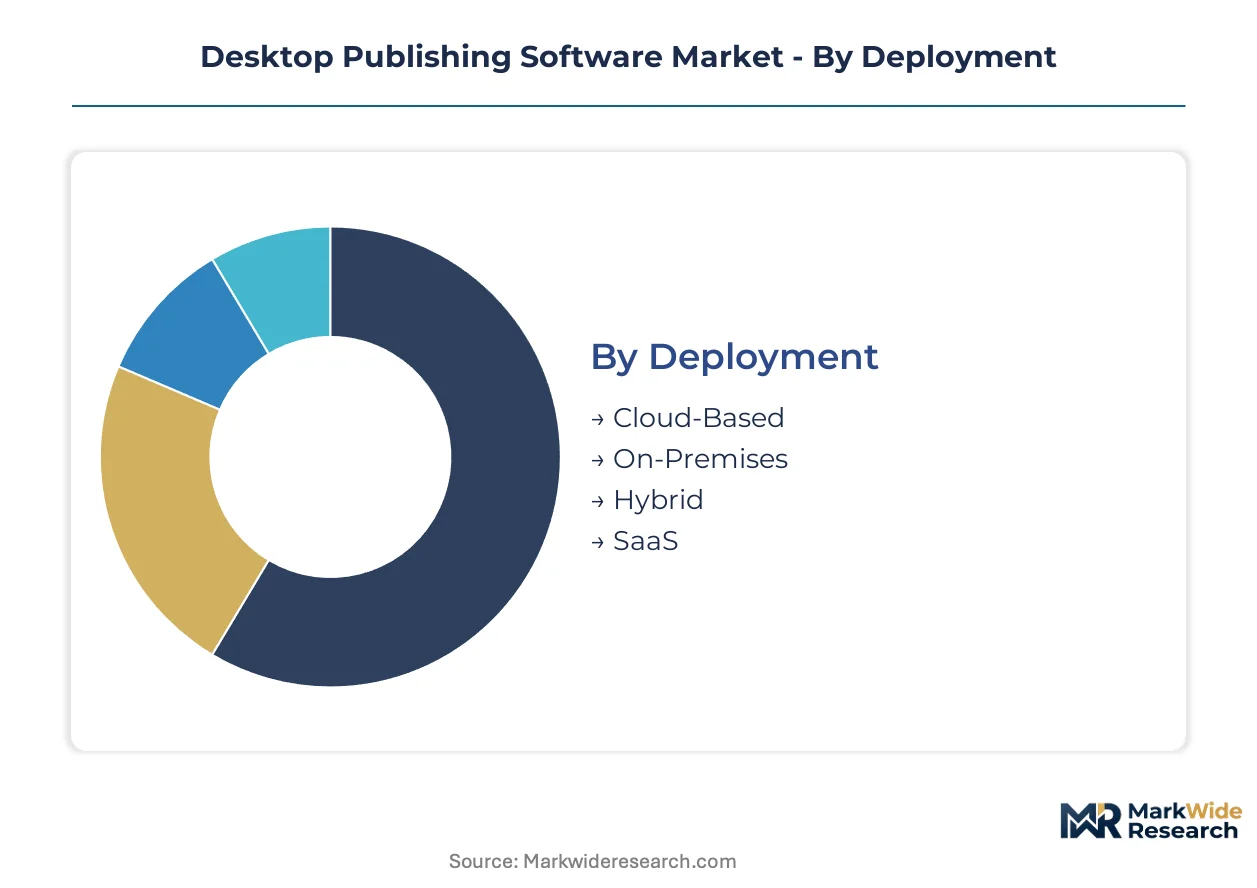
Desktop publishing software vendors architect product roadmaps around four intersecting dimensions that determine pricing power and retention economics. Deployment mode dictates infrastructure investment, while license model shapes customer lifetime value calculations across professional and institutional segments.
Deployment:
Supply concentration in cloud infrastructure is compressing deployment options toward browser-native architectures.
- Cloud-Based:Real-time collaboration engines power distributed creative teams through centralized GPU rendering farms. Marketing agencies in the United States mandate this architecture as a baseline procurement criterion, driven by FCC digital accessibility compliance automation requirements.
- SaaS:Modular feature tiers enable rapid scaling from individual freelancers to enterprise communications departments. Mid-market corporate communications teams in Germany and France show strongest adoption as subscription fatigue drives demand for usage-optimized pricing.
- On-Premises:Air-gapped installations serve defense contractors and classified government publishers with strict data sovereignty requirements.
- Hybrid:Local rendering with cloud asset libraries bridges latency-sensitive typography workflows with centralized template management.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Application:
Cost tier stratification separates premium pagination tools from entry-level marketing collateral generators.
- Magazine Layout:Long-form pagination with master page inheritance and CMYK-RGB color space conversion serves pharmaceutical advertising contracts. EMA medical literature formatting rules force template standardization upgrades across European compliance departments, sustaining premium per-seat pricing.
- Graphic Design:Vector-raster integration with OpenType variable font control anchors creative professional workflows. Freelance designers in Mumbai and Bangalore represent expanding demand for cost-sensitive perpetual-licensed alternatives.
- Brochure Creation:Template-driven production enables generalist marketers to execute specialist-grade collateral without typography engineering expertise.
- Book Publishing:EPUB export automation and reflowable text engines support academic and trade publishing houses with complex indexing requirements.
- Newsletter Production:Lightweight HTML email composition tools compete with dedicated email marketing platforms for corporate communications budgets.
Magazine Layout commands premium pricing. Brochure Creation expands the addressable user base fastest.
End User:
Volume concentration among marketing agencies is restructuring feature prioritization toward collaborative workflow tooling.
- Marketing Agencies:Multi-client asset management with brand guideline enforcement drives enterprise suite procurement. EU AI Act content authenticity mandates force provenance tracking integration into automated publishing workflows.
- Corporate Communications:Template standardization for FDA promotional material compliance shapes pharmaceutical sector demand. Legacy InDesign file migration complexity constrains vendor switching for established enterprise accounts.
- Publishing Houses:Print-digital hybrid production pipelines require color-accurate proofing and imposition automation.
- Freelancers:Perpetual license preference in cost-sensitive segments fragments procurement patterns away from cloud-only roadmaps.
- Educational Institutions:Volume licensing with curriculum integration supports design program accreditation requirements.
Marketing Agencies drive roadmap velocity. Freelancers represent the most price-elastic demand pool.
License Model:
Margin structure diverges sharply between recurring subscription revenue and one-time perpetual transactions.
- Subscription License:Continuous feature delivery and cloud storage integration capture dominant share of recurring revenue. Adobe's subscription-only pivot has stranded cost-sensitive professional users who resist recurring payment obligations.
- Perpetual License:One-time purchase with optional maintenance contracts appeals to budget-constrained institutional procurement. Affinity Publisher anchors competitive stance through this model in Germany and France.
- Freemium:Feature-gated entry tiers convert individual users to paid plans through advanced typography controls.
- Open Source:Community-developed alternatives constrain pricing power at the low end of professional segments.
- Volume Licensing:Enterprise agreements with site-wide deployment rights serve multinational corporate communications departments.
Subscription License sustains vendor valuations. Perpetual License gains traction in procurement divergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Desktop publishing software originated in the United States during the 1980s with the convergence of PostScript technology and graphical user interfaces. This American foundation established the technical standards and business models that subsequently diffused to European and Asian markets. Today, demand clusters concentrate in specific metropolitan innovation corridors with dense concentrations of marketing agencies and corporate communications departments.
United States
Freelance design professionals in Austin and mid-market corporate communications teams in Chicago drive subscription growth for cloud-native layout tools. FCC digital accessibility standards for public communications mandate captioning and alt-text automation features in procurement specifications. Marketing agencies in New York City and Los Angeles represent the densest concentration of multi-client asset management demand, forcing provenance tracking integration into vendor roadmaps.
Germany
Cost-sensitive professional users in Berlin and Munich exhibit the strongest preference divergence from cloud-only roadmaps across Europe. EU Green Deal digital sustainability reporting requirements rebalancing procurement criteria for enterprise publishing suites. The publishing technology cluster in Hamburg anchors demand for print-digital hybrid production pipelines with color-accurate proofing requirements.
United Kingdom
Marketing agencies in London mandate real-time collaboration engines as baseline procurement criteria for distributed creative teams. GDPR compliance frameworks shape data residency requirements for cloud-based deployment decisions. The corporate communications sector in Manchester and Birmingham drives template standardization demand for regulatory documentation workflows.
India
Cost-sensitive professional users in Mumbai and Bangalore represent underpenetrated demand for perpetual-licensed alternatives to subscription models. The country's national software industry regulator influences data localization requirements for cloud storage integration. Freelance designers in Hyderabad and Pune expand adoption of browser-native layout tools for marketing collateral production.
Japan
Publishing houses in Tokyo require EPUB export automation and reflowable text engines for complex academic indexing workflows. METI standards influence color space conversion accuracy requirements in print-production environments. The design technology cluster in Osaka anchors demand for vector-raster integration with OpenType variable font control.
Desktop Publishing Software Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the desktop publishing software landscape. The market structure fragments between integrated creative cloud ecosystems and specialized layout tool vendors. Three strategic archetypes dominate: subscription-first platform incumbents, perpetual-license challengers, and browser-native collaboration specialists. M&A activity concentrates on acquiring real-time collaboration engines, while portfolio diversification drives expansion into automated layout intelligence.
Within the subscription-first tier, Adobe InDesign and Canva exemplify divergent approaches to creative professional capture. Affinity Publisher occupies a position representing the perpetual-license challenger archetype for cost-sensitive segments. These three anchors illustrate how licensing model differentiation creates distinct competitive territories rather than direct feature parity competition.
| Leading Market Players |
|---|
| Canva |
| Affinity Publisher |
| Adobe InDesign |
| Lucidpress |
| Marq |
| QuarkXPress |
| Scribus |
| Venngage |
| Microsoft Publisher |
| Others |
Supply Flow & Price Mechanics
Marketing agencies in the United States anchor procurement volume for cloud-native layout tools, locking vendors into subscription-first pricing models that extract recurring revenue from distributed creative teams while compressing perpetual-license alternatives to cost-sensitive freelance segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enterprise communications departments from mid-market corporate teams from individual freelancers. Price differentiation rests on collaboration seat count, cloud storage allocation, and API access depth. Cost compression in the freelance tier is intensifying because Affinity Publisher's perpetual-license model captures defecting Adobe subscribers. Marketing agencies show least price sensitivity due to multi-client asset management requirements; Indian freelancers in Mumbai and Bangalore exhibit highest elasticity.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating restricts cloud infrastructure vendor selection to hyperscalers with compliance-ready data centers, concentrating supply among Amazon Web Services, Microsoft Azure, and Google Cloud Platform. GPU rendering farms for browser-native layout tools draw from Taiwan and South Korea for advanced semiconductor sourcing. Single-source vulnerability in cloud storage pricing creates margin compression risk for SaaS providers. Distribution runs through direct-to-customer digital storefronts with enterprise sales overlays for site-wide licensing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany and France exceed FCC accessibility mandate burdens in the United States, creating divergent vendor investment priorities across Atlantic procurement clusters.
For Market Incumbents: Anchor enterprise retention through deep Creative Cloud ecosystem integration while accelerating cryptographic provenance tooling development to preempt EU AI Act retrofit demands. Defensive capacity addition in Indian cloud regions addresses data localization requirements from the country's national software industry regulator. Certification investment in ISO 27001 and SOC 2 compliance maintains hyperscaler partnership eligibility.
For New Entrants and Emerging Players: Automated layout intelligence tools offer a technology-first wedge into brochure creation workflows currently served by generalist marketers lacking typography engineering expertise. White-space concentration sits with cost-sensitive freelance designers in Mumbai, Bangalore, and Berlin where subscription fatigue fragments procurement patterns. Channel partnership with design education institutions accelerates curriculum-embedded user acquisition.
For Investors and Strategic Acquirers: Creative cloud platform consolidators are the most active acquirer in this space, targeting real-time collaboration engine specialists to fill architectural gaps. Long-term viability hinges on provenance-tracking feature depth as regulatory mandates expand across jurisdictions. Acquisition target archetype: browser-native layout tools with hybrid deployment flexibility. The signal to watch is EMA medical literature formatting rule expansion forcing pharmaceutical sector template standardization upgrades.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Adobe Creative Cloud connectivity sustains enterprise switching costs for corporate communications departments. |
| Acquisition of Specialist Firm | Real-time collaboration engine purchases fill architectural gaps in legacy pagination tool portfolios. |
| Geographic Expansion | Indian cloud region deployment satisfies data localization requirements from the national software industry regulator. |
| Product Launch | Perpetual-license alternatives capture subscription-fatigued freelance designers in Berlin and Munich. |
| Strategic Partnership | Design education curriculum integration embeds tools into accreditation-dependent training pipelines. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with creative directors at marketing agencies, procurement officers at corporate communications departments, freelance designers in Mumbai and Berlin, and platform engineering leads at SaaS vendors with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory databases, and design education accreditation records. Bottom-up deployment mode adoption curves and top-down license model revenue estimates were triangulated against vendor-reported segment metrics.
Segment-weighting across deployment mode, application type, end-user vertical, and license model determined value allocation throughout the forecast period. CAGRs were derived from trend extrapolation of cloud-native adoption rates and perpetual-license erosion patterns across the analysis window. Industry-specific inputs included EMA medical literature formatting rule implementation timelines and FCC digital accessibility standard enforcement intensity.
The model holds under stable regulatory enforcement intensity; deviation in EU AI Act penalty structures or FDA promotional material guideline expansion would shift enterprise upgrade timing. Forecasts reflect assumptions regarding cloud infrastructure cost trajectories and GPU availability for browser-based rendering. A model refresh is warranted upon material change in pharmaceutical advertising compliance mandate breadth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Search and Discovery Software Market
Software & Services
Admission Management Software Market
Software & Services
Global MSP Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Servicenow Tech Services Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Global Directory Software Market
Software & Services
Global Automation Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Load Balancing Software Market
Software & Services
HVAC Solution Software Market
Software & Services
Staffing Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Global Server Management Software Market