
 Global Cloud Enterprise Resource Planning Market | 2026-2036
Global Cloud Enterprise Resource Planning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Enterprise Resource Planning Market Foresight
Subscription-based software-defined feature layers is shifting how cloud ERP vendors monetize platform access beyond traditional licensing. SAP leverages deep vertical integration across manufacturing and supply chain modules to sustain competitive positioning. Oracle anchors its cloud ERP portfolio through aggressive database-to-application integration, while Microsoft differentiates by embedding ERP workflows within its broader productivity ecosystem.
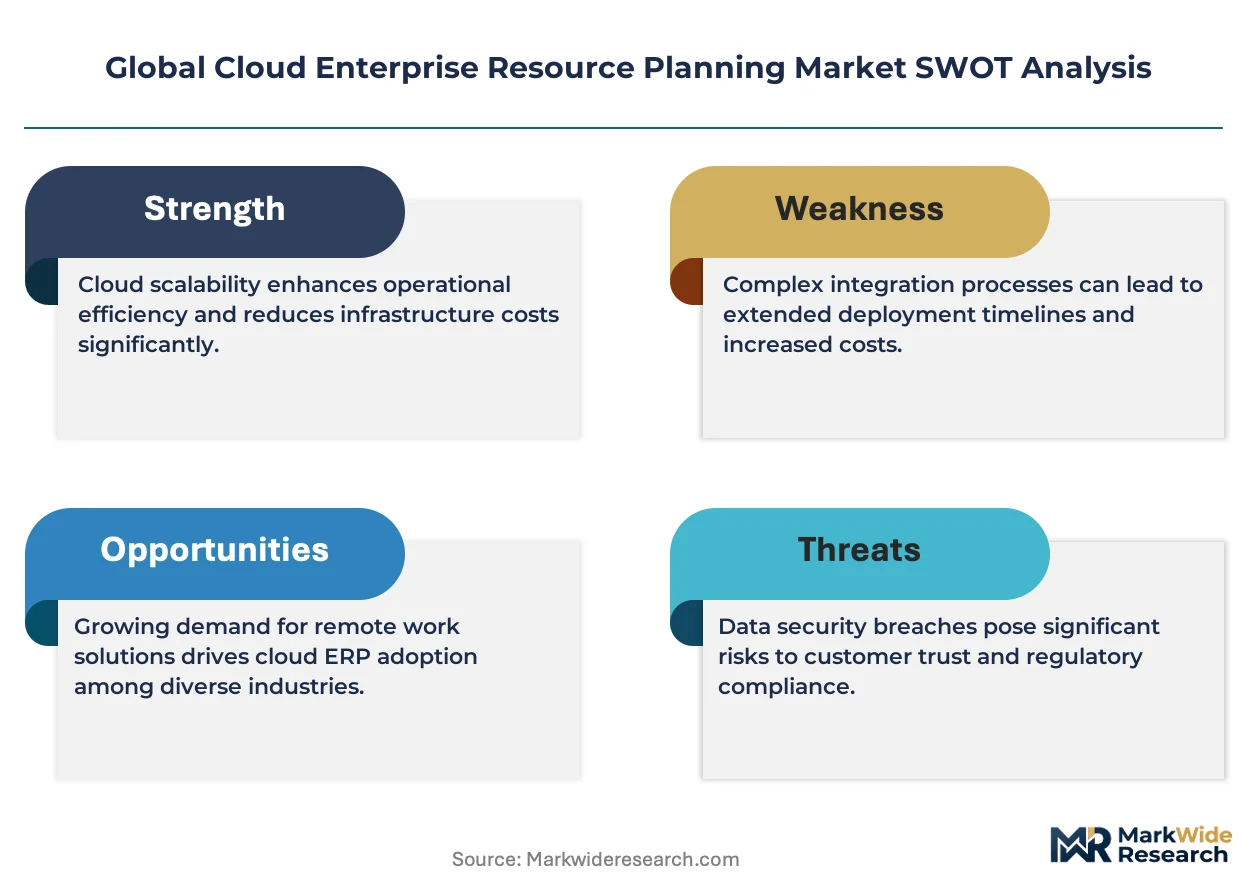
Cloud Enterprise Resource Planning denotes a software architecture delivered via internet-hosted infrastructure that centralizes financial, operational, and human resource data through multi-tenant or single-tenant configurations with API-driven interoperability standards. Its primary commercial purpose is to unify transactional processing and predictive analytics across geographically dispersed business units without on-premises hardware maintenance. Financial Management and Supply Chain Management solution types currently occupy the deepest margin pools due to compliance complexity and inventory optimization requirements, while Human Capital Management is accelerating fastest as distributed workforce administration demands real-time payroll and talent analytics integration. Public Cloud deployment retains volume leadership for mid-market buyers, though Hybrid Cloud configurations are gaining traction among regulated industries requiring partitioned data residency.
The EU AI Act, GDPR, and SEC disclosure rules collectively shape cloud ERP product roadmaps by mandating algorithmic transparency, cross-border data governance, and automated audit trails for financial reporting. FDA and HIPAA frameworks extend these requirements into life sciences and healthcare verticals where ERP systems must validate batch records and protect patient-adjacent operational data. Stakeholders must evaluate vendor certification breadth against their specific industry regulatory perimeter before committing to multi-year platform contracts.
Market Dynamics
Algorithmic accountability mandates embedded in the EU AI Act and SEC disclosure frameworks are forcing cloud ERP vendors to rearchitect financial reporting modules for explainable automation, compressing development cycles while elevating compliance costs.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated financial reporting modules now require auditable decision trails, driving replacement demand among European enterprises with complex multi-entity structures.
- Manufacturing supply chain visibility requirements:German and US industrial firms are consolidating procurement, inventory, and logistics data onto unified cloud platforms to mitigate disruption exposure.
- API-driven interoperability standards:Open banking protocols and ISO 20022 messaging formats are accelerating ERP integration with external financial networks, reducing custom development overhead.
Market Restraints
- Cross-border data residency friction:GDPR localization requirements and China's data sovereignty rules fragment cloud architecture decisions, forcing redundant infrastructure deployment.
- Specialized ERP talent scarcity:Implementation partners with deep SAP S/4HANA or Oracle Fusion certification command premium rates, elongating deployment timelines for mid-market buyers.
- Legacy on-premises sunk costs:Enterprises with depreciated hardware investments face write-down pressure when migrating to subscription-based cloud models.
Strategic Opportunities
- India's PLI-linked manufacturing digitization:Production-linked incentive beneficiaries require compliant ERP systems for subsidy verification, creating a captive mid-market segment.
- Healthcare HIPAA-adjacent operational modules:FDA validation requirements for batch record management in life sciences ERP remain underserved by horizontal platforms.
- Hybrid cloud configurations for regulated industries:Partitioned data residency architectures address financial services and defense sector security clearance requirements.
Industry Challenges
- Multi-tenant security isolation complexity:Public cloud providers must demonstrate logical separation robust enough for competing pharmaceutical firms sharing infrastructure.
- Retrofitting AI explainability into legacy codebases:Black-box predictive analytics modules require expensive reconstruction to meet emerging algorithmic accountability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Enterprise Resource Planning Market |
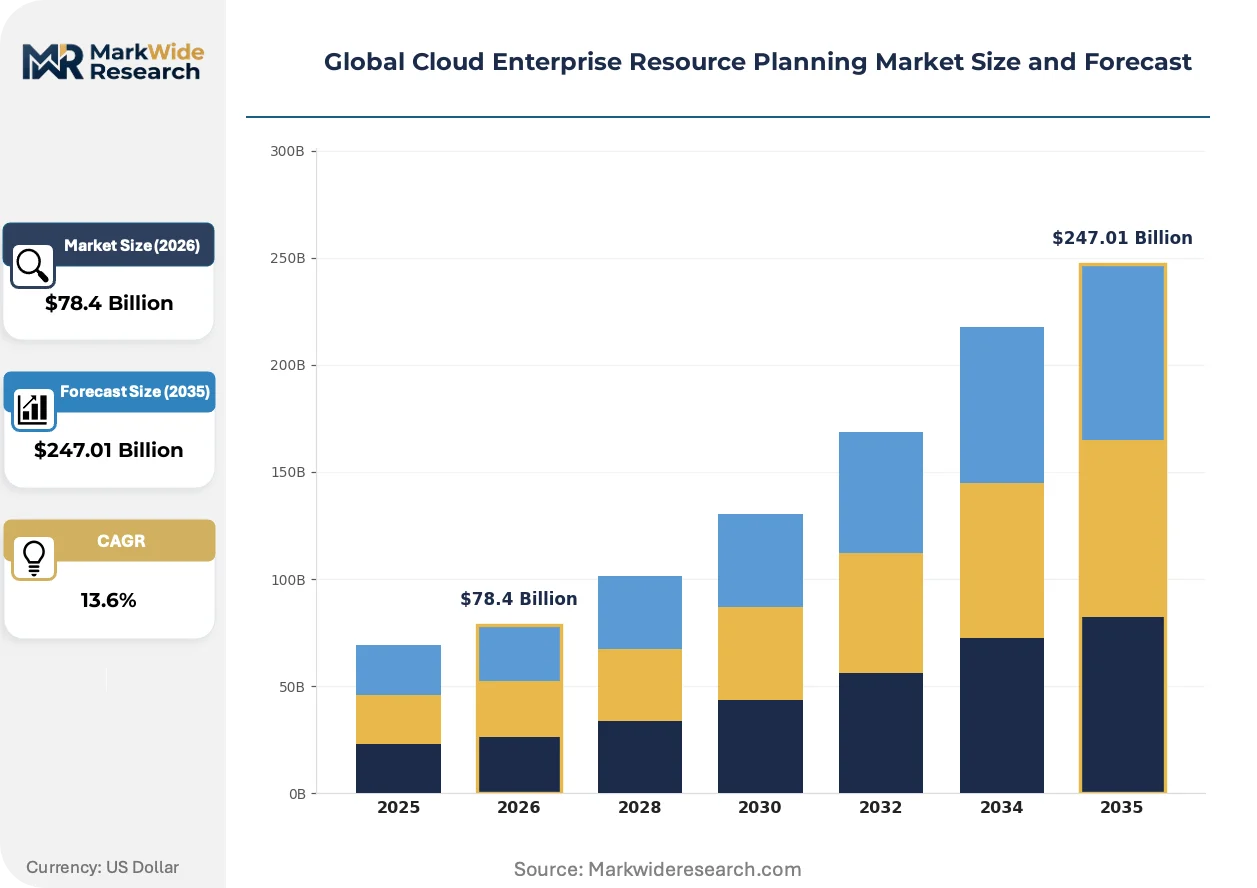
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Financial Management, Supply Chain Management, Human Capital Management, Customer Relationship Management, Project Management Use Case: Order Management, Inventory Control, Procurement Automation, Compliance Management, Resource Planning End User: Manufacturing Firms, Wholesale Distributors, Professional Services, IT Services Providers, Educational Institutions |
| Companies Covered | SAP, Oracle, Microsoft, Infor, Workday, Epicor Software Corporation, Deltek, Sage Group plc, Acumatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Enterprise Resource Planning Market Shifts & Advancements
Embedded machine learning capabilities are migrating from standalone analytics layers into core transactional workflows, compressing the latency between operational data capture and predictive insight generation.
Agentic AI orchestration is expanding into procurement and treasury automation, enabling autonomous execution of purchase order matching and cash flow forecasting. Mid-market manufacturers in Germany and the United States are piloting these capabilities ahead of broader rollout. The technology is expanding into decision domains previously reserved for human judgment, forcing ERP vendors to retrain implementation methodologies around exception-handling protocols.
The EU AI Act's risk-based classification system for automated decision-making is mandating built-in logging and human oversight interfaces for high-stakes financial modules. Vendors must now engineer "stop buttons" and audit trails natively rather than retrofitting compliance. Life sciences and banking verticals face the steepest reconfiguration burden as their ERP deployments trigger the Act's "high-risk" category thresholds.
Subscription fatigue among CFOs is compressing enterprise software evaluation cycles, with multi-year contracts giving way to annual renewal scrutiny. Buyers are unbundling ERP suites to purchase finance and supply chain modules from separate best-of-breed vendors. This pattern is most pronounced in North American technology and professional services firms with lean IT procurement functions.
Global Cloud Enterprise Resource Planning Market Segmentation
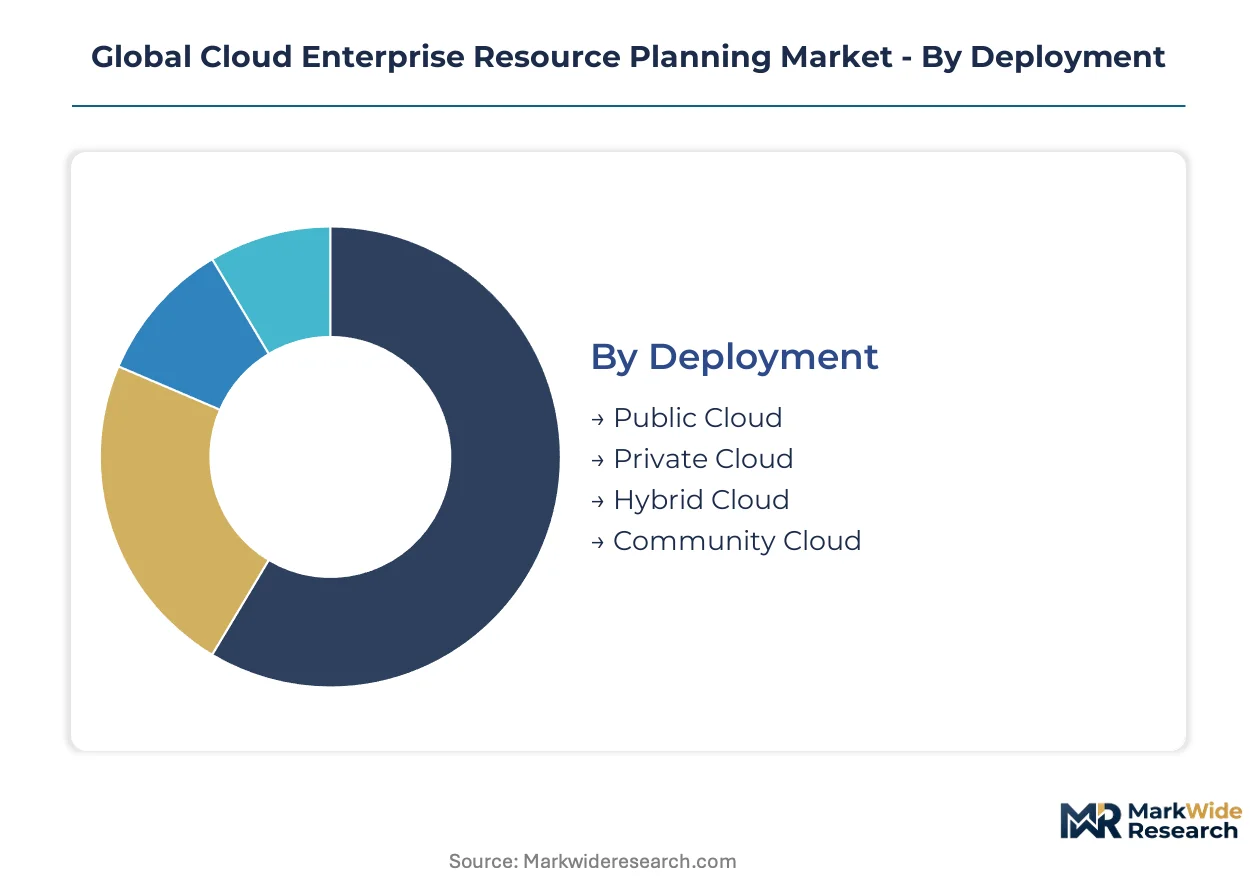
Cloud ERP purchasing decisions fragment across deployment architecture, functional scope, and operational intensity. Buyers trade off control against elasticity, while regulatory exposure and workforce dispersion determine module prioritization.
Deployment:
Volume leadership sits with standardized multi-tenant configurations, while premium pricing attaches to partitioned infrastructure with data residency guarantees.
- Public Cloud:Multi-tenant architectures deliver elastic compute without capital commitment. Mid-market manufacturers in Germany and the United States favor this model for rapid supply chain module deployment amid disruption volatility.
- Hybrid Cloud:Partitioned workloads split transactional processing between public elasticity and private control. Financial services firms under SEC disclosure mandates and EU AI Act algorithmic accountability requirements drive premium uptake for audit-isolated financial reporting modules.
- Private Cloud:Single-tenant dedicated infrastructure with full stack control. Defense contractors and pharmaceutical batch record systems under FDA validation protocols require this architecture.
- Community Cloud:Shared infrastructure among affiliated organizations with common compliance profiles. Hospital networks and university systems under HIPAA and FERPA frameworks pilot these configurations.
Today's leader: Public Cloud. Tomorrow's challenger: Hybrid Cloud.
Solution Type:
Margin depth correlates with compliance complexity and cross-border data governance requirements.
- Financial Management:Core ledger, consolidation, and automated reporting modules with embedded audit trails. EU AI Act mandates and SEC disclosure rules are forcing explainable automation reconstruction, elevating replacement demand among European multi-entity enterprises.
- Supply Chain Management:Procurement, inventory optimization, and logistics orchestration with predictive demand sensing. German industrial firms consolidate these functions onto unified platforms to mitigate supplier disruption exposure.
- Human Capital Management:Distributed payroll, talent analytics, and workforce planning with real-time compliance updates. Professional services firms with remote employee concentration across multiple tax jurisdictions drive expansion.
- Customer Relationship Management:Quote-to-cash automation with embedded revenue recognition. IT services providers with project-based billing complexity represent primary demand concentration.
- Project Management:Resource allocation, time capture, and milestone tracking with profitability analytics. Engineering consultancies and construction firms with multi-site contract execution requirements deploy these modules.
Financial Management commands current margin pools. Human Capital Management is climbing the fastest as distributed workforce administration becomes non-negotiable.
Use Case:
Operational intensity determines module bundling decisions, with high-frequency transactional workflows anchoring initial deployments.
- Order Management:Quote configuration, availability checking, and fulfillment orchestration with customer-specific pricing rules. Wholesale distributors with high SKU complexity and thin margins prioritize this capability.
- Inventory Control:Multi-location stock visibility, replenishment automation, and obsolescence forecasting. US manufacturers rebuilding buffer stock after recent supply shocks drive concentrated demand.
- Procurement Automation:Supplier onboarding, purchase order matching, and three-way invoice reconciliation. Agentic AI orchestration is penetrating this domain first, with German manufacturers piloting autonomous execution.
- Compliance Management:Regulatory deadline tracking, documentation workflows, and audit preparation with jurisdiction-specific rule engines. Life sciences firms under FDA and EMA parallel requirements represent the steepest configuration burden.
- Resource Planning:Capacity scheduling, skill matching, and utilization optimization across project portfolios. Professional services firms with billable hour economics depend on this precision.
Order Management anchors initial cloud ERP commitments. Procurement Automation is gaining share fastest as autonomous execution capabilities mature.
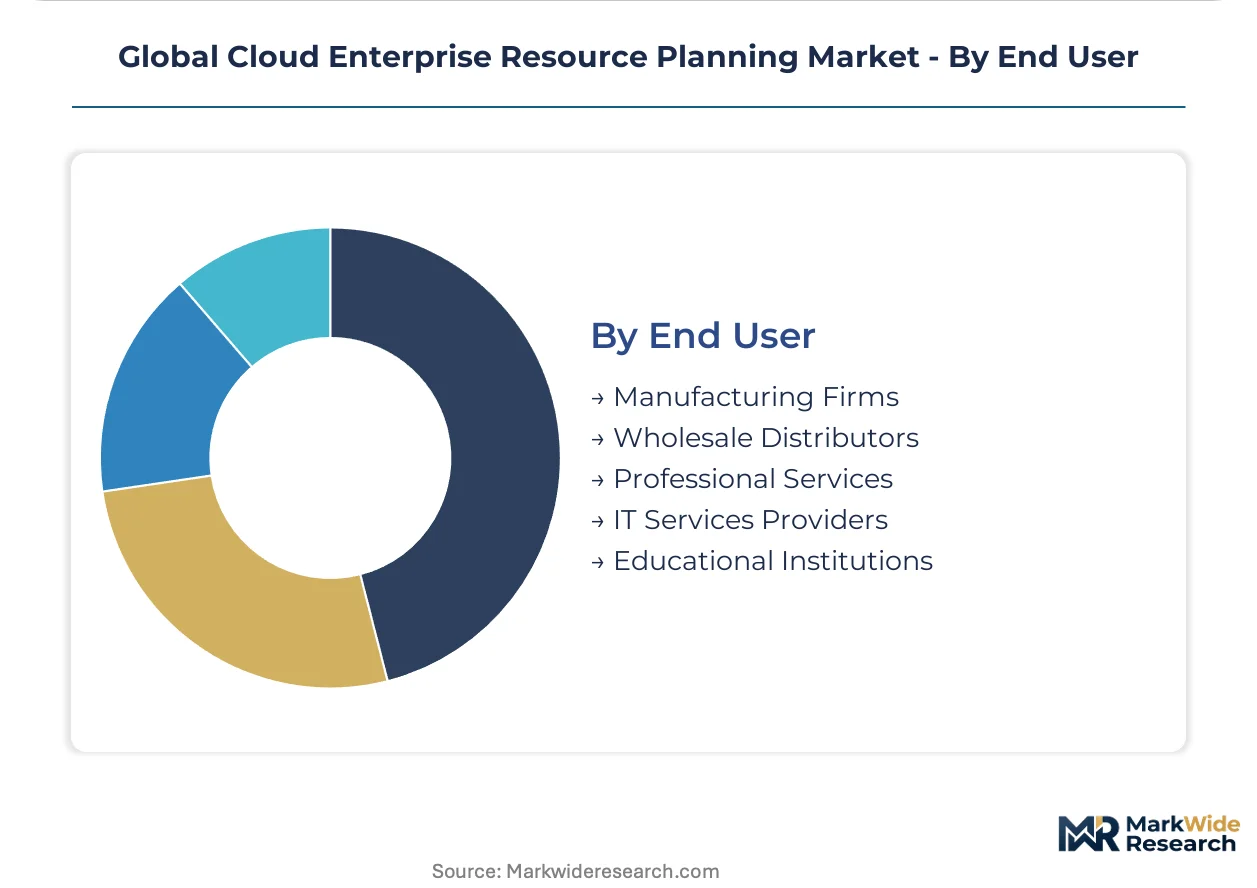
End User:
Customer concentration varies by sales cycle length and implementation complexity, with asset-heavy verticals showing stickier retention.
- Manufacturing Firms:Discrete and process producers with multi-site production, complex BOM structures, and regulatory batch documentation. German automotive suppliers and US industrial equipment makers represent the deepest vertical integration into supply chain modules.
- Wholesale Distributors:Inventory-intensive intermediaries with high transaction velocity and thin working capital cycles. These buyers demand real-time visibility across supplier networks and customer commitments.
- Professional Services:Legal, accounting, and consulting partnerships with project-based revenue recognition and partner compensation allocation. Subscription fatigue among CFOs in this segment is accelerating unbundling toward best-of-breed finance modules.
- IT Services Providers:Technology consultancies with global delivery models and multi-currency contract portfolios. These firms often self-implement, reducing services attach rates for vendors.
- Educational Institutions:Universities and K-12 districts with grant accounting, student information system integration, and state reporting requirements. Budget constraints elongate evaluation cycles in this segment.
Manufacturing Firms dominate current contract value. Professional Services is emerging as the most contested battleground as unbundling pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises outpace German manufacturers in cloud ERP contract velocity, yet both markets concentrate demand in discrete industrial verticals with complex multi-entity financial consolidation requirements.
United States
SEC disclosure mandates and multi-subsidiary financial consolidation requirements drive replacement demand among Fortune 500 industrials. The Sarbanes-Oxley Act and emerging algorithmic accountability frameworks elevate audit trail specifications for automated reporting modules. Manufacturing clusters in Michigan and Ohio consolidate supply chain visibility onto unified platforms to rebuild buffer stock resilience after recent disruption cycles.
Germany
Automotive suppliers and industrial equipment makers anchor European cloud ERP adoption with complex BOM structures and supplier network orchestration demands. The EU AI Act's high-risk classification for automated financial decision-making forces explainable automation reconstruction in S/4HANA deployments. The Baden-Württemberg industrial corridor around Stuttgart pilots agentic AI procurement modules ahead of broader continental rollout.
India
Production-linked incentive beneficiaries require compliant ERP systems for subsidy verification and export documentation, creating captive mid-market demand. The RBI's data localization guidelines and SEBI's algorithmic trading disclosures shape vendor selection criteria for financial services deployments. Manufacturing digitization concentrates in Gujarat and Tamil Nadu automotive clusters where PLI-linked investments mandate integrated supply chain modules.
China
State-owned manufacturers and private industrial conglomerates balance cloud elasticity against data sovereignty requirements under MIIT cybersecurity regulations. SAMR antitrust scrutiny and GB standards compliance elevate domestic vendor preference in sensitive verticals. The Yangtze River Delta manufacturing belt around Shanghai deploys hybrid configurations to partition financial data residency while retaining public cloud scalability for operational modules.
United Kingdom
Professional services firms and fintech operators drive unbundling pressure toward best-of-breed finance modules amid subscription fatigue among CFOs. The FCA's operational resilience requirements and post-Brexit data adequacy negotiations fragment cloud architecture decisions. London's technology and consulting corridor accelerates annual renewal scrutiny, compressing multi-year contract structures toward modular procurement patterns.
Global Cloud Enterprise Resource Planning Market Competitive Landscape
Top-tier vendors anchor enterprise-grade deployments with deep vertical integration, while mid-market specialists and vertical SaaS providers fragment the lower tiers with modular, best-of-breed alternatives. The competitive structure stratifies across three archetypes: database-to-application integrators, productivity ecosystem embedders, and manufacturing-centric vertical specialists. Consolidation pressure intensifies through strategic partnerships between hyperscale infrastructure providers and application-layer vendors, alongside geographic expansion into PLI-linked manufacturing corridors in India and Southeast Asia.
Within the database-centric tier, Oracle anchors enterprise financial consolidation through aggressive infrastructure-to-application integration, while SAP exemplifies manufacturing vertical specialization with deep supply chain module penetration. Microsoft occupies the productivity ecosystem position, embedding ERP workflows within collaborative software environments. These three vendors represent distinct competitive vectors—data gravity, operational depth, and user experience ubiquity—rather than direct feature parity, forcing mid-market buyers to trade off control against contextual accessibility.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| Microsoft |
| Infor |
| Workday |
| Epicor Software Corporation |
| Deltek |
| Sage Group plc |
| Acumatica |
| Others |
Supply & Pricing Matrix
Captive infrastructure ownership among hyperscale cloud providers anchors both supply security and pricing power for enterprise ERP deployments, with SAP and Oracle leveraging proprietary data center networks across Germany and the United States to sustain premium positioning against modular competitors.
Pricing Analysis
Capacity additions in India's PLI-linked manufacturing corridors are reshaping price floors for mid-market cloud ERP tiers. Subscription-based SaaS models dominate, with pricing stratifying across premium, standard, and economy tiers differentiated by compliance certification depth and data residency guarantees. Cost compression in standard tiers intensifies as Workday and Acumatica compete for professional services accounts with lean procurement functions. Mid-market manufacturers in Germany exhibit the highest price sensitivity, while defense contractors under FDA validation mandates accept premium positioning for private cloud isolation.
Supply Chain Analysis
Reverse-logistics flows for ERP hardware refreshes remain underdeveloped, though Oracle and SAP pilot refurbishment programs for decommissioned on-premises servers in European data centers. Supply concentration sits with Taiwan and South Korea for advanced server components, while software development draws from India and Ireland. The supply chain rests on specialized semiconductor availability and certified implementation partner capacity. Single-source vulnerability in SAP S/4HANA certification pipelines elongates deployment timelines. Distribution runs through direct enterprise sales forces with systems integrator co-delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud ERP vendors capture margin expansion through compliance-module premiumization, as EU AI Act mandates force explainable automation reconstruction that buyers cannot defer.
For Market Incumbents: Extend vertical integration into manufacturing-specific compliance modules to defend against unbundling pressure from best-of-breed finance specialists. Deepen SAP S/4HANA certification pipelines in India and Germany to alleviate implementation partner scarcity. Anchor database-to-application integration as the priority defensive lever against Microsoft's productivity ecosystem embedment. For New Entrants and Emerging Players: Enter via HIPAA-adjacent operational modules for life sciences batch record management, a whitespace underserved by horizontal platforms. Target India's PLI-linked automotive suppliers in Gujarat and Tamil Nadu with subsidy-verification-native ERP configurations. Pursue channel partnerships with regional systems integrators over direct enterprise sales to bypass incumbent relationship density. For Investors and Strategic Acquirers: Roll-up economics work for vertical SaaS specialists with FDA validation capabilities because regulatory certification creates natural acquisition moats. Five-to-ten year viability favors manufacturing-centric platforms with embedded supply chain AI over generic finance modules facing unbundling pressure. Monitor EU AI Act enforcement patterns as the inflection signal for compliance-module replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding ERP workflows within Microsoft Teams and Office 365 accelerates user adoption across distributed professional services firms. |
| Acquisition of Specialist Firm | Horizontal vendors acquire life sciences compliance specialists to close FDA validation gaps in batch record modules. |
| Geographic Expansion | Establishing delivery centers in India's PLI corridors captures captive demand from subsidy-verification requirements. |
| Strategic Partnership | Hyperscale infrastructure alliances with AWS and Azure partition data residency for financial services hybrid deployments. |
| Product Launch | Agentic AI procurement modules with native EU AI Act logging penetrate German automotive supplier pilot programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research incorporated CTOs at Fortune 500 industrials, SAP S/4HANA implementation partners, IT procurement officers at German automotive suppliers, and compliance leads at life sciences firms. Secondary validation drew from SEC 10-K filings, EU AI Act regulatory texts, RBI data localization guidelines, and hyperscaler capex disclosures. Bottom-up deployment counts and top-down vendor revenue estimates were triangulated to anchor market sizing.
Segment-weighting approaches applied differential growth assumptions across deployment architectures, solution types, and end-user verticals. The analytical framework modeled public cloud, hybrid cloud, private cloud, and community cloud configurations alongside financial management, supply chain management, human capital management, and customer relationship management modules. CAGRs were derived from deployment velocity trends and replacement cycle compression. Forecast inputs included PLI scheme expansion trajectories and algorithmic accountability mandate enforcement timelines.
Inputs from vendor certification databases and regulatory filing repositories were available through the study window; gaps in private cloud deployment counts at defense contractors introduce uncertainty bands in the premium tier. Forecasts incorporate assumptions around EU AI Act implementation consistency and SEC disclosure rule finalization. Practitioners should monitor enforcement patterns for algorithmic transparency mandates and PLI scheme renewal decisions for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Feedback Management Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
Global Calendar Scheduling Software Market
Software & Services
Decision Support System (DSS) Software Market
Software & Services
Lead Management Software Market
Software & Services
Global Data Warehouse Software Market
Software & Services
Low Code Development Platform Market
Software & Services
Document Capture Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Global App Design Software Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Chemical Manufacturing Software Market
Software & Services
US Software Consulting Market
Software & Services
Global Architecture Software Market
Software & Services
Testing As a Service (Taas) Market