
 Pet Tech Market | 2026-2036
Pet Tech Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Tech Market Analysis
Veterinary data science talent is bifurcating the competitive landscape, as firms with in-house animal health analytics capabilities pull ahead of hardware-only vendors. Garmin International leverages its GPS heritage to dominate location-tracking wearables. Mars Incorporated sustains broad channel control through retail and veterinary distribution networks. Petcube differentiates via camera-integrated engagement platforms that occupy the premium home-monitoring tier.
Pet tech encompasses connected devices, software platforms, and sensor systems engineered for animal health, behavior, and welfare management, typically operating through Bluetooth 5.0 or low-power wide-area protocols with IP67-rated durability for animal wear. The primary commercial purpose centers on translating biometric and locomotive data into actionable care protocols for owners and clinicians. Wearable devices anchor current revenue pools, while artificial intelligence-enabled health monitoring represents the fastest-expanding margin segment. Smart feeders command stable replacement demand, and interactive toys face compressed margins amid commodity sensor proliferation.
FDA Center for Veterinary Medicine oversight shapes device classification and clinical claim substantiation for health-monitoring products in the United States. The EU Green Deal and REACH chemical standards constrain battery and polymer material choices for European market access. Stakeholders must weigh regulatory compliance investment against the pace of AI diagnostic feature deployment to capture veterinary channel adoption.
Market Dynamics
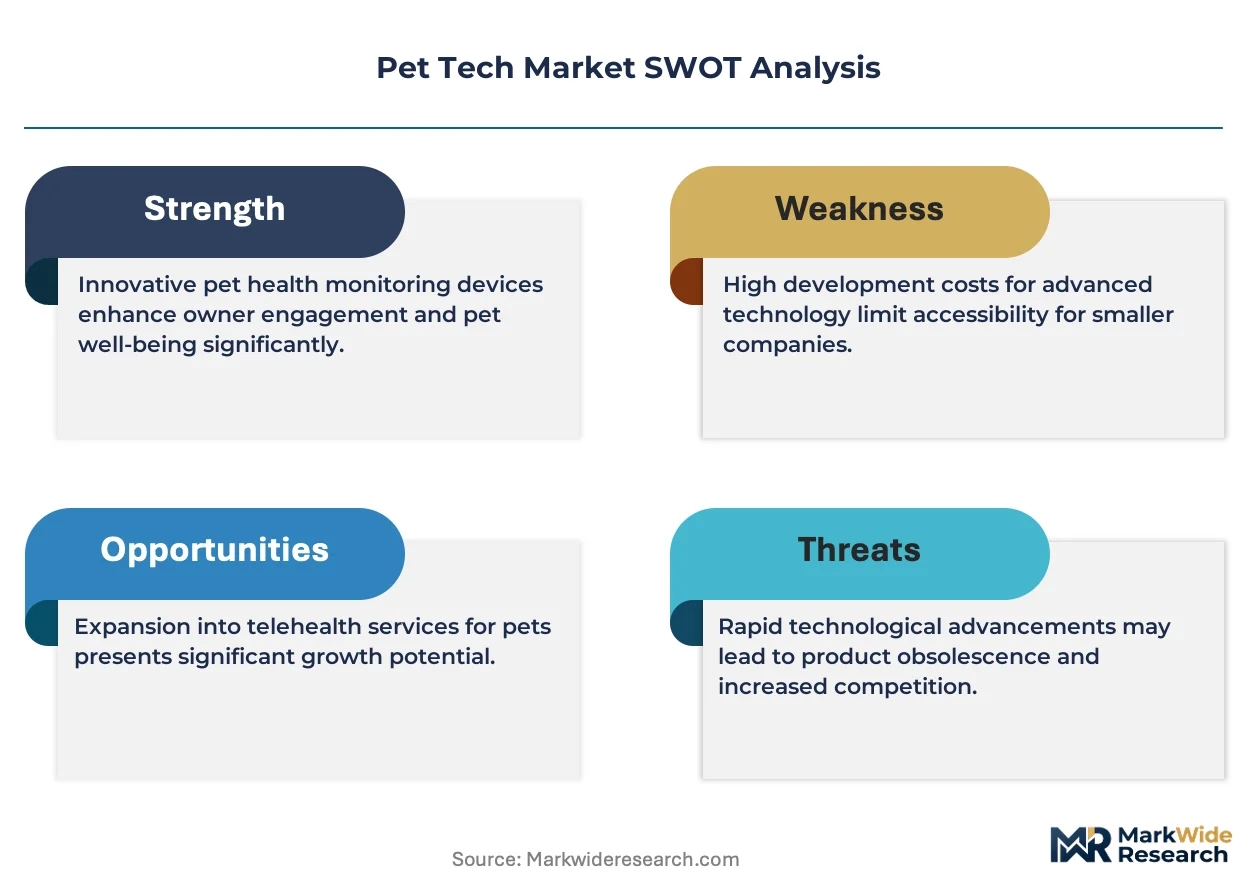
Veterinary data science talent scarcity is concentrating competitive advantage among firms that integrate hardware with proprietary animal health analytics, while hardware-only vendors face margin compression.
Growth Catalysts
- Remote Monitoring Protocols:FDA Center for Veterinary Medicine guidance on digital health devices is accelerating clinical validation pathways for biometric wearables. Veterinary clinics are adopting continuous glucose monitors and activity trackers as standard care extensions.
- REACH Chemical Standards:EU battery and polymer material restrictions are forcing redesigns that improve device durability and recyclability, creating premium positioning for compliant manufacturers.
- Subscription Service Models:Pet owners in the United States are converting to recurring revenue platforms that bundle hardware with cloud-based health analytics and tele-veterinary consultations.
Market Restraints
- Lithium-Ion Supply Concentration:Battery raw material processing concentrates in China, exposing wearable device manufacturers to input cost volatility and geopolitical supply disruptions.
- Clinical Claim Substantiation:FDA substantiation requirements for diagnostic algorithms create multi-year validation timelines that delay product launches and consume R&D capital.
- Smartphone Dependency:Bluetooth 5.0 pairing requirements limit addressable markets in regions with lower smartphone penetration, constraining rural and elderly pet owner adoption.
Strategic Opportunities
- Japan's Aging Pet Population:METI incentives for eldercare technology extension into animal health create regulatory tailwinds for arthritis monitoring and pain management devices.
- AI-Veterinary Convergence:Machine learning diagnostic tools trained on breed-specific biometric baselines are opening white space in predictive health alerts before symptom onset.
- Veterinary Channel Integration:Direct distribution partnerships with clinic networks bypass retail margin extraction and capture prescription-aligned device sales.
Industry Challenges
- Veterinary Data Science Talent:The intersection of animal physiology, machine learning, and regulatory science commands salary premiums that strain mid-cap firm hiring.
- Multi-Jurisdiction Certification:Simultaneous FDA, CE marking, and PMDA clearance processes create compliance timeline bottlenecks that delay global product rollouts.
- Legacy Practice Management Integration:Veterinary clinic software systems lack standardized APIs, forcing custom integration work that extends deployment cycles and raises implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Tech Market |
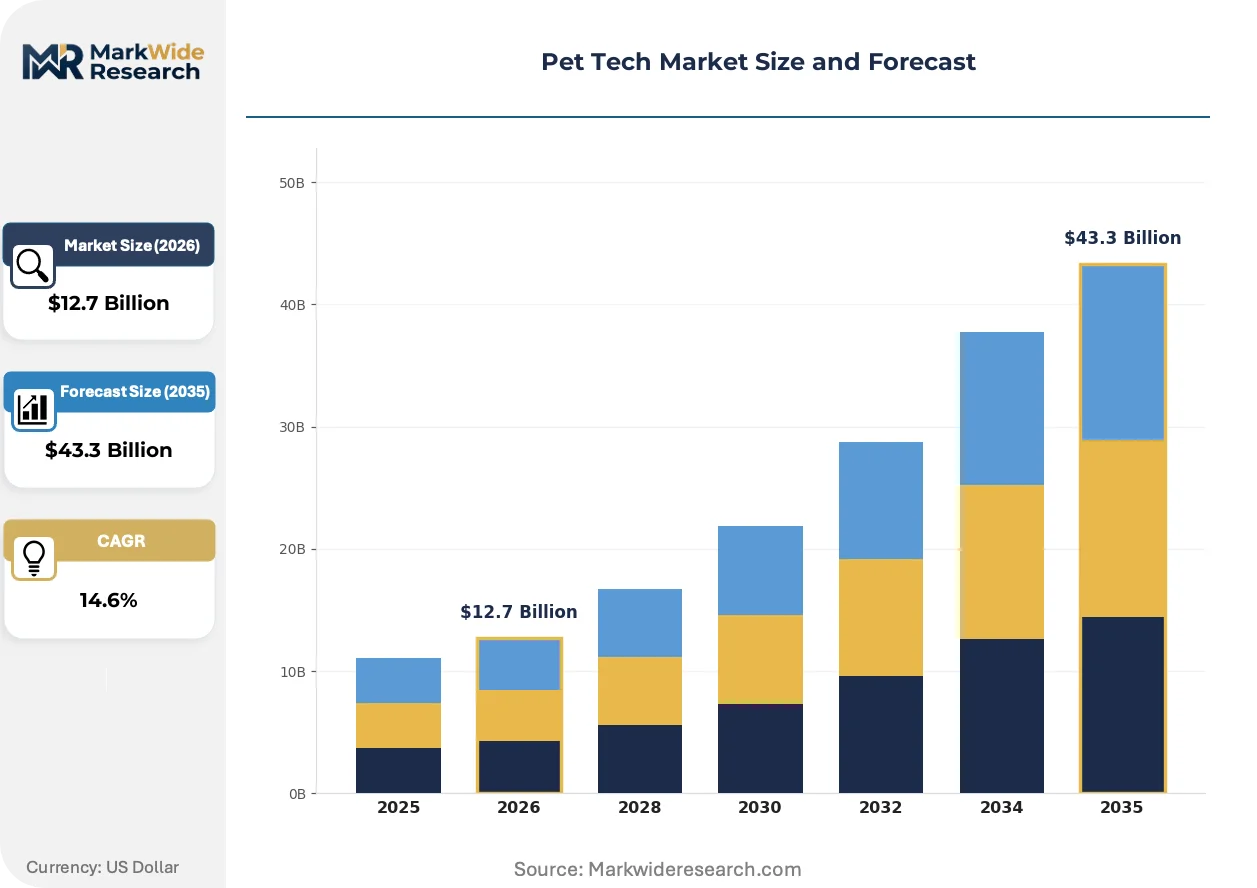
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $43.3 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Nutrition Trackers, Smart Feeders, Interactive Toys Technology: IoT Solutions, GPS Tracking, Artificial Intelligence, Bluetooth Connectivity Application: Health Monitoring, Training, Playtime Engagement, Exercise Tracking End User: Pet Owners, Veterinarians, Shelters, Trainers |
| Companies Covered | Pawbo, Luma Pet Ltd, Garmin International, Vetster, Petnow Inc., Mars Incorporated, Furbo, Moggie.me, Petcube, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Tech Market Emerging Trajectories
Edge computing architectures and federated learning frameworks are redistributing data processing from cloud centers to device-local inference, altering competitive requirements for hardware-software integration.
Low-power wide-area network (LPWAN) protocols are fragmenting connectivity standards across pet tech devices. Cat-M1 and NB-IoT chipsets enable GPS tracking without smartphone tethering. Rural and working-dog segments are adopting these standards fastest. The technology is fragmenting vendor ecosystems into carrier-partnered versus Bluetooth-dependent competitive camps.
EU AI Act risk classification rules are reshaping algorithm deployment for health-monitoring devices. Diagnostic features triggering high-risk categorization face conformity assessment burdens. Wearable vendors with veterinary diagnostic claims in European markets are restructuring feature sets to avoid classification thresholds.
Subscription unbundling is separating hardware ownership from analytics access. Pet owners purchase devices outright while paying monthly for AI-powered health insights and tele-veterinary connectivity. United States direct-to-consumer channels are capturing this shift ahead of retail and veterinary distribution.
Pet Tech Market Segmentation
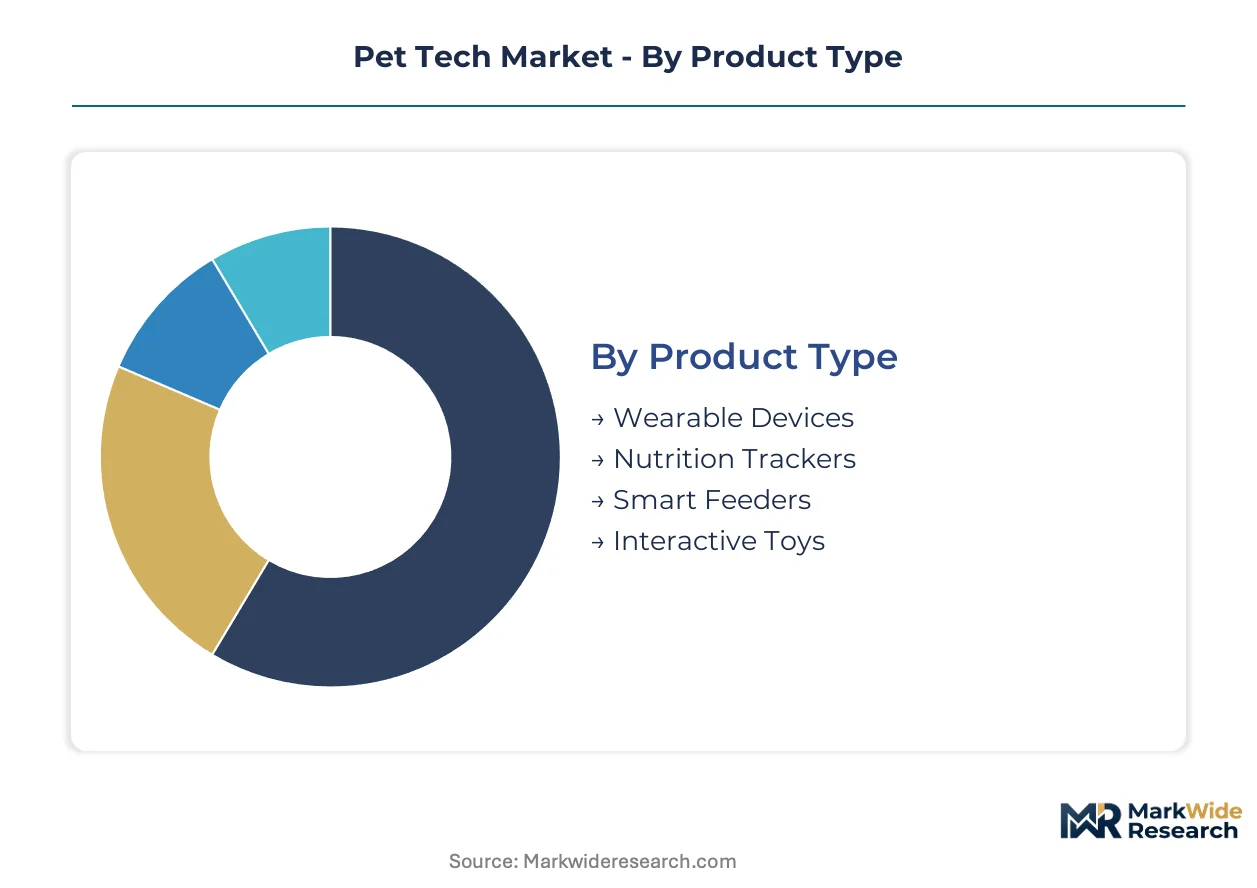
Pet tech segmentation reveals divergent channel economics across hardware categories and user workflows. Product type and end user dimensions determine whether devices flow through retail, veterinary, or direct-to-consumer channels with markedly different margin structures.
Product Type:
Wearable devices and smart feeders dominate veterinary and premium retail channels, while nutrition trackers and interactive toys concentrate in mass-market and e-commerce distribution.
- Wearable Devices:Biometric collars and activity monitors incorporate accelerometers, photoplethysmography sensors, and IP67-rated housings for continuous physiological capture. Demand clusters among urban pet owners in the United States seeking preventive health insights, constrained by lithium-ion supply volatility affecting hardware margins.
- Smart Feeders:Microprocessor-controlled dispensing systems with portion calibration and smartphone scheduling interface anchor the connected home ecosystem. Veterinary clinics in Germany and France are prescribing these for diabetic pet management, driving prescription-channel adoption.
- Nutrition Trackers:Camera-enabled bowl monitors with AI food recognition algorithms.
- Interactive Toys:Motion-activated laser and treat-dispensing units with Bluetooth 5.0 pairing.
By volume, interactive toys lead. By growth pace, wearable devices are climbing the fastest.
Technology:
Technology choice determines power architecture, connectivity cost, and data sovereignty positioning across customer segments.
- Artificial Intelligence:Edge-deployed neural networks for behavioral classification and anomaly detection run on-device to minimize latency and cloud dependency. Breed-specific health baselines trained on veterinary datasets in Japan and the United Kingdom are expanding predictive alert capabilities.
- GPS Tracking:Multi-constellation receivers with Cat-M1 fallback enable geofencing and recovery services for working dogs and rural deployments. Adoption concentrates in Australia and Canada where livestock protection and search-and-rescue applications justify hardware premiums.
- IoT Solutions:Cloud-integrated sensor networks with API ecosystems for third-party platform integration.
- Bluetooth Connectivity:Low-energy protocols for smartphone-tethered data sync in cost-sensitive consumer segments.
Bluetooth connectivity commands unit volume leadership. Artificial intelligence captures the steepest expansion trajectory.
Application:
Application segmentation maps to distinct hardware specifications and recurring revenue potential.
- Health Monitoring:Continuous glucose monitors, ECG-enabled vests, and respiratory rate trackers with FDA Center for Veterinary Medicine clearance pathways. United States veterinary chains are standardizing these for post-surgical and chronic condition management.
- Exercise Tracking:Step-counting wearables with breed-adjusted activity targets and calorie burn estimation. Demand from working dog handlers in rural Germany and competitive agility communities in the United Kingdom supports premium positioning.
- Training:Remote correction collars and positive-reinforcement clicker systems with geofencing integration.
- Playtime Engagement:Automated laser and feather toys with motion sensing and owner-remote activation.
Health monitoring leads in revenue per unit. Exercise tracking is gaining share fastest among performance-oriented owners.
End User:
End user type dictates purchasing authority, price sensitivity, and integration complexity requirements.
- Veterinarians:Clinical-grade diagnostic wearables with EHR integration and telemedicine platform connectivity. United States specialty practices are consolidating procurement through group purchasing organizations, compressing vendor margins while expanding volume commitments.
- Pet Owners:Direct-to-consumer purchasers through Amazon, Chewy, and brand-owned e-commerce with subscription bundling. Urban millennials in New York and Los Angeles demonstrate highest willingness-to-pay for AI-enabled health analytics.
- Shelters:Volume purchasers of basic identification and health screening tools for intake processing.
- Trainers:Behavior-focused professionals prioritizing GPS boundary systems and remote correction devices.
Pet owners dominate unit shipments. Veterinarians deliver the highest customer lifetime value through recurring diagnostic service subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine oversight in the United States establishes the regulatory baseline that shapes product development cycles and clinical claim pathways across developed markets.
United States
Urban millennials in New York and Los Angeles drive premium wearable adoption with subscription bundling for AI health analytics. FDA Center for Veterinary Medicine guidance on digital health devices accelerates clearance pathways for biometric monitors. Veterinary chains in Texas and California are consolidating procurement through group purchasing organizations.
Germany
Working dog handlers in rural Bavaria and competitive agility communities sustain demand for exercise-tracking wearables with breed-adjusted activity targets. REACH chemical standards constrain battery and polymer material choices, forcing durability redesigns. Veterinary clinics in North Rhine-Westphalia prescribe smart feeders for diabetic pet management.
Japan
METI incentives for eldercare technology extension create regulatory tailwinds for arthritis monitoring devices targeting the country's aging pet population. PMDA clearance processes for diagnostic algorithms remain rigorous but predictable. Machine learning tools trained on breed-specific biometric baselines in Kanto cluster around Tokyo veterinary research centers.
United Kingdom
Competitive agility communities and performance-oriented owners support premium positioning for exercise-tracking hardware. EU AI Act risk classification rules reshape algorithm deployment for health-monitoring devices sold across the channel. Breed-specific health baselines trained on veterinary datasets expand predictive alert capabilities in Greater London research partnerships.
Australia
Livestock protection and search-and-rescue applications justify hardware premiums for GPS-enabled tracking devices in Queensland and Western Australia. Multi-constellation receivers with Cat-M1 fallback enable geofencing services for working dogs in rural deployments. TGA oversight of animal health devices aligns with veterinary telemedicine platform growth in Sydney and Melbourne.
Pet Tech Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Veterinary data science capabilities concentrate advantage among integrated hardware-analytics firms while hardware-only vendors face margin compression. Three archetypes dominate: GPS heritage technology extenders, retail-veterinary channel controllers, and camera-integrated engagement platform specialists. M&A activity targets veterinary data science talent pools, while strategic partnerships with clinic networks bypass retail margin extraction.
Within the integrated analytics tier, Garmin International and Mars Incorporated exemplify divergent pathway dominance. Garmin International leverages location-tracking heritage into wearable device leadership. Mars Incorporated sustains broad channel control through retail and veterinary distribution networks. Petcube occupies the premium home-monitoring tier through camera-integrated engagement platforms.
| Leading Market Players |
|---|
| Pawbo |
| Luma Pet Ltd |
| Garmin International |
| Vetster |
| Petnow Inc. |
| Mars Incorporated |
| Furbo |
| Moggie.me |
| Petcube |
| Others |
Supply Flow & Price Mechanics
FDA Center for Veterinary Medicine clearance pathways gate both component supplier qualification and price tier separation in the United States, with CE marking and PMDA processes extending similar dual-control effects in Europe and Japan. Hardware vendors face simultaneous certification costs and tiered pricing pressure that compress margins at the economy end while rewarding premium positioning.
Pricing Analysis
United States urban markets command premium multiples over rural Germany and working-dog segments in Australia. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic wearables from Bluetooth-tethered activity trackers and unbranded commodity sensors. Cost compression in the economy tier intensifies because lithium-ion supply volatility and smartphone-dependency constraints limit addressable markets. Shelters and mass-market e-commerce buyers exhibit highest price sensitivity; veterinary chains and direct-to-consumer AI-analytics subscribers demonstrate lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate wearable assembly for fast-moving consumer channels, while strategic stockpiling of Cat-M1 chipsets and IP67-rated polymer housings secures production continuity for veterinary-grade devices. Component sourcing concentrates in China for lithium-ion cells and battery management systems, Taiwan for Bluetooth and GPS chipsets, and Germany for precision sensor modules. Single-source vulnerability in rare-earth magnet supply for GPS receivers creates exposure to export restriction shocks. Distribution runs through Amazon and Chewy for direct-to-consumer, clinic group purchasing organizations for veterinary, and mass retail for interactive toys.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet tech market exhibits cyclical recovery characteristics as veterinary clinic consolidation and subscription model maturation drive replacement demand for connected hardware. FDA digital health guidance acceleration and METI eldercare technology incentives provide cyclical uplift.
For Market Incumbents: Compound data science capabilities through targeted acquisition of veterinary analytics specialists, as hardware-only vendors face displacement from integrated hardware-software competitors. Deepen backward integration into edge-computing chip design to reduce Qualcomm and Nordic Semiconductor dependency. Defend against margin compression by locking multi-year lithium supply contracts before geopolitical disruption intensifies.
For New Entrants and Emerging Players: Differentiate on federated learning architectures that enable clinic-local model training without cloud data transfer, addressing EU AI Act high-risk classification concerns. Target Japan's aging pet population with arthritis monitoring devices, where METI incentives reduce regulatory friction and PMDA pathways remain predictable. Pursue direct-to-consumer launch through TikTok and Instagram shop integrations to bypass established retail margin extraction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed veterinary telemedicine platforms holding captive device distribution relationships. Long-term viability hinges on AI diagnostic claim substantiation capabilities and clinic network lock-in effects. Watch FDA 510(k) clearance velocity for biometric wearables as inflection indicator; acceleration signals channel consolidation opportunity, while delays suggest extended capital requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Data Science Acquisition | Captures scarce talent pools in animal physiology-machine learning intersection before salary premiums escalate further. |
| Edge Computing Architecture Deployment | Reduces cloud dependency and latency for behavioral classification algorithms running on-device in GPS collars. |
| Clinic Network Direct Partnership | Bypasses retail margin extraction and aligns device sales with prescription workflows in United States specialty practices. |
| EU AI Act Compliance Restructuring | Avoids high-risk classification thresholds for diagnostic features through algorithm feature-set modification. |
| Subscription Unbundling Launch | Separates hardware ownership from analytics access to capture recurring revenue in urban millennial segments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, veterinary clinic procurement databases, and hyperscaler IoT platform disclosures. Interviews with biomedical engineers at wearable device manufacturers, GPO contracts managers at United States veterinary chains, and regulatory affairs leads at animal health technology firms provided operational validation. Secondary sources include customs records for lithium-ion cell imports, App Annie data for pet tech application engagement, and SEC filings for connected hardware revenue segmentation. Bottom-up unit shipment estimates triangulate against top-down addressable market sizing.
Segmentation dimensions modeled span product type, technology architecture, application workflow, and end-user purchasing authority across the projection horizon. Wearable devices, smart feeders, and interactive toys anchor product segmentation; artificial intelligence, GPS tracking, and Bluetooth connectivity drive technology splits; health monitoring, exercise tracking, and training applications complete the framework. CAGRs derive from logistic diffusion curves fitted to veterinary adoption rates and consumer willingness-to-pay surveys. Breed-specific biometric baseline development timelines and FDA clinical validation pathway durations serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight, EU REACH chemical standards, and Japan METI eldercare incentive programs; material policy shifts would require re-modeling. Lithium supply disruption, smartphone penetration stagnation in rural markets, or EU AI Act risk reclassification constitute primary revision triggers. Revision becomes warranted when veterinary clinic consolidation rates or AI diagnostic claim substantiation timelines cross thresholds outside modeled ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
UK Pet Grooming Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
South America Dog Food Market
Pet Care Products
Asia-Pacific Pet Travel Services Market
Pet Care Products
Dry Dog Food Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
US Pet Food Market
Pet Care Products
Dog Float Market
Pet Care Products
North America Cat Food Market
Pet Care Products
China Pet Food Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Pet Care Market
Pet Care Products
Global Pet Carriers Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
Pet Transporting Service Market