
 USA Bird Food Market | 2026-2036
USA Bird Food Market Size, Share, and Industry Trends Forecast 2026-2036
USA Bird Food Market Analytics
Modular packaging configurations is pivoting how consumers purchase bird food, with retailers now bundling seasonal seed blends into stackable tubs alongside refill pouches. Kaytee leverages its R&D intensity to develop species-specific formulations that command shelf space in pet specialty channels. Pennington anchors its position through geographic dominance in the lawn and garden retail network, while Wild Birds Unlimited controls a premium franchise model that locks in recurring customer traffic.
USA bird food comprises formulated nutritional products designed to supplement or replace natural foraging for wild and captive birds, typically specified by protein content, fat percentage, and seed granularity calibrated to species beak morphology. The primary commercial purpose centers on attracting target bird species to residential observation settings while supporting avian health during seasonal migration stress. Seeds occupies the largest volume share among product types due to established consumer familiarity and lower per-unit pricing, though pellets represents the fastest-growing category as birders seek reduced-waste alternatives with complete nutritional profiles. Online channels capture expanding margin pools as subscription models reduce customer acquisition costs for specialized blends.
The FDA enforces Current Good Manufacturing Practice and Hazard Analysis requirements under FSMA for animal food facilities, elevating compliance costs for smaller regional blenders while creating barriers to market entry. The USDA's Agricultural Marketing Service oversees organic certification pathways that allow premium positioning for sunflower and millet products. State-level Department of Agriculture inspectors in key producing states conduct periodic facility audits that influence interstate distribution eligibility. Stakeholders must monitor evolving state wildlife feeding restrictions and municipal nuisance ordinances that could constrain backyard birding participation in densely populated jurisdictions.
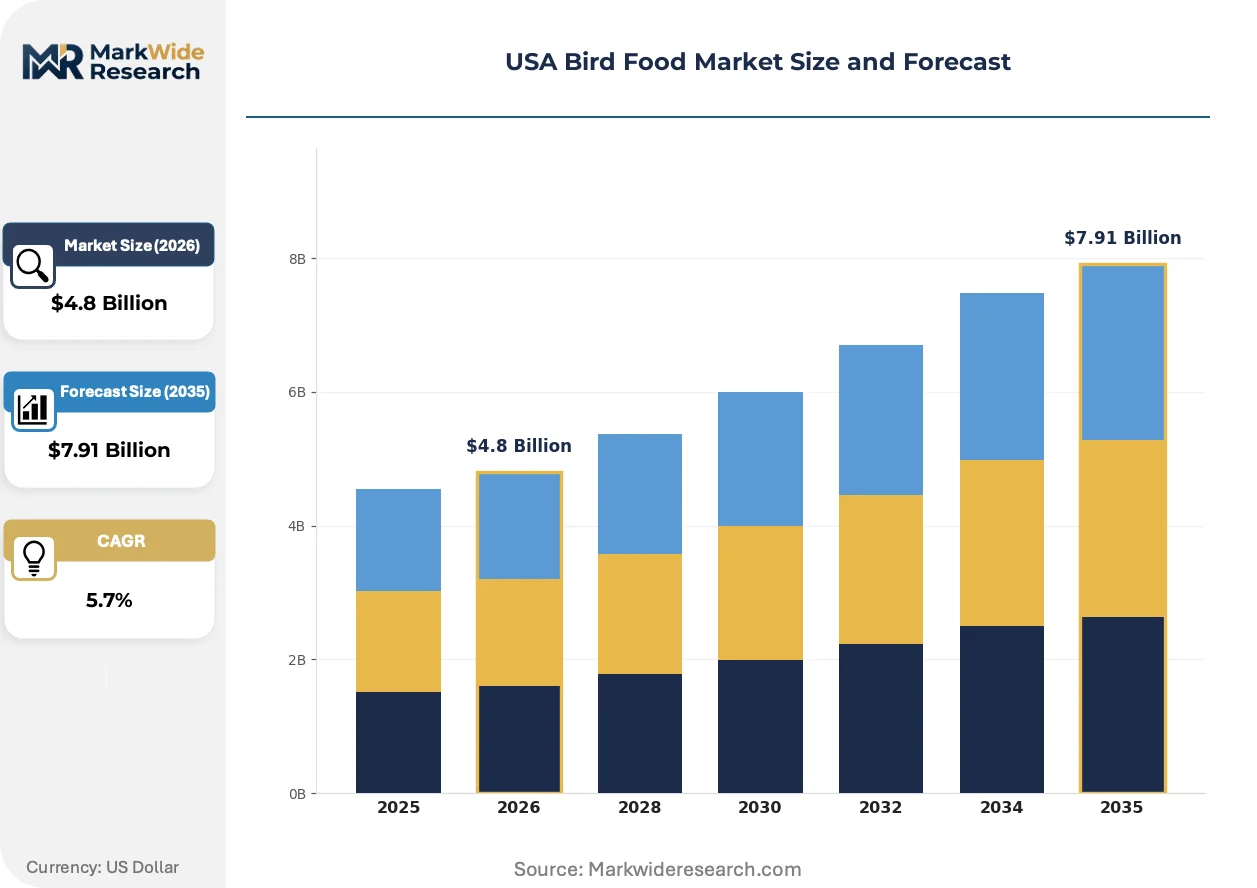
Market Dynamics
FSMA compliance mandates are compressing margins for regional blenders while accelerating consolidation toward vertically integrated manufacturers with captive laboratory testing capacity.
Growth Catalysts
- Backyard Birding Participation:Suburban households across the Midwest and Southeast are installing dedicated feeding stations at accelerating rates, creating durable recurring purchase patterns for specialized seed formulations.
- FDA FSMA Enforcement:Current Good Manufacturing Practice requirements are professionalizing production standards, elevating consumer trust in commercial bird food safety versus unregulated backyard mixing.
- Pellet Technology Maturation:Extruded complete-nutrition pellets are capturing share from traditional seed blends as waste-conscious birders prioritize clean feeding environments.
Market Restraints
- Sunflower Seed Price Volatility:Drought cycles in the Dakotas and Canadian Prairie provinces create input cost spikes that compress blender margins during contract renewal periods.
- Municipal Nuisance Ordinances:Dense coastal jurisdictions including Boston and San Francisco are restricting backyard feeding to reduce rodent vectors, constraining addressable household penetration.
- Wild Foraging Substitution:Native habitat restoration programs in exurban corridors reduce supplemental feeding dependency among target species during non-migration months.
Strategic Opportunities
- Subscription Channel Expansion:Direct-to-consumer platforms are capturing margin pools through automated replenishment of seasonal blends calibrated to regional migration calendars.
- USDA Organic Certification:Premium positioning pathways for sunflower and millet products allow price stratification above conventional commodity seed tiers.
- Species-Specific Formulation:Hummingbird nectar, suet cakes for woodpeckers, and finch-specific thistle blends create micro-segments with reduced price elasticity.
Industry Challenges
- Laboratory Testing Bottlenecks:FSMA-mandated hazard analysis verification requires third-party pathogen testing capacity that faces 6-8 week queue times during peak formulation cycles.
- Legacy Equipment Retrofit Costs:Regional blenders must replace open-air mixing vessels with enclosed pneumatic systems to satisfy FDA sanitary transport requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Bird Food Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeds, Pellets, Suet, Nuts Customer Type: Pet Owners, Retailers, Farmers, Garden Centers Packaging Type: Bags, Tubs, Boxes, Bulk Distribution Channel: Online, Supermarkets, Pet Shops, Farm Supply Stores |
| Companies Covered | ScottsMiracle-Gro, Kaytee, Pennington, Wild Delight, Wagner’s, Wild Birds Unlimited, Nature's Nuts, F.M. Brown's Sons, Songbird Essentials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Bird Food Market Evolving Landscape
Formulation science is migrating from commodity grain blending toward precision nutrition engineering, with packaging and channel models adapting to serve increasingly sophisticated hobbyist segments.
Extruded pellet technology is absorbing waste-reduction demand from suburban birders frustrated by discarded hulls and sprouted waste beneath traditional feeders. Homeowners in the Southeast and Pacific Northwest are converting to complete-nutrition pellets at rates exceeding the national average. This transition is absorbing shelf space from bulk seed bins in specialty retail channels.
The FDA's intensified FSMA enforcement is absorbing capital toward compliance infrastructure rather than product innovation. Small regional blenders face facility audit failures that trigger distribution suspensions until corrective action plans are implemented. Pellet manufacturers with integrated quality laboratories are capturing shelf space formerly occupied by commodity seed suppliers.
Birder purchasing is fragmenting across seasonal subscription platforms and big-box lawn-and-garden seasonal resets. Enthusiasts are consolidating volume through automated delivery while casual participants remain anchored to spring impulse purchases at home improvement centers. This bifurcation is most pronounced in the Midwest, where dedicated hobbyist density overlaps with mass retail penetration.
USA Bird Food Market Segmentation
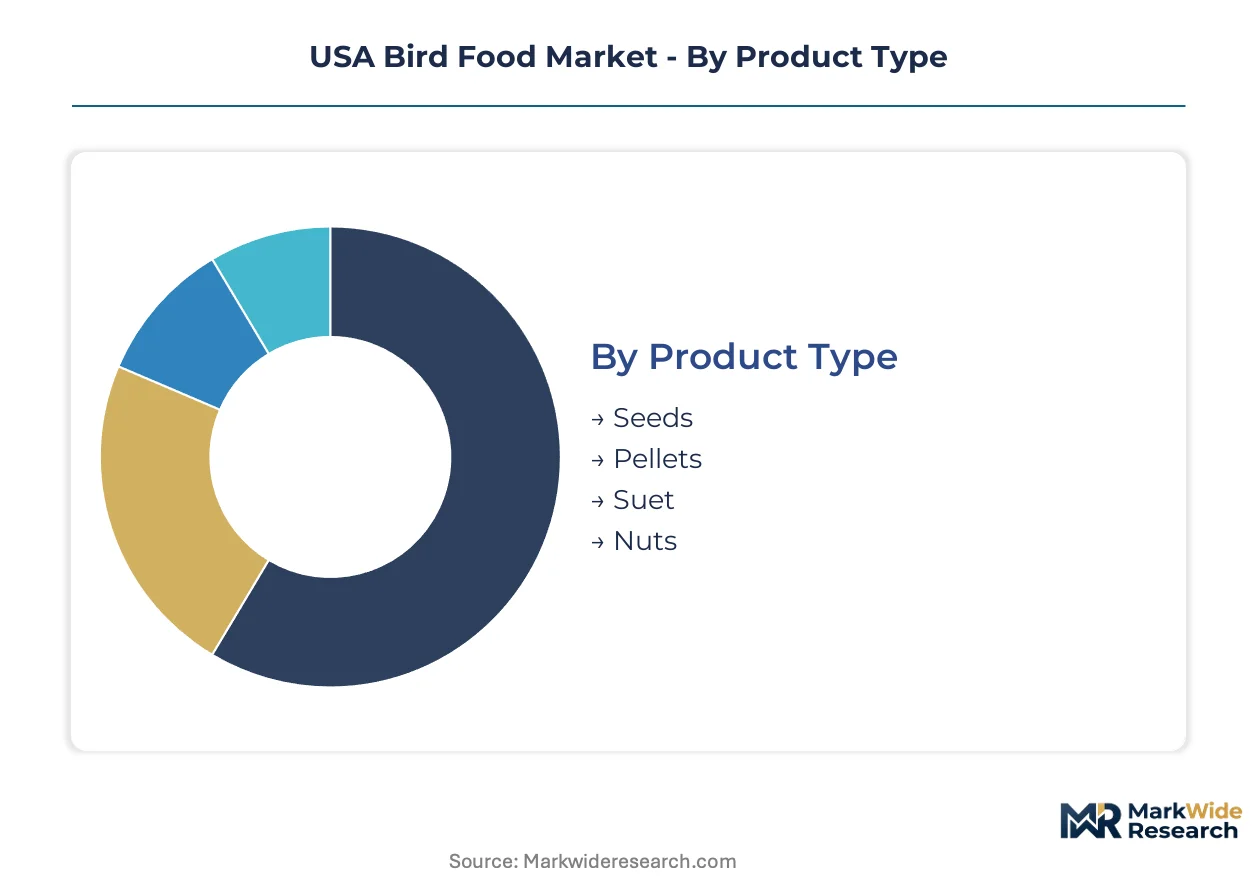
Bird food purchasing patterns diverge sharply between dedicated hobbyists seeking species-specific formulations and casual consumers responding to seasonal retail cues. Understanding these segment fractures reveals where margin pools concentrate and which channels warrant capital deployment.
Product Type:
Buyers in this category separate by waste tolerance and nutritional sophistication rather than price sensitivity alone.
- Seeds:Traditional grain blends dominated by sunflower, millet, and safflower varieties calibrated to regional bird populations. Midwest and Southeast suburban households drive recurring volume through established feeding station habits, though hull waste generates mounting frustration among maintenance-conscious homeowners.
- Pellets:Extruded complete-nutrition formulations manufactured through thermal processing that eliminates selective feeding behavior. Pacific Northwest and Southeast markets absorb these products fastest as cleanliness-minded birders prioritize tidy feeding environments over lower per-pound costs.
- Suet:Rendered fat cakes fortified with seeds, insects, or fruit targeted at woodpeckers and winter-resident species during cold-stress periods.
- Nuts:Whole or shelled peanuts and tree nuts positioned for high-energy demands of jays, nuthatches, and titmice.
Seeds leads volumes today; pellets is gaining share fastest.
Customer Type:
Purchase frequency and basket composition vary dramatically by whether the buyer maintains living inventory or serves end-consumers.
- Pet Owners:Individual hobbyists operating backyard feeding stations with species-specific knowledge and brand loyalty. These buyers generate the highest lifetime value through subscription replenishment and seasonal formulation switches aligned with migration calendars.
- Retailers:Independent pet shops and lawn-and-garden centers curating assortments for local bird populations. Their procurement concentrates on turn velocity and margin protection through private-label alternatives.
- Farmers:Agricultural operations purchasing bulk volumes for pest-control bird attraction or hobby-scale aviary maintenance.
- Garden Centers:Seasonal retailers anchoring bird food to spring planting and holiday gift cycles with limited year-round inventory depth.
Pet Owners anchor absolute revenue; Retailers command the densest purchase frequency.
Packaging Type:
Storage constraints and consumption rates dictate format selection more than unit economics.
- Bags:Flexible polywoven or paper containers dominating mass retail and farm supply channels. Standard 20-50 pound sizes serve high-volume feeders in rural and exurban corridors.
- Tubs:Rigid stackable containers with resealable lids capturing premium positioning in specialty pet channels. These formats reduce pest infiltration and moisture degradation for humid-climate households.
- Boxes:Corrugated retail packaging for gift-oriented suet cakes and nectar concentrates.
- Bulk:Loose-fill dispensing systems in cooperative and farm supply settings serving price-sensitive volume buyers.
Bags maintains volume leadership; Tubs shows the steepest expansion trajectory in dollar terms.
Distribution Channel:
Channel selection tracks buyer expertise and replenishment urgency more than demographic profile.
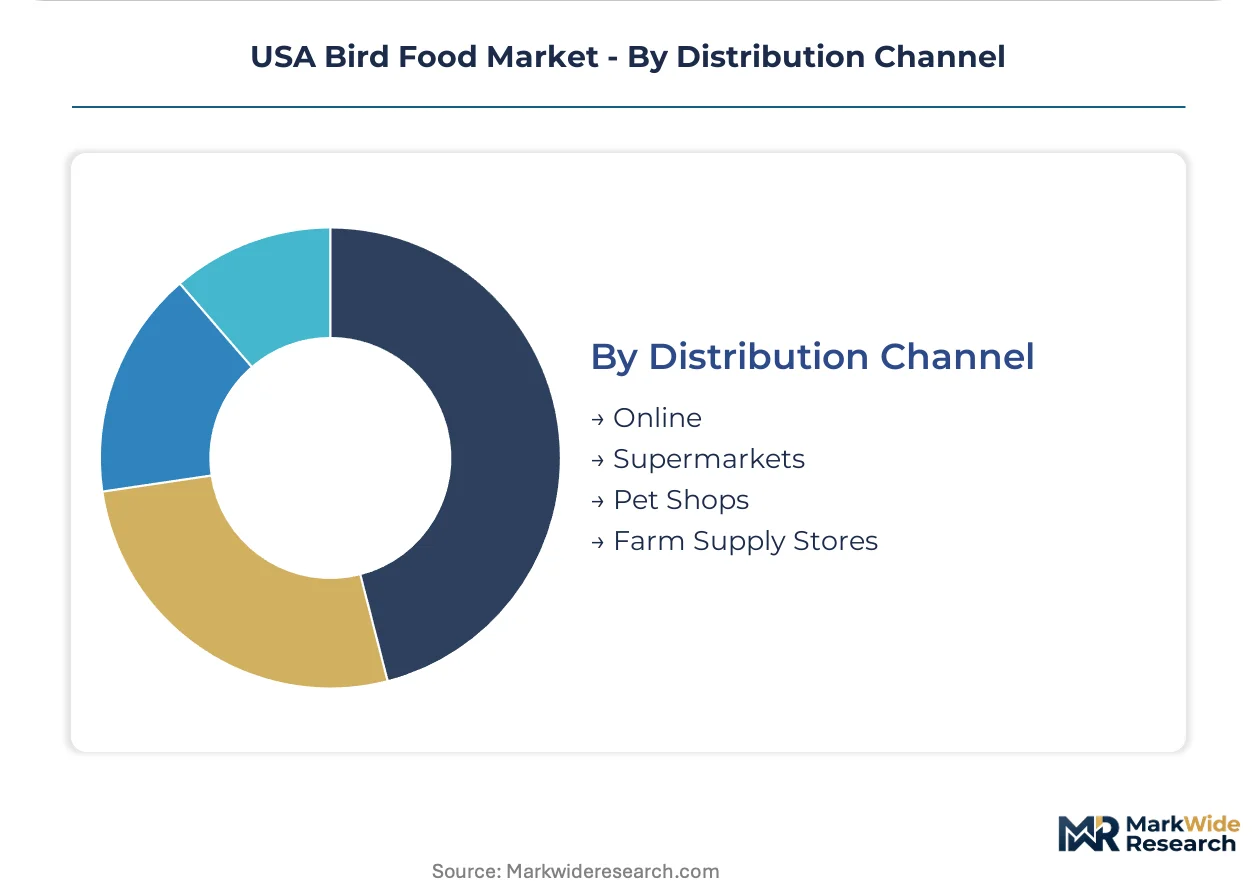
- Online:Direct-to-consumer platforms and marketplace sellers capturing subscription-driven recurring revenue. These channels absorb the most sophisticated buyers seeking species-specific formulations unavailable in mass retail.
- Supermarkets:Grocery and big-box lawn-and-garden seasonal resets serving impulse purchasers and casual participants. Spring reset periods concentrate volume in compressed windows.
- Pet Shops:Specialty retailers with trained staff guiding formulation selection for discerning hobbyists.
- Farm Supply Stores:Rural-focused distributors emphasizing bulk pricing and commodity seed blends for agricultural and large-property applications.
Supermarkets transact the most units; Online captures margin expansion most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial bird food production in the United States traces its origins to the post-war suburban expansion of the 1950s, when seed blending operations emerged to serve the nascent backyard birdwatching hobby across the Midwest and Eastern seaboard.
Midwest
Illinois, Ohio, and Michigan households maintain the densest concentration of dedicated feeding stations per capita, generating recurring bulk purchases through farm supply cooperatives and lawn-and-garden retailers. State Departments of Agriculture in Illinois and Ohio conduct periodic facility audits under FSMA-aligned protocols that determine interstate distribution eligibility for regional blenders. Chicago and Detroit metropolitan corridors anchor manufacturing and distribution infrastructure, with blending operations clustered near rail terminals serving Dakotas sunflower sourcing routes.
Southeast
Florida, Georgia, and North Carolina birders drive year-round consumption absent hard winter dormancy, sustaining elevated replenishment frequency through specialty pet channels and subscription platforms. Municipal nuisance ordinances in Miami-Dade and Atlanta metro jurisdictions periodically restrict backyard feeding density to manage rodent vectors, creating localized demand volatility. Raleigh-Durham and Charlotte serve as distribution hubs for pellet formulations targeting waste-conscious suburban homeowners.
Pacific Northwest
Washington and Oregon markets absorb complete-nutrition pellets fastest nationally, with Portland and Seattle metropolitan birders prioritizing tidy feeding environments over per-pound cost considerations. State environmental agencies in both jurisdictions monitor backyard feeding impacts on native habitat restoration programs, occasionally aligning with conservation groups to discourage supplemental feeding during non-migration months. Vancouver-Portland corridor blending facilities specialize in organic-certified sunflower products leveraging USDA Agricultural Marketing Service pathways.
Southwest
Texas and Arizona exurban expansion creates new addressable households, though drought-induced sunflower seed price volatility from adjacent Prairie provinces compresses blender margins during contract cycles. Texas Department of Agriculture inspectors enforce sanitary transport requirements that disadvantage smaller regional operators lacking enclosed pneumatic systems. Dallas-Fort Worth and Houston retail networks concentrate spring seasonal volume through big-box lawn-and-garden resets.
Northeast Corridor
New York, Pennsylvania, and New England states present constrained penetration due to dense urban zoning and wildlife feeding restrictions in Boston and New York City proper. Pennsylvania Department of Agriculture maintains stringent pathogen testing queues that extend 6-8 weeks during peak formulation cycles, favoring vertically integrated manufacturers with captive laboratory capacity. Philadelphia and Pittsburgh suburban rings retain viable hobbyist density supporting specialty pet channel presence.
USA Bird Food Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and channel access, with tiered pricing separating species-specific blends from bulk commodity seeds. The vendor base concentrates around three strategic archetypes: vertically integrated manufacturers with captive R&D laboratories, lawn-and-garden retail anchors with geographic distribution dominance, and premium franchise operators locking in recurring customer traffic. Dominant competitive moves include portfolio diversification into pellet technology and backward integration into organic-certified ingredient sourcing.
Among scale-driven manufacturers, ScottsMiracle-Gro and Kaytee occupy positions exemplifying the R&D-intensive archetype, while Pennington anchors the lawn-and-garden retail network tier. Wild Birds Unlimited represents the premium franchise model, sitting within a category that captures recurring traffic through membership-based customer relationships. These three named entities collectively illustrate how channel control and formulation specialization determine margin capture across suburban and exurban demand corridors.
| Leading Market Players |
|---|
| ScottsMiracle-Gro |
| Kaytee |
| Pennington |
| Wild Delight |
| Wagner's |
| Wild Birds Unlimited |
| Nature's Nuts |
| F.M. Brown's Sons |
| Songbird Essentials |
| Others |
Value Network & Pricing Analysis
Captive laboratory testing capacity anchors both supply security and pricing power for pellet manufacturers facing FSMA-mandated hazard analysis verification. Vertically integrated operators with in-house pathogen testing bypass the 6-8 week third-party queue times that suspend distribution for regional blenders, translating compliance infrastructure into shelf space capture and premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates species-specific formulations from commodity seed blends. USDA organic certification and FSMA compliance tiering drive price differentiation, with certified organic sunflower products commanding stratification above conventional tiers. Pricing pressure stems from drought-induced sunflower seed volatility in the Dakotas and Canadian Prairie provinces compressing blender margins during contract renewals. Casual spring impulse buyers at big-box lawn-and-garden retailers exhibit highest price sensitivity; dedicated hobbyists subscribing to automated replenishment platforms show least sensitivity.
Supply Chain Analysis
Returns and refurbishment flows are minimal in bird food, though seasonal inventory rotation creates reverse logistics pressure for retailers managing spring reset unsold stock. Primary supply concentrates in the Dakotas and Canadian Prairie provinces for sunflower sourcing, with Illinois and Ohio anchoring Midwest blending infrastructure. Raw material dependencies center on sunflower, millet, and safflower seed grades. Single-source vulnerability runs through Prairie province drought cycles disrupting input costs. Distribution runs through rail terminals serving Chicago and Detroit metropolitan corridors, with last-mile delivery fragmenting between farm supply cooperatives and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as waste-conscious suburban birders migrate from hull-heavy seed blends toward complete-nutrition pellets, elevating formulation sophistication as the defining purchase criterion.
For Market Incumbents: Hedge against pellet technology displacement by accelerating captive laboratory investments that satisfy FDA FSMA enforcement timelines. Consolidate regional blending assets to absorb testing queue bottlenecks that suspend distribution for smaller competitors. Channel control through specialty pet retail relationships protects margin pools as mass retail seasonal resets commoditize volume tiers. For New Entrants and Emerging Players: USDA organic certification pathways in the Pacific Northwest open a window for premium positioning without competing against vertically integrated laboratory infrastructure. Target Washington and Oregon markets where cleanliness-minded birders prioritize tidy feeding environments and tolerate price premiums. White-space exists in species-specific micro-segments—hummingbird nectar concentrates and finch-specific thistle blends—where subscription platforms reduce customer acquisition costs. For Investors and Strategic Acquirers: Roll-up economics work for regional blenders with FSMA-compliant facilities because FDA enforcement is accelerating consolidation toward operators with captive testing capacity. Five-to-ten year viability favors pellet manufacturers with backward integration into organic-certified ingredient sourcing. Monitor municipal nuisance ordinance adoption in dense coastal jurisdictions as an inflection indicator constraining addressable household penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Laboratory Investment | FSMA-mandated hazard analysis verification absorbs 6-8 week queue times that suspend distribution. |
| Organic Certification Pathway | USDA Agricultural Marketing Service standards allow premium positioning above commodity sunflower tiers. |
| Subscription Platform Launch | Direct-to-consumer automated replenishment reduces customer acquisition costs for seasonal blend switches. |
| Species-Specific Formulation | Hummingbird nectar and finch thistle micro-segments exhibit reduced price elasticity versus commodity seeds. |
| Regional Blending Consolidation | Illinois and Ohio facility clusters leverage rail terminal access to Dakotas sourcing routes. |
Research Methodology
Direct dialogue with blending facility operators, specialty pet channel buyers, lawn-and-garden procurement managers, and state Department of Agriculture inspectors grounded qualitative findings. Secondary validation drew from FDA FSMA guidance documents, USDA Agricultural Marketing Service organic certification records, state-level facility audit protocols, and trade flow data through U.S. Customs. Bottom-up volume estimates triangulated against top-down category spend analysis.
Bottom-up modeling projected demand across product type, customer archetype, packaging format, and distribution channel dimensions over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Industry-specific inputs included regional migration calendar alignment for seasonal blend timing and municipal nuisance ordinance adoption tracking.
Revisions become necessary when FDA enforcement intensity shifts, drought cycles disrupt Prairie province sunflower harvests, or coastal jurisdictions expand wildlife feeding restrictions. Practitioners should monitor state-level facility audit failure rates and third-party laboratory queue times for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Raw Pet Food Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Dog Vest Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Pet Slow Feeder Bowl Market
Pet Care Products
Pet Tag Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
GPS Dog Collar Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Pet Water Fountain Market