
 Tobacco Cutting Machines Market | 2026-2036
Tobacco Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Tobacco Cutting Machines Market Insights
A capital-intensity divergence between integrated systems builders and component suppliers is rotating competitive advantage toward full-line providers. Hauni Maschinenbau GmbH leverages its vertical integration across conditioning, cutting, and drying modules to command premium positioning in high-volume cigarette manufacturing. Körber Technologies GmbH anchors its presence through aftermarket service networks that sustain recurring revenue from legacy machine installed bases. GD (G.D S.p.A.) differentiates via precision engineering partnerships with European original equipment manufacturers.
Tobacco cutting machines are industrial processing equipment designed to shred, slice, or granulate cured tobacco leaf to specified particle sizes, typically operating at throughput rates exceeding 6,000 kilograms per hour with cut-width tolerances of 0.1 millimeters. These systems serve as critical upstream assets in primary tobacco processing, determining burn characteristics, filling power, and final product consistency for cigarette and cigar manufacturers. Rotary cutting equipment dominates installed capacity across major processing facilities due to its continuous-feed design and uniform particle distribution, while electric cutting technology is displacing pneumatic alternatives as factories face escalating energy audits and carbon accounting requirements. Shredder cutting configurations occupy a specialized niche in pipe and hookah tobacco preparation where coarse, irregular particle geometry is commercially valued.
The FDA's Center for Tobacco Products enforces Good Manufacturing Practice standards that shape machine validation protocols for equipment supplying US cigarette manufacturers, while the EU Tobacco Products Directive mandates ingredient disclosure and traceability systems that require cutting-line integration with serialization infrastructure. China's SAMR enforces GB standards for tobacco machinery safety and electromagnetic compatibility, creating compliance thresholds for imported equipment. Stakeholders must monitor regulatory divergence between emissions-focused European frameworks and productivity-centered Asian enforcement to align R&D allocation and regional go-to-market sequencing.
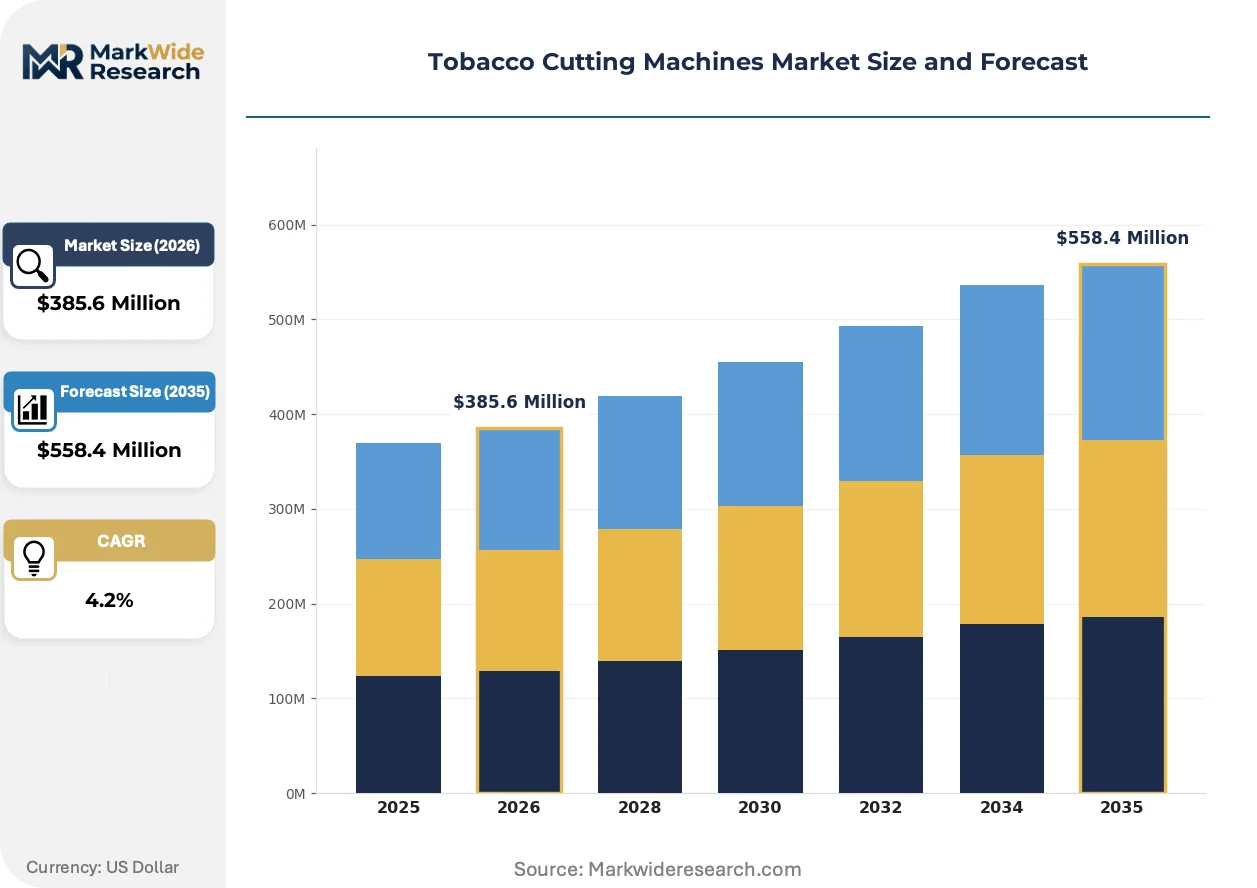
Market Dynamics
Electric cutting systems are displacing pneumatic infrastructure across Southeast Asian cigarette manufacturing, driven by WHO Framework Convention traceability mandates and national energy audits in Vietnam and Indonesia.
Growth Catalysts
- WHO FCTC traceability mandates:Cigarette manufacturers in Vietnam and Indonesia must modernize production lines for compliance, creating replacement demand for integrated cutting-to-serialization systems.
- Electric cutting technology:Factories phase out pneumatic systems to meet energy efficiency compliance, with electric drives offering 15-20% power reduction and simplified carbon accounting.
- Hookah tobacco preparation:Shredder cutting configurations gain traction in pipe and hookah segments where coarse, irregular particle geometry commands commercial premiums.
Market Restraints
- Specialized steel alloy volatility:Rotary cutter blade materials face price instability from nickel and cobalt supply concentration in Central African mining operations.
- GB standard electromagnetic compliance:China's SAMR enforcement creates certification friction for European and Japanese equipment imports, extending validation timelines.
- Heat-not-burn substitution:Reduced tobacco heating products compress leaf processing volumes in South Korean and Japanese manufacturing facilities.
Strategic Opportunities
- Indonesia's unpenetrated mid-tier:Domestic kretek cigarette producers operate aging pneumatic infrastructure, creating white space for electric retrofit packages.
- EU Tobacco Products Directive serialization:Mandated ingredient disclosure and track-and-trace systems require cutting-line integration with authentication infrastructure.
- IIoT-converged predictive maintenance:Sensor-embedded rotary cutters enable remote throughput optimization, opening recurring revenue streams for full-line providers.
Industry Challenges
- Electromechanical technician scarcity:Electric cutting system deployment outpaces vocational training capacity in Vietnamese and Indonesian industrial zones.
- FDA GMP validation timelines:Center for Tobacco Products documentation requirements extend equipment qualification periods for suppliers to US manufacturers.
- Legacy pneumatic integration:Retrofit projects face control architecture mismatches between 1990s-era programmable logic controllers and modern electric drive systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tobacco Cutting Machines Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $558.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Rotary Cutting, Guillotine Cutting, Rotary & Guillotine, Shredder Cutting Cutting Technology: Electric Cutting, Pneumatic Cutting, Hydraulic Cutting, Manual Cutting Application: Cigarette Manufacturing, Cigar Production, Pipe Tobacco Processing, Hookah Tobacco Preparation End User: Original Equipment Manufacturers, Contract Manufacturers, Tobacco Packagers, Aftermarket Suppliers |
| Companies Covered | Körber Technologies GmbH, Hauni Maschinenbau GmbH, GD (G.D S.p.A.), COMAS S.p.A., Focke & Co., TREZO Sp. z o.o., Akyurek Technology, Tokyo Automatic Machinery Works, Vinpat Machinery OPC Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tobacco Cutting Machines Market Trends and Innovations
Precision engineering and digital integration are compressing equipment footprints while expanding throughput capabilities. Manufacturers now compete on energy-adjusted output metrics rather than raw speed.
Direct-drive servo motors are miniaturizing rotary cutter powertrains while maintaining 6,000 kilogram-per-hour throughput. Vietnamese and Indonesian factories adopt these compact units to reclaim floor space for serialization modules. The technology is miniaturizing traditional gearbox assemblies into integrated motor-spindle units that reduce maintenance intervals.
The EU Tobacco Products Directive mandates ingredient disclosure and traceability infrastructure that cutting lines must feed directly. Cigarette manufacturers in Germany and Poland retrofit conditioning-to-cutting sequences with automated sampling ports. High-volume exporters to European markets face the steepest compliance costs, driving preference for full-line providers with integrated serialization.
After-sales service unbundling accelerates as component suppliers offer standalone maintenance contracts for legacy pneumatic systems. Indonesian kretek producers fragment vendor relationships, sourcing blades from one supplier and control retrofits from another. This pattern concentrates in Southeast Asian facilities where capital constraints favor incremental upgrades over integrated replacements.
Tobacco Cutting Machines Market Segmentation
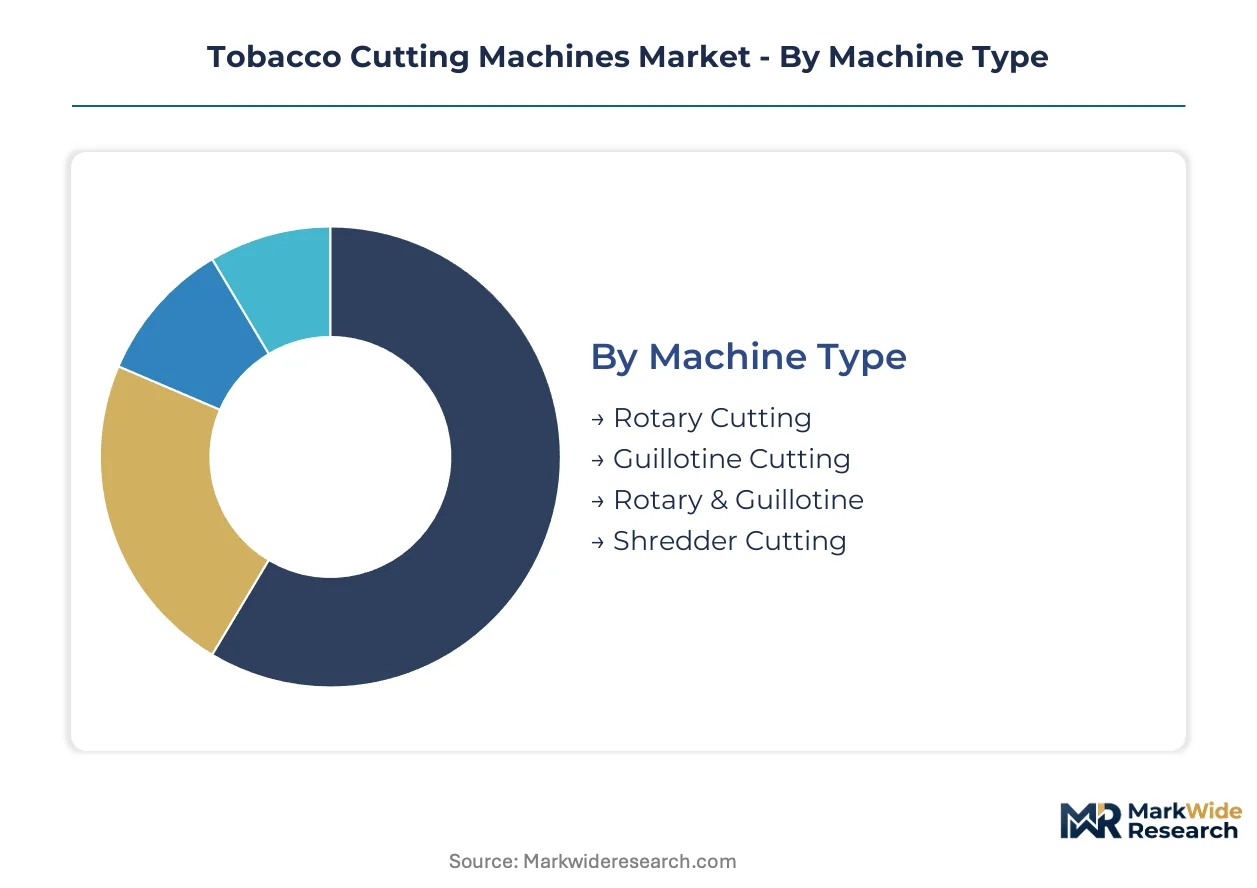
Tobacco cutting machine segmentation reveals how regulatory pressure and energy compliance reshape procurement patterns across primary processing. Manufacturers configure product portfolios around traceability mandates and carbon accounting requirements rather than throughput alone.
Machine Type:
FDA GMP validation protocols and EU Tobacco Products Directive serialization requirements create divergent equipment specifications across manufacturing destinations.
- Rotary Cutting:Continuous-feed drum systems achieve 6,000+ kilograms per hour with 0.1 millimeter cut-width tolerance. Demand concentrates in high-volume cigarette facilities in Germany and Poland where EU traceability mandates require stable, auditable throughput.
- Shredder Cutting:Coarse-geometry blade configurations produce irregular particle distributions valued in hookah and pipe tobacco preparation. Adoption climbs fastest in Indonesia's kretek segment and Middle Eastern processing clusters where traditional consumption patterns persist.
- Guillotine Cutting:Reciprocating blade systems suit batch-oriented cigar production with lower throughput requirements.
- Rotary & Guillotine:Hybrid configurations serve multi-product facilities seeking format flexibility without dedicated lines.
Established volume favors rotary configurations; emerging adoption favors shredder systems for specialty tobacco segments.
Cutting Technology:
Factory energy audits in Vietnam and Indonesia accelerate displacement of legacy pneumatic infrastructure toward electrified alternatives.
- Electric Cutting:Servo-driven blade actuation reduces power consumption 15-20% versus pneumatic equivalents while simplifying carbon footprint documentation. Vietnamese facilities prioritize these systems to satisfy national efficiency compliance deadlines.
- Pneumatic Cutting:Compressed-air infrastructure dominates installed bases across Southeast Asian kretek producers. Indonesian manufacturers face retrofit cost barriers despite rising energy audit pressure.
- Hydraulic Cutting:High-torque systems persist in cigar production requiring dense leaf compression.
- Manual Cutting:Artisan-scale equipment serves craft tobacco processors and heritage brand preservation.
Procurement momentum concentrates in electric systems; residual demand sustains pneumatic aftermarket services.
Application:
Heat-not-burn product expansion in South Korea and Japan compresses traditional leaf processing volumes while specialty segments expand.
- Cigarette Manufacturing:Integrated cutting-to-conditioning lines dominate capital allocation. German and Polish exporters to EU markets bear the steepest serialization compliance costs, driving preference for full-line providers.
- Hookah Tobacco Preparation:Shredder-dependent coarse cutting commands commercial premiums in Middle Eastern and Southeast Asian markets. Indonesian domestic consumption and Gulf export demand sustain capacity expansion.
- Cigar Production:Batch-oriented guillotine systems serve premium hand-rolled and machine-made segments.
- Pipe Tobacco Processing:Specialty flake and ribbon cuts occupy niche volume with stable artisan demand.
Volume concentration remains in cigarette systems; margin expansion favors hookah preparation equipment.
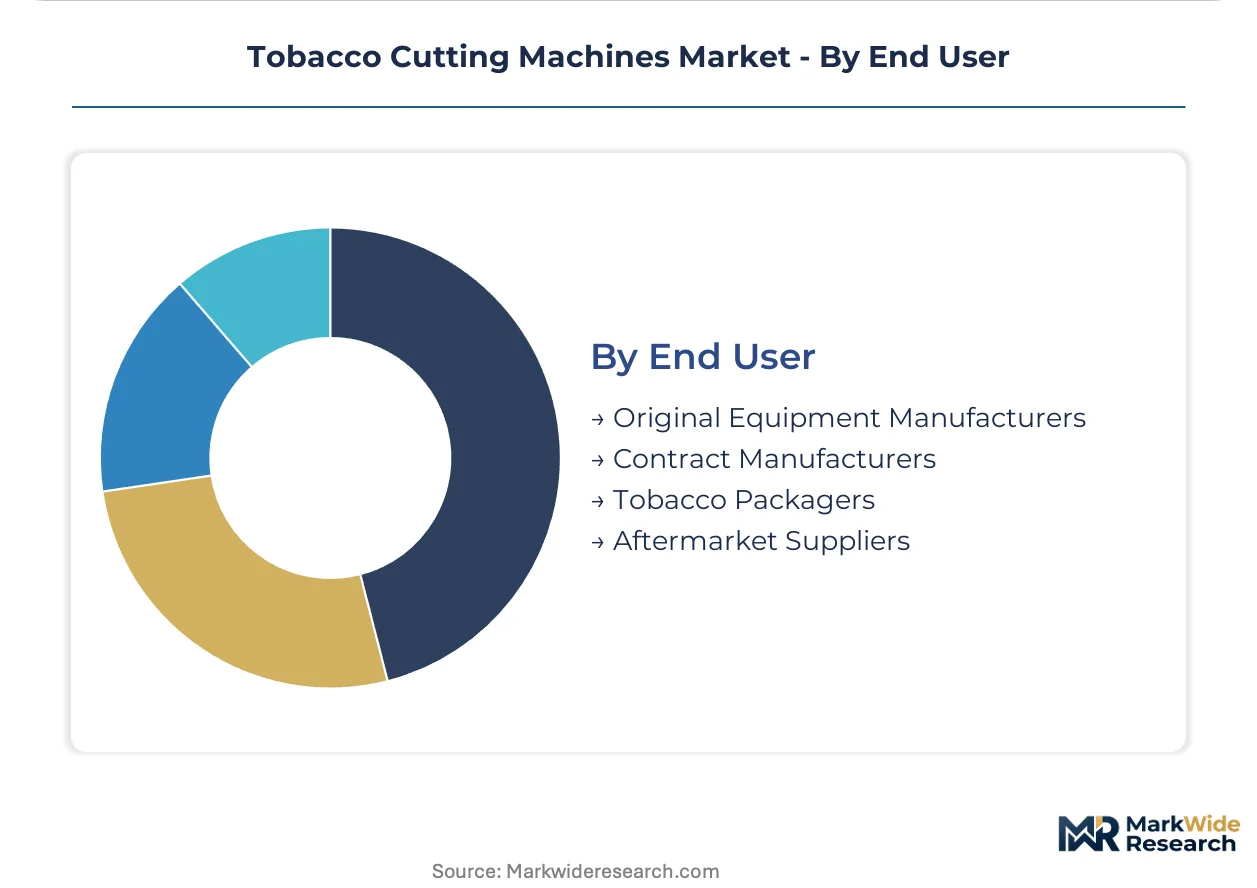
End User:
Capital intensity divergence rotates competitive advantage toward integrated full-line providers versus component specialists.
- Original Equipment Manufacturers:Vertically integrated builders capture premium positioning through conditioning-cutting-drying module control. These stakeholders dictate specification standards for downstream contract manufacturers.
- Contract Manufacturers:Toll processing facilities in Vietnam and Indonesia prioritize electric retrofit packages over greenfield investment. Capital constraints favor incremental upgrades to existing pneumatic lines.
- Tobacco Packagers:Late-stage integrators require cutting-line compatibility with serialization and authentication infrastructure.
- Aftermarket Suppliers:Blade replacement and control retrofit vendors fragment vendor relationships across Southeast Asian installed bases.
Recurring revenue concentrates in aftermarket channels; growth investment flows toward OEM integrated systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Italian machinery exporters while Vietnamese and Indonesian manufacturers absorb compliance cost premiums on imported electric systems. This asymmetry rotates procurement decisions toward regional fabrication partnerships.
Germany
Precision engineering clusters in Hamburg and Berlin-Brandenburg supply rotary cutting systems to EU exporters facing Tobacco Products Directive serialization mandates. The country's machinery builders command premium positioning through integrated conditioning-to-cutting modules. German facilities in the Ruhr industrial corridor specialize in high-throughput electric drives for Polish and Czech contract manufacturers.
China
Domestic kretek cigarette producers drive demand for shredder configurations in Yunnan and Guizhou provinces. SAMR enforcement of GB electromagnetic compatibility standards extends validation timelines for European equipment imports. Manufacturing concentration in the Yangtze River Delta produces blade alloys and control systems for Southeast Asian retrofit markets.
Vietnam
National energy audit deadlines accelerate factory replacement of pneumatic infrastructure with electric cutting systems. The country's industrial zones around Ho Chi Minh City and Hanoi host toll processing facilities prioritizing compact servo-driven units. Vietnamese contract manufacturers fragment vendor relationships across blade suppliers and control retrofit specialists.
Indonesia
Kretek cigarette production in East Java and Central Java sustains demand for coarse-geometry shredder cutting. Domestic producers operate aging pneumatic lines that face mounting pressure from WHO Framework Convention traceability mandates. Surabaya-based processing clusters represent the largest unpenetrated mid-tier opportunity for electric retrofit packages.
United States
FDA Center for Tobacco Products GMP validation protocols shape equipment qualification timelines for domestic cigarette manufacturers. Processing facilities in North Carolina and Virginia prioritize rotary cutting stability for burn consistency documentation. US machinery buyers favor full-line providers capable of integrated serialization compliance.
Tobacco Cutting Machines Market Competitive Landscape
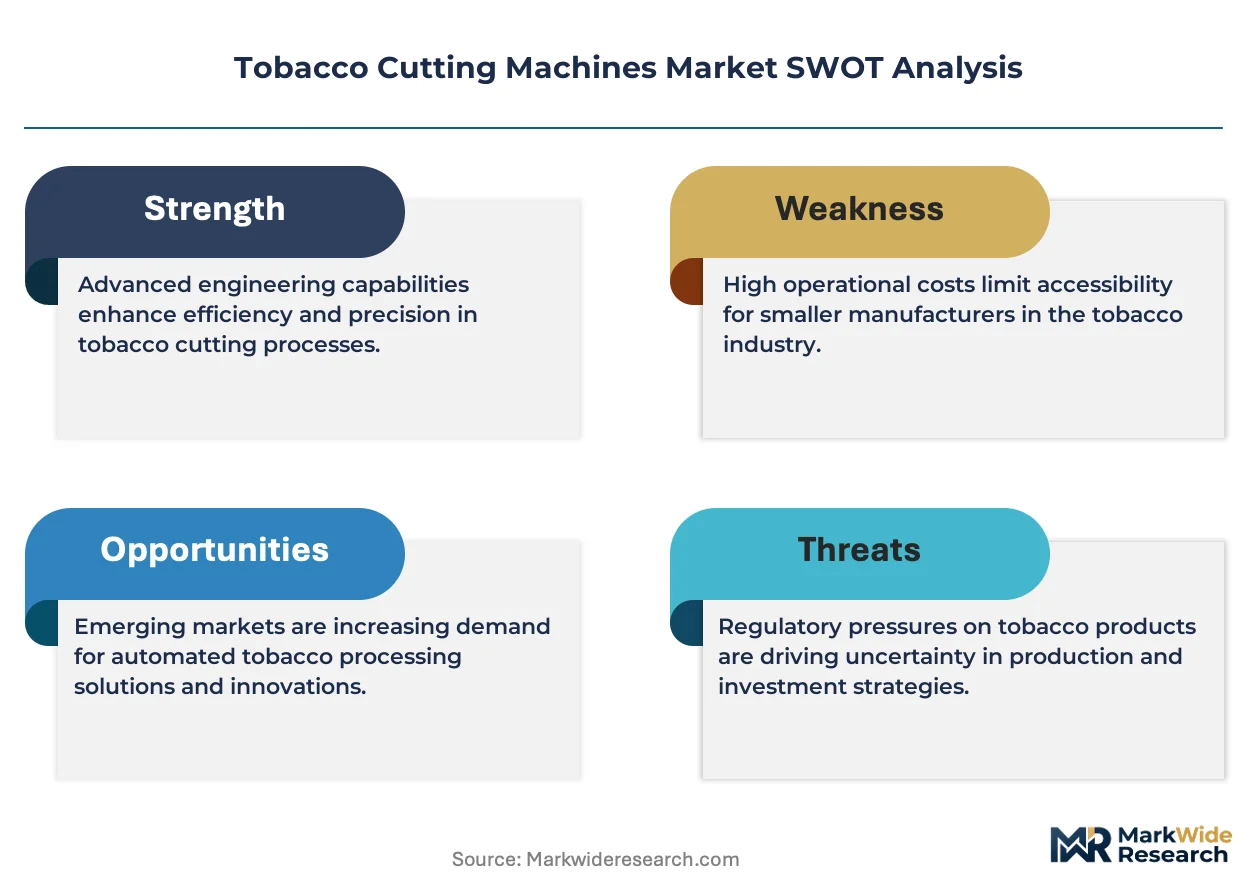
Concentration sits with vertically integrated European full-line builders and specialized component suppliers serving legacy installed bases. The vendor base separates into three strategic archetypes: conditioning-to-drying module integrators, aftermarket service specialists, and precision engineering partners. Competitive moves center on IIoT-converged predictive maintenance offerings and electric drive retrofit packaging for Southeast Asian pneumatic infrastructure.
Among German full-line builders, Hauni Maschinenbau GmbH and Körber Technologies GmbH exemplify the integrated systems archetype through captive control over upstream conditioning and downstream drying modules. Körber Technologies GmbH anchors recurring revenue streams via aftermarket service networks. Italian precision engineering specialists including GD (G.D S.p.A.) occupy partnership-dependent positioning with European original equipment manufacturers. COMAS S.p.A. represents the mid-tier fabrication segment serving regional cigarette processors.
| Leading Market Players |
|---|
| Körber Technologies GmbH |
| Hauni Maschinenbau GmbH |
| GD (G.D S.p.A.) |
| COMAS S.p.A. |
| Focke & Co. |
| TREZO Sp. z o.o. |
| Akyurek Technology |
| Tokyo Automatic Machinery Works |
| Vinpat Machinery OPC Private Limited |
| Others |
Pricing and Supply Chain Analysis
Ninety-day blade alloy lead times from Central African mining operations concentrate pricing power with specialty steel processors, compressing margins for European cutter manufacturers while amplifying premiums on certified electromagnetic-compliant systems for Chinese import.
Pricing Analysis
Configured-to-order electric cutting systems command 25-40% premiums over standard pneumatic equivalents, with price differentiation driven by SAMR GB certification tier and after-sales service bundling. Cost compression in mid-tier shredder configurations is intensifying because Indonesian kretek producers fragment vendor relationships across blade suppliers and retrofit specialists. Contract manufacturers in Vietnamese industrial zones exhibit highest price sensitivity; integrated full-line OEMs face lowest.
Supply Chain Analysis
Inventory cycles for nickel-cobalt blade alloys stretch 60-90 days, tethering supply security to Central African mining concentration and German precision forging clusters. Rotary cutter spindle assemblies draw from Italian machining centers and Japanese bearing specialists. Single-source vulnerability in cobalt supply creates exposure to export restriction shocks. Distribution runs through OEM direct sales for integrated systems and aftermarket parts networks for legacy pneumatic infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tobacco cutting equipment demand follows cigarette manufacturing capital expenditure cycles, with WHO FCTC compliance deadlines in Southeast Asia triggering a replacement wave across the analysis window.
For Market Incumbents: Compound aftermarket service revenue by unbundling maintenance contracts for Indonesian pneumatic installed bases while deepening upstream control over blade alloy supply. Electric cutting retrofit demand from Vietnamese contract manufacturers threatens component suppliers with disintermediation; prioritize IIoT-embedded predictive maintenance offerings to lock in recurring revenue. For New Entrants and Emerging Players: Anchor in Surabaya-based kretek processing clusters where aging pneumatic infrastructure and capital constraints create white space for modular electric retrofit packages. Indonesia's unpenetrated mid-tier favors go-to-market partnerships with local control systems integrators over direct OEM competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned tobacco machinery divisions lacking IIoT capabilities. Long-term viability hinges on heat-not-burn substitution pace in Northeast Asian markets. Monitor South Korean leaf processing volume trends as inflection signal for traditional cutting equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drive Retrofit Packaging | Captures Indonesian kretek modernization demand ahead of WHO FCTC traceability deadlines. |
| IIoT Predictive Maintenance Deployment | Converts Vietnamese contract manufacturers from transactional blade sales to subscription service models. |
| Blade Alloy Backward Integration | Insulates German full-line builders from Central African cobalt supply volatility and price spikes. |
| EU Serialization Line Integration | Locks in Polish and German exporters facing Tobacco Products Directive authentication mandates. |
| SAMR Certification Pre-Validation | Accelerates Chinese market entry timelines for European electric cutting system imports. |
Research Methodology
Operator-level perspectives from plant engineers at Vietnamese toll processing facilities, maintenance directors at Indonesian kretek manufacturers, and procurement leads at German cigarette exporters anchored the qualitative base. Secondary validation drew from SAMR GB standard filings, EU Tobacco Products Directive implementation guidance, and customs trade data for blade alloy imports. Bottom-up equipment shipment analysis triangulated against top-down cigarette production capacity estimates across the analysis window.
Sensitivity analysis tested forecast outputs against variable adoption rates for electric cutting technology and divergent WHO FCTC compliance timelines. The analytical framework modeled machine type, cutting technology, and application dimensions across the projection horizon. CAGRs derived from installed base replacement cycles and greenfield capacity additions in Southeast Asian processing clusters. Forecast inputs incorporated national energy audit enforcement intensity and heat-not-burn product substitution elasticities.
Decision-makers should treat outputs as directional under sustained WHO FCTC implementation and stable nickel-cobalt alloy supply; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Tobacco Films Market
Tobacco
North America Tobacco Market
Tobacco
Heat-Not-Burn Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Egypt Tobacco Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
Cigarette Paper Market
Tobacco
Middle East and Africa Smokeless Tobacco Market
Tobacco
Organic Tobacco Market
Tobacco
US Tobacco Market
Tobacco
North America Cigarette Market