
 Organic Tobacco Market | 2026-2036
Organic Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Tobacco Market Outlook
The gap between premium organic leaf and commodity-grade tobacco is shifting from a niche positioning tool to a structural market divider. Philip Morris International leverages its global procurement network to secure certified organic supply chains across multiple growing regions. Mother Earth Tobacco anchors its competitive stance through direct farmer partnerships that guarantee traceability from seed to shelf. Imperial Brands plc differentiates by concentrating its organic portfolio within European specialty channels where regulatory scrutiny on additive disclosure runs highest.
Organic tobacco denotes leaf cultivated without synthetic pesticides, herbicides, or genetically modified organisms, typically meeting third-party certification standards such as USDA Organic or EU Organic Regulation while maintaining nicotine content and combustion profiles comparable to conventional flue-cured varieties. The material serves manufacturers targeting consumers who associate chemical-free cultivation with reduced exposure risk, despite equivalent tar and carbon monoxide yields upon combustion. Roll-Your-Own products occupy the deepest margin pools as consumers pay premiums for perceived purity while purchasing raw leaf with minimal processing overhead. Snuff and cigarillos represent the fastest-expanding categories as smokeless formats bypass increasingly restrictive public smoking bans in urban centers.
USDA Organic certification and the EU Tobacco Products Directive jointly govern market access, with the former dictating cultivation inputs and the latter mandating ingredient transparency that amplifies consumer awareness of synthetic additive absence. Health Canada and the FDA apply parallel but non-identical standards for residual chemical testing, creating compliance complexity for cross-border suppliers. Stakeholders must monitor how evolving pesticide residue thresholds in major consuming countries reshape sourcing economics and farmer conversion incentives.
Market Dynamics
The EU Tobacco Products Directive is compressing disclosure timelines for additive content, forcing manufacturers to rebuild supply chains around certified organic leaf that can substantiate chemical-free claims through third-party verification.
Growth Catalysts
- EU Organic Regulation:Mandatory ingredient transparency under the EU Tobacco Products Directive is amplifying consumer awareness of synthetic additive absence, pulling certified leaf into premium cigarette formulations.
- Snuff and cigarillo manufacturers:Smokeless format producers are capturing margin expansion as urban smoking bans accelerate category rotation away from combustibles.
- German specialty tobacconists:Direct-to-consumer channels in Germany are commanding premium positioning through certified organic product exclusivity and traceability guarantees.
Market Restraints
- USDA Organic conversion costs:Synthetic pesticide elimination requires three-year field transition periods that depress yields before certification eligibility.
- Brazilian supply concentration:Organic flue-cured leaf sourcing clusters in southern Brazilian growing regions, creating weather and logistics vulnerability.
- Nicotine equivalence constraint:Organic cultivation methods must maintain combustion profiles comparable to conventional varieties without yield-enhancing GMO seed stock.
Strategic Opportunities
- Indian organic certification pipeline:Tobacco Board of India incentives for pesticide-free cultivation are opening farmer conversion programs in Andhra Pradesh and Karnataka.
- Heat-not-burn convergence:Reduced-risk product manufacturers are sourcing organic leaf to differentiate cartridge formulations in regulatory-sensitive European markets.
- Blockchain traceability platforms:Seed-to-shelf verification systems are enabling direct farmer partnerships that bypass traditional leaf merchant intermediaries.
Industry Challenges
- Multi-jurisdictional residue testing:Health Canada and FDA apply non-identical thresholds for synthetic chemical detection, complicating cross-border shipment compliance.
- Organic agronomist scarcity:Certified cultivation expertise for nicotine-bearing crops remains concentrated among legacy tobacco extension services with limited organic transition experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Tobacco Market |
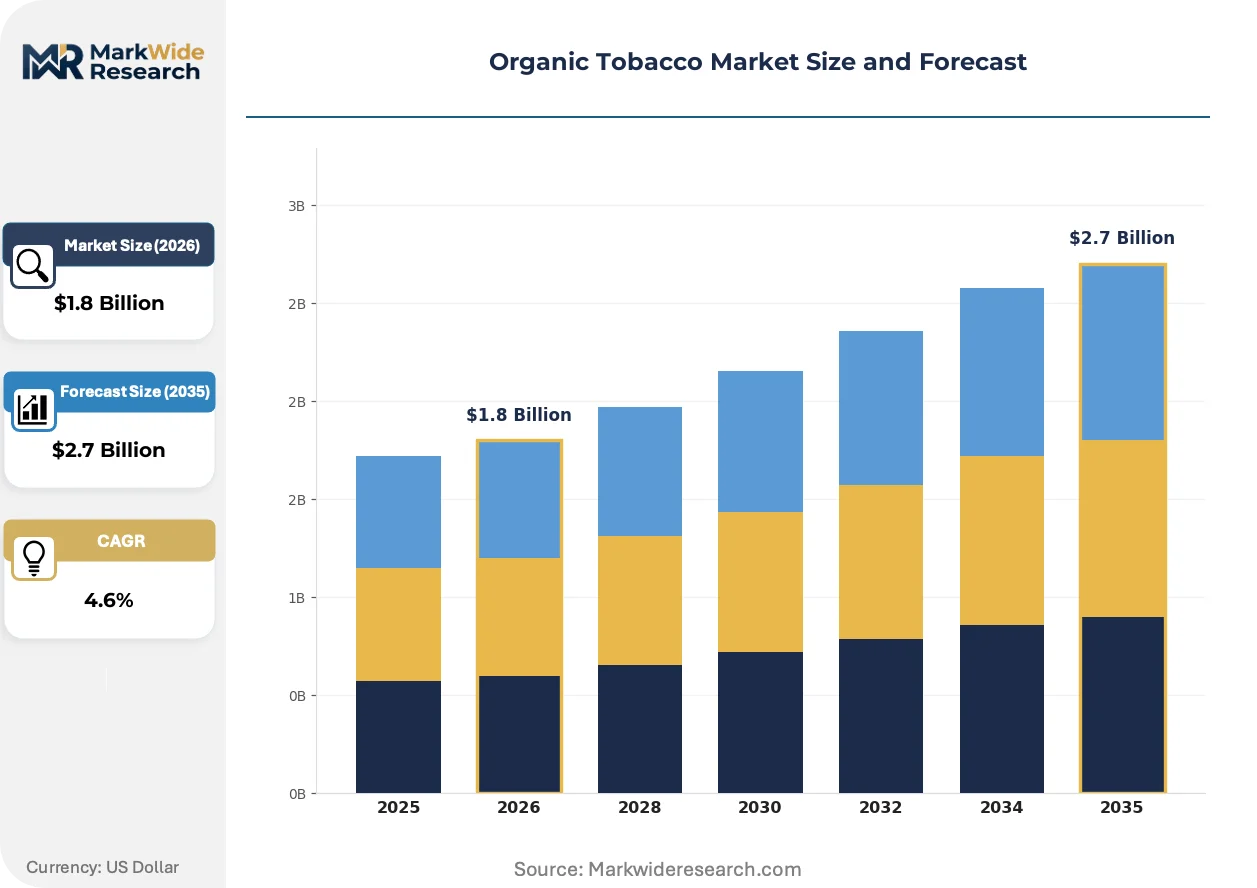
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-Your-Own, Snuff, Cigarettes, Cigarillos End User: Personal Use, Retailers, Wholesalers, Distributors Sales Channel: Online, Convenience Stores, Specialty Shops, Supermarkets Packaging Type: Loose, Pouches, Cans, Pre-packed |
| Companies Covered | Japan Tobacco Inc., Reynolds American Inc., Swedish Match AB, Philip Morris International, Mother Earth Tobacco, Santa Fe Natural Tobacco Company, MAC BAREN, Imperial Brands plc, Leaf Only, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Tobacco Market Strategic Shifts
Verification technologies and cultivation methods are converging to substantiate chemical-free claims while distribution channels fragment toward direct relationships between manufacturers and certified growers.
Spectral imaging for pesticide residue detection is electrifying incoming leaf inspection protocols at processing facilities. Cigarette manufacturers deploying this technology are compressing supplier qualification cycles from months to weeks. The structural consequence is a widening capability gap between integrated processors with in-house testing labs and commodity traders dependent on third-party certification.
REACH chemical registration requirements are tightening disclosure obligations for imported tobacco products entering European markets. Manufacturers must now document cultivation inputs across entire supply chains to satisfy downstream due diligence obligations. Roll-Your-Own product categories face the steepest compliance burden given their minimal processing overhead and direct consumer packaging.
Specialty tobacconist channels are displacing traditional wholesale distribution for certified organic products. German and Austrian retailers are building direct procurement relationships with certified cooperatives, bypassing leaf merchants entirely. This pattern concentrates most visibly in urban centers where consumers pay traceability premiums and regulatory scrutiny on additive disclosure runs highest.
Organic Tobacco Market Segmentation
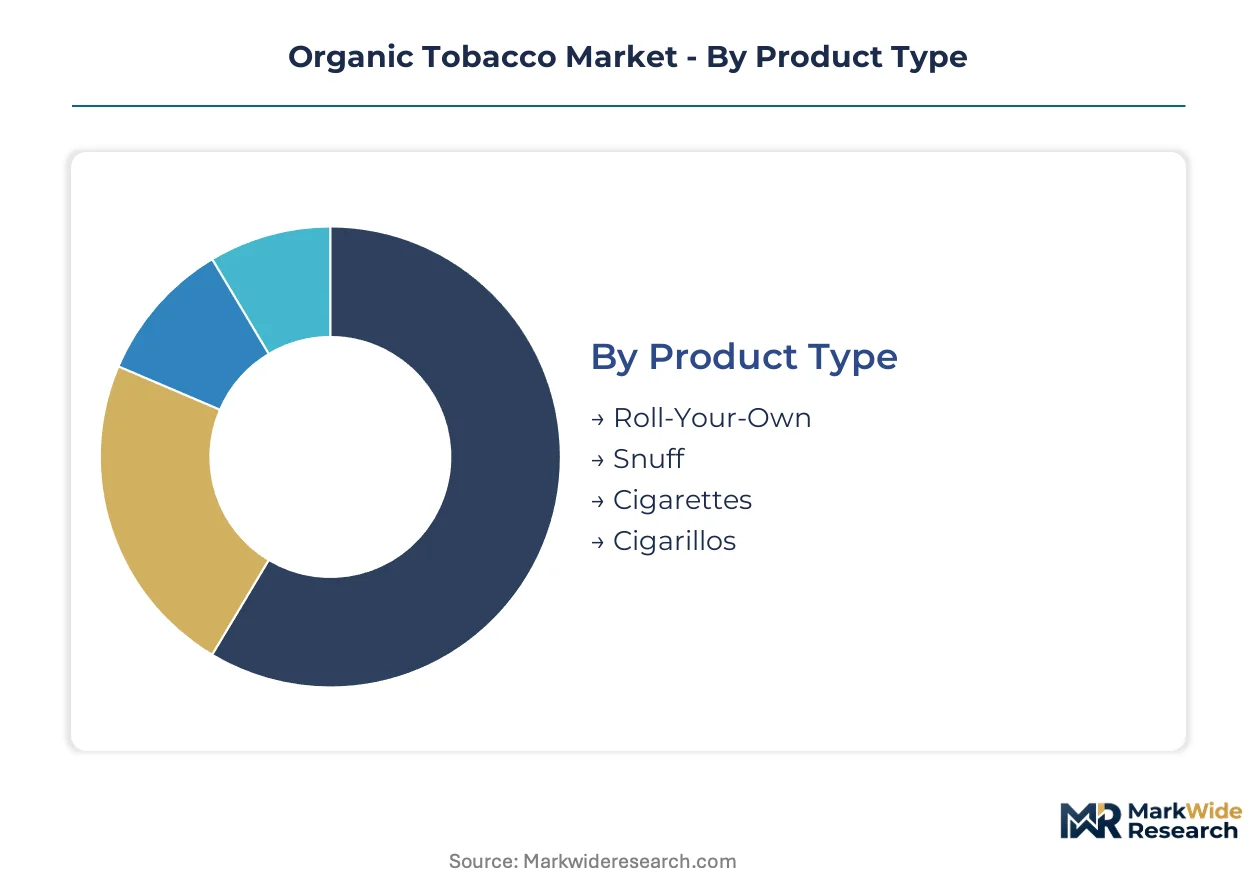
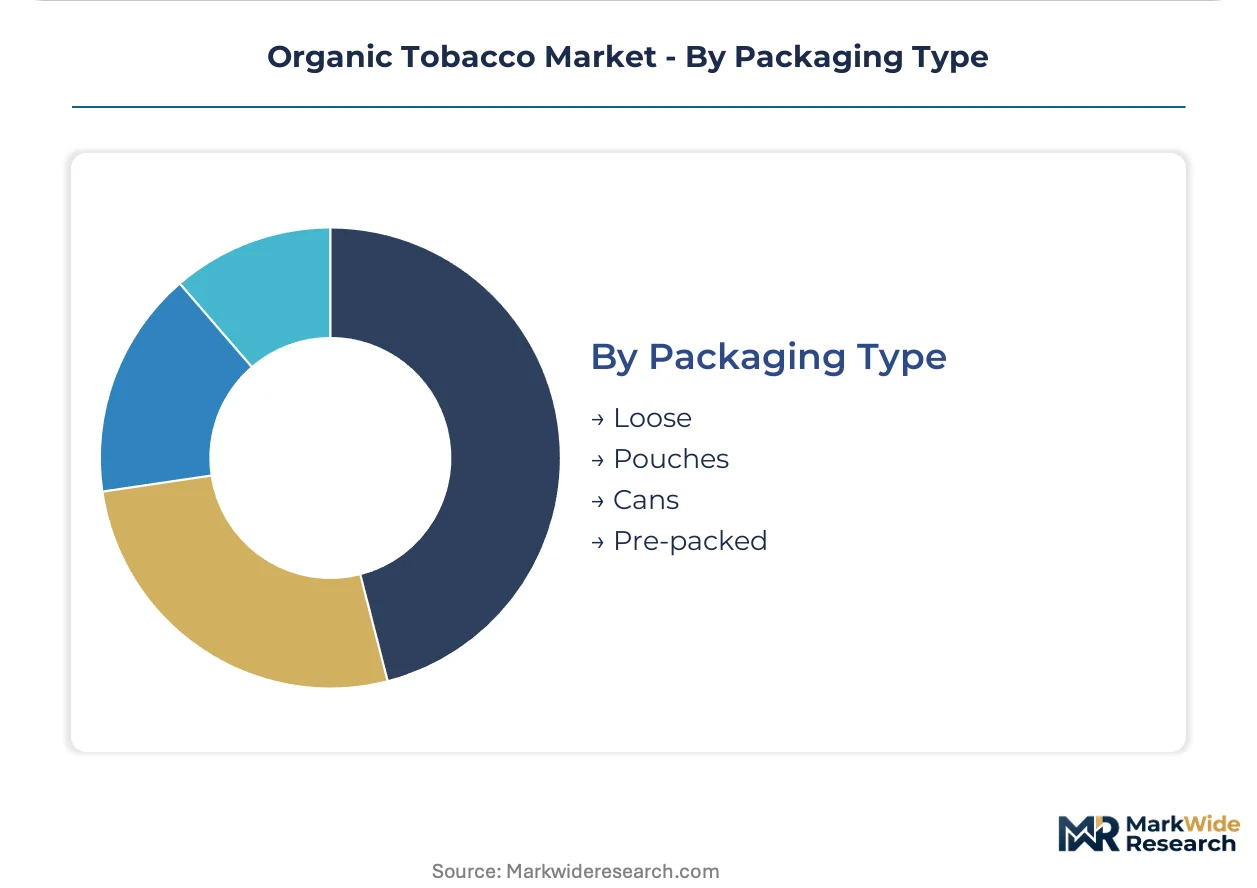
Organic tobacco segmentation reveals how certification premiums flow through divergent product formats and channel structures. Buyer priorities shift dramatically between personal consumers seeking traceability guarantees and B2B purchasers optimizing for compliance documentation.
Product Type:
Margin capture potential determines manufacturer portfolio allocation across combustible and smokeless formats.
- Roll-Your-Own:Raw leaf with minimal processing overhead commands the steepest purity premiums as consumers pay directly for perceived chemical-free cultivation. German specialty tobacconists and direct-to-consumer channels in Austria concentrate demand for certified organic loose leaf with seed-to-shelf traceability.
- Snuff:Smokeless format producers bypass increasingly restrictive public smoking bans in urban centers while capturing expanded margins through organic certification differentiation. Heat-not-burn cartridge manufacturers in regulatory-sensitive European markets source organic leaf to distinguish reduced-risk formulations.
- Cigarettes:Philip Morris International and Imperial Brands plc integrate certified organic supply chains into premium portfolio tiers where EU Tobacco Products Directive additive disclosure requirements amplify chemical-free positioning.
- Cigarillos:Small-format combustibles appeal to occasional smokers seeking occasion-based premium experiences without full cigarette commitment.
Roll-Your-Own leads on scale; Snuff leads on momentum.
End User:
Procurement sophistication separates direct consumers from intermediaries with divergent compliance documentation needs.
- Personal Use:Individual purchasers prioritize USDA Organic and EU Organic Regulation certification marks as shorthand for reduced exposure risk, despite equivalent tar and carbon monoxide yields upon combustion.
- Retailers:Specialty tobacconists in Germany build direct farmer partnerships through blockchain traceability platforms that bypass traditional leaf merchant intermediaries entirely.
- Wholesalers:Volume aggregators face compressing margins as manufacturer vertical integration into certified growing regions reduces intermediary value capture.
- Distributors:Cross-border logistics providers manage multi-jurisdictional residue testing complexity where Health Canada and FDA apply non-identical synthetic chemical detection thresholds.
Retailers capture the fastest value growth; Personal Use anchors absolute volume.
Sales Channel:
Channel fragmentation accelerates as traceability premiums reshape traditional wholesale hierarchies.
- Online:Direct-to-consumer platforms enable manufacturer bypass of wholesale markups while delivering seed-to-shelf verification documentation demanded by certification-conscious purchasers.
- Convenience Stores:High-velocity outlets stock limited organic SKUs given certification documentation requirements and inventory turnover constraints.
- Specialty Shops:Urban tobacconists in Germany and Austria command premium positioning through certified organic product exclusivity and farmer-direct procurement relationships.
- Supermarkets:Mass retail channels apply volume purchasing power to compress organic premiums toward commodity parity, squeezing supplier margins.
Specialty Shops concentrate margin extraction; Online climbs the fastest.
Packaging Type:
Packaging configuration signals processing intensity and corresponding certification verification burden.
- Loose:Minimal processing aligns with Roll-Your-Own consumer preferences for raw leaf perceived as closest to field-origin purity.
- Pouches:Pre-portioned formats reduce consumer handling while maintaining organic certification integrity through sealed packaging.
- Cans:Moist snuff containers preserve product freshness for smokeless format consumers in markets with restrictive public smoking regulations.
- Pre-packed:Finished cigarette packs face steepest EU Tobacco Products Directive additive disclosure obligations given direct consumer-facing labeling requirements.
Loose dominates absolute volume; Pouches gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium positioning for certified organic tobacco, while the United States cultivates specialty snuff and Roll-Your-Own demand through direct-to-consumer channels. Brazil anchors raw leaf supply chains for multinational manufacturers seeking additive-free cultivation verification.
Germany
Specialty tobacconists in Berlin and Hamburg drive demand for EU Organic Regulation-certified products with seed-to-shelf traceability. The country's national tobacco regulator enforces strict additive disclosure timelines under the EU Tobacco Products Directive. Bavarian retail cooperatives bypass traditional leaf merchants through blockchain-verified direct farmer partnerships.
United States
Roll-Your-Own consumers in urban markets pay steep premiums for USDA Organic-certified loose leaf perceived as chemical-free. The FDA applies non-identical residue testing thresholds compared to Health Canada, complicating cross-border supplier compliance. North Carolina processing facilities deploy spectral imaging to compress organic leaf qualification cycles.
Brazil
Flue-cured organic leaf production clusters in southern growing regions supplying Philip Morris International and Imperial Brands plc. The country's national agricultural regulator monitors pesticide residue thresholds for export eligibility to European and North American markets. Rio Grande do Sul farmer cooperatives face weather vulnerability and logistics constraints from single-region supply concentration.
India
Andhra Pradesh and Karnataka farmer conversion programs expand organic cultivation acreage under Tobacco Board of India incentives. The Central Drugs Standard Control Organization parallels USDA Organic standards for residual chemical testing protocols. Guntur district processing hubs integrate certified organic supply chains into premium cigarette formulations for export.
United Kingdom
Specialty retailers in London and Manchester stock certified organic snuff and cigarillos as urban smoking bans accelerate category rotation. The Medicines and Healthcare products Regulatory Agency aligns with EU Tobacco Products Directive disclosure requirements post-Brexit transition. Midlands distribution centers manage multi-jurisdictional compliance documentation for cross-channel shipments.
Organic Tobacco Market Competitive Environment
Top-tier vendors anchor multinational procurement networks, while regional specialists capture traceability premiums through direct farmer relationships. The vendor base stratifies across three tiers: integrated tobacco majors with certified organic portfolio tiers, mid-scale specialists in smokeless formats, and farmer-direct cooperatives supplying specialty channels. Archetypes include backward-integrated leaf processors, certification-focused niche brands, and blockchain-enabled traceability platforms. Dominant competitive moves encompass strategic partnerships with certified growing cooperatives and geographic expansion into Indian and Brazilian organic certification pipelines.
Within the integrated multinational tier, Philip Morris International exemplifies global procurement scale across multiple certified growing regions, while Imperial Brands plc occupies a position concentrated within European specialty channels where regulatory scrutiny runs highest. Mother Earth Tobacco represents the farmer-direct archetype through cooperative partnerships that guarantee field-to-shelf verification. Japan Tobacco Inc. and Swedish Match AB sit within the smokeless format specialization vector, capturing margin expansion as urban smoking restrictions accelerate category rotation.
| Leading Market Players |
|---|
| Japan Tobacco Inc. |
| Reynolds American Inc. |
| Swedish Match AB |
| Philip Morris International |
| Mother Earth Tobacco |
| Santa Fe Natural Tobacco Company |
| MAC BAREN |
| Imperial Brands plc |
| Leaf Only |
| Others |
Value Chain & Pricing Dynamics
Cigarette manufacturers seeking additive-free leaf concentrate procurement power around certified organic supply chains, compressing margins for intermediaries while amplifying premiums for verified chemical-free cultivation. This buyer-archetype concentration forces pricing stratification across certification tiers rather than conventional quality grades alone.
Pricing Analysis
Unbundled raw leaf for Roll-Your-Own formats commands steeper purity premiums than processed cigarette formulations where certification costs distribute across manufacturing overhead. Price differentiation rests on USDA Organic versus EU Organic Regulation tier thresholds and traceability documentation depth. Pricing pressure intensifies in supermarket channels where volume purchasing power erodes organic premiums toward commodity parity. Personal Use consumers exhibit lowest price sensitivity, paying traceability premiums through specialty tobacconist channels, while mass-market wholesalers face margin compression from manufacturer vertical integration.
Supply Chain Analysis
Freight costs from southern Brazilian growing regions to European processing facilities amplify landed costs for certified organic flue-cured leaf, creating geographic arbitrage opportunities for Indian Andhra Pradesh and Karnataka suppliers. Raw material inputs draw from pesticide-free seed stock, organic-approved fertilizers, and third-party certification audit services. Single-region concentration in Rio Grande do Sul cooperatives exposes supply chains to weather vulnerability and logistics disruption. Distribution runs through specialty tobacconist channels in Germany and Austria, bypassing traditional leaf merchant hierarchies through blockchain-verified direct farmer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic tobacco offers margin-expansion potential as synthetic pesticide elimination costs stabilize and EU Tobacco Products Directive disclosure requirements pull certified leaf into premium cigarette formulations. The shift from commodity-grade to certified organic sourcing reduces price competition on conventional quality metrics.
For Market Incumbents: Anchor defensive positioning through backward integration into Indian Andhra Pradesh and Karnataka farmer conversion programs before Tobacco Board of India incentives attract competing procurement networks. Secure exclusive blockchain traceability partnerships with Rio Grande do Sul cooperatives to preempt supply concentration risk. Invest in spectral imaging capabilities at processing facilities to compress supplier qualification cycles and widen capability gaps against commodity traders.
For New Entrants and Emerging Players: Urban specialty tobacconists in German and Austrian cities represent the most penetrable buyer archetype, underserved by existing leaf merchant relationships and willing to pay seed-to-shelf verification premiums. Heat-not-burn cartridge manufacturers in regulatory-sensitive European markets offer white-space demand for organic leaf differentiation. Pursue direct-to-consumer online platforms with USDA Organic certification documentation to bypass wholesale markup structures entirely.
For Investors and Strategic Acquirers: Integrated tobacco majors with certified organic portfolio tiers are the most active acquirer in this space, seeking farmer-direct cooperatives with blockchain-enabled traceability platforms. Long-term viability hinges on multi-jurisdictional residue testing compliance infrastructure spanning FDA, Health Canada, and EU thresholds. Watch for pesticide residue threshold tightening in major consuming countries as the inflection signal for sourcing economics disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Growing Regions | Philip Morris International secures organic flue-cured supply chains across Brazilian and Indian cultivation zones. |
| Blockchain Traceability Platform Deployment | Mother Earth Tobacco enables seed-to-shelf verification that bypasses traditional leaf merchant intermediaries entirely. |
| EU Organic Regulation Certification Investment | Imperial Brands plc substantiates chemical-free claims for premium portfolio tiers in disclosure-intensive European markets. |
| Heat-not-Burn Cartridge Formulation Differentiation | Reduced-risk product manufacturers source organic leaf to distinguish offerings in urban smoking ban environments. |
| Specialty Tobacconist Channel Exclusivity | German retailers command premium positioning through certified organic product exclusivity and farmer-direct procurement. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with certified organic tobacco growers, leaf processing facility managers, specialty tobacconist buyers, EU regulatory affairs specialists, and multinational cigarette manufacturer procurement directors with secondary validation from USDA Organic certification databases, EU Tobacco Products Directive disclosure filings, Tobacco Board of India incentive program documentation, and customs trade data on organic leaf shipments. Bottom-up farmer conversion program tracking and top-down manufacturer procurement spend analysis were triangulated against third-party certification audit volumes.
Segment-weighting approaches modeled organic tobacco demand across product type dimensions including Roll-Your-Own, snuff, cigarettes, and cigarillos; end user categories spanning personal use, retailers, wholesalers, and distributors; and sales channel structures covering online, convenience stores, specialty shops, and supermarkets. CAGRs were derived from certification pipeline expansion rates and premium pricing persistence in German and Austrian markets. Forecast inputs incorporated EU Tobacco Products Directive timeline compression effects and Indian farmer incentive program uptake curves.
Inputs from USDA Organic and EU Organic Regulation certification bodies were available through the study window; gaps in real-time farmer conversion cost data introduce uncertainty bands around yield recovery assumptions following three-year field transition periods. Forecasts reflect documented assumptions on pesticide residue threshold stability and specialty channel premium persistence. A model refresh is warranted upon material change in EU Tobacco Products Directive enforcement intensity or Brazilian weather disruption frequency affecting southern growing region output.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Tobacco Films Market
Tobacco
Heat-Not-Burn Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
North America Cigarette Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
US Tobacco Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Cigarette Paper Market
Tobacco
Middle East and Africa Smokeless Tobacco Market
Tobacco
Egypt Tobacco Market
Tobacco
North America Tobacco Market