
 Low Tar Cigarette Paper Market | 2026-2036
Low Tar Cigarette Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Low Tar Cigarette Paper Market Insights
Ultra-thin specification-grade paper is unwinding legacy medium-thickness supply chains across the low tar cigarette paper category. Schweitzer-Mauduit International leverages its backward integration into flax fiber sourcing to secure batch consistency for European OEMs. Delfort Group anchors Central European demand through specialized coating lines that control porosity within tight tolerances. Republic Technologies International competes on roll-format customization for private-label distributors seeking differentiated burn rates.
Low tar cigarette paper denotes porous, low-substance wrapping material engineered to reduce smoke condensate delivery while maintaining structural integrity during combustion; manufacturers typically target air permeability between 20 and 80 CORESTA units and basis weights below 25 grams per square meter to achieve these functional parameters. Flax-based material dominates premium positioning owing to its natural strength and clean burn profile, while wood pulp occupies cost-sensitive volume tiers where opacity and printability matter more than porosity precision. The thickness dimension stratifies sharply: ultra-thin grades command margin pools in Japan and South Korea where machine-rolled product specifications are most demanding, whereas medium thickness sustains broader retail booklets across European convenience channels.
The EU Tobacco Products Directive and REACH frameworks constrain additive use and mandate emissions disclosures, compelling mills to validate paper chemistry through ECHA-registered testing protocols. The US FDA exercises parallel authority through premarket tobacco product application requirements that classify modified-risk paper as a separate review pathway. China's SAMR enforces GB standards on tar labeling that indirectly pressure domestic paper suppliers to certify porosity claims. Stakeholders must monitor how regulatory divergence between Brussels and Beijing reshapes specification harmonization costs for multinational supply contracts.
Market Dynamics
Ultra-thin specification-grade paper is unwinding legacy medium-thickness supply chains as health-conscious smokers in Germany and machine-rolled product manufacturers in East Asia demand tighter porosity tolerances and reduced basis weights below 25 grams per square meter.
Growth Catalysts
- EU Tobacco Products Directive:Tightening tar and emissions thresholds in Brussels compel OEMs to source filter-compatible papers with validated air permeability between 20 and 80 CORESTA units.
- China domestic upgrading:SAMR-enforced GB standards on tar labeling pressure local manufacturers to certify porous paper specifications for reduced-delivery products.
- Flax fiber backward integration:Mills securing captive flax supply achieve batch consistency that satisfies European premium positioning requirements.
Market Restraints
- Flax input cost volatility:Weather-driven harvest fluctuations in Baltic and French growing regions destabilize raw material pricing for premium-grade production.
- Supply concentration in China:Domestic paper mills control volume-tier wood pulp capacity, creating dependency risks for multinational distributors seeking cost-sensitive sourcing alternatives.
- REACH additive constraints:ECHA-registered testing protocols limit coating chemistry options, extending validation timelines for new porosity-control formulations.
Strategic Opportunities
- Japan ultra-thin penetration:Machine-rolled product specifications in Tokyo and Osaka markets remain underserved by European mills with coating line flexibility.
- South Korea filter convergence:Heat-not-burn device manufacturers seek paper substrates compatible with reduced-risk delivery platforms.
- US FDA modified-risk pathway:Premarket tobacco product applications create a separate review track for papers positioned as reduced-exposure components.
Industry Challenges
- Porosity certification timelines:ECHA-registered laboratories face backlog pressures, delaying OEM qualification cycles for new ultra-thin grades.
- Coating line reconfiguration:Mills must retool specialized equipment to achieve tight air permeability tolerances without sacrificing throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Tar Cigarette Paper Market |
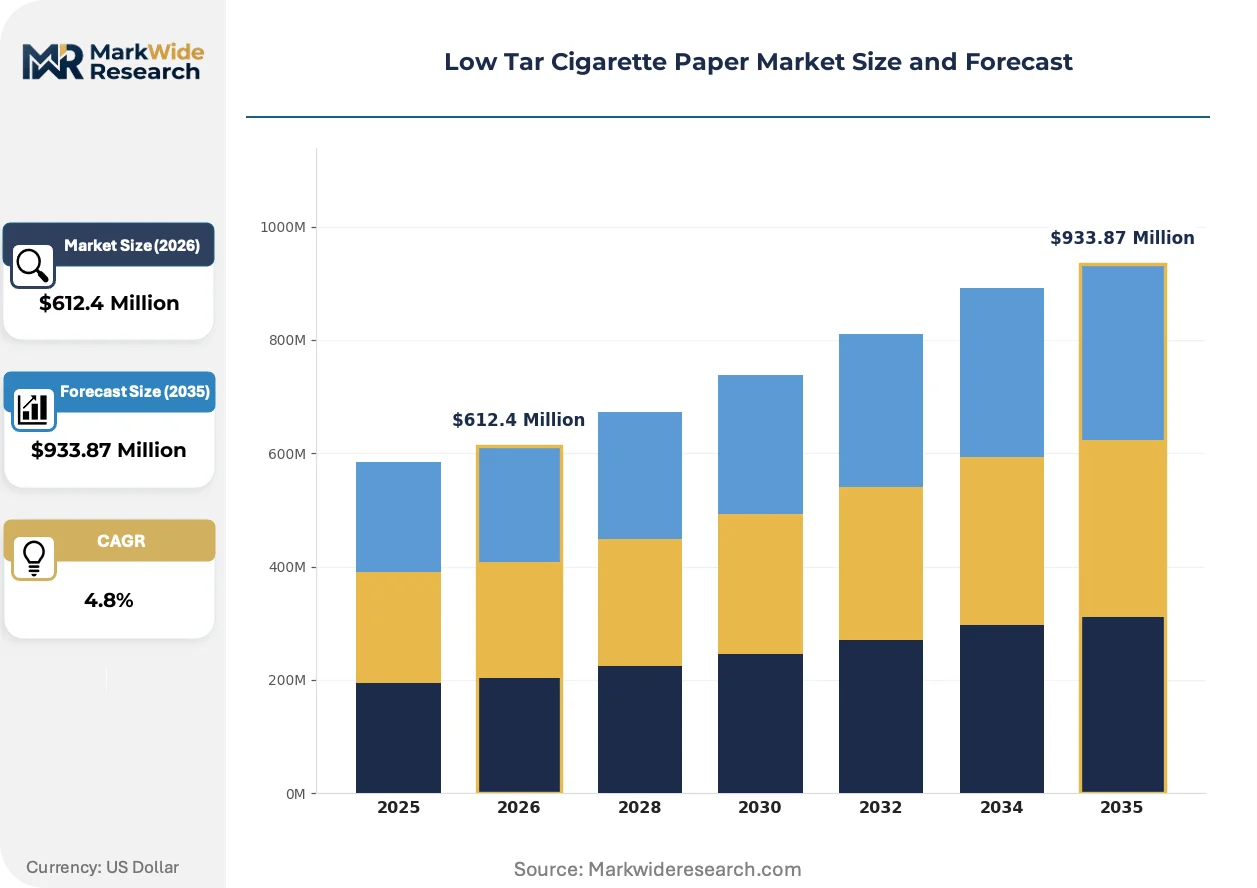
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $933.87 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Sheet, Booklets, Rolls, Pre-Rolled Material: Flax, Hemp, Rice, Wood Pulp Thickness: Thin, Medium, Thick, Ultra-Thin Market Channel: Online Retail, Convenience Stores, Tobacco Shops, Supermarkets |
| Companies Covered | Delfort Group, Republic Technologies International, Schweitzer-Mauduit International, Miquel y Costas, Glatz Feinpapiere, Hangzhou Huafeng Paper, Mudanjiang Hengfeng Paper, The Rolling Paper Company, BMJ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Tar Cigarette Paper Market Trends and Innovations
Specification-grade paper evolution is compressing legacy supply relationships as technical requirements fragment across health-driven regulatory jurisdictions and precision-manufacturing end-uses.
Ultra-thin grades below 20 grams per square meter are displacing medium-thickness inventory across Japanese and South Korean machine-rolled channels. Premium OEMs in Osaka and Seoul specify sub-25 GSM basis weights for reduced condensate delivery without structural failure. This displacement is compressing margin pools for European mills lacking coating line precision.
REACH and EU Tobacco Products Directive convergence is tightening additive disclosure and emissions validation requirements. ECHA-registered testing protocols now govern paper chemistry certification for filter-compatible products. German and French OEMs are responding by locking multi-year supply contracts with mills possessing validated laboratory partnerships.
Specification-driven procurement is fragmenting traditional volume-based supplier relationships. Private-label distributors now demand roll-format customization with differentiated burn rates rather than standard catalog offerings. This behavioral shift is most visible in Central European convenience channels where Delfort Group and Republic Technologies International compete on format flexibility.
Low Tar Cigarette Paper Market Segmentation
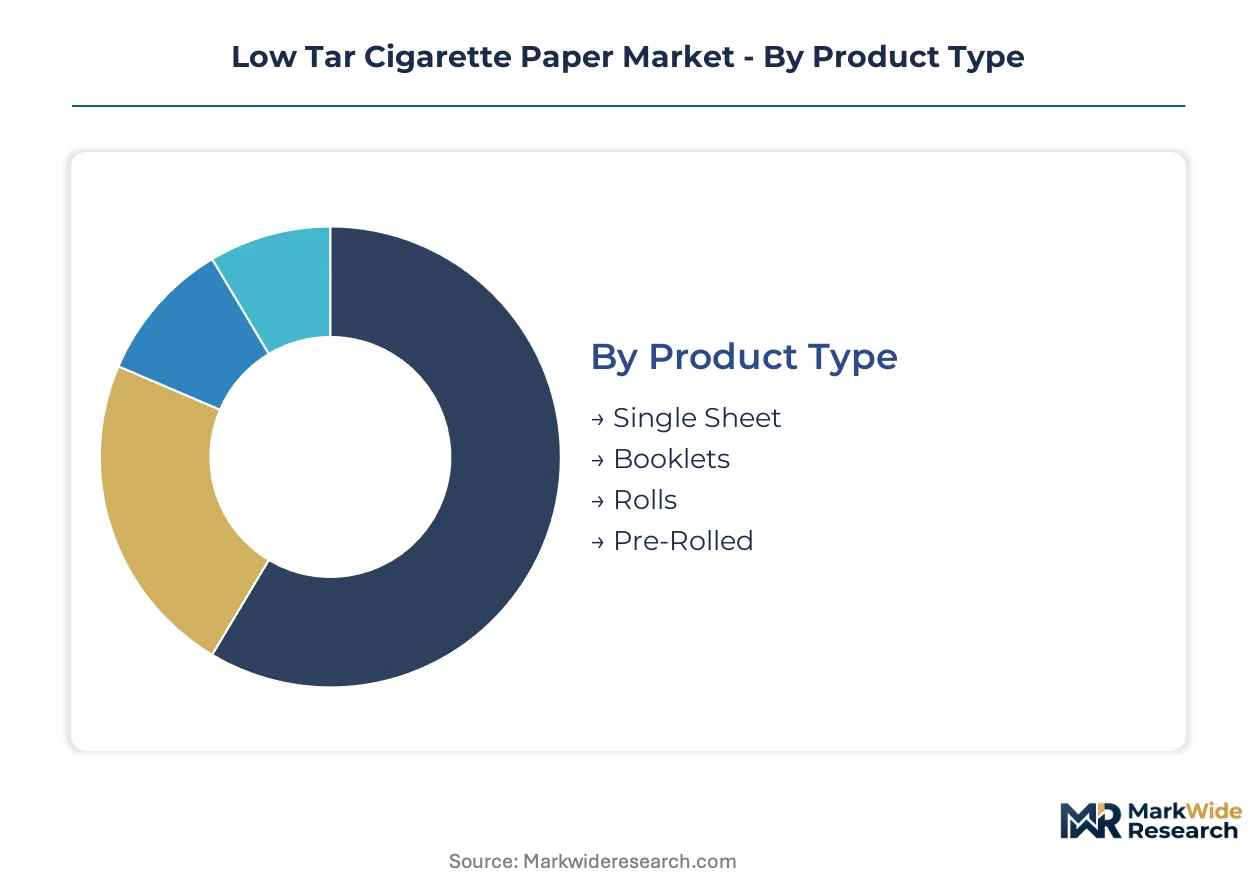
Low tar cigarette paper segmentation reflects divergent technical requirements across machine-rolled manufacturing and hand-rolled retail channels. Specification-grade thickness tiers and material sourcing strategies separate premium OEM supply contracts from cost-driven private-label procurement.
Product Type:
Roll formats face the strongest substitution pressure as machine-rolled manufacturers in East Asia shift toward pre-rolled specifications that eliminate handling inconsistency.
- Rolls:Continuous-format paper wound on spools serves high-speed manufacturing lines in Osaka and Seoul. Demand concentrates among OEMs seeking batch-to-batch porosity consistency for filter-tipped products.
- Pre-Rolled:Factory-formed tubes eliminate consumer rolling variation and command premium positioning in Japanese convenience channels. Heat-not-burn device manufacturers in Tokyo are evaluating these substrates for reduced-risk platform compatibility.
- Booklets:Folded-sheet formats dominate European retail distribution where private-label distributors specify differentiated burn rates through roll-format customization.
- Single Sheet:Individual leaves serve specialty tobacco shops in Germany catering to hand-rolling enthusiasts who prioritize tactile control over production efficiency.
Rolls retain volume leadership; Pre-Rolled holds the steepest expansion curve.
Material:
Cost tier stratification separates captive-flax premium supply from commoditized wood pulp volume production.
- Flax:Natural fiber delivers superior tensile strength and clean combustion profiles. Mills with backward integration into Baltic and French growing regions secure batch consistency for European OEM qualification cycles.
- Wood Pulp:Bleached kraft occupies opacity-sensitive tiers where printability outweighs porosity precision. Chinese domestic mills control this capacity, creating sourcing dependency risks for multinational distributors.
- Hemp:Alternative cellulose source attracts sustainability-positioned brands navigating REACH additive constraints through reduced chemical processing.
- Rice:Ultra-thin sheet formation enables sub-20 GSM specifications demanded by South Korean machine-rolled channels where structural integrity at minimal basis weight is non-negotiable.
Wood Pulp dominates unit economics; Flax commands margin expansion.
Thickness:
Application-specific requirements fragment supply relationships as precision-manufacturing end-uses diverge from retail booklet standards.
- Ultra-Thin:Sub-20 GSM grades achieve reduced condensate delivery without combustion failure. Japanese OEMs in Tokyo and Osaka specify these for machine-rolled products where tolerance tightness determines supplier qualification.
- Thin:20-25 GSM range balances porosity control with structural reliability. German health-conscious smokers drive filter-compatible paper adoption in this specification band.
- Medium:Legacy thickness sustains broader European convenience channel distribution where coating line reconfiguration investments lag specification evolution.
- Thick:Higher basis weights serve opacity-critical applications in markets where printability and handling durability outweigh emissions reduction priorities.
Medium thickness retains installed base; Ultra-Thin is climbing the fastest.
Market Channel:
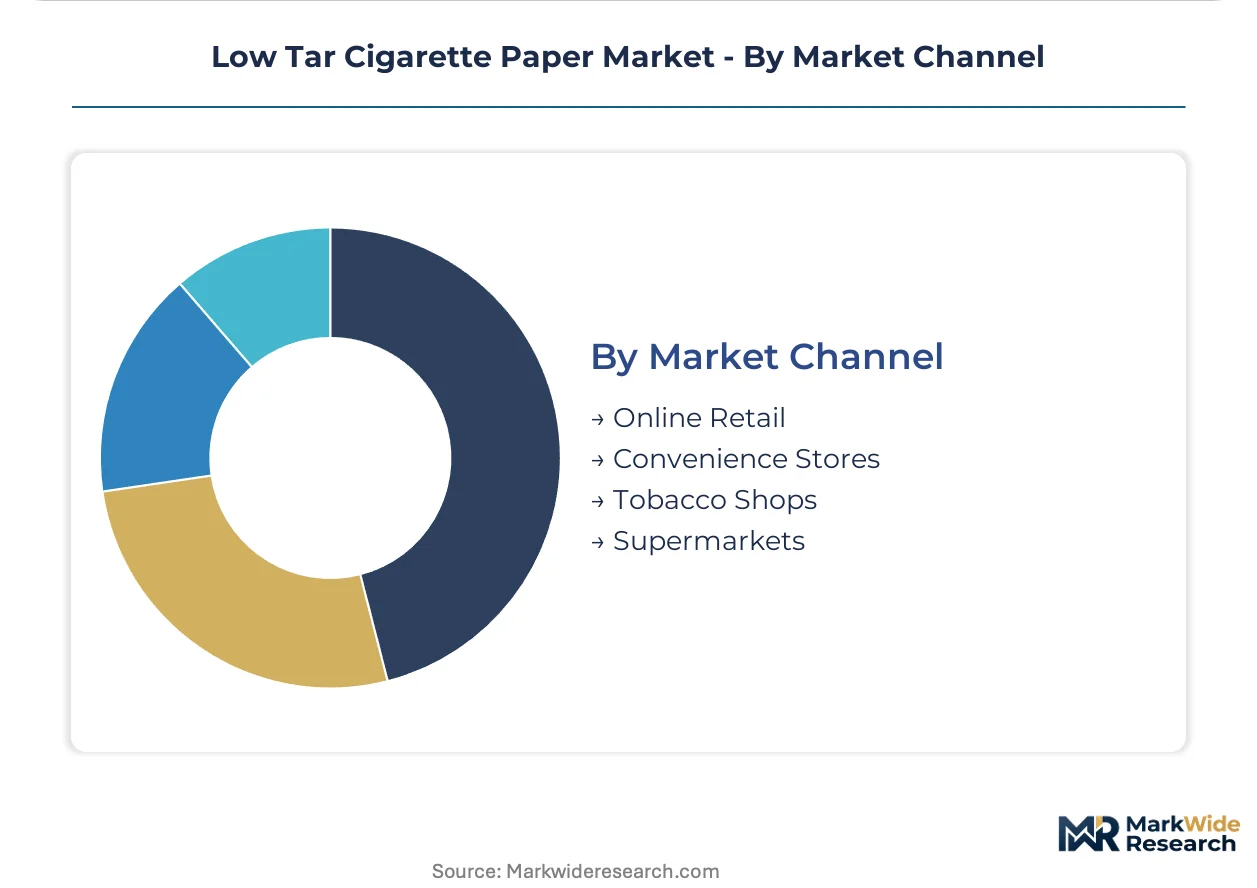
Customer type differentiation separates specification-driven OEM procurement from price-sensitive retail replenishment.
- Convenience Stores:High-frequency replenishment channels in Germany and France stock standardized booklets. Delfort Group anchors this tier through specialized coating lines with tight porosity tolerances.
- Tobacco Shops:Specialist retailers command format flexibility and differentiated burn rate specifications. Republic Technologies International competes here on roll-format customization for private-label distributors.
- Online Retail:Direct-to-consumer platforms aggregate niche demand for hemp and rice variants underserved by mass-market distribution.
- Supermarkets:Volume-tier consolidation favors wood pulp-based products with economies of scale and simplified supply chain requirements.
Convenience Stores maintain transaction density; Tobacco Shops deliver margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese mills export porous paper specifications to European OEMs upgrading filter-compatible product lines, while Japanese and South Korean manufacturers import ultra-thin grades for machine-rolled channels.
China
Domestic manufacturers upgrade porous paper specifications for reduced-delivery products under SAMR-enforced GB standards on tar labeling. The Yangtze River Delta cluster concentrates wood pulp capacity that supplies volume-tier production for multinational distributors seeking cost-sensitive sourcing alternatives.
Germany
Health-conscious smokers drive premium filter-compatible paper adoption as the EU Tobacco Products Directive tightens emissions thresholds. ECHA-registered testing protocols govern paper chemistry validation, compelling mills near Hamburg and Munich to secure multi-year laboratory partnerships.
Japan
Machine-rolled product specifications in Tokyo and Osaka demand sub-20 GSM ultra-thin grades with tolerance tightness that determines supplier qualification. METI industrial standards pressure OEMs to certify batch-to-batch porosity consistency for filter-tipped products.
South Korea
Heat-not-burn device manufacturers in Seoul evaluate paper substrates for reduced-risk delivery platform compatibility. MFDS regulatory frameworks constrain additive use, directing procurement toward mills with validated coating chemistry for tight air permeability control.
United States
FDA premarket tobacco product applications create a separate review pathway for papers positioned as reduced-exposure components. Domestic distributors seek roll-format customization with differentiated burn rates for private-label positioning in convenience channels.
Low Tar Cigarette Paper Market Competitive Landscape
Listed leaders compete with private specialists across specification-grade thickness tiers and material sourcing strategies. The supplier base fragments between flax-based premium positioning and wood pulp volume production, with backward integration into fiber supply emerging as a critical differentiator. Three archetypes dominate: integrated fiber-to-paper mills, coating-line specialists, and format-flexible converters. Competitive moves concentrate on laboratory partnership lock-ins and coating line reconfiguration for ultra-thin tolerance achievement.
Within the European premium tier, Schweitzer-Mauduit International exemplifies integrated supply chain positioning, while Delfort Group occupies a specialist role in Central European coating precision. Republic Technologies International represents format-flexible conversion capabilities for distributor customization requirements.
| Leading Market Players |
|---|
| Delfort Group |
| Republic Technologies International |
| Schweitzer-Mauduit International |
| Miquel y Costas |
| Glatz Feinpapiere |
| Hangzhou Huafeng Paper |
| Mudanjiang Hengfeng Paper |
| The Rolling Paper Company |
| BMJ |
| Others |
Pricing and Supply Chain Analysis
Multi-year offtake agreements with European OEMs lock in flax fiber supply access and insulate mills from Baltic harvest volatility while anchoring price visibility across the ultra-thin specification tier. These contracts concentrate procurement power among mills with backward integration into French and Estonian growing regions, compressing margin pools for spot-market dependent converters.
Pricing Analysis
Thickness-generation pricing gaps separate sub-20 GSM ultra-thin premiums from legacy medium-thickness commoditization. Three-tier pricing structure across premium flax-based, standard wood pulp, and economy uncoated tiers differentiates on certification grade and porosity precision. Pricing pressure stems from Chinese wood pulp oversupply eroding European volume-tier margins. Private-label distributors exhibit highest price sensitivity; Japanese OEMs prioritize tolerance consistency over unit cost.
Supply Chain Analysis
Container availability constraints on Baltic-to-Rotterdam lanes elevate inbound logistics costs for flax fiber shipments during Q3 harvest windows. Supply concentrates in China for wood pulp, France and Belgium for flax cultivation, and Germany for coating line finishing. Raw material dependencies span Baltic flax straw, Scandinavian bleached kraft, and specialty coating chemicals. Single-source vulnerability runs through Chinese pulp capacity concentration. Distribution runs through European converter hubs serving OEM direct contracts and Asian trading houses for spot volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-thin specification migration constitutes a high-growth disruption as REACH additive constraints and FDA modified-risk pathways simultaneously elevate technical barriers and reward certified positioning.
For Market Incumbents: Compound laboratory partnership lock-ins with ECHA-registered facilities to extend qualification cycle advantages against emerging Asian competitors. Deepen captive flax supply through long-term Baltic growing contracts that neutralize harvest volatility threatening batch consistency. Defend against Chinese wood pulp incursion by emphasizing REACH-compliant chemistry validation that SAMR-enforced GB standards increasingly reference. For New Entrants and Emerging Players: Differentiate on coating line flexibility for sub-20 GSM tolerance achievement in Japanese machine-rolled channels where European mills lag reconfiguration speed. Target South Korean heat-not-burn device manufacturers seeking paper substrate compatibility with reduced-risk delivery platforms. Pursue private-label distributor relationships in Central European tobacco shops demanding roll-format customization with differentiated burn rates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated fiber-to-paper mills with captive flax supply and multi-year OEM offtake structures. Five-to-ten year viability favors backward-integrated specialists over format-flexible converters exposed to wood pulp commoditization. Monitor ECHA laboratory backlog resolution as inflection signal for qualification cycle compression and supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flax Fiber | Captive Baltic and French supply secures batch consistency for REACH-compliant European OEM contracts. |
| Coating Line Reconfiguration for Ultra-Thin | Sub-20 GSM tolerance achievement unlocks Japanese machine-rolled specifications currently underserved by European mills. |
| ECHA Laboratory Partnership Lock-in | Validated testing protocols compress OEM qualification cycles and create switching costs against unregistered competitors. |
| Heat-not-Burn Substrate Development | MFDS-constrained additive chemistry positions paper suppliers for Seoul-based reduced-risk platform integration. |
| Private-Label Format Customization | Roll-format flexibility with differentiated burn rates captures margin in Central European tobacco shop channels. |
Research Methodology
The analysis maps ultra-thin, thin, medium, and thick specification tiers, each validated through coating line engineers, OEM procurement managers, ECHA laboratory directors, and flax fiber agronomists. Primary interviews with paper mill technical directors and secondary validation through REACH registration databases, SAMR GB standard filings, and FDA premarket tobacco product application dockets anchored supply-side characterization. Customs trade data on flax fiber imports and cigarette paper exports provided demand-side cross-checks. Bottom-up segment sizing and top-down market reconciliation ensured consistency.
Consistency checks against external benchmarks validated projection outputs across the modeling period. Segmentation dimensions modeled include thickness tier, material composition, product format, and regional regulatory cluster. CAGRs derived from weighted average growth contributions across specification-grade adoption curves. Industry-specific inputs incorporated ECHA laboratory capacity expansion timelines and SAMR enforcement intensity on tar labeling compliance.
The analysis sits within stated boundaries; outcomes outside sustained REACH additive constraint tightening and FDA modified-risk pathway activation would require recalibration. Forecasts reflect assumptions on flax harvest stability and Chinese pulp capacity discipline. Regulatory divergence between Brussels and Beijing on emissions disclosure protocols poses revision risk to multinational supply contract harmonization models. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
North America Tobacco Market
Tobacco
Heat-Not-Burn Market
Tobacco
US Tobacco Market
Tobacco
Tobacco Films Market
Tobacco
Cigarette Paper Market
Tobacco
North America Cigarette Market
Tobacco
Egypt Tobacco Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
Organic Tobacco Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
Middle East and Africa Smokeless Tobacco Market