
 Cigarette Rolling Paper Market | 2026-2036
Cigarette Rolling Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Cigarette Rolling Paper Market Analysis
Premium ultra-thin specifications is reorganizing the Cigarette Rolling Paper Market as consumers migrate from standard-weight papers toward lower-basis-weight grades. Schweitzer-Mauduit International sustains vertical integration from wood pulp refining to finished reel conversion across its North American and European mills. Miquel y Costas & Miquel anchors European supply through its Barcelona-area manufacturing complex, while Republic Technologies International competes on flavor-infused and specialty-size variants.
Cigarette rolling paper denotes a thin, combustible sheet engineered from wood pulp, hemp, flax, or rice fibers with typical basis weights of 12–25 grams per square meter, designed to encase loose tobacco for hand-rolled or machine-rolled consumption. The manufacturing process employs Fourdrinier or cylinder machines with precise calendering to achieve uniform porosity for controlled burn rates. Hemp-based papers command widening share in Western European markets as consumers prioritize fiber provenance and reduced chemical processing. King Size formats lead volume in North American convenience channels, while Super Slim variants attract younger demographics in urban centers. Unflavored papers retain dominant share, though mint and berry flavor segments generate disproportionate margin contributions in specialty retail.
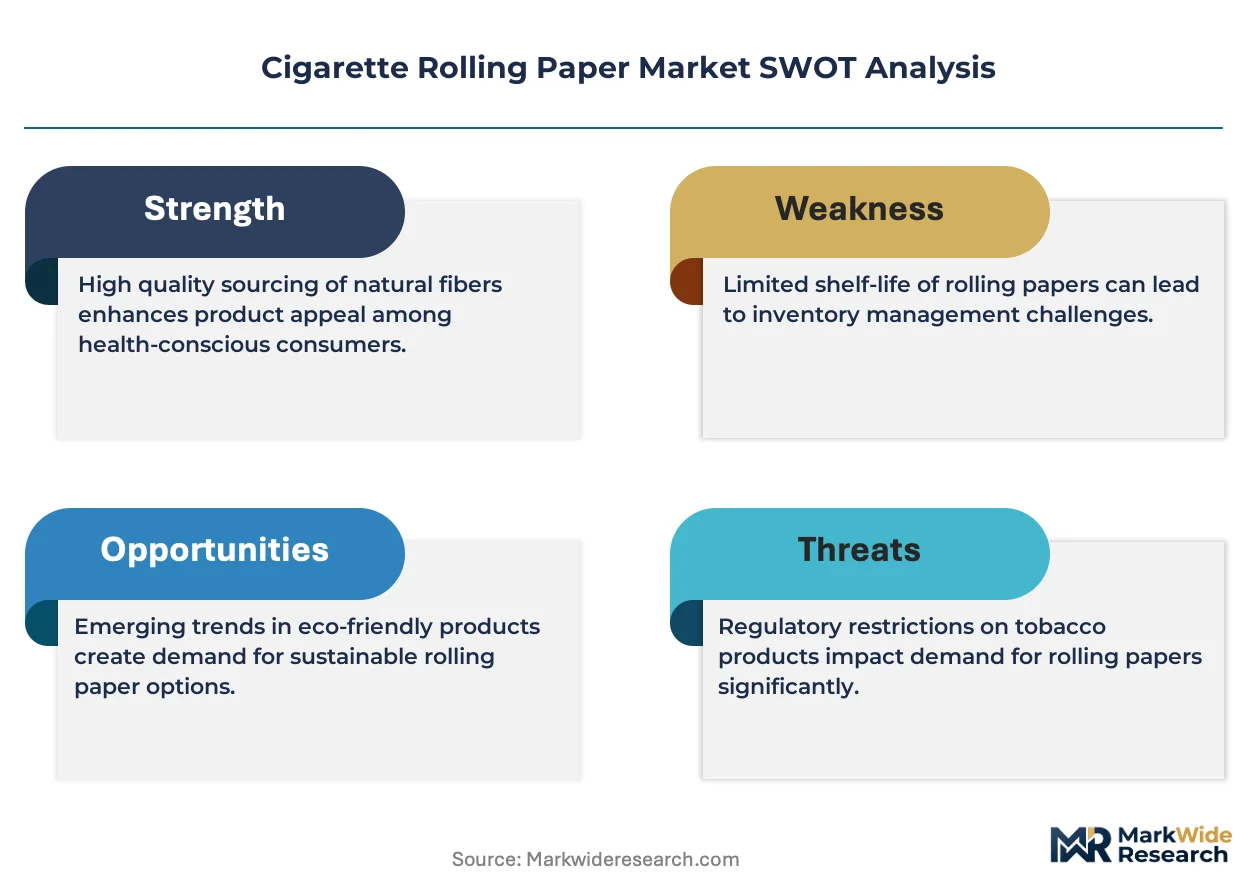
FDA oversight of tobacco product components in the United States requires rolling paper manufacturers to comply with ingredient listing and modified risk tobacco product pathways. The EU Tobacco Products Directive mandates emissions testing and additive transparency, while REACH governs chemical substance registration for coatings and flavor carriers. Stakeholders must monitor evolving cellulose sourcing regulations and anticipate how emerging sustainability disclosure rules reshape supplier qualification criteria.
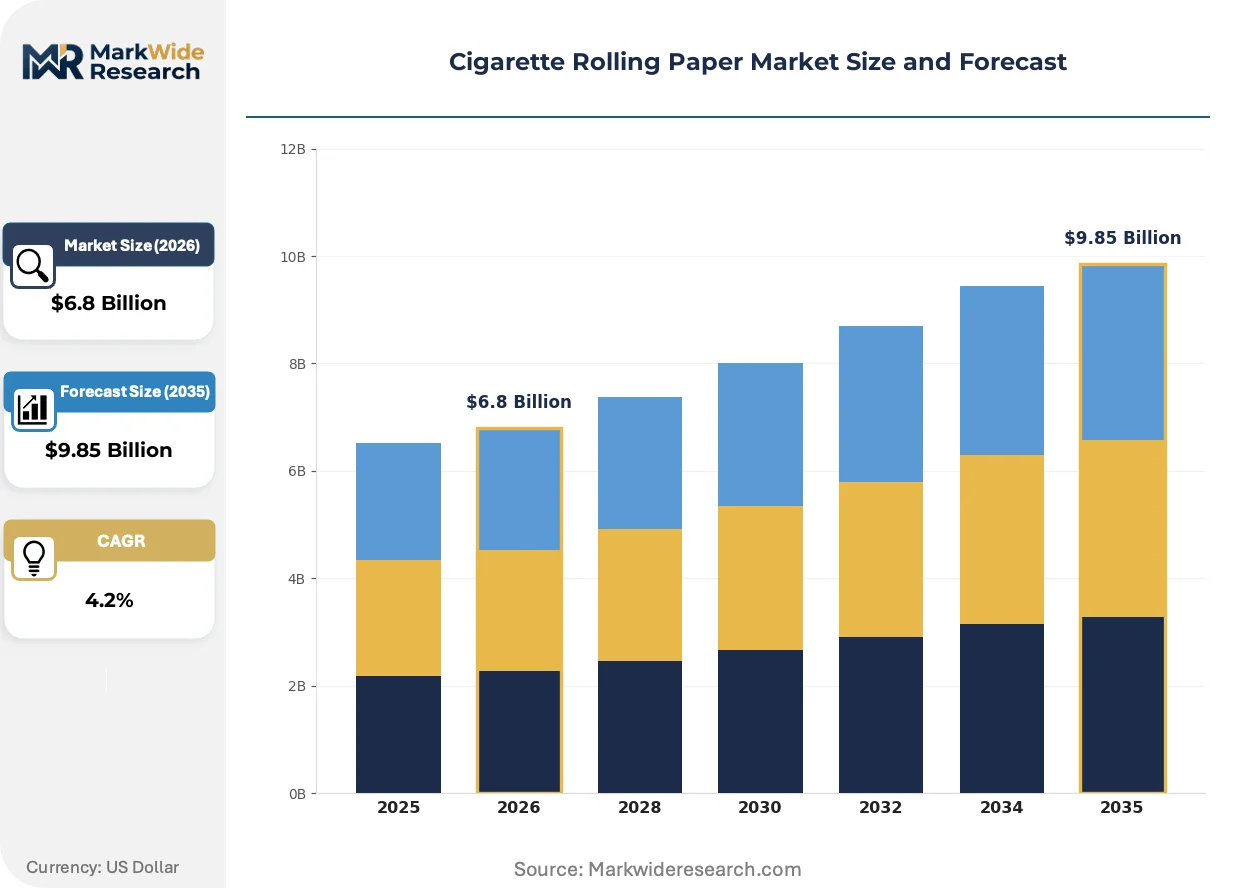
Market Dynamics
The EU Tobacco Products Directive is compressing formulation flexibility across the Cigarette Rolling Paper Market as manufacturers absorb additive disclosure mandates and emissions testing protocols into their product development cycles.
Growth Catalysts
- Hemp-fiber provenance preference:Consumers in France, Spain, and the Netherlands are prioritizing reduced chemical processing in their rolling paper selections. This fiber-sourcing shift is pulling capacity toward European hemp cultivation zones.
- REACH chemical transparency:The European regulation governing coatings and flavor carriers is standardizing supplier qualification criteria. Manufacturers complying early are securing preferred supplier status with boutique smoke shop chains.
- Private-label expansion:Artisanal tobacco retailers across Western Europe are developing captive rolling paper lines. This channel evolution is creating dedicated demand streams outside conventional branded distribution.
Market Restraints
- Wood pulp input volatility:Energy-intensive refining processes face margin pressure from Nordic pulp pricing swings. Basis weight standardization limits pass-through flexibility to downstream buyers.
- EU regulatory friction:The Tobacco Products Directive's tightening additive disclosure requirements are extending product development timelines. Reformulation costs concentrate disproportionately on smaller specialty manufacturers.
- Pre-rolled cone substitution:Machine-manufactured pre-rolled cones are capturing convenience-oriented consumers in North American urban centers. Hand-rolling ritual persistence varies sharply by demographic cohort.
Strategic Opportunities
- Carbon disclosure alignment:The EU Green Deal's emerging sustainability reporting frameworks will favor early cellulose sourcing certifiers. Mills with chain-of-custody documentation are positioning for procurement preference.
- Specialty retail channel innovation:Direct-to-consumer subscription models for premium rolling paper assortments remain underdeveloped. Urban smoke shop cooperatives in Barcelona and Amsterdam are piloting curated delivery services.
- Flavor carrier technology convergence:Micro-encapsulation techniques from food processing are migrating into berry and mint segment production. This cross-industry transfer enables cleaner burn profiles without additive disclosure triggers.
Industry Challenges
- Emissions testing talent scarcity:Laboratory capacity for EU-mandated burn emission analysis is concentrating in Germany and the Netherlands. Smaller manufacturers face six-month queue times for certification completion.
- Fourdrinier machine reconfiguration:Calendering precision upgrades for ultra-thin basis weights require capital outlays that strain mid-tier producers. Legacy cylinder machine operators confront technical obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cigarette Rolling Paper Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood Pulp, Hemp, Rice, Flax Size: Single Wide, Double Wide, King Size, Super Slim Flavor: Unflavored, Mint, Berry, Chocolate Brand: Dutch Masters, RAW, OCB, Zig-Zag |
| Companies Covered | HBI International, Miquel y Costas & Miquel, Schweitzer-Mauduit International (SWM), Nippon Paper Papylia, Hengfeng Paper, Republic Technologies International, Glatz Feinpapiere, ITC Limited, Delfort Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cigarette Rolling Paper Market Emerging Trajectories
Ultra-thin specification migration is fragmenting manufacturing investment priorities as producers split capacity between premium low-basis-weight grades and conventional product lines serving price-sensitive channels.
Hemp-fiber processing technology is bifurcating the raw material procurement landscape. Mechanical decortication methods preserve fiber length for premium European markets, while chemical retting serves cost-optimized Asian supply chains. Specialty retailers in France and the Netherlands are absorbing mechanical-process premiums at three-to-one volume ratios versus standard grades.
REACH chemical substance registration is compressing flavor carrier innovation cycles. ECHA's expanding candidate list for substances of very high concern is forcing reformulation of mint and berry segment coatings. Manufacturers with in-house toxicology assessment capabilities are accelerating product launches while competitors await third-party laboratory clearances.
Urban convenience channel concentration is rotating demand toward king-size format standardization. Younger demographics in metropolitan centers are consolidating purchases through smoke shop loyalty programs and subscription services. This channel consolidation is marginalizing traditional tobacconist distribution in Barcelona, Madrid, and Amsterdam retail corridors.
Cigarette Rolling Paper Market Segmentation
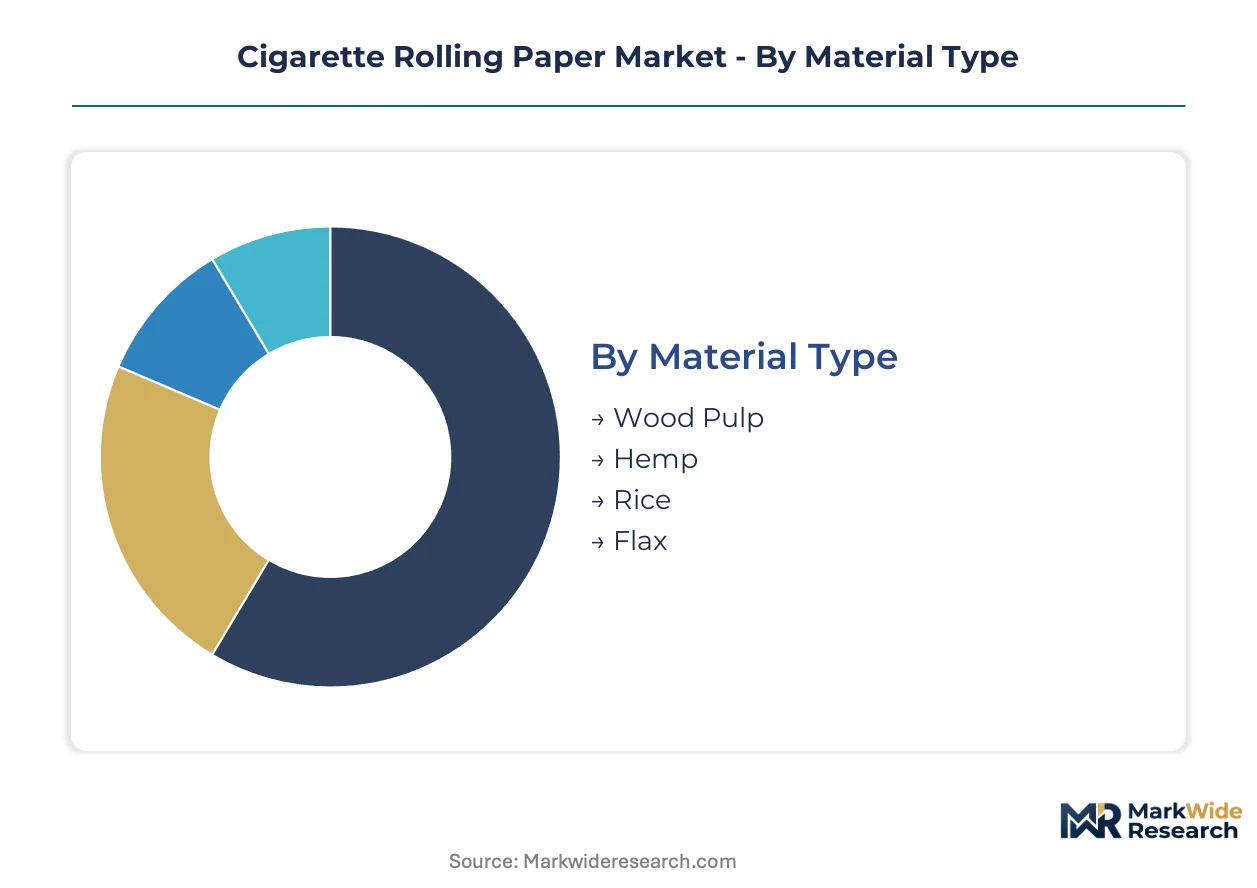
Cigarette rolling paper segmentation reveals how regulatory pressure and fiber sourcing transparency reshape procurement patterns across distinct material grades and format specifications. Manufacturers calibrate capacity allocation between REACH-compliant premium lines and standard-weight production serving price-sensitive channels.
Material Type:
REACH chemical substance registration and EU Tobacco Products Directive emissions testing create divergent compliance burdens across fiber categories, with hemp and flax processors absorbing disproportionate certification costs.
- Hemp:Mechanical decortication preserves long fiber strands for ultra-thin specifications favored in France, Spain, and the Netherlands. Boutique smoke shops in Amsterdam and Barcelona absorb three-to-one volume premiums over chemically retted alternatives.
- Wood Pulp:Fourdrinier machine production dominates volume throughput, though Nordic pulp pricing volatility compresses margins on standard-weight grades. Energy-intensive refining faces mounting pressure from EU Green Deal carbon disclosure frameworks.
- Rice:Asian supply chains serve cost-optimized markets with shorter burn profiles. REACH registration gaps limit European distribution penetration.
- Flax:Belgian and French cultivation zones supply premium European markets with established chain-of-custody documentation. Linen fiber variants command specialty retail placement.
Wood pulp handles the majority of throughput; hemp is the fastest mover on share.
Size:
Urban convenience channel consolidation rotates demand toward format standardization, with metropolitan smoke shop loyalty programs driving volume concentration in specific dimensions.
- King Size:North American convenience channels standardize on this format, with urban centers consolidating purchases through subscription services. Younger demographics in metropolitan areas favor the extended rolling surface for hand-rolling rituals.
- Super Slim:Barcelona and Amsterdam retail corridors show fastest adoption among younger urban consumers seeking reduced tobacco consumption per roll. Calendering precision requirements strain mid-tier producer capacity.
- Single Wide:Traditional tobacconist distribution retains residual demand in rural European markets. Price sensitivity limits margin expansion.
- Double Wide:Specialty applications and artisanal blending shops absorb limited volume. Niche positioning constrains scale economies.
King Size commands the volume base; Super Slim is expanding most quickly in urban premium channels.
Flavor:
ECHA's candidate list for substances of very high concern forces reformulation cycles across coated segments, with in-house toxicology capabilities determining launch velocity.
- Unflavored:Dominant share reflects regulatory caution and additive disclosure avoidance. Clean burn profiles satisfy EU emissions testing protocols without reformulation risk.
- Mint:Micro-encapsulation techniques from food processing enable cleaner burn profiles. Berry segment coatings face parallel innovation pressure.
- Berry:Specialty retail generates disproportionate margin contributions despite smaller volume base. REACH compliance timelines concentrate advantage with early certifiers.
- Chocolate:Niche positioning in European boutique channels. Limited distribution outside artisanal tobacco retailer networks.
Unflavored carries the volume foundation; mint and berry are climbing the fastest on regulatory-compliant reformulation.
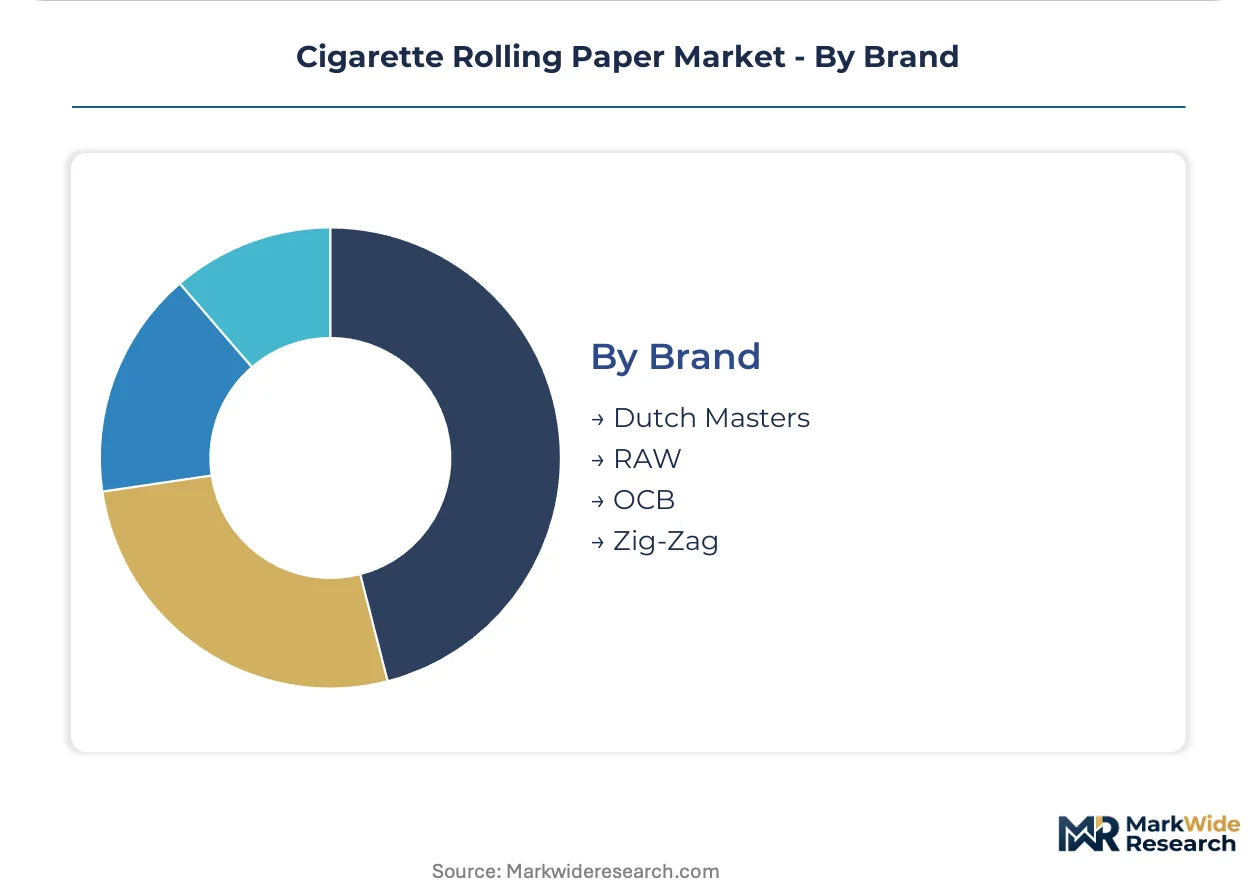
Brand:
Private-label expansion across Western European boutique smoke shops fragments branded distribution, though established names retain procurement preference in conventional channels.
- RAW:Unbleached hemp fiber positioning aligns with provenance-preference trends in France and the Netherlands. Barcelona-area manufacturing complex anchors European supply security.
- OCB:Premium ultra-thin specifications sustain placement in Amsterdam and Madrid urban retail corridors. King Size format standardization supports convenience channel penetration.
- Zig-Zag:Heritage recognition sustains volume in traditional tobacconist networks. Flavor-infused variants compete for specialty retail shelf space.
- Dutch Masters:Cigarillo heritage constrains rolling paper category expansion. Limited format range restricts urban convenience channel access.
RAW and OCB split the premium channel throughput; private-label capture is gaining share fastest in Western European boutique retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in cigarette rolling paper track regulatory divergence and fiber-sourcing specialization. Western European markets absorb premium hemp-fiber imports while Asian supply chains serve cost-optimized distribution networks. The United States, Germany, France, Spain, and the Netherlands concentrate distinct demand patterns and compliance burdens.
United States
FDA ingredient listing requirements and modified risk tobacco product pathways shape formulation decisions for domestic manufacturers. Urban convenience channels in New York and Los Angeles consolidate purchases through smoke shop loyalty programs. King Size format standardization dominates volume throughput across metropolitan retail corridors.
Germany
Laboratory capacity for EU-mandated burn emission analysis concentrates in German testing facilities, creating six-month queue times for certification completion. ECHA's expanding candidate list for substances of very high concern forces reformulation of flavor carrier coatings. The Rhine-Ruhr industrial zone hosts specialized paper machinery reconfiguration services for ultra-thin calendering upgrades.
France
Mechanical decortication of hemp fibers preserves long strands for premium ultra-thin specifications favored in Paris and Lyon retail networks. ANSM oversight of tobacco-related products aligns with EU Tobacco Products Directive additive disclosure mandates. French cultivation zones in Auvergne-Rhône-Alpes supply established chain-of-custody documentation for linen fiber variants.
Spain
Barcelona-area manufacturing anchors European supply security for unbleached hemp fiber positioning. REACH chemical substance registration governs coatings and flavor carriers entering Spanish distribution channels. Madrid retail corridors show fastest adoption of Super Slim formats among younger urban consumers seeking reduced tobacco consumption per roll.
Netherlands
Amsterdam boutique smoke shops absorb three-to-one volume premiums for mechanically processed hemp papers over chemically retted alternatives. Dutch regulators enforce EU Tobacco Products Directive emissions testing protocols with accelerated timelines for specialty manufacturers. The Randstad urban cluster pilots curated direct-to-consumer subscription services for premium rolling paper assortments.
Cigarette Rolling Paper Market Vendor Landscape
Concentration sits with vertically integrated pulp-to-reel converters and specialty flavor-infused producers. The market structure splits between large-scale Fourdrinier operators serving standardized formats and niche players capturing premium provenance segments. Strategic archetypes include European heritage manufacturers with Barcelona-area production complexes, North American integrated pulp refiners, and Asian cost-optimized fiber processors. Dominant competitive moves encompass emissions testing certification racing and private-label partnership development with boutique retail chains.
Within the heritage European tier, Miquel y Costas & Miquel S.A. and Glatz Feinpapiere GmbH exemplify established positioning through geographic naming and corporate structure. Republic Technologies International occupies a representative position among specialty variant developers. These anchors illustrate how family-owned S.A. structures, German GmbH engineering heritage, and international branding frameworks coexist within regulatory-intensive market conditions.
| Leading Market Players |
|---|
| HBI International |
| Miquel y Costas & Miquel |
| Schweitzer-Mauduit International (SWM) |
| Nippon Paper Papylia |
| Hengfeng Paper |
| Republic Technologies International |
| Glatz Feinpapiere |
| ITC Limited |
| Delfort Group |
| Others |
Supply Flow & Price Mechanics
Fourdrinier machine scale economies in Nordic pulp refining establish cost floors that compress mid-tier producer margins while rewarding integrated operators with captive fiber supply. REACH chemical registration burdens and EU Tobacco Products Directive compliance costs concentrate pricing power among early-certifying mills with in-house toxicology capabilities, fragmenting competitive positioning across premium and standard tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade (REACH-compliant versus standard) and fiber provenance transparency, with mechanical-decortication hemp commanding three-to-one premiums over chemically retted alternatives. Pricing pressure stems from Nordic pulp input volatility and energy-intensive refining costs that limit pass-through flexibility. Price-sensitive convenience channels in North American urban centers resist premium migration, while boutique smoke shops in Amsterdam and Barcelona absorb provenance premiums with minimal elasticity.
Supply Chain Analysis
Inventory lead times for EU-mandated emissions testing stretch six months as German and Dutch laboratory capacity concentrates certification queues. Geographic supply concentration centers on Spain, France, and Belgium for premium hemp and flax fiber, with Asian chemical-retting operations serving cost-optimized distribution. Raw material dependencies span Nordic wood pulp, European hemp cultivation zones, and specialty coating chemicals governed by REACH. Single-source vulnerability sits with emissions testing talent scarcity. Distribution runs through boutique smoke shop cooperatives piloting direct-to-consumer subscription models alongside conventional tobacconist networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as hemp-fiber provenance preference penetrates Western European premium channels ahead of regulatory disclosure mandates. Private-label capture in artisanal retail creates white-space opportunity outside established branded distribution.
For Market Incumbents: Compound defensible positioning through backward integration into European hemp cultivation zones and accelerated REACH certification investment ahead of ECHA candidate list expansion. Pre-rolled cone substitution threatens hand-rolling ritual persistence in North American urban centers; defend through smoke shop loyalty program exclusivity and ultra-thin calendering capacity expansion in Barcelona-area manufacturing complexes. For New Entrants and Emerging Players: Differentiate on mechanical-decortication fiber provenance and direct-to-consumer subscription fulfillment to bypass entrenched branded distribution. White-space concentrates in curated delivery services for Amsterdam and Barcelona urban clusters and REACH-compliant flavor carrier micro-encapsulation. Target boutique smoke shop private-label partnerships as the most penetrable channel entry vector. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated pulp-to-reel converters with emissions testing certification momentum and chain-of-custody documentation capabilities. Long-term viability hinges on EU Green Deal carbon disclosure alignment and cellulose sourcing certifier status. Watch for inflection signals in boutique retail cooperative procurement consolidation and private-label volume share capture rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hemp Cultivation | Captures provenance premiums in France, Spain, and Netherlands retail corridors. |
| REACH Certification Acceleration | Secures preferred supplier status with ECHA candidate list expansion looming. |
| Ultra-Thin Calendering Capacity Expansion | Positions for Super Slim format adoption in Barcelona and Madrid urban centers. |
| Direct-to-Consumer Subscription Launch | Pilots curated delivery through Amsterdam smoke shop cooperatives. |
| Private-Label Partnership Development | Captures boutique retail channel fragmentation outside branded distribution. |
Methodological Framework
Operator-level perspectives from mill production managers, boutique smoke shop procurement leads, specialty paper machinery engineers, and ECHA regulatory affairs specialists anchored the qualitative base. Primary interview insights combined with secondary validation from EU Tobacco Products Directive implementation reports, REACH substance registration databases, Nordic pulp trade association publications, and customs fiber import records. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates across material type, format specification, and distribution channel dimensions.
Sensitivity analysis tested forecast robustness against pulp pricing volatility scenarios and regulatory timeline acceleration assumptions across the projection horizon. Segmentation dimensions modeled include fiber material category, basis weight grade, format size, flavor coating status, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules, demographic consumption pattern shifts, and channel migration trajectories. Industry-specific inputs incorporated Fourdrinier machine utilization rates and emissions testing laboratory queue dynamics.
Material uncertainties — regulatory timeline delays, pulp commodity price spikes, and pre-rolled cone substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about hemp cultivation zone expansion and boutique retail channel consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Cigarette Paper Market
Tobacco
US Tobacco Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Heat-Not-Burn Market
Tobacco
North America Cigarette Market
Tobacco
Organic Tobacco Market
Tobacco
Tobacco Films Market
Tobacco
North America Tobacco Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
Egypt Tobacco Market
Tobacco
Middle East and Africa Smokeless Tobacco Market