
 Egypt Tobacco Market | 2026-2036
Egypt Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Tobacco Market Analysis
Egypt's excise tax framework is rebalancing consumer purchasing patterns toward lower-tar and value-tier alternatives. Eastern Company SAE anchors domestic manufacturing through its state-affiliated production scale across multiple governorate facilities. Philip Morris International Inc. navigates the heated-tobacco segment with specialized device portfolios. Al Mansour International Distribution Co. controls extensive retail channel access, particularly in urban convenience networks.
Egypt tobacco comprises cured leaf products manufactured through flue-curing, air-curing, or sun-curing processes, typically containing nicotine levels between 1.5% and 3% by dry weight, with primary commercial purpose centered on combustion or heated aerosol delivery for recreational use. Cigarettes occupy the dominant volume position within product type classification, while roll-your-own variants capture growing price-sensitive migration. Supermarkets and convenience stores together constitute the structural backbone of distribution channel segmentation, though online retail demonstrates accelerating penetration among digitally native consumer cohorts.
Egypt's Ministry of Finance and the Egyptian Organization for Standardization and Quality impose product composition and packaging standards that directly constrain manufacturing inputs and marketing presentation. The country's national pharmaceutical regulator maintains oversight of nicotine concentration claims and reduced-harm positioning. Stakeholders must monitor excise policy calibration and potential plain-packaging mandates to anticipate margin compression and portfolio restructuring requirements.
Market Dynamics
Egypt's Ministry of Finance excise tax adjustments are compressing volume elasticity and forcing portfolio restructuring across manufacturing tiers. State-affiliated production scale confronts price-sensitive consumer migration toward value-tier alternatives.
Growth Catalysts
- Heated-tobacco device penetration:Specialized aerosol delivery systems are capturing urban adult smokers seeking reduced-combustion alternatives. Cairo and Alexandria convenience networks report accelerating device turnover.
- Nile Delta distribution density:Population concentration across Gharbia, Dakahlia, and Sharqia governorates sustains volume throughput via established wholesale corridors. Eastern Company SAE manufacturing footprint aligns with this geography.
- Excise tax tier differentiation:Lower-tar product categories benefit from favorable tax brackets under current Ministry of Finance calibration. Manufacturers are reallocating leaf blend inputs toward qualifying thresholds.
Market Restraints
- Flue-cured leaf import dependency:Domestic curing capacity constraints force reliance on international leaf suppliers. Currency volatility directly impacts input cost structures.
- Plain-packaging regulatory trajectory:Egyptian Organization for Standardization and Quality draft standards threaten brand differentiation mechanics. Margin compression looms for premium-positioned portfolios.
- Pharmaceutical regulator oversight expansion:National pharmaceutical regulator scrutiny of reduced-harm claims limits marketing vocabulary. Product positioning flexibility narrows.
Strategic Opportunities
- Upper Egypt underpenetration:Sohag, Qena, and Aswan governorates exhibit lower per-capita consumption versus Delta benchmarks. Distribution infrastructure gaps present first-mover expansion potential.
- Digital-native cohort channel migration:Online retail penetration among consumers under 30 years is accelerating. Platform partnerships with local e-commerce operators unlock direct-to-consumer pathways.
- Value-tier roll-your-own segment:Price-sensitive smokers are migrating toward loose-leaf and manual-rolling formats. Manufacturing flexibility toward cut-rag output captures this shift.
Industry Challenges
- Excise tax compliance system integration:Real-time reporting requirements to Ministry of Finance tax portals demand ERP upgrades. Legacy manufacturing accounting systems face replacement timelines.
- Reduced-harm certification evidence generation:Clinical study design and toxicological data assembly for regulatory submissions require specialized biostatistical expertise. Talent scarcity in Cairo's contract research sector delays dossier preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Tobacco Market |
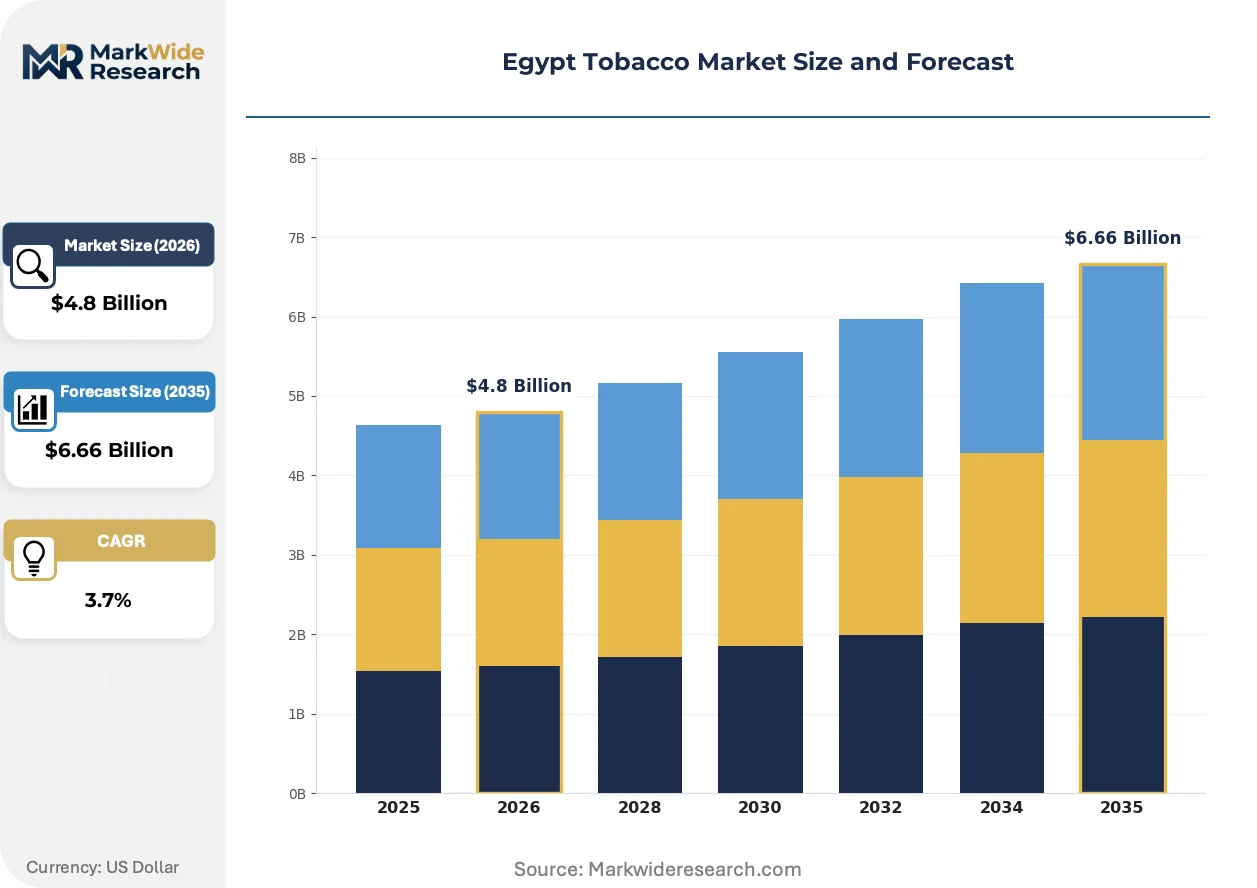
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarettes, Cigars, Roll Your Own, Smokeless Tobacco Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Duty-Free Shops Consumer Type: Adults, Youth, Occasional Smokers, Daily Smokers Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | Japan Tobacco International SA, Al Mansour International Distribution Co., Eastern Company SAE, China Tobacco International (HK), United Tobacco Co., Philip Morris International Inc., Imperial Brands PLC, Al Nakhla Tobacco Co., British American Tobacco PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Tobacco Market Emerging Trajectories
Heated-tobacco technology and excise-driven product reformulation are restructuring Egypt's competitive landscape. Manufacturers confront simultaneous pressure from device innovation and tax-calibrated portfolio rebalancing.
Heated-tobacco platforms are consolidating market position among urban adult smokers in Cairo and Alexandria. These devices generate nicotine-containing aerosol without combustion, appealing to consumers navigating public smoking restrictions. Philip Morris International Inc. and comparable multinationals are scaling specialized device portfolios through convenience store partnerships. The technology is consolidating demand around rechargeable hardware ecosystems rather than disposable cigarette formats.
Egypt's Ministry of Finance excise tax framework is tightening the price gap between tar tiers. Lower-tar cigarettes face reduced per-unit taxation, creating explicit manufacturing incentives for leaf blend reformulation. Eastern Company SAE and domestic competitors are reallocating curing processes toward air-cured and sun-cured outputs that qualify for favorable brackets. The policy is compressing premium-standard-economy pricing stratification.
Urban convenience networks are displacing traditional kiosk channels among younger adult consumers. Supermarket and hypermarket tobacco sections now anchor brand visibility, particularly in Cairo's new administrative capital retail zones. Al Mansour International Distribution Co. and comparable wholesalers are restructuring territory assignments around modern trade format density. Alexandria's coastal retail corridors exhibit the most visible channel consolidation.
Egypt Tobacco Market Segmentation
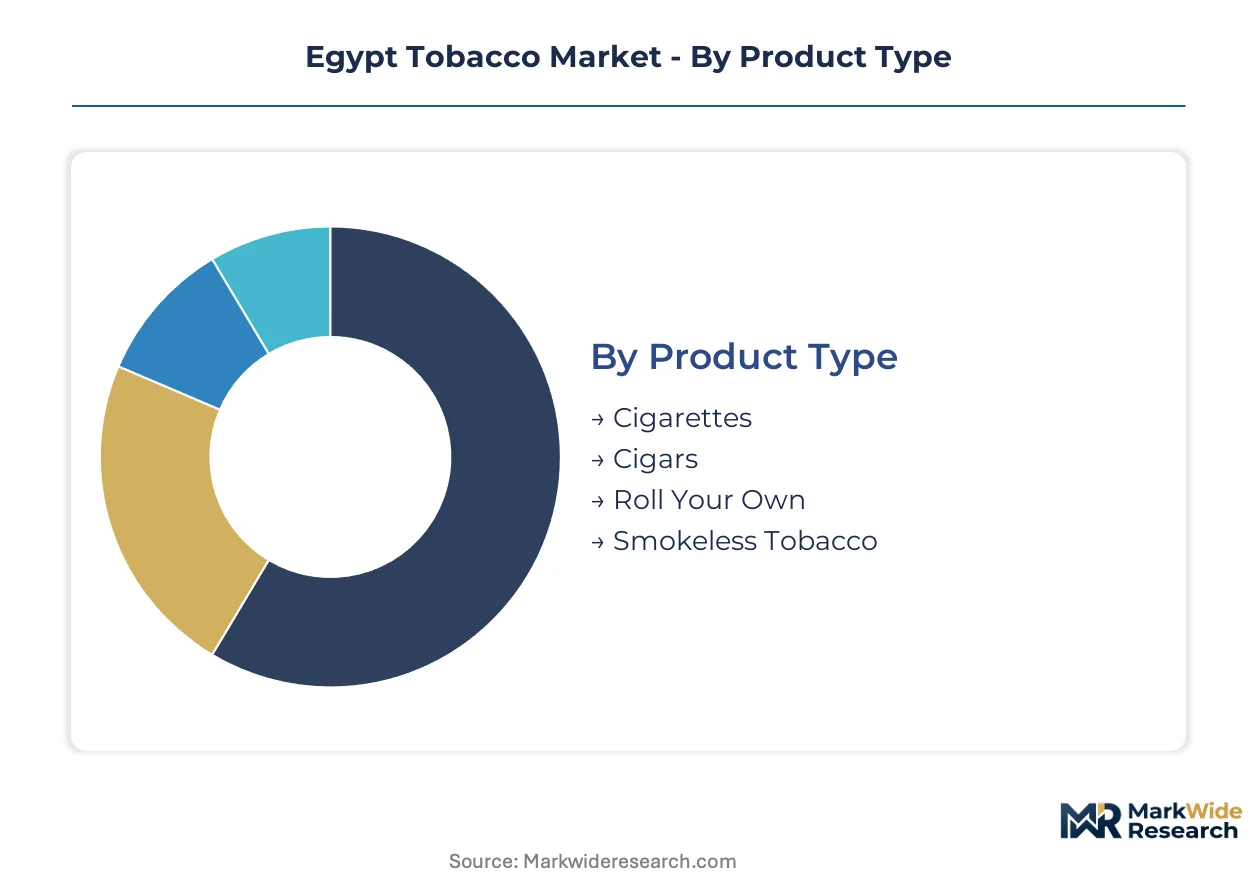
Egypt's tobacco market segmentation reveals how excise tax calibration and distribution infrastructure shape consumption patterns across distinct product formats and channel pathways. Understanding these segment boundaries enables stakeholders to align manufacturing capacity and retail partnerships with where demand is actually concentrating.
Product Type:
Cigarettes function as standalone combustion products, while roll-your-own and smokeless formats embed into consumer routines as flexible, price-responsive alternatives.
- Cigarettes:Flue-cured and air-cured leaf blends deliver nicotine through combustion, with filter-tipped formats dominating Cairo and Alexandria retail turnover. Egypt's Ministry of Finance excise tax tiers compress margin structures toward lower-tar variants.
- Cigars:Fermented whole-leaf wrappers containing higher alkaloid concentrations serve ceremonial and premium gifting occasions. Demand clusters in Alexandria's coastal hospitality venues and Cairo's diplomatic zones.
- Roll Your Own:Cut-rag tobacco with separate paper and filter components allows manual assembly. Price-sensitive smokers in Gharbia and Dakahlia governorates are migrating toward this format as tax-adjusted pack prices rise.
- Smokeless Tobacco:Moist snuff and chewing variants bypass combustion entirely. Limited penetration currently, though pharmaceutical regulator oversight of reduced-harm claims creates positioning constraints for expansion.
Cigarettes lead volumes today; roll-your-own is gaining share fastest.
Distribution Channel:
Channel selection maps directly to consumer urgency and purchase frequency, with modern trade formats capturing planned replenishment and convenience networks serving immediate need states.
- Supermarkets:Climate-controlled tobacco sections with standardized shelving enable brand visibility and bulk purchasing. Cairo's new administrative capital retail zones anchor this channel's growth trajectory.
- Convenience Stores:Extended operating hours and dense urban placement support impulse and replacement purchases. Alexandria's coastal corridors exhibit the most visible network consolidation.
- Online Retail:Platform-based ordering with delivery logistics serves digitally native consumers under 30 years. Egyptian Organization for Standardization and Quality packaging standards complicate direct-to-consumer fulfillment.
- Duty-Free Shops:Airport and port-adjacent retail captures inbound and outbound traveler flows. Currency volatility impacts pricing competitiveness versus domestic taxed alternatives.
Convenience stores lead volumes today; online retail is expanding most quickly.
Consumer Type:
Consumption intensity and regulatory exposure diverge sharply across this dimension, with daily users driving revenue concentration and occasional users presenting acquisition economics challenges.
- Adults:Consumers aged 18+ constitute the legally addressable market, with urban Cairo and Alexandria cohorts showing highest per-capita expenditure. Egypt's Ministry of Finance tax policy directly shapes their brand switching behavior.
- Youth:Consumers under 18 fall outside legal purchase parameters, though enforcement gaps in informal retail channels sustain access. National pharmaceutical regulator scrutiny of marketing vocabulary limits targeted outreach.
- Occasional Smokers:Intermittent consumption patterns correlate with social and stress-triggered use cases. Lower lifetime value complicates loyalty program design for manufacturers.
- Daily Smokers:Habituated consumption routines generate predictable volume throughput and brand stickiness. This segment concentrates in Nile Delta manufacturing belt governorates with established distribution corridors.
Daily smokers lead volumes today; occasional smokers show steepest expansion trajectory among legally addressable segments.
Price Tier:
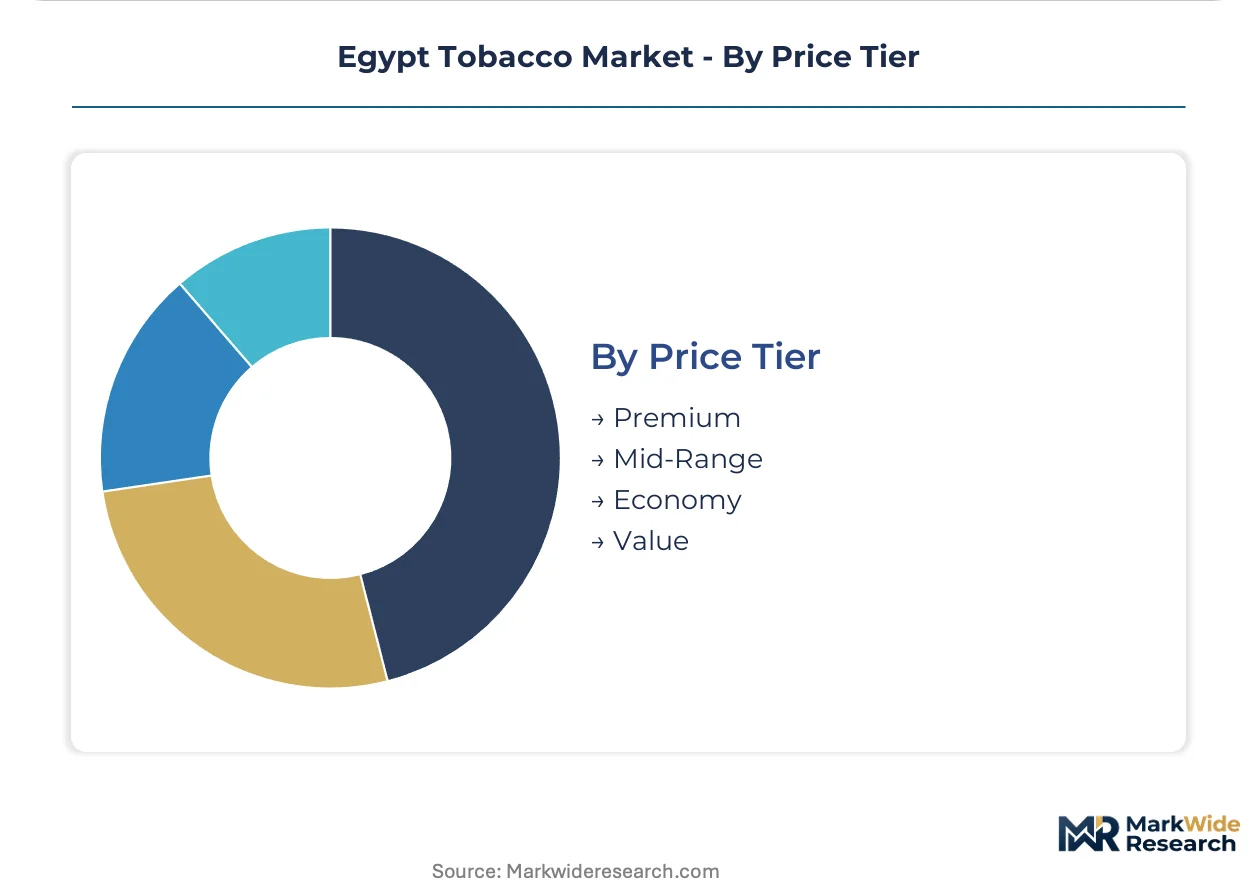
Tax bracket alignment and leaf input costs create four distinct margin structures, with excise calibration actively compressing the gap between adjacent tiers.
- Premium:Higher-tar blends with established brand heritage and differentiated packaging command elevated price points. Plain-packaging regulatory drafts from Egyptian Organization for Standardization and Quality threaten differentiation mechanics.
- Mid-Range:Balanced quality-positioning targets white-collar urban consumers seeking perceived value. Alexandria's retail networks show strongest mid-range shelf space allocation.
- Economy:Standardized leaf blends with minimal marketing overhead serve price-conscious daily smokers. Eastern Company SAE production scale anchors supply security for this tier.
- Value:Aggressive price positioning through reduced filter costs and simplified packaging captures migration from higher tiers. Ministry of Finance excise adjustments accelerate consumer flow into this bracket.
Economy tier leads volumes today; value tier is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tobacco cultivation and curing operations first scaled along the Nile Delta during the late nineteenth century, establishing Egypt as a regional processing hub. State-affiliated manufacturing subsequently concentrated in Cairo and Alexandria, with distribution corridors extending southward through Upper Egypt. The analysis now examines consumption patterns and regulatory exposure across Egypt's primary sub-regional markets.
Nile Delta Corridor
Gharbia, Dakahlia, and Sharqia governorates generate the highest per-capita cigarette consumption volumes nationwide. Egypt's Ministry of Finance excise tax tiers compress margins toward lower-tar variants in these price-sensitive manufacturing belt communities. Eastern Company SAE maintains production facilities across this geography, aligning leaf curing capacity with established wholesale distribution infrastructure.
Cairo Metropolitan Area
Urban adult smokers in Cairo demonstrate accelerating adoption of heated-tobacco devices and reduced-combustion alternatives. The Egyptian Organization for Standardization and Quality imposes packaging standards that constrain direct-to-consumer online fulfillment. New administrative capital retail zones anchor modern trade format expansion, displacing traditional kiosk channels among consumers under thirty years.
Alexandria Coastal Zone
Alexandria's hospitality venues and diplomatic zones sustain premium cigar and ceremonial gifting demand distinct from mass-market cigarette patterns. The Ministry of Finance tax policy directly shapes brand switching behavior among white-collar urban cohorts. Coastal retail corridors exhibit the most visible convenience store network consolidation, with Al Mansour International Distribution Co. controlling extensive territory assignments.
Upper Egypt Governorates
Sohag, Qena, and Aswan exhibit significantly lower per-capita tobacco consumption versus Delta benchmarks. Distribution infrastructure gaps and wholesale corridor underdevelopment present first-mover expansion potential for manufacturers. The national pharmaceutical regulator maintains oversight of nicotine concentration claims, limiting reduced-harm positioning vocabulary in these underpenetrated markets.
Egypt Tobacco Market Vendor Landscape
Capital-heavy producers with integrated curing and manufacturing assets compete with asset-light distributors and multinational brand licensors for shelf space and consumer mindshare. The market structure consolidates around state-affiliated domestic manufacturing scale, regional distribution specialists, and global tobacco multinationals with heated-tobacco device portfolios. Three archetypes dominate: integrated domestic producers controlling leaf-to-pack supply chains, multinational technology licensors specializing in aerosol delivery systems, and regional distribution houses commanding retail channel access. Competitive maneuvering centers on excise tax tier qualification through leaf blend reformulation and convenience network territory consolidation.
Among state-affiliated integrated producers, Eastern Company SAE anchors domestic manufacturing scale across multiple governorate facilities. Philip Morris International Inc. occupies the multinational technology licensor position, navigating heated-tobacco segments through specialized device portfolios. Al Mansour International Distribution Co. exemplifies the regional distribution house archetype, controlling extensive retail channel access particularly in urban convenience networks. These three entities collectively represent the competitive structure's primary tension points: manufacturing scale versus technology differentiation versus channel control.
| Leading Market Players |
|---|
| Japan Tobacco International SA |
| Al Mansour International Distribution Co. |
| Eastern Company SAE |
| China Tobacco International (HK) |
| United Tobacco Co. |
| Philip Morris International Inc. |
| Imperial Brands PLC |
| Al Nakhla Tobacco Co. |
| British American Tobacco PLC |
| Others |
Supply Flow & Price Mechanics
Captive leaf curing capacity across Eastern Company SAE governorate facilities anchors both input security and tax-tier qualification leverage. Egypt's Ministry of Finance excise calibration rewards manufacturers controlling in-house air-cured and sun-cured output with favorable bracket access, compressing margins for competitors dependent on imported flue-cured leaf.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies around tar content and filter specification. Price differentiation rests on Ministry of Finance tax brackets and leaf blend origin, with domestic air-cured inputs qualifying for reduced per-unit taxation. Cost compression in premium tiers intensifies because plain-packaging drafts threaten brand heritage mechanics. Value-tier smokers in Nile Delta manufacturing belt communities exhibit highest price sensitivity; diplomatic-zone cigar purchasers in Alexandria show lowest.
Supply Chain Analysis
Device return and refurbishment flows for heated-tobacco hardware remain nascent, with Philip Morris International Inc. piloting closed-loop collection in Cairo convenience networks. Geographic supply concentration draws from Brazil, Zimbabwe, and Malawi for flue-cured leaf; Indonesia and India for air-cured varieties. Raw material dependencies center on fertilizer inputs, curing fuel, and filter tow. Single-source vulnerability looms in flue-cured import corridors exposed to currency volatility. Distribution runs through Al Mansour International Distribution Co. wholesale assignments into urban convenience and modern trade formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's tobacco market functions as a regulatory compounder where Ministry of Finance excise tier differentiation directly determines manufacturing profitability and portfolio allocation. The Egyptian Organization for Standardization and Quality draft plain-packaging standards represent the decisive milestone reshaping competitive positioning toward tax-optimized leaf blend capabilities.
For Market Incumbents: Acquire specialized air-curing and sun-curing facility assets in Nile Delta governorates to secure favorable excise bracket qualification. Integrate backward into cut-rag processing capacity to capture roll-your-own migration. Defend against heated-tobacco device entrants by controlling convenience store shelf space through Al Mansour International Distribution Co.-style territory consolidation. For New Entrants and Emerging Players: Egyptian Organization for Standardization and Quality packaging standard delays open a window for direct-to-consumer online platform partnerships before enforcement tightens. Target Upper Egypt governorates where distribution infrastructure gaps create first-mover whitespace. Pursue value-tier roll-your-own positioning with simplified packaging to exploit tax-driven consumer flow. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy ERP systems face Ministry of Finance real-time tax portal integration deadlines. Long-term viability favors integrated manufacturers with captive curing capacity and established wholesale corridor control. Monitor Egyptian Organization for Standardization and Quality plain-packaging implementation timing as inflection signal for premium portfolio write-downs.| Strategic Initiative | Industry Significance |
|---|---|
| Leaf Blend Reformulation | Ministry of Finance tax bracket qualification directly determines per-unit margin retention. |
| Heated-Tobacco Device Launch | Cairo and Alexandria convenience networks anchor urban adult smoker acquisition economics. |
| Distribution Territory Consolidation | Al Mansour International Distribution Co.-style channel control defends against multinational encroachment. |
| Online Retail Platform Partnership | Egyptian Organization for Standardization and Quality compliance gaps enable direct-to-consumer pathways. |
| Upper Egypt Expansion | Sohag, Qena, and Aswan infrastructure underdevelopment creates first-mover volume capture potential. |
Methodological Framework
Bottom-up consumption modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with Eastern Company SAE production executives, Al Mansour International Distribution Co. channel managers, Ministry of Finance tax policy officials, and Cairo retail network operators combined with secondary validation from Egyptian Organization for Standardization and Quality regulatory filings, customs leaf import records, and Eastern Company SAE financial disclosures. Top-down excise revenue data and bottom-up point-of-sale turnover triangulate volume estimates.
Input-output matrices map leaf curing capacity through wholesale distribution into retail channel turnover across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, consumer intensity, and price tier alignment with tax brackets. CAGRs derive from weighted average of historical excise revenue trajectories and projected consumption elasticity responses. Industry-specific forecast inputs incorporate Ministry of Finance tax calibration announcements and heated-tobacco device adoption curves in Cairo metropolitan retail zones.
Revisions become necessary when Ministry of Finance excise tier thresholds shift, Egyptian Organization for Standardization and Quality packaging standards finalize, or currency volatility disrupts flue-cured leaf import cost structures. Forecasts reflect assumptions around regulatory implementation timing and consumer substitution elasticity between combustion and heated-aerosol formats. Practitioners should monitor Ministry of Finance pre-budget policy consultations and Eastern Company SAE capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Cigarette Paper Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
Middle East and Africa Smokeless Tobacco Market
Tobacco
Tobacco Films Market
Tobacco
Organic Tobacco Market
Tobacco
North America Cigarette Market
Tobacco
US Tobacco Market
Tobacco
Heat-Not-Burn Market
Tobacco
North America Tobacco Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Cigarette Rolling Paper Market