
 North America Cigarette Market | 2026-2036
North America Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cigarette Market Intelligence
Aftermarket service revenue from loyalty programs and direct-to-consumer digital platforms is fragmenting as traditional retail margins compress. Altria Group leverages its Marlboro Rewards ecosystem to sustain recurring engagement beyond the point of sale. Reynolds American competes through its Camel and Newport brand architectures, while ITG Brands anchors volume in value-tier segments through Liggett Vector's discount positioning.
A cigarette is a cylindrical roll of cured and finely cut tobacco leaf wrapped in paper, typically containing 10-14 mg of tar and 0.8-1.2 mg of nicotine per unit, designed for combustion and inhalation to deliver alkaloid absorption through pulmonary capillaries. Filter cigarettes dominate unit economics due to higher per-pack pricing and established manufacturing infrastructure, while menthol cigarettes face structural decline from regulatory pressure despite historically outsized profit contribution. Online retail channels are gaining fastest within distribution architecture as age-verification technology matures, though convenience stores still occupy the majority of transaction volume through impulse-purchase placement and tobacco-specific licensing density.
The US FDA exercises premarket authority under the Family Smoking Prevention and Tobacco Control Act, while state attorneys general enforce Master Settlement Agreement provisions that constrain marketing and fund cessation programs. Health Canada and PMRA administer parallel product standards including graphic warning mandates and maximum emission limits that shape cross-border product differentiation. Stakeholders must monitor pending federal menthol rulemaking and state excise tax ballot initiatives to calibrate portfolio allocation between premium and discount tiers.
Market Dynamics
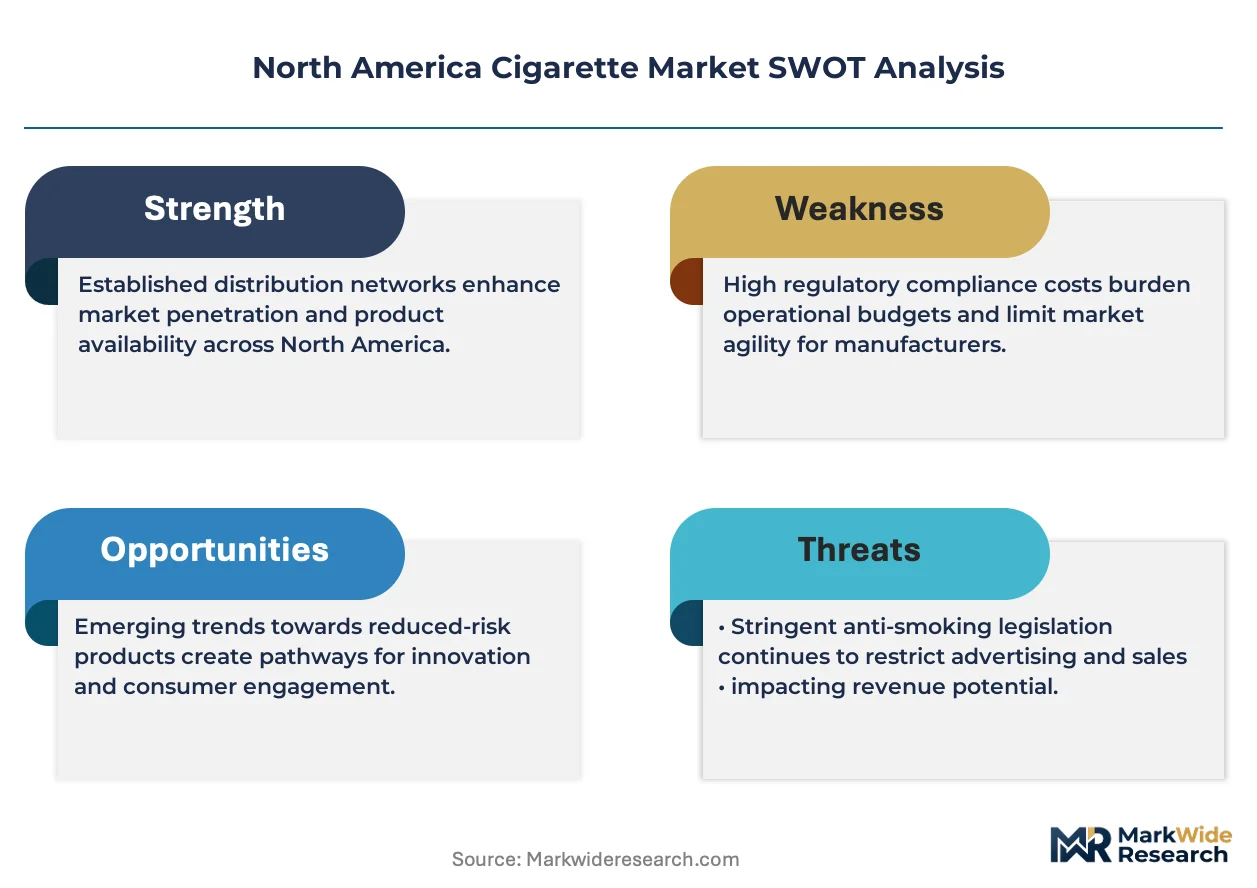
The US FDA's pending menthol prohibition is compressing the most profitable cigarette sub-category while concentrating volume in southern states with lower excise tax burdens and higher retail density.
Growth Catalysts
- Adult smoker cohort persistence:The 35-44 age bracket sustains core consumption volume through established brand loyalty and habitual purchase patterns.
- Texas and Florida retail density:These states preserve affordability through below-average state excise tax rates and high tobacco outlet concentration.
- Digital age-verification maturation:Biometric and third-party verification technologies are unlocking compliant direct-to-consumer channels.
Market Restraints
- Flavor restriction cascade:California and Massachusetts state-level bans on flavored tobacco products are eliminating menthol and other additive-enhanced variants.
- Master Settlement Agreement constraints:State attorneys general enforce marketing restrictions and fund cessation programs that reduce initiation rates.
- Smoke-free substitution:Heat-not-burn and oral nicotine products are capturing switching demand from combustible categories.
Strategic Opportunities
- Value-tier portfolio expansion:Discount segments in price-sensitive southern markets offer volume defense against premium compression.
- Loyalty platform monetization:Direct-to-consumer engagement ecosystems can capture recurring revenue beyond point-of-sale transactions.
- Cross-border product differentiation:Health Canada and PMRA regulatory divergence enables tailored formulations for Canadian versus US markets.
Industry Challenges
- SKU rationalization complexity:Portfolio managers must balance menthol inventory drawdown against non-menthol production ramp-up under uncertain FDA rulemaking timelines.
- Retail license consolidation risk:Convenience store channel concentration creates vulnerability to municipal tobacco retail caps and zoning restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cigarette Market |
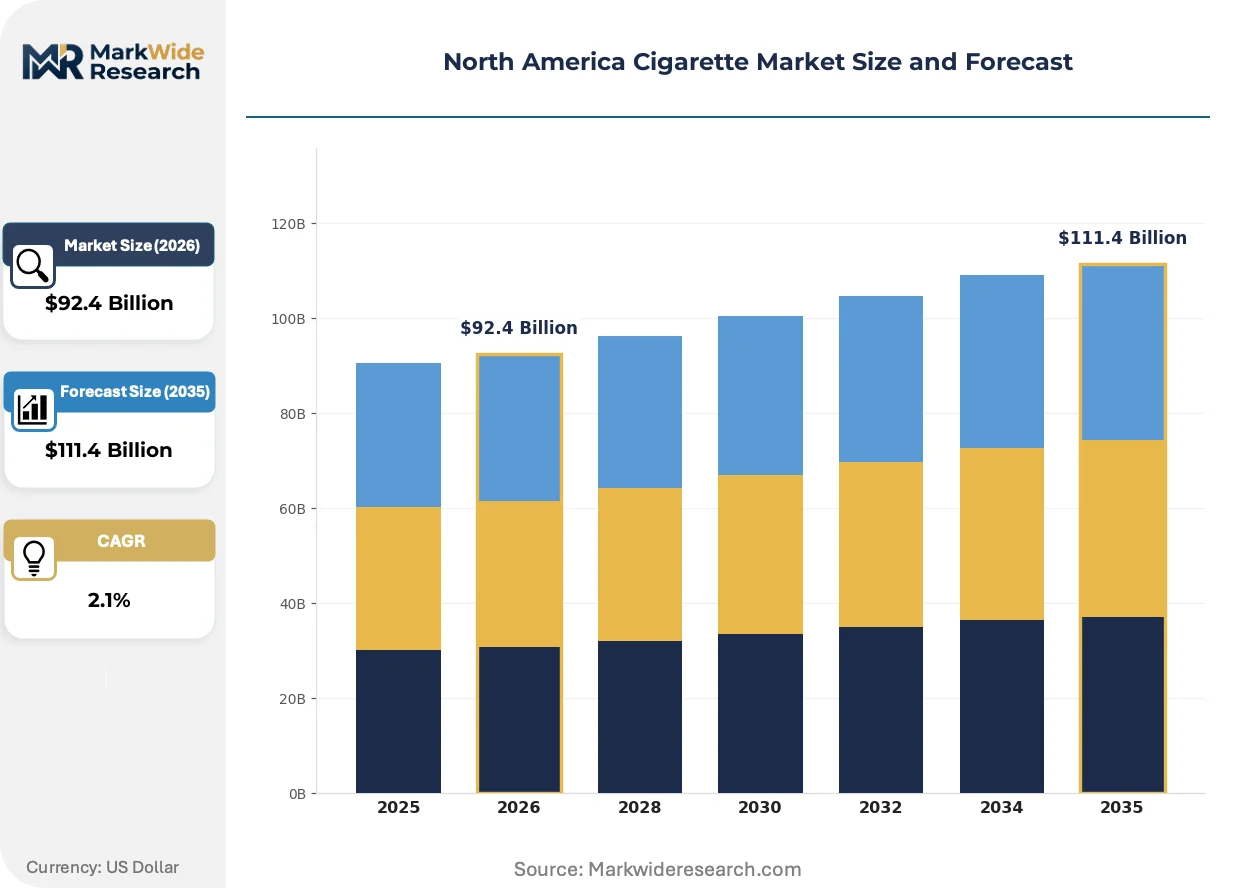
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $111.4 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filter Cigarettes, Non-Filter Cigarettes, Menthol Cigarettes, Light Cigarettes Distribution Channel: Convenience Stores, Supermarkets, Online Retail, Specialty Shops Consumer Age Group: 18-24 Years, 25-34 Years, 35-44 Years, 45+ Years Brand Type: Premium Brands, Mid-Range Brands, Budget Brands, Local Brands |
| Companies Covered | Altria Group, Inc., Reynolds American Inc., Philip Morris USA, ITG Brands, LLC, British American Tobacco, Liggett Vector Brands LLC, Imperial Brands, Japan Tobacco International, Vector Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cigarette Market Strategic Shifts & Innovations
Combustible cigarette markets are bifurcating between premium brand defense and value-tier volume retention while regulatory pressure accelerates format experimentation and channel migration.
Heat-not-burn technology is virtualizing traditional combustion economics by delivering nicotine absorption without pyrolysis byproducts. Adult smokers aged 35-50 in Texas and Florida are adopting these devices at measurable rates. This shift is virtualizing R&D investment away from filter and paper innovation toward aerosol engineering and device ecosystem lock-in.
The US FDA's premarket tobacco product application pathway is extending time-to-market for novel combustible variants. Manufacturers face multi-year review cycles that freeze product pipeline diversification. Menthol and other characterizing flavor categories bear the heaviest compliance burden as the agency prioritizes prohibition over authorization.
After-sales engagement is unbundling from traditional retail relationships as loyalty programs capture behavioral data and repeat purchase intent. Convenience store distributors are losing exclusive customer access to manufacturer-owned digital platforms. This channel disintermediation is most advanced in southern states where mobile penetration and reward program enrollment rates exceed national averages.
North America Cigarette Market Segmentation
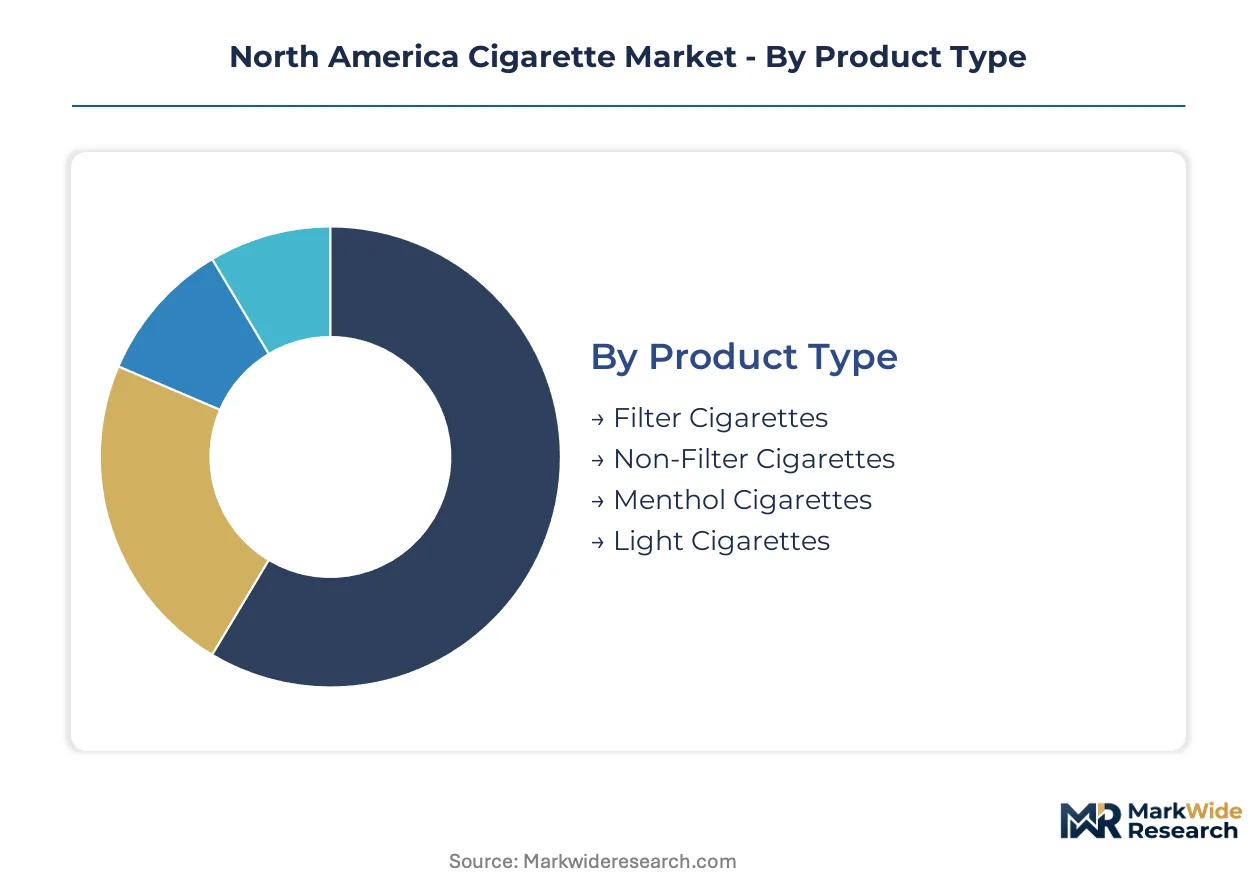
Segmentation in the North America cigarette market reveals how regulatory pressure and channel economics are redistributing volume across product formats and retail architectures. Manufacturers calibrate portfolio depth against state-level flavor restrictions while convenience store licensing density shapes geographic prioritization.
Product Type:
Mature segments dominate unit economics while emerging variants face accelerated regulatory compression.
- Filter Cigarettes:These products incorporate cellulose acetate or charcoal filtration mechanisms designed to reduce particulate matter inhalation. Demand concentrates in Texas and Florida where tobacco retail density and below-average state excise taxes preserve affordability for habitual purchasers.
- Menthol Cigarettes:Formulations containing L-menthol or synthetic analogs deliver cooling sensations and anesthetic effects that mask throat irritation. California and Massachusetts state-level prohibitions are eliminating this sub-category in coastal markets while concentrating remaining volume in southern jurisdictions without flavor restrictions.
- Non-Filter Cigarettes:Unfiltered variants deliver higher tar and nicotine yields through direct tobacco combustion without barrier mechanisms.
- Light Cigarettes:Products marketed with reduced tar and nicotine ratings through ventilation holes and modified paper porosity.
Filter cigarettes handle the majority of throughput; menthol variants are contracting fastest on share as FDA rulemaking advances.
Distribution Channel:
Channel economics separate high-frequency impulse purchase venues from compliance-heavy digital alternatives.
- Convenience Stores:These outlets leverage tobacco-specific licensing density and countertop placement to capture unplanned purchases. Volume concentrates in southern states where outlet concentration per capita exceeds national averages and municipal zoning remains permissive.
- Online Retail:Direct-to-consumer platforms deploy biometric age-verification and third-party identity confirmation to satisfy FDA and state attorney general compliance requirements. Texas and Florida consumers are adopting these channels fastest where mobile penetration supports digital loyalty program enrollment.
- Supermarkets:Grocery chains with tobacco retail licenses operate behind-the-counter protocols with lower SKU breadth than convenience specialists.
- Specialty Shops:Tobacconists and cigar lounges cater to connoisseur segments with premium and imported inventory.
Convenience stores retain dominant transaction share; online retail is climbing the fastest as verification technology matures.
Consumer Age Group:
Purchase frequency and brand loyalty intensity vary sharply across generational cohorts.
- 35-44 Years:This bracket sustains core consumption volume through established brand loyalty and habitual purchase patterns formed during earlier initiation periods. Demand concentrates in southern markets where social smoking norms persist and cessation program penetration lags coastal states.
- 25-34 Years:Younger adults in this cohort exhibit higher switching propensity between combustible and alternative nicotine formats. Heat-not-burn adoption rates in Texas and Florida are measurably elevated within this demographic.
- 18-24 Years:Initiation rates are compressing under Master Settlement Agreement-funded prevention programs and flavored product restrictions.
- 45+ Years:Established smokers in this bracket demonstrate lowest quit attempt rates but face accelerating health-driven cessation pressure.
The 35-44 year segment anchors volume stability; the 25-34 year bracket shows the steepest format-switching trajectory.
Brand Type:
Pricing architecture separates premium defense strategies from value-tier volume retention plays.
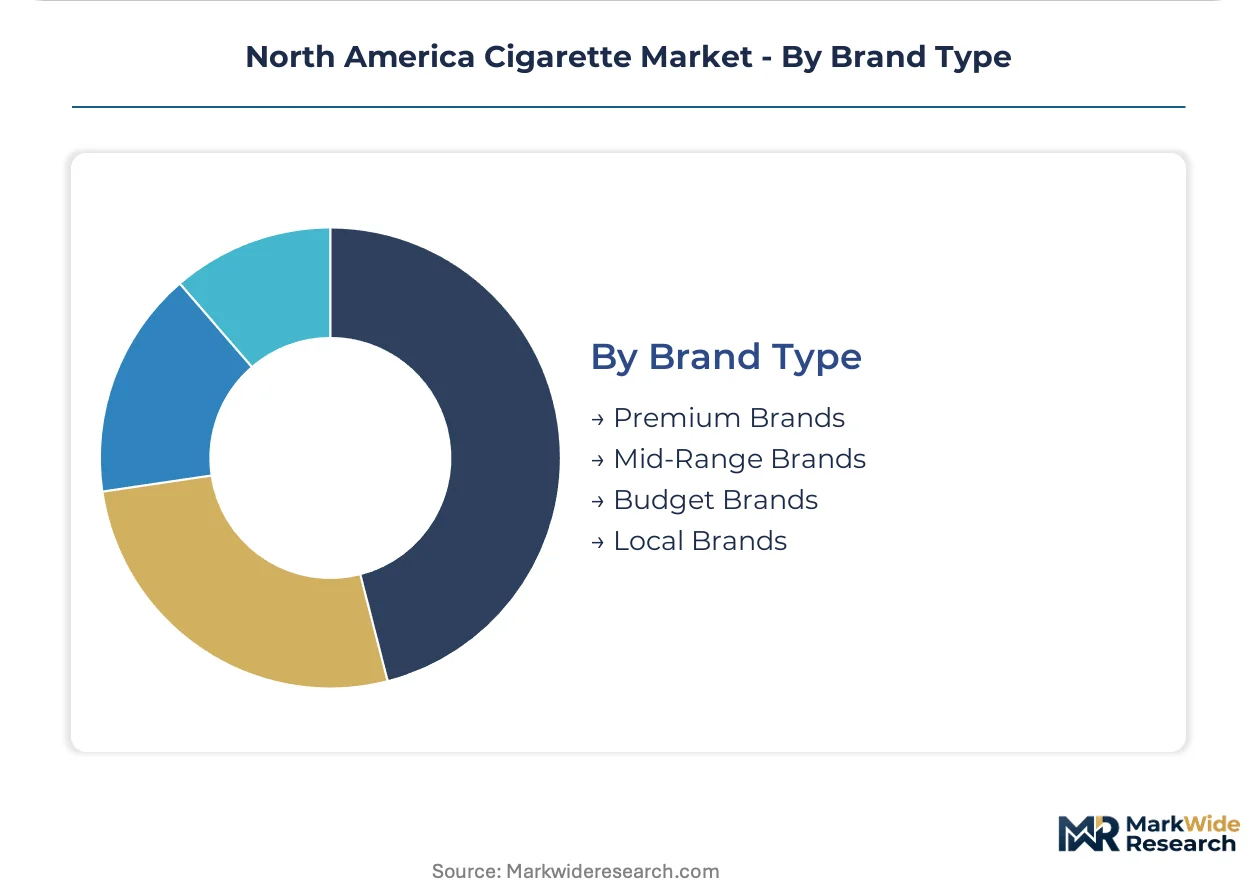
- Premium Brands:These products command per-pack price premiums through established trademark recognition and filtered product consistency. Demand concentrates in metropolitan markets where disposable income supports brand loyalty despite state excise tax escalation.
- Budget Brands:Discount positioning captures price-sensitive consumers in high-tax jurisdictions and economically constrained rural markets. Volume in Texas and Florida benefits from below-average state tax burdens that narrow the premium-to-discount price spread.
- Mid-Range Brands:Positioned between premium and economy tiers with moderate price points and regional distribution concentration.
- Local Brands:Smaller manufacturers and regional labels serving niche geographic markets with limited national distribution infrastructure.
Premium brands defend margin concentration; budget labels are expanding most quickly in price-sensitive southern markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North America, with southern US states exhibiting the highest price sensitivity due to lower excise tax burdens, while Canadian markets demonstrate more inelastic consumption patterns under stricter regulatory frameworks and higher per-pack pricing.
United States
Volume concentrates in Texas and Florida where below-average state excise taxes preserve affordability for habitual purchasers. The FDA's pending menthol prohibition under the Family Smoking Prevention and Tobacco Control Act is compressing the most profitable sub-category while redirecting inventory toward non-flavored variants. The I-35 corridor through Dallas-Fort Worth and Houston hosts dense convenience store networks that capture impulse purchases through high tobacco licensing density.
Canada
Health Canada and PMRA administer parallel product standards including graphic warning mandates and maximum emission limits that constrain format experimentation. The Prairie Provinces of Alberta and Saskatchewan sustain higher per-capita consumption rates than Ontario and Quebec where municipal smoke-free ordinances and cessation program penetration are more aggressive. Cross-border product differentiation enables tailored formulations that comply with stricter Canadian additive restrictions.
Mexico
Price-sensitive demand in northern border states responds to tax differentials with US markets, while central Mexico around Mexico City Metro exhibits brand loyalty patterns shaped by different competitive dynamics. The country's federal commission for protection against sanitary risks enforces tobacco control provisions that limit advertising and mandate health warnings. Manufacturing activity clusters in Nuevo León and the Bajío Region where distribution infrastructure serves both domestic and export channels.
North America Cigarette Market Key Industry Players
Premium-brand defenders and value-tier volume specialists split the market into distinct competitive spheres with limited overlap in pricing architecture. The structure consolidates around a handful of integrated manufacturers with national distribution infrastructure and deep convenience store relationships. Three archetypes dominate: multinational premium houses with diversified next-generation product portfolios, domestic value specialists focused on discount positioning in price-sensitive markets, and hybrid players balancing premium defense with value-tier expansion. Competitive moves center on loyalty platform monetization to capture recurring engagement beyond point-of-sale transactions, and SKU rationalization to navigate uncertain menthol rulemaking timelines.
Within the premium-brand defender archetype, Altria Group, Inc. and Reynolds American Inc. occupy positions that exemplify ecosystem-based customer retention strategies. Altria's Marlboro Rewards infrastructure anchors recurring engagement through digital channels, while Reynolds American leverages Newport and Camel architectures to defend volume in menthol-dependent markets before regulatory compression completes. ITG Brands, LLC represents the value-tier specialist archetype, with Liggett Vector positioning that captures price-sensitive demand in high-retail-density southern states where tax burdens remain below national averages.
| Leading Market Players |
|---|
| Altria Group, Inc. |
| Reynolds American Inc. |
| Philip Morris USA |
| ITG Brands, LLC |
| British American Tobacco |
| Liggett Vector Brands LLC |
| Imperial Brands |
| Japan Tobacco International |
| Vector Group Ltd. |
| Others |
Cost & Logistics Intelligence
Tobacco leaf sourcing concentrates in Brazil, Zimbabwe, and the United States, anchoring margin pools in premium brand architectures that command loyalty-driven price premiums downstream. Manufacturers translate agricultural cost volatility into tiered retail pricing through filter technology differentiation and menthol additive positioning.
Pricing Analysis
After-sales revenue from loyalty program enrollment and direct-to-consumer digital engagement drives lifetime value beyond initial pack transactions. Three-tier pricing structure across premium, standard, and economy levels segments buyers by brand recognition intensity and habitual purchase frequency. Price differentiation hinges on filter technology sophistication and state excise tax exposure, with southern markets exhibiting compressed spreads due to below-average tax burdens. Cost compression in menthol-dependent portfolios is intensifying because FDA prohibition timelines are forcing inventory drawdowns at discounted clearance rates.
Supply Chain Analysis
Flue-cured and burley tobacco leaf supply draws from Brazil, Zimbabwe, and the United States, with secondary sourcing in Malawi and India for oriental varietals. Raw material dependencies center on cured leaf grades, acetate tow for filtration, and proprietary flavoring compounds for additive-enhanced variants. Supply chain risk rests on single-source vulnerability for menthol synthetic production and tariff exposure on Brazilian leaf imports. Distribution runs through convenience store licensing networks in Texas and Florida, supplemented by maturing biometric age-verification platforms for compliant direct-to-consumer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against heat-not-burn and oral nicotine formats that are capturing switching demand from combustible categories. Incumbents must navigate portfolio compression while extracting value from loyalty infrastructure.
For Market Incumbents: Insulate core revenue streams by accelerating loyalty platform monetization through Marlboro Rewards-style ecosystems that capture behavioral data and repeat purchase intent. Secure backward integration into filter manufacturing to defend margin position against acetate tow price volatility. Prioritize SKU rationalization that balances menthol inventory drawdown against non-menthol production ramp-up under uncertain FDA rulemaking timelines.
For New Entrants and Emerging Players: Value-tier discount positioning in Texas and Florida convenience store networks represents the most penetrable entry point, given below-average state excise taxes and high retail density that narrow premium-to-discount price spreads. Digital-native age-verification platforms with biometric compliance layers offer a go-to-market angle that bypasses incumbent convenience store exclusivity arrangements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across next-generation nicotine delivery manufacturing as heat-not-burn device ecosystems require less fixed asset deployment than traditional combustion infrastructure. Acquisition targets should emphasize loyalty platform infrastructure and direct-to-consumer channel control rather than production capacity. The signal to watch is FDA premarket tobacco product application approval velocity for novel combustible variants as an indicator of regulatory risk tolerance.
| Strategic Initiative | Industry Significance |
|---|---|
| Loyalty Platform Expansion | Marlboro Rewards ecosystems capture recurring engagement beyond point-of-sale transactions in southern states. |
| SKU Rationalization | Portfolio managers balance menthol drawdown against non-menthol ramp-up under uncertain FDA timelines. |
| Digital Channel Development | Biometric age-verification unlocks compliant direct-to-consumer sales in Texas and Florida markets. |
| Value-Tier Portfolio Defense | Discount positioning in high-retail-density southern states preserves volume against premium compression. |
| Cross-Border Formulation Tailoring | Health Canada additive restrictions enable differentiated Canadian product architectures versus US variants. |
Research Approach
The analysis maps combustible cigarette, heat-not-burn, and oral nicotine sub-sectors, each validated through primary interviews with brand portfolio managers, convenience store category buyers, regulatory affairs specialists, and state attorney general enforcement officers. Secondary validation draws from FDA premarket tobacco product application filings, Master Settlement Agreement expenditure reports, state excise tax databases, and convenience store licensing records. Bottom-up volume triangulation across retail channels converges with top-down manufacturer shipment data to anchor forecast integrity.
Assumption sets held FDA menthol prohibition timing and state-level flavor restriction cascades as variable inputs while fixing adult smoker cohort persistence rates and southern state retail density parameters. The analytical framework segments by product format, distribution channel, consumer age bracket, and brand tier across the projection horizon. CAGRs derive from regression analysis against historical tax elasticity patterns and substitution rate trajectories, with heat-not-burn adoption curves and oral nicotine switching propensity serving as key demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in disposable income growth across the 35-44 age bracket and state excise tax ballot initiative outcomes would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and alternative nicotine format penetration rates. Cross-checking against convenience store scan data and manufacturer shipment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Organic Tobacco Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Middle East and Africa Smokeless Tobacco Market
Tobacco
Heat-Not-Burn Market
Tobacco
Cigarette Paper Market
Tobacco
North America Tobacco Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
Tobacco Films Market
Tobacco
Egypt Tobacco Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
US Tobacco Market