
 Heat-Not-Burn Market | 2026-2036
Heat-Not-Burn Market Size, Share, and Industry Trends Forecast 2026-2036
Heat-Not-Burn Market Intelligence
EU Tobacco Products Directive revision is recalibrating the cost-of-entry calculus for heat-not-burn manufacturers across European markets. Philip Morris International leverages its vertically integrated supply chain for tobacco sticks to sustain manufacturing scale advantages. British American Tobacco anchors its competitive position through R&D intensity in conduction heating architectures. Japan Tobacco International dominates its domestic market through decades of consumer trust and regulatory navigation.
Heat-not-burn systems heat processed tobacco to temperatures below combustion, typically between 300°C and 350°C, generating an inhalable aerosol with reduced pyrolytic byproducts compared to conventional cigarettes. The technology serves adult smokers seeking alternatives to combustible products while maintaining ritual and nicotine delivery. Tobacco sticks and heaters command the dominant product type positions, with smart devices representing the fastest-growing technology segment as Bluetooth connectivity and usage tracking reshape user engagement. Conduction heating occupies the mature core of installed devices, while hybrid systems capture emerging margin pools from consumers demanding customizable temperature profiles.
FDA premarket tobacco product application requirements, EU Tobacco Products Directive standards, and Japan's Ministry of Health, Labour and Welfare notification systems collectively shape product approval timelines, emissions testing protocols, and market access pathways across major jurisdictions. Regulatory divergence between permissive frameworks in some Asian markets and restrictive European disclosure mandates forces manufacturers to maintain parallel compliance infrastructures. Stakeholders must monitor pending flavor restriction proposals and taxation parity debates, as these policy trajectories will determine whether heat-not-burn products retain their cost advantage over combustible cigarettes in key markets.
Market Dynamics
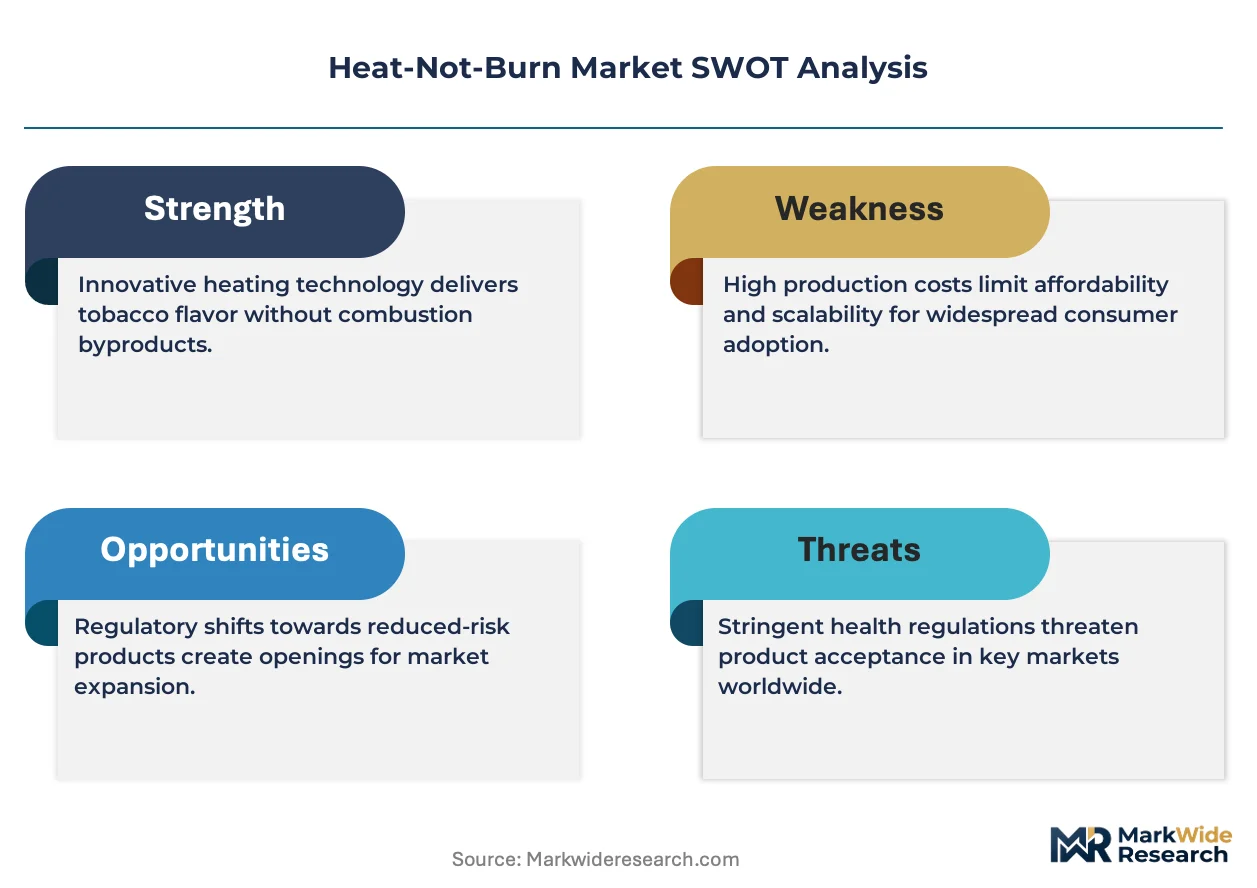
EU Tobacco Products Directive revision is compressing approval timelines while mandating granular emissions disclosure, forcing manufacturers to rebuild compliance architectures around aerosol constituent testing protocols.
Growth Catalysts
- Adult smoker transition from combustibles:Heat-not-burn systems retain ritual and nicotine delivery while reducing pyrolytic byproduct exposure, sustaining pull from established tobacco consumers in Japan and Italy.
- Bluetooth-enabled device connectivity:Smart heating systems with usage tracking and temperature customization are expanding user engagement metrics and reorder frequency through app-integrated ecosystems.
- Japan's Ministry of Health, Labour and Welfare notification pathway:Streamlined pre-market procedures for modified-risk tobacco products accelerate commercialization velocity relative to FDA premarket tobacco product application requirements.
Market Restraints
- Flavor restriction proposals:Pending menthol and characterizing flavor bans in multiple EU member states threaten product differentiation and user retention among adult smokers.
- Tobacco leaf supply concentration:Dependence on specific curing and processing facilities in Brazil and Zimbabwe creates input vulnerability during climate-induced harvest variability.
- Taxation parity debates:Legislative movements toward equalizing excise rates with combustible cigarettes erode the cost advantage that drives initial trial and switching economics.
Strategic Opportunities
- South Korea's underpenetrated non-urban markets:Provincial cities outside Seoul-Incheon corridor show latent demand for heated tobacco systems with limited retail saturation.
- Hybrid conduction-convection architectures:Convergence of precision temperature control with reduced heating-element degradation opens premium positioning above single-mechanism devices.
- Pharmacy and convenience store channel expansion:Regulatory acceptance in select European markets enables placement alongside smoking cessation products, normalizing heat-not-burn as transition tool.
Industry Challenges
- Aerosol chemistry expertise scarcity:Recruitment of toxicologists and analytical chemists capable of characterizing complex vapor-phase emissions lags behind testing mandate expansion.
- Parallel compliance infrastructure costs:Maintaining separate emissions testing protocols for FDA, EU TPD, and Japan MHLW requirements strains mid-scale manufacturers without captive laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat-Not-Burn Market |
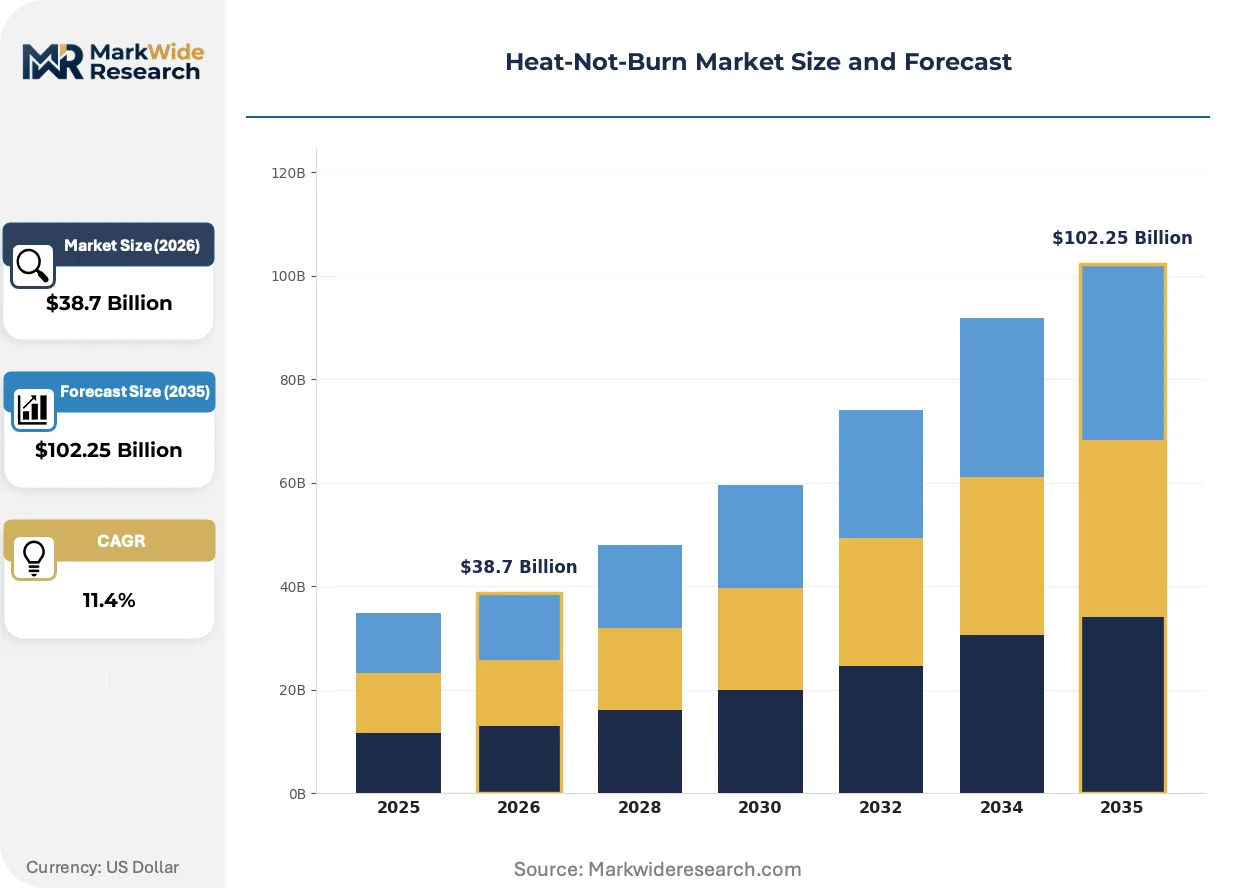
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarettes, Heaters, Tobacco Sticks, Accessories End User: Adult Smokers, Retailers, Distributors, Health-Conscious Consumers Distribution Channel: Online Retail, Convenience Stores, Supermarkets, Specialty Shops Technology: Conduction Heating, Convection Heating, Smart Devices, Hybrid Systems |
| Companies Covered | Philip Morris International, British American Tobacco, Japan Tobacco International, Altria Group, Imperial Brands, KT&G Corp., PAX Labs, China National Tobacco Corporation, Shenzhen Yukan Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat-Not-Burn Market Strategic Shifts & Innovations
Heat-not-burn technology trajectories center on precision thermal management, regulatory transparency mandates, and shifting procurement relationships between manufacturers and specialized component suppliers.
Hybrid heating architectures combining conduction and convection mechanisms are consolidating competitive positioning in the premium device segment. Adult smokers seeking granular control over aerosol density and temperature curves are migrating toward these systems at accelerating rates. This consolidation is compressing margins for single-mechanism devices while rewarding R&D investment in multi-mode thermal engineering.
EU Tobacco Products Directive emissions disclosure mandates are forcing component-level transparency across supply chains. Manufacturers must now document and report specific aerosol constituents including carbonyl compounds and volatile organic compounds to national regulators. Heated tobacco stick producers are responding by vertically integrating filter and substrate production to control data lineage and testing consistency.
Specialized procurement of ceramic heating elements and precision temperature sensors is shifting toward long-term supply agreements with dedicated electronics manufacturers. Distributors previously serving multiple vaping device categories are narrowing supplier relationships to secure allocation priority during component shortages. This concentration is most visible in Japan and South Korea, where device refresh cycles have compressed below twenty-four months.
Heat-Not-Burn Market Segmentation
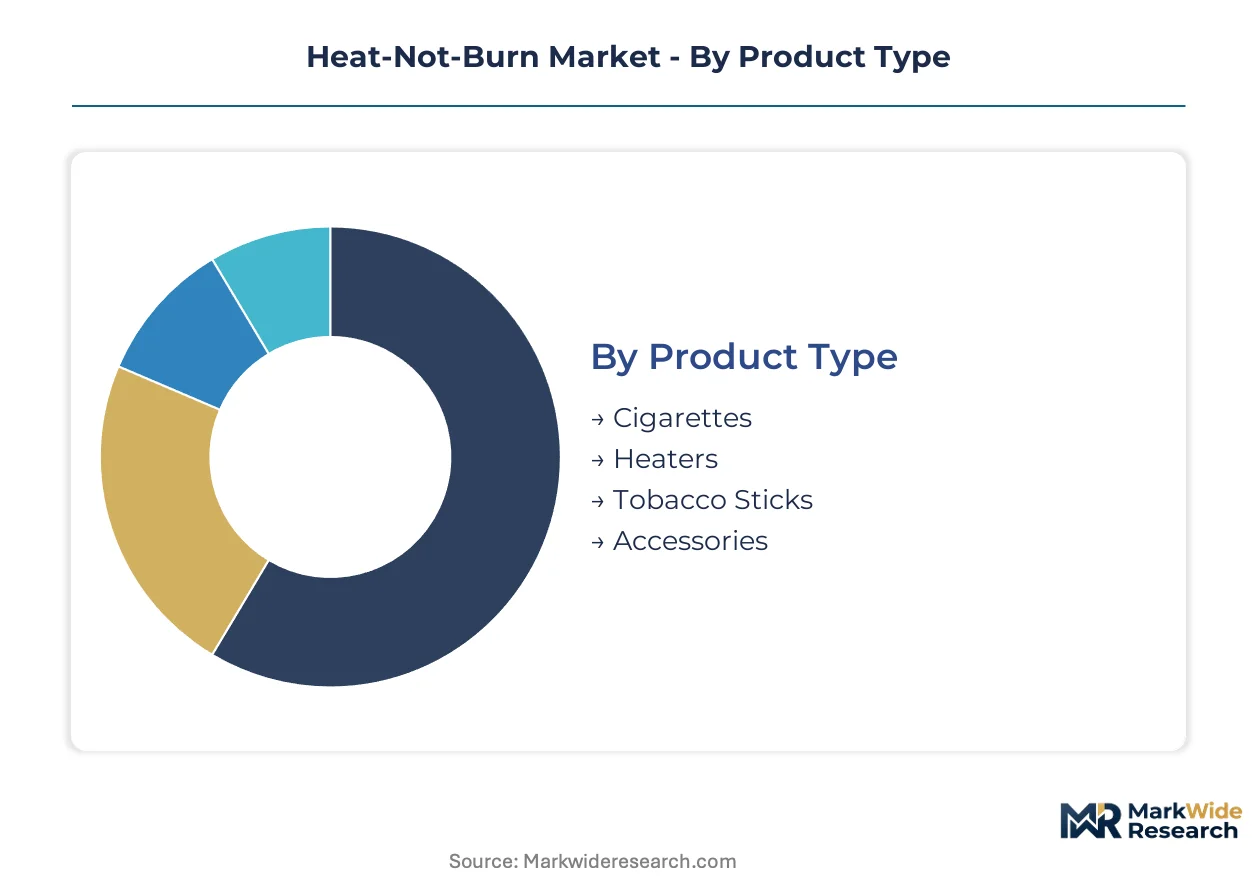
Segmentation in the Heat-Not-Burn Market reveals how product architecture, user profiles, and channel economics create distinct competitive battlegrounds. Manufacturers must align R&D investment, regulatory compliance, and distribution strategy to the specific requirements of each segment cluster.
Product Type:
Standalone consumables dominate recurring revenue streams, while integrated hardware systems lock in platform loyalty through proprietary formats.
- Cigarettes:Combustible tobacco products remain the reference point for switching economics and taxation benchmarks. Adult smokers in Italy and Japan evaluate heat-not-burn alternatives against cigarette ritual fidelity and per-use cost differentials.
- Heaters:Electronic heating devices with precision temperature control and rechargeable power systems constitute the core hardware investment. Demand concentrates in device refresh cycles below twenty-four months in Japan and South Korea, driven by METI energy efficiency standards and consumer appetite for connectivity features.
- Tobacco Sticks:Proprietary consumables with processed tobacco substrates and engineered filters.
- Accessories:Charging cases, cleaning kits, and protective sleeves.
Volume placements concentrate in Tobacco Sticks; the faster expansion belongs to Heaters.
End User:
Customer archetypes span from nicotine-dependent adults seeking harm reduction to institutional buyers managing inventory complexity across regulated categories.
- Adult Smokers:Nicotine-dependent consumers transitioning from combustible products. Japan's Ministry of Health, Labour and Welfare notification pathway accelerates product access relative to FDA timelines, concentrating trial behavior in Japanese metropolitan clusters.
- Health-Conscious Consumers:Adults prioritizing reduced pyrolytic byproduct exposure over nicotine cessation. Demand clusters in EU markets with stringent emissions disclosure mandates under revised Tobacco Products Directive standards.
- Retailers:Convenience store and pharmacy operators seeking category margin expansion.
- Distributors:Wholesale intermediaries managing cold-chain logistics and excise compliance.
Adult Smokers anchor volume throughput; Health-Conscious Consumers are climbing the fastest.
Distribution Channel:
Channel selection determines regulatory exposure, price transparency, and consumer education intensity.
- Convenience Stores:High-frequency retail locations with established tobacco category presence. South Korea's provincial cities outside Seoul-Incheon corridor show latent demand with limited saturation, creating whitespace for placement expansion.
- Specialty Shops:Dedicated vaping and reduced-risk product retailers with trained staff. European pharmacy channel acceptance in select markets enables positioning alongside smoking cessation products, normalizing heat-not-burn as transition tools.
- Online Retail:Direct-to-consumer platforms with age verification requirements.
- Supermarkets:Mass retail with broad demographic reach and standardized merchandising.
Convenience Stores capture the highest transaction velocity; Specialty Shops gain share fastest through education-intensive consultation.
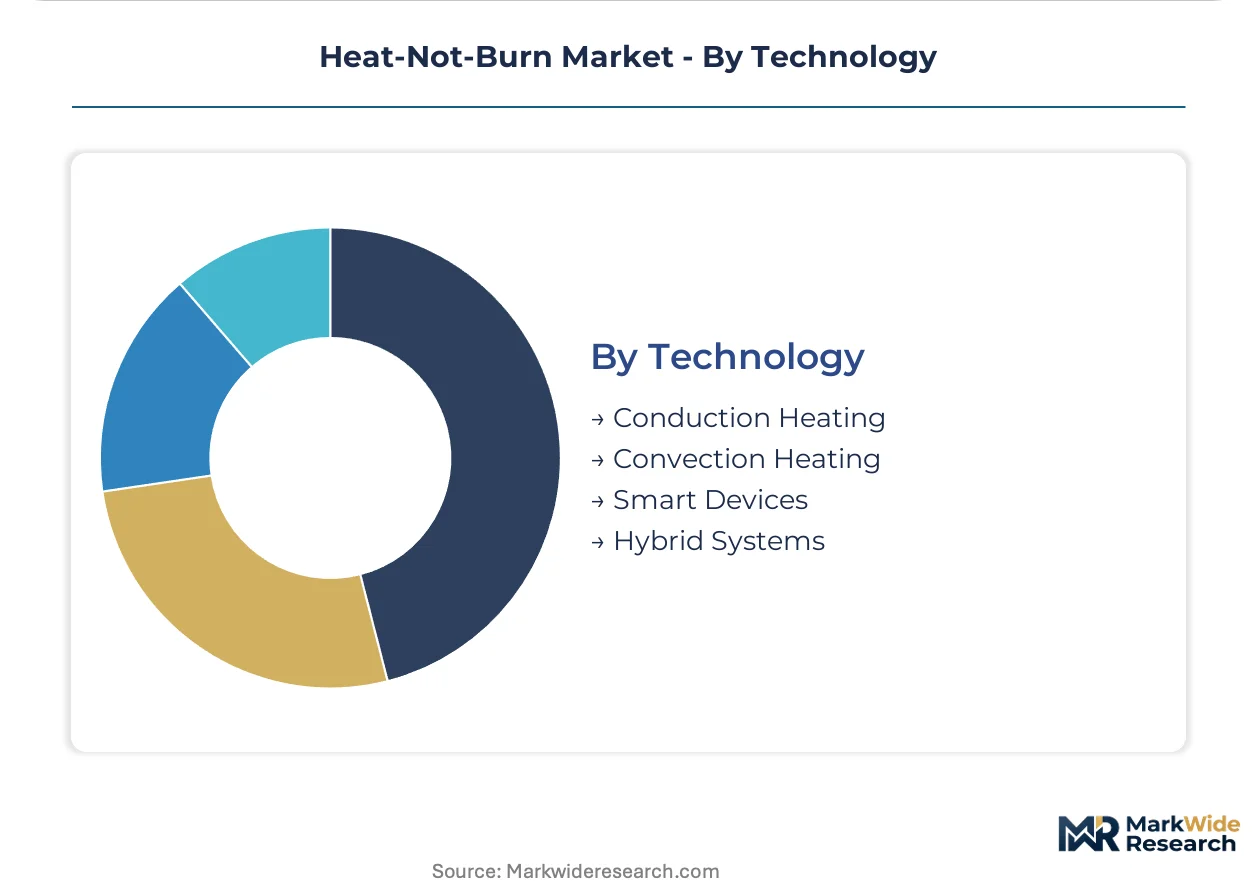
Technology:
Thermal engineering architectures differentiate user control precision, heating-element durability, and aerosol consistency.
- Conduction Heating:Direct contact between heating element and tobacco substrate. This mature technology occupies the installed base core in Japan, where early adoption established conduction as the default mechanism.
- Hybrid Systems:Combined conduction-convection architectures with customizable temperature profiles. Precision control capabilities are expanding margin pools in premium device tiers as users demand granular aerosol density modulation.
- Convection Heating:Hot air circulation without direct element contact.
- Smart Devices:Bluetooth-enabled systems with usage tracking and app integration.
Conduction Heating retains the largest installed footprint; Hybrid Systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates the highest per-capita demand for heated tobacco systems, with Italy and South Korea forming secondary demand poles. Adult smoker transition rates and regulatory pathway efficiency determine geographic expansion velocity across these markets.
Japan
Metropolitan Tokyo and Osaka clusters drive device refresh cycles below twenty-four months through consumer appetite for connectivity features. METI energy efficiency standards compress hardware replacement timelines while accelerating smart device adoption. The Ministry of Health, Labour and Welfare notification pathway streamlines pre-market procedures, concentrating commercialization velocity in Kanto and Kansai regions.
South Korea
Provincial cities outside the Seoul-Incheon corridor exhibit latent demand with limited retail saturation for heated tobacco systems. MFDS notification requirements shape product approval timelines distinct from FDA or EU pathways. Daegu-Gyeongbuk and Busan-Ulsan industrial zones host electronics manufacturers supplying precision temperature sensors and ceramic heating elements.
Italy
Adult smokers in Lombardy and Piedmont evaluate heat-not-burn alternatives against cigarette ritual fidelity and per-use cost differentials. EU Tobacco Products Directive emissions disclosure mandates force granular aerosol constituent testing for market access. Milan-Turin corridor retailers position heated tobacco alongside smoking cessation products, normalizing transition tool positioning.
Germany
Health-conscious consumers in Bavaria and North Rhine-Westphalia prioritize reduced pyrolytic byproduct exposure over nicotine cessation. BfR (Federal Institute for Risk Assessment) evaluation protocols influence product formulation decisions for German market entry. Munich and Cologne pharmacy channel acceptance enables placement expansion alongside regulated nicotine replacement therapies.
United States
FDA premarket tobacco product application requirements extend approval timelines relative to Asian regulatory pathways, compressing commercialization velocity. Adult smoker trial behavior concentrates in metropolitan clusters with established reduced-risk product retail infrastructure. California and New York state-level flavor restriction debates create compliance uncertainty for national product portfolio planning.
Heat-Not-Burn Market Key Industry Players
Swiss-American producers anchor the premium device tier; South Korean specialists hold mid-market positioning through component supply relationships. The vendor structure concentrates around vertically integrated tobacco conglomerates with captive consumable formats, while electronics fabricators compete on heating element precision and connectivity integration. Three archetypes dominate: integrated tobacco-heating platforms, standalone device manufacturers, and specialized component suppliers. Capacity expansion in ceramic heating element production and strategic partnerships for aerosol chemistry expertise represent the dominant competitive moves.
Among integrated platform operators, Philip Morris International, British American Tobacco, and Japan Tobacco International exemplify the vertically consolidated archetype. Philip Morris International occupies a position defined by captive tobacco stick supply chains. British American Tobacco sits within the R&D-intensive tier for thermal engineering architectures. Japan Tobacco International anchors its competitive stance through domestic market density and regulatory navigation experience. These three entities collectively represent the scale-driven end of competitive positioning, with their geographic origins and corporate structures reflecting decades of tobacco industry consolidation.
| Leading Market Players |
|---|
| Philip Morris International |
| British American Tobacco |
| Japan Tobacco International |
| Altria Group |
| Imperial Brands |
| KT&G Corp. |
| PAX Labs |
| China National Tobacco Corporation |
| Shenzhen Yukan Technology |
| Others |
Cost & Logistics Intelligence
Hybrid conduction-convection heating architectures are compressing cost curves while concentrating procurement leverage among precision electronics suppliers in Japan and South Korea. This technology shift simultaneously elevates R&D amortization burdens and reshapes supplier tiering as ceramic heating element fabrication migrates toward dedicated contract manufacturers.
Pricing Analysis
Volume placements in tobacco sticks run on thin per-unit margins, while hardware heaters capture wider spreads through Bluetooth connectivity and temperature customization features. Price differentiation hinges on METI energy efficiency certification tiers and proprietary consumable lock-in. Cost compression in mid-tier devices is intensifying because South Korean electronics suppliers are scaling ceramic element production. Price-sensitive provincial retailers in South Korea's secondary cities resist premium positioning, whereas Tokyo metropolitan consumers absorb connectivity-enabled hardware premiums.
Supply Chain Analysis
Japan's local-content thresholds for modified-risk tobacco product notifications are redirecting sourcing toward domestic filter substrate producers. Manufacturing gravity centers on Japan, South Korea, and Italy for final device assembly, with precision temperature sensors and ceramic heating elements feeding from Daegu-Gyeongbuk industrial zones. Raw material dependencies include cured tobacco leaf from Brazil and Zimbabwe, engineered cellulose acetate for filters, and lithium-ion power cells. Single-source vulnerability concentrates in Brazilian leaf supply during climate-induced harvest variability. Distribution runs through convenience store chains with established tobacco category presence and pharmacy channels in select European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heat-not-burn market sits in a technology-transition phase as hybrid heating systems displace pure conduction architectures. Smart device connectivity with app-integrated usage tracking is replacing legacy standalone heaters.
For Market Incumbents: Anchor platform loyalty through proprietary tobacco stick formats that lock consumable replenishment. Deepen backward integration into ceramic heating element production to defend margin position against South Korean electronics suppliers. Prioritize R&D investment in aerosol chemistry expertise to meet EU Tobacco Products Directive emissions disclosure mandates. Channel control through pharmacy placement alongside smoking cessation products offers defensive positioning against flavor restriction proposals.
For New Entrants and Emerging Players: Direct-to-consumer digital channels with age-verified subscription models offer white-space entry around incumbent retail saturation. Target South Korea's provincial cities outside the Seoul-Incheon corridor where heated tobacco retail penetration remains limited. Pharmacy channel partnerships in Germany and Italy provide education-intensive consultation positioning that bypasses convenience store slotting fee barriers. Emphasize health-conscious consumer segmentation with granular emissions transparency to differentiate from established tobacco-heating platforms.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated tobacco conglomerates seeking captive consumable formats. Long-term viability hinges on regulatory navigation capabilities across FDA, EU TPD, and Japan MHLW compliance pathways. Acquisition target archetype: mid-scale manufacturers with captive laboratory capacity for aerosol constituent testing. The signal to watch is legislative movement toward taxation parity with combustible cigarettes, which would compress switching economics and reshape category growth trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Heating Architecture R&D | Precision temperature control captures premium device margins above single-mechanism competitors. |
| Proprietary Tobacco Stick Format | Consumable lock-in secures recurring revenue streams and defends against generic alternatives. |
| Aerosol Chemistry Laboratory Investment | In-house testing capacity satisfies EU TPD, FDA, and Japan MHLW parallel compliance requirements. |
| Pharmacy Channel Expansion | Placement alongside smoking cessation products normalizes heat-not-burn as transition tools in European markets. |
| Bluetooth Connectivity Integration | App-integrated usage tracking elevates user engagement metrics and accelerates device refresh cycles. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with heat-not-burn device engineering directors, tobacco procurement managers at integrated manufacturers, pharmacy category buyers, and convenience store tobacco category managers combined with FDA premarket tobacco product application databases, EU TPD emissions disclosure filings, and Japan MHLW notification records. Bottom-up device shipment and consumable volume estimates triangulated against top-down market value reconstruction across the analysis window.
Data-stream reconciliation between manufacturer-reported device activations and retail audit scan data shaped the forecast framework. Segmentation dimensions modeled include product type, heating technology architecture, distribution channel, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical adoption curves and smoker transition elasticity estimates. Industry-specific inputs incorporated METI energy efficiency standard compliance timelines and flavor restriction proposal legislative tracking.
The model holds under stable regulatory pathways across FDA, EU TPD, and Japan MHLW jurisdictions; deviation in taxation parity legislation or menthol ban implementation would shift commercialization velocity assumptions. Forecasts reflect documented assumptions regarding adult smoker transition rates and device refresh cycle compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Tobacco Films Market
Tobacco
North America Tobacco Market
Tobacco
US Tobacco Market
Tobacco
Cigarette Paper Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Middle East and Africa Smokeless Tobacco Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
Egypt Tobacco Market
Tobacco
North America Cigarette Market
Tobacco
Organic Tobacco Market