
 US Tobacco Market | 2026-2036
US Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
US Tobacco Market Intelligence
The divergence in research and development investment for next-generation products versus manufacturing scale for traditional cigarettes is bifurcating the competitive landscape. Altria Group leverages its extensive distribution network for combustible products. Reynolds American competes through its portfolio diversification into both traditional and modern oral nicotine formats. Juul Labs specializes in the electronic nicotine delivery systems category, focusing on device technology and navigating specific regulatory hurdles.
Tobacco products encompass items derived from the cured leaves of the Nicotiana plant, processed for smoking, chewing, or inhalation. These products are defined by their nicotine content, leaf blend, and curing method, such as flue-curing for cigarettes or air-curing for cigars. While the cigarettes segment remains the largest by value, e-cigarettes represent the fastest-growing product category. Distribution remains dominated by convenience stores and other physical retail stores, though online sales are gaining traction for specific smokeless products.
The Food and Drug Administration (FDA) holds primary regulatory authority, setting product standards and marketing restrictions through the Tobacco Control Act. The Federal Trade Commission (FTC) monitors and reports on industry marketing and sales practices. These regulations directly influence product innovation, particularly concerning flavored products and nicotine levels. Stakeholder success depends on navigating the evolving regulatory pathways for reduced-risk product authorizations.
Market Dynamics
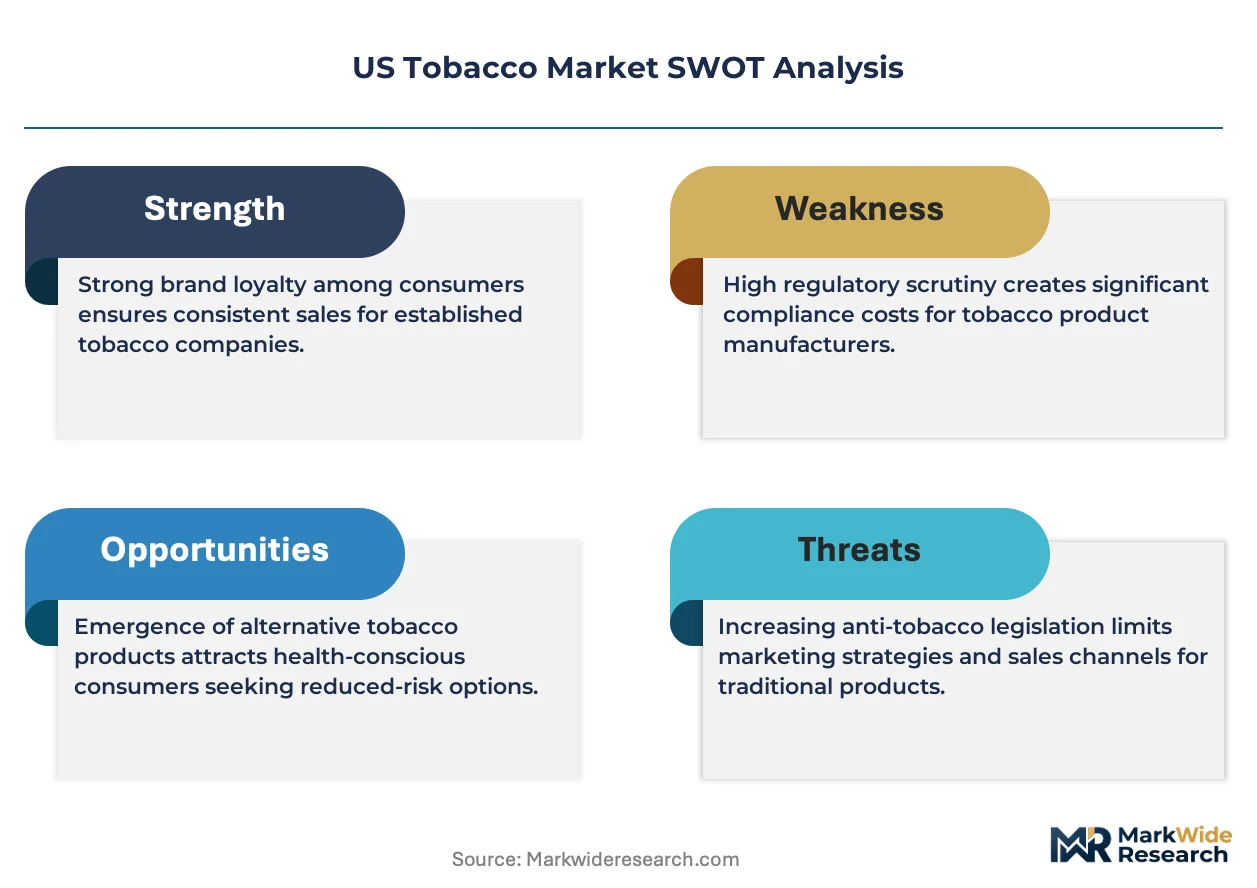
The primary structural force is the regulatory framework established by the Food and Drug Administration, which dictates pathways for product innovation and marketing. This pressure shapes all strategic decisions, from research investment to distribution tactics for new and legacy products.
Growth Catalysts
- Modern Oral Nicotine:Adoption of smoke-free, spit-free nicotine pouches by adult consumers seeking discreet alternatives drives new demand.
- Premium Cigar Demand:Concentrated demand in states like Florida for premium cigars provides a resilient, high-margin niche.
- Online Channel Growth:The expansion of e-commerce for certain smokeless and modern oral products bypasses traditional retail limitations.
Market Restraints
- FDA Premarket Review:The lengthy and costly Premarket Tobacco Product Application (PMTA) process is a significant barrier to entry for new products.
- Marketing Restrictions:Strict regulations from the FDA and monitoring by the FTC on advertising limit communication with adult consumers.
- Excise Tax Complexity:A rising patchwork of state and local excise taxes on vapor and oral nicotine products compresses margins.
Strategic Opportunities
- Reduced-Risk Authorization:Securing a Modified Risk Tobacco Product (MRTP) order from the FDA provides a powerful marketing advantage.
- Targeted Adult Segments:Developing products for specific adult smoker demographics currently underserved by non-combustible alternatives presents a growth avenue.
- Synthetic Nicotine:Formulations using non-tobacco-derived nicotine may create new product categories, navigating some existing regulatory frameworks.
Industry Challenges
- Flavor Ban Compliance:Adapting product portfolios and supply chains to a shifting landscape of federal, state, and local prohibitions on flavored tobacco products is a constant challenge.
- Litigation Exposure:The industry faces persistent and costly legal challenges from state attorneys general and class-action lawsuits concerning marketing and health impacts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Tobacco Market |
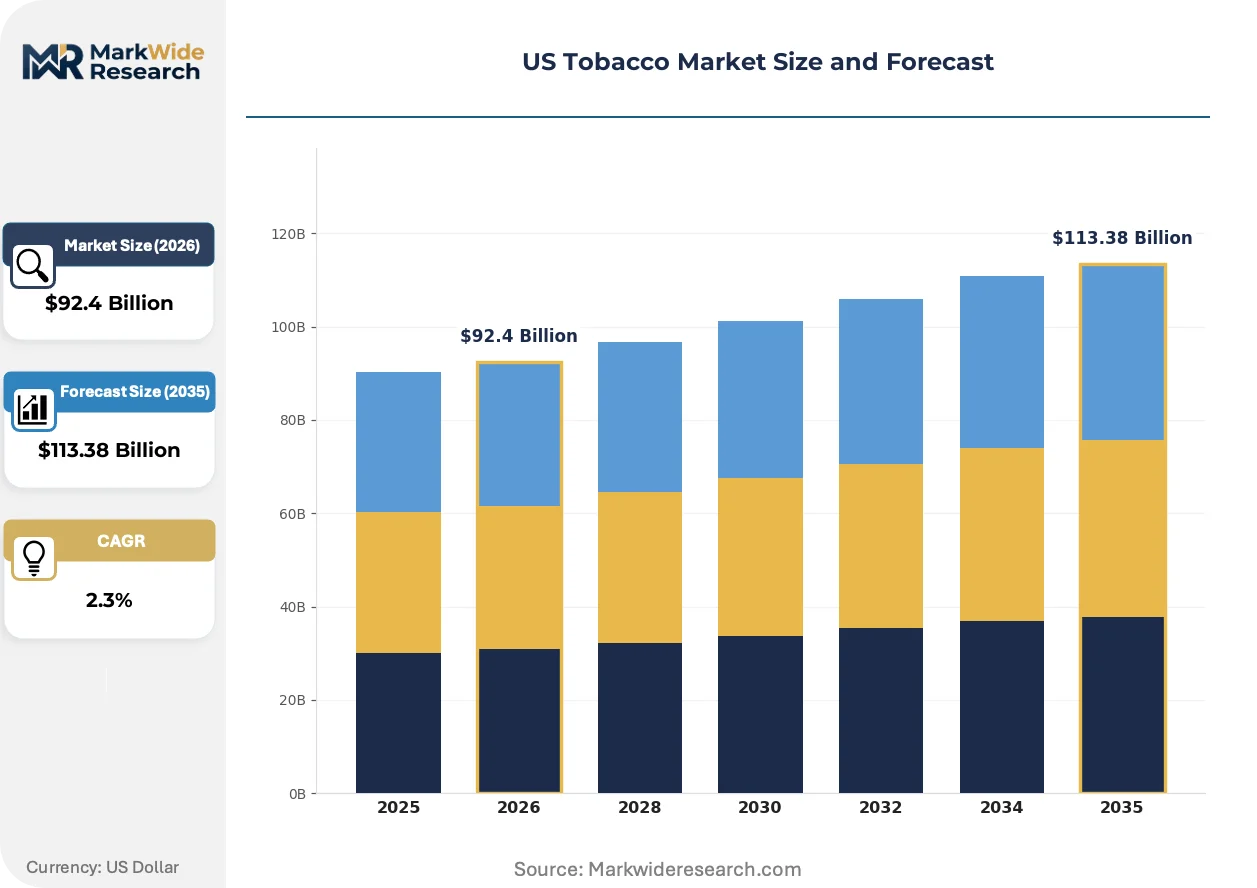
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $113.38 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarettes, Cigars, Smokeless Tobacco, E-cigarettes Distribution Channel: Retail Stores, Online Sales, Convenience Stores, Vending Machines Consumer Type: Adults, Teenagers, Occasional Users, Regular Users Form: Traditional, Premium, Filtered, Flavored |
| Companies Covered | Altria Group, Reynolds American, Philip Morris USA, Juul Labs, U.S. Smokeless Tobacco, American Snuff Company, Turning Point Brands, Universal Corporation, Swedish Match, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Tobacco Market Strategic Shifts & Innovations
The US tobacco market is defined by a fundamental divergence between the managed decline of combustible products and the rapid evolution of next-generation nicotine delivery systems. Regulatory actions and consumer health consciousness are the primary catalysts for this market split.
Advanced nicotine salt chemistry in e-liquids delivers nicotine more efficiently than earlier freebase formulations. Adult smokers transitioning from combustible cigarettes are the primary adopters of these closed-pod and disposable systems. This technology is bifurcating the e-cigarette category, creating a distinct high-potency segment that faces heightened regulatory scrutiny compared to open-system vaping devices.
FDA authority under the Tobacco Control Act to mandate product standards, including potential nicotine reductions, is a central regulatory trend. This power compels investment in research for very low nicotine content (VLNC) cigarettes and other alternative designs. The combustible cigarette segment is most affected, facing a future where its core product characteristics could be fundamentally altered by federal mandate.
Consumer purchasing behavior is shifting from brand-centric loyalty in cigarettes to feature-driven selection in modern nicotine categories. This change disrupts traditional mass-media marketing, favoring product attributes like device form factor, battery life, and nicotine pouch strength. This pattern is most pronounced in urban markets where a diverse retail environment of vape shops and convenience stores fosters direct product comparison.
US Tobacco Market Segmentation
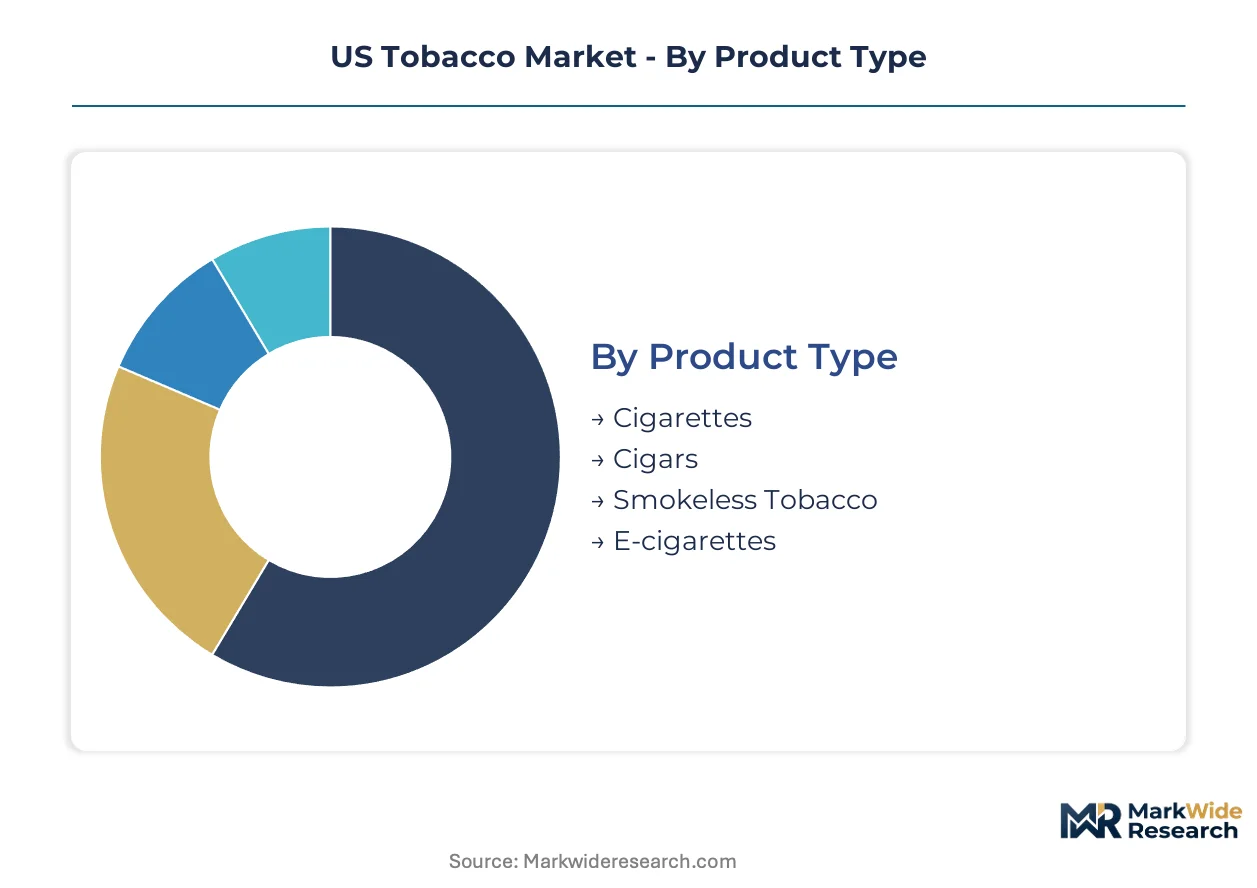
Understanding the US tobacco market's segmentation is critical for strategic planning, revealing distinct consumer preferences and regulatory impacts across product types. This granular view helps stakeholders identify pockets of demand and tailor product development to specific distribution channels. Effective segmentation illuminates where growth is occurring and where traditional segments face managed decline.
Product Type:
The geographic spread of product consumption varies significantly across the United States, with certain product types showing regional concentration. This reflects diverse cultural preferences and state-specific regulatory environments.
- Cigarettes:These combustible products, primarily flue-cured tobacco, remain the largest segment by value, despite declining consumption trends. Demand concentrates in states with less stringent regulations and lower excise taxes, particularly in the Southeast.
- E-cigarettes:Electronic nicotine delivery systems vaporize e-liquids, often containing nicotine salts, offering a smoke-free alternative. This category shows rapid expansion, particularly among adult consumers in urban markets seeking discreet and feature-driven products.
- Cigars:Products made from air-cured tobacco leaves, often hand-rolled, cater to a niche market. Premium cigar demand is notably concentrated in states like Florida and Texas, driven by specific consumer demographics.
- Smokeless Tobacco:This category includes chewing tobacco, snus, and modern oral nicotine pouches, consumed without combustion. Demand for these products is prevalent in regions with traditional tobacco use and among those seeking spit-free options.
Cigarettes commands the established base. The steepest expansion runs through E-cigarettes.
Distribution Channel:
The volume of tobacco products moved through various distribution channels reflects established consumer purchasing habits and evolving retail landscapes. Traditional channels still handle the majority of transactions, but digital platforms are gaining ground.
- Retail Stores:This broad category encompasses supermarkets, gas stations, and dedicated tobacco shops, serving as the primary point of sale for most tobacco products. These physical locations benefit from high foot traffic and immediate product availability across the US.
- Online Sales:E-commerce platforms facilitate direct-to-consumer purchases, particularly for smokeless and modern oral nicotine products, bypassing some traditional retail limitations. This channel is expanding quickly, offering convenience and broader product selection to adult consumers.
- Convenience Stores:These ubiquitous outlets are critical for impulse purchases and quick access to combustible cigarettes and some smokeless products. They dominate the traditional tobacco distribution landscape across American towns and cities.
- Vending Machines:Historically used for cigarette sales, their prevalence has significantly declined due to age verification laws and increased regulatory scrutiny. This channel now represents a minimal portion of the market.
Physical Retail Stores continue to account for the largest sales volume. However, Online Sales are experiencing the most dynamic growth.
Consumer Type:
The maturity of different consumer segments dictates product development and marketing strategies within the US tobacco market. Established adult users form the foundation, while evolving preferences among various groups drive innovation.
- Adults:This demographic, comprising individuals 21 years and older, represents the legal and primary consumer base for all tobacco and nicotine products in the United States. Their shifting demand towards e-cigarettes and modern oral nicotine products influences market trends and product diversification.
- Regular Users:These consumers exhibit consistent purchasing patterns and brand loyalty for their preferred tobacco or nicotine products, whether combustible or next-generation. They provide a stable revenue stream and are often targeted for product retention strategies.
- Teenagers:Individuals under the legal purchasing age, their consumption is heavily restricted and closely monitored by regulatory bodies like the FDA. Efforts to prevent underage use of nicotine products are a significant focus for public health and industry compliance.
- Occasional Users:These consumers use tobacco or nicotine products intermittently, often in social settings or during specific activities. Their purchasing behavior is less predictable and can be influenced by product availability and social trends.
Adults form the fundamental demand base for the industry. Regular Users ensure consistent market volume.
Form:
The application of various product forms dictates their appeal to different consumer preferences and their susceptibility to evolving regulatory standards across the US. This influences product design and market positioning.
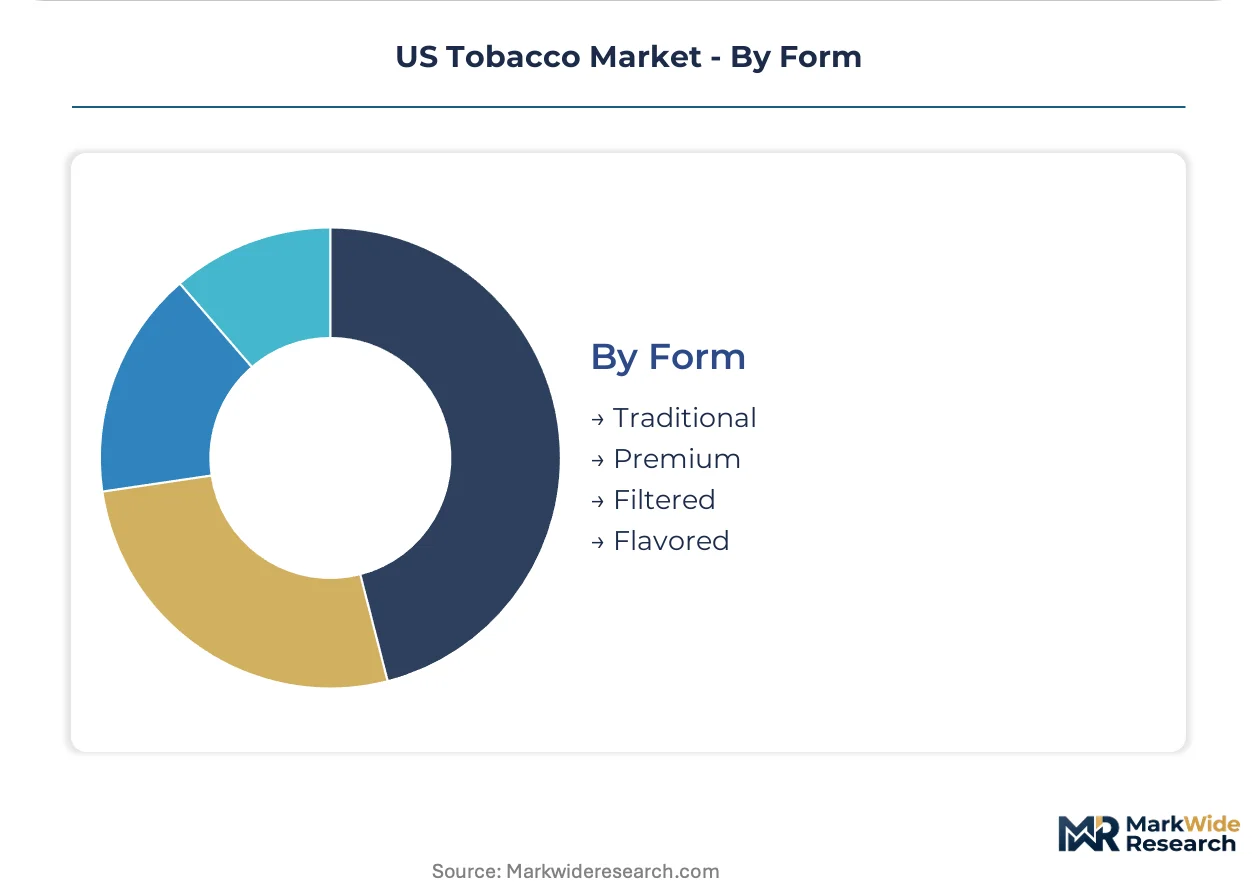
- Traditional:This form encompasses conventional combustible cigarettes and some forms of smokeless tobacco, characterized by their established manufacturing processes and historical consumer base. These products face managed decline and heightened regulatory scrutiny from the FDA.
- Flavored:Products incorporating flavors beyond tobacco or menthol, such as fruit or dessert profiles, are popular in e-cigarettes and modern oral nicotine pouches. These forms face significant federal, state, and local flavor ban compliance challenges, impacting their market availability.
- Premium:This designation applies to higher-priced products, often associated with cigars or specialty tobacco blends, emphasizing quality ingredients and craftsmanship. Premium offerings cater to discerning consumers willing to pay more for perceived superior experience.
- Filtered:Primarily referring to cigarettes equipped with a filter at the mouth end, this design aims to reduce the harshness of smoke inhalation. Filtered cigarettes remain the dominant format within the combustible segment due to consumer preference.
Traditional forms maintain the largest market presence. However, Flavored products are a key area for both consumer appeal and regulatory focus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for tobacco products varies across the United States, with some consumers highly sensitive to price changes while others prioritize premium experiences. States with lower excise taxes often see higher consumption of traditional combustible products. Conversely, regions with affluent demographics drive demand for higher-margin premium cigars and modern oral nicotine alternatives.
Florida
Florida exhibits strong demand for premium cigars, driven by its affluent coastal communities and tourist markets. The state's relatively favorable regulatory environment for cigars supports this niche. Miami and Tampa serve as key distribution hubs, facilitating access to specialty retailers and lounges.
Texas
Texas shows significant consumption of smokeless tobacco and premium cigars, reflecting its diverse consumer base and cultural preferences. The Federal Trade Commission monitors marketing practices across the state. Major urban centers like Houston and Dallas concentrate distribution networks for both traditional and modern nicotine products.
New York Metro
New York Metro consumers increasingly adopt e-cigarettes and modern oral nicotine products, driven by health consciousness and discreet usage preferences. New York State's strict flavor bans profoundly influence product availability and consumer choices. Manhattan's dense retail environment fosters rapid uptake of innovative reduced-risk alternatives.
Southeast
The broader Southeast region maintains a substantial base for traditional combustible cigarettes, often due to lower excise taxes and established purchasing habits. The Food and Drug Administration's evolving product standards impact manufacturers operating in this area. Atlanta and Charlotte act as logistical centers for extensive distribution of conventional tobacco products.
US Tobacco Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the US tobacco market, reflecting a bifurcated industry structure. Large incumbents focus on managing the decline of traditional products while investing in next-generation alternatives. Archetypes include diversified tobacco giants, specialized e-vapor innovators, and niche premium cigar players. Strategic moves involve portfolio diversification and navigating complex regulatory pathways.
Within the diversified tobacco giants archetype, Altria Group and Reynolds American exemplify established market presence and extensive distribution networks. Altria Group, Inc. and Reynolds American Inc. maintain significant market share in combustible products while strategically expanding into modern oral nicotine formats. Juul Labs, Inc. occupies a position as a specialized e-vapor innovator, focusing on device technology and navigating specific regulatory hurdles within the electronic nicotine delivery systems category.
| Leading Market Players |
|---|
| Altria Group |
| Reynolds American |
| Philip Morris USA |
| Juul Labs |
| U.S. Smokeless Tobacco |
| American Snuff Company |
| Turning Point Brands |
| Universal Corporation |
| Swedish Match |
| Others |
Cost & Logistics Intelligence
FDA premarket review processes gate both product supply qualification and subsequent price differentiation for novel nicotine products. This regulatory framework significantly influences investment returns and market access.
Pricing Analysis
Recurring e-liquid and pod sales drive a significant after-sales revenue stream for electronic nicotine delivery systems. The market primarily uses a per-unit transactional pricing model, with premium offerings in cigars and next-generation products commanding higher prices. Price differentiation stems from product innovation, regulatory compliance, and brand equity. Pricing pressure intensifies for traditional combustible products due to declining demand and rising excise taxes. Adult consumers of premium cigars exhibit lower price sensitivity compared to those purchasing value-tier cigarettes.
Supply Chain Analysis
The United States anchors tobacco leaf cultivation and significant manufacturing capacity for traditional products. Raw material dependencies include flue-cured tobacco leaf, synthetic nicotine, and specialized e-cigarette hardware components. Supply chain risk arises from evolving federal and state regulatory restrictions, particularly concerning flavor bans and import controls. Distribution runs through a dual model, with physical retail stores dominating for combustibles and online channels gaining traction for modern oral nicotine products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US tobacco market is experiencing an early-cycle expansion story, driven by the rapid adoption and penetration of modern oral nicotine products. This shift reflects evolving adult consumer preferences for reduced-risk alternatives.
For Market Incumbents: Fortify existing distribution networks for combustible products while aggressively investing in next-generation nicotine delivery systems. Secure Modified Risk Tobacco Product (MRTP) authorizations from the FDA to counter the managed decline of traditional segments. This strategy addresses the threat of market share erosion from specialized e-vapor innovators. Prioritize research and development for very low nicotine content (VLNC) cigarettes.
For New Entrants and Emerging Players: Modified Risk Tobacco Product (MRTP) applications offer a certification fast-track for market entry and differentiation. Target underserved adult smoker demographics seeking non-combustible alternatives, particularly within urban markets. Develop synthetic nicotine formulations to navigate some existing regulatory frameworks. Leverage direct-to-consumer online sales platforms for efficient market penetration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the modern oral nicotine and e-cigarette sub-segments, signaling significant growth potential. The long-term viability favors companies with robust regulatory compliance and diversified reduced-risk product portfolios. Target acquisition profiles include specialized e-vapor innovators or firms with strong intellectual property in nicotine salt chemistry. The signal to watch is the pace of FDA Premarket Tobacco Product Application (PMTA) approvals for novel products.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Shifts revenue streams from declining combustible products to growing next-generation nicotine alternatives. |
| Regulatory Authorization Pursuit | Secures market access and marketing advantages through FDA Premarket Tobacco Product Application (PMTA) and MRTP orders. |
| E-commerce Channel Expansion | Reaches adult consumers for specific smokeless and modern oral nicotine products, bypassing traditional retail limitations. |
| Synthetic Nicotine Research & Development | Creates new product categories and potentially navigates some existing tobacco-derived nicotine regulations. |
| Targeted Adult Segment Development | Addresses specific adult smoker demographics currently underserved by non-combustible alternatives for market growth. |
Research Approach
A spread of perspectives from tobacco company executives, regulatory affairs specialists, retail channel partners, and public health officials converged on the working assumptions for this analysis. This involved combining primary interviews with extensive secondary data validation from FDA filings, FTC reports, and industry association publications. Bottom-up market sizing was triangulated against top-down industry revenue figures.
Product type, distribution channel, consumer type, and product form constituted the segmentation dimensions modeled across the analysis window. The analytical framework incorporated historical trends, evolving regulatory impacts, and consumer preference shifts to derive compound annual growth rates. Key industry-specific forecast inputs included federal and state-level nicotine content regulations and flavor ban implementation timelines.
Decision-makers should treat outputs as directional under current regulatory enforcement and projected consumer transition rates; material deviation would warrant model refresh. Unforeseen federal flavor bans, new excise tax implementations, or significant litigation outcomes represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Tobacco Cutting Machines Market
Tobacco
Cigarette Paper Market
Tobacco
Tobacco Films Market
Tobacco
North America Cigarette Market
Tobacco
Heat-Not-Burn Market
Tobacco
Egypt Tobacco Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
Middle East and Africa Smokeless Tobacco Market
Tobacco
Organic Tobacco Market
Tobacco
North America Tobacco Market