
 Middle East and Africa Smokeless Tobacco Market | 2026-2036
Middle East and Africa Smokeless Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Smokeless Tobacco Market Foresight
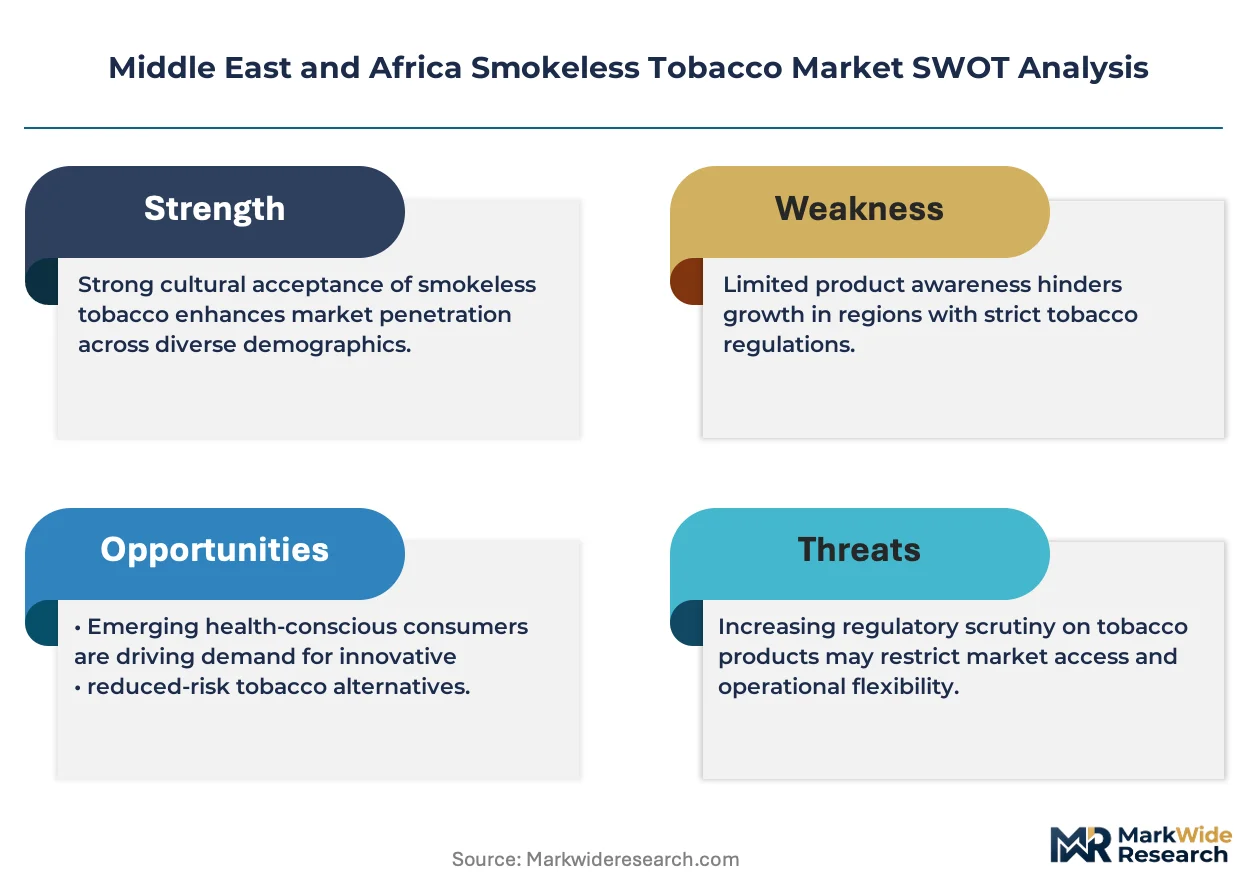
The EU Green Deal is hardening sustainability benchmarks that regional exporters must meet to maintain access to European-adjacent markets, reshaping sourcing and packaging protocols across North African supply corridors. Orchid Tobacco Dubai leverages its Gulf logistics hub to sustain distribution reach across Levant and Horn of Africa territories. British American Tobacco Plc anchors its regional portfolio through established moist snuff formulations, while Swedish Match AB specializes in reduced-risk product narratives that differentiate its offering in emerging urban markets.
Middle East and Africa smokeless tobacco encompasses orally consumed, non-combusted tobacco products including moist and dry snuff, chewing tobacco, and dissolvable formats, typically containing cured leaf material with moisture content ranging from 15% to 50% depending on processing method, designed to deliver nicotine through buccal absorption without pyrolysis. Moist snuff dominates volume throughput across convenience store channels where chilled storage infrastructure supports product integrity, while dissolvable tobacco occupies the fastest-expanding margin pool among former smokers seeking discrete consumption formats. Chewing tobacco maintains entrenched demand in traditional retail settings across East African markets, though flavored variants particularly mint and spiced profiles are capturing shelf space in Gulf specialty shops.
South Africa's national health regulator enforces strict oral tobacco labeling requirements that constrain marketing vocabulary and mandate addiction warnings, while Saudi Arabia's SFDA maintains import licensing protocols that filter product origin and composition standards. The UAE's MOHAP coordinates with Gulf standardization bodies to harmonize tar and nicotine disclosure thresholds across member states, tightening market access for non-compliant suppliers. Stakeholders must monitor evolving excise tax structures and plain-packaging proposals across key African markets where fiscal policy increasingly substitutes for direct consumption bans.
Market Dynamics
The EU Green Deal's extraterritorial reach is compressing export viability for North African manufacturers who supply European-adjacent markets, forcing wholesale redesigns of packaging substrates and leaf sourcing protocols across Mediterranean supply corridors.
Growth Catalysts
- Harm-reduction narratives:Adult consumers in South Africa are pivoting toward reduced-risk oral formats as public health discourse reframes smokeless alternatives to combustible products.
- SFDA import licensing:Saudi Arabia's standardized composition protocols are filtering out substandard suppliers and concentrating shelf space among compliant incumbents.
- Chilled storage infrastructure:Convenience store networks across Gulf Cooperation Council states are expanding cold-chain capacity that preserves moist snuff integrity through last-mile distribution.
Market Restraints
- Leaf input volatility:Cured tobacco leaf prices fluctuate with climate stress across Zimbabwe and Malawi growing belts, compressing margin predictability for regional processors.
- Excise tax escalation:Kenya and Nigeria are implementing ad-valorem tobacco levies that price out economy-tier consumers and shrink addressable market volume.
- Substitution pressure:Nicotine pouches and pharmaceutical cessation aids are capturing former chewing tobacco users in urban South African and Egyptian markets.
Strategic Opportunities
- East African traditional retail:Chewing tobacco penetration remains shallow in Ethiopia and Tanzania rural trade networks, offering first-mover expansion corridors.
- MOHAP-GCC harmonization:UAE-led standardization of tar and nicotine disclosure thresholds creates regulatory economies of scale for compliant suppliers across five member states.
- Dissolvable format innovation:Discrete nicotine delivery systems are capturing former smokers in Dubai and Riyadh professional districts where workplace consumption restrictions apply.
Industry Challenges
- Plain-packaging compliance timelines:South Africa's proposed standardized oral tobacco containers would obsolete existing brand equity and require full packaging line retooling.
- Skill scarcity in cold-chain logistics:Qualified technicians for temperature-controlled transport maintenance are concentrated in Gulf urban centers, leaving Horn of Africa distribution exposed to spoilage risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Smokeless Tobacco Market |
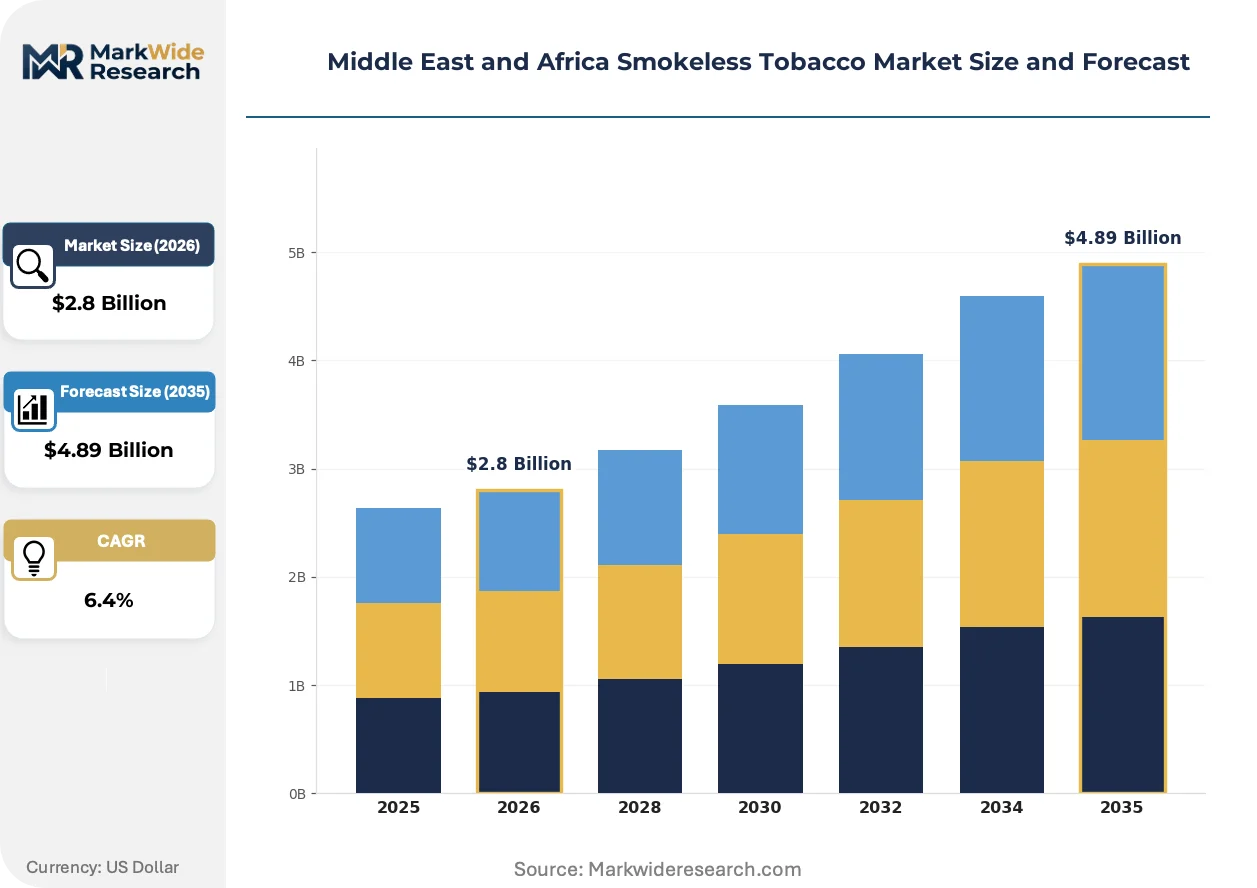
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moist Snuff, Dry Snuff, Chewing Tobacco, Dissolvable Tobacco End User: Adults, Minors, Former Smokers, New Users Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops Flavor Type: Mint, Fruit, Spiced, Herbal |
| Companies Covered | Orchid Tobacco Dubai, Altria Group, Inc., British American Tobacco Plc, Japan Tobacco International, Swedish Match AB, AL MATUCO TOBACCO COMPANY, KINGS TOBACCO FZ-LLC, Imperial Brands PLC, Gulbahar Tobacco, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Smokeless Tobacco Market Shifts & Advancements
Moisture-retention technologies and discrete consumption formats are displacing traditional chewing bundles across Middle East and Africa distribution channels, while regulatory disclosure mandates reshape product development priorities.
Modified-atmosphere packaging is unifying shelf-life extension with portability requirements for moist snuff products. Gulf Cooperation Council retailers are adopting these barrier-layer formats at accelerating rates to reduce refrigeration dependency. This convergence is unifying supply chain efficiency with expanded distribution reach into ambient-temperature retail environments across Levant and North African territories.
The EU Green Deal's packaging sustainability benchmarks are hardening compliance requirements for North African exporters serving European-adjacent markets. Manufacturers must now document recyclable substrate content and carbon footprint across leaf sourcing corridors. Moroccan and Egyptian processors face the steepest adaptation curves as their traditional supply routes confront these extraterritorial standards.
Urban professional consumers in Dubai, Johannesburg, and Riyadh are compressing their switching cycles between nicotine formats as discrete pouch and dissolvable alternatives proliferate in workplace-adjacent retail. Pharmacy and convenience channels are displacing traditional tobacconists for these segments. This behavioral rotation is most visible in Saudi Arabia and UAE corporate districts where consumption visibility carries social cost.
Middle East and Africa Smokeless Tobacco Market Segmentation
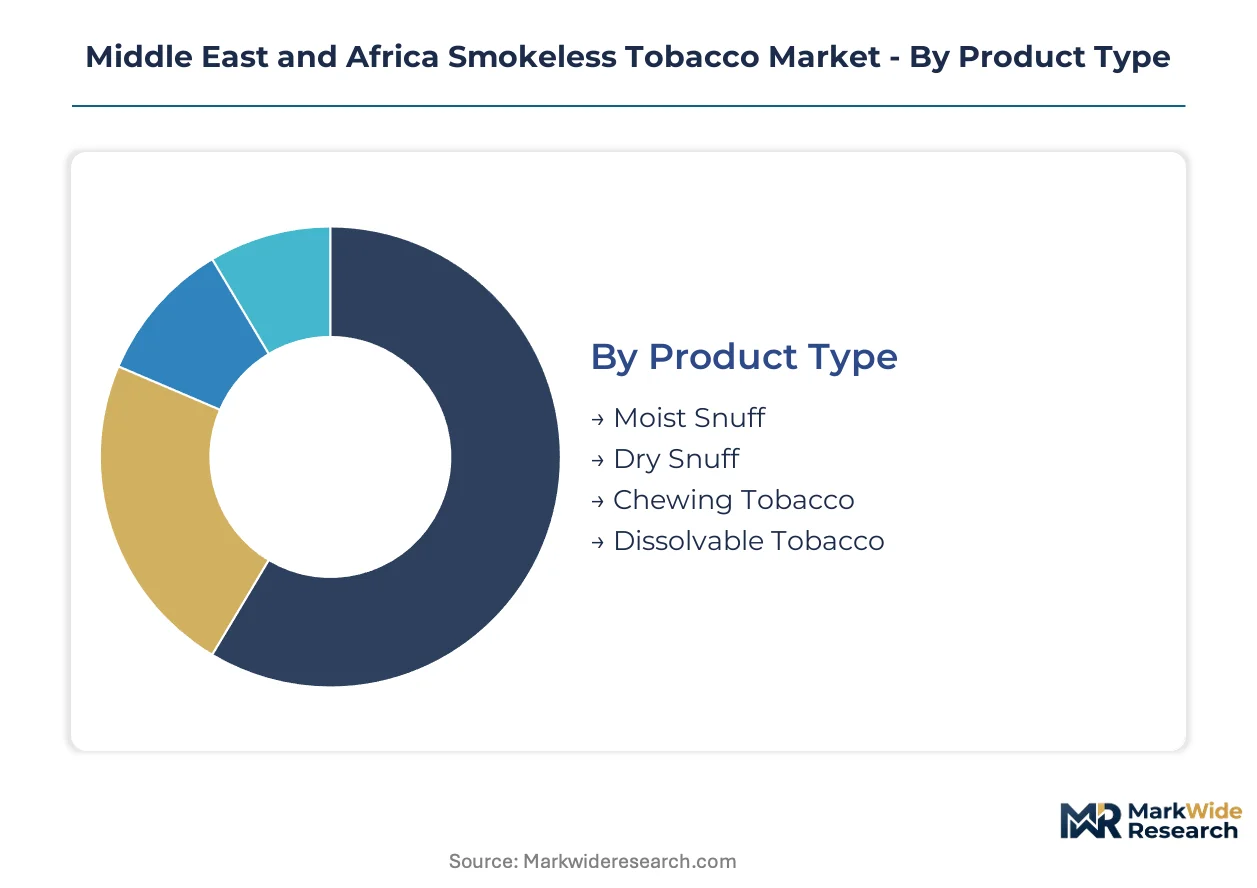
Segmentation across the Middle East and Africa smokeless tobacco market reveals how product formats, user profiles, and channel access intersect with regulatory pressure and consumption culture. Manufacturers calibrate portfolio depth against cold-chain infrastructure limits and disclosure mandates that vary by national jurisdiction.
Product Type:
Customization intensity spans from standardized bulk formats to precision-engineered discrete delivery systems, with moisture content and processing method determining shelf-life requirements and distribution reach.
- Moist Snuff:Finely ground cured tobacco with 30-50% moisture content requires chilled storage infrastructure that Gulf Cooperation Council convenience networks have prioritized. South African adult consumers in harm-reduction cohorts are pivoting toward this format as SFDA import licensing concentrates compliant supply among established incumbents.
- Dissolvable Tobacco:Compressed or extruded formats engineered for complete oral dissolution without expectoration target professional districts in Dubai and Riyadh where workplace visibility constraints apply. This segment captures former smokers seeking discrete nicotine delivery without the social cost of traditional oral tobacco use.
- Dry Snuff:Powdered cured leaf with sub-15% moisture tolerates ambient-temperature distribution across Levant and Horn of Africa territories lacking cold-chain coverage.
- Chewing Tobacco:Bundled or loose-leaf formats with 15-30% moisture maintain entrenched demand in East African traditional retail settings across Ethiopia and Tanzania rural trade networks.
Most installed capacity flows through Moist Snuff. Expansion is steepest in Dissolvable Tobacco.
End User:
User acquisition cost and retention strategy diverge sharply across maturity levels, from entrenched traditional consumers to nicotine-naive entrants requiring format education.
- Adults:The core revenue base spans established oral tobacco users in Gulf states and South African harm-reduction adopters. Kenya and Nigeria excise tax escalation is pricing out economy-tier consumers within this cohort, compressing addressable volume.
- Former Smokers:Urban professional segments in Johannesburg, Cairo, and Dubai corporate districts are compressing switching cycles between nicotine formats as pharmacy and convenience channels displace traditional tobacconists.
- New Users:Nicotine-naive entrants in Ethiopian and Tanzanian rural networks require format education and chewing bundle familiarity.
- Minors:Regulatory frameworks across South Africa, Saudi Arabia, and UAE explicitly prohibit targeting this cohort through labeling mandates and marketing vocabulary constraints.
Adult consumers generate the majority of current revenue. Former Smokers are climbing the fastest as discrete format availability expands.
Distribution Channel:
Channel selection determines temperature control investment, regulatory exposure, and customer education burden across the value chain.
- Convenience Stores:Gulf Cooperation Council networks are expanding cold-chain capacity that preserves moist snuff integrity through last-mile distribution. These outlets capture impulse replenishment from established adult users in Saudi Arabia and UAE urban corridors.
- Specialty Shops:Curated inventory of flavored variants—particularly mint and spiced profiles—serves discerning consumers in Dubai and Riyadh seeking product guidance and format experimentation.
- Supermarkets:Mass-market penetration in South African metropolitan areas confronts plain-packaging compliance timelines that would obsolete existing brand equity.
- Online Retail:Digital channels face MOHAP-GCC harmonization challenges around age verification and cross-border nicotine disclosure thresholds.
Most volume currently moves through Convenience Stores. Online Retail faces the steepest regulatory adaptation curve.
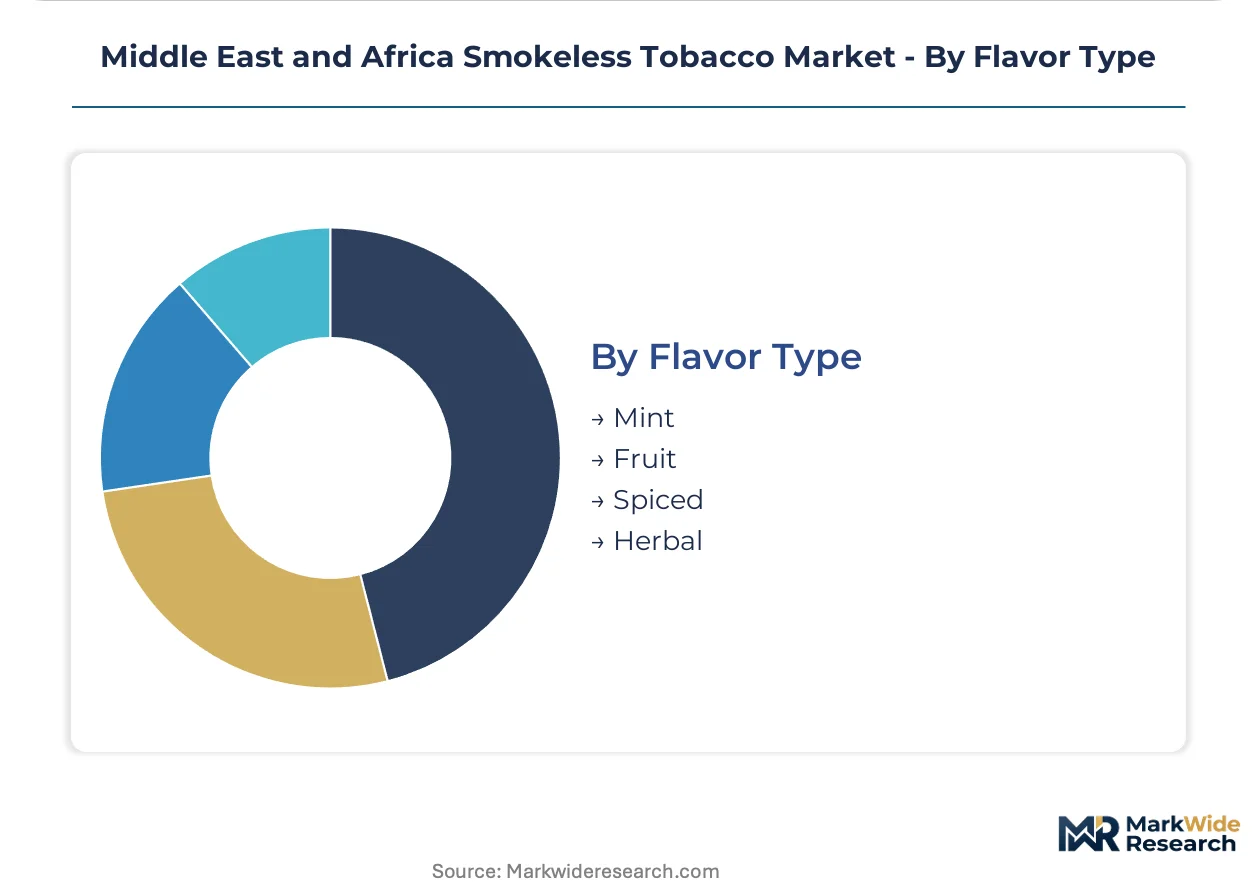
Flavor Type:
Flavor innovation serves as the primary differentiation vector where packaging standardization proposals threaten brand equity, with regional palate preference dictating R&D allocation.
- Mint:The dominant flavor profile across Gulf Cooperation Council states provides sensory masking and freshness signaling that appeals to former smokers transitioning from combustible products. Mint variants command premium shelf positioning in UAE specialty retail.
- Spiced:Traditional aromatic blends resonate with entrenched chewing tobacco users in East African markets and heritage-oriented consumers in North African territories.
- Fruit:Sweetened profiles target newer user acquisition in urban South African and Egyptian markets where nicotine pouch substitution pressure is intensifying.
- Herbal:Botanical-infused formats appeal to wellness-positioned consumers in Dubai and Johannesburg seeking reduced-perception alternatives.
Mint captures the largest share of flavor-driven premiumization. Fruit is gaining share fastest as manufacturers respond to substitution pressure from nicotine alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smokeless tobacco consumption in the Middle East and Africa traces its commercial lineage to colonial-era chewing traditions that evolved into branded moist snuff and dissolvable formats. Gulf Cooperation Council states now anchor regional volume through convenience store cold-chain networks, while South Africa's harm-reduction pivot reshapes product mix toward reduced-risk oral alternatives.
Saudi Arabia
SFDA import licensing protocols filter substandard suppliers and concentrate shelf space among compliant incumbents serving Riyadh and Jeddah metropolitan corridors. The regulator mandates standardized composition disclosure that elevates manufacturing transparency requirements. Eastern Province distribution hubs leverage proximity to Gulf logistics corridors for Levant re-export.
United Arab Emirates
MOHAP coordinates with GCC standardization bodies to harmonize tar and nicotine disclosure thresholds across member states, tightening market access for non-compliant suppliers. Dubai's specialty retail channels capture professional consumers seeking discrete dissolvable formats. Abu Dhabi anchors federal regulatory coordination that shapes compliance economics across five neighboring territories.
South Africa
Adult consumers represent the fastest-expanding end-user cohort as harm-reduction narratives gain traction in Johannesburg and Cape Town urban markets. The national health regulator enforces strict oral tobacco labeling requirements that constrain marketing vocabulary and mandate addiction warnings. Western Cape cold-chain infrastructure supports moist snuff integrity through last-mile distribution to metropolitan convenience networks.
Egypt
Traditional chewing tobacco maintains entrenched demand along Nile Delta rural trade networks while urban Cairo districts experience nicotine pouch substitution pressure. The country's pharmaceutical regulator monitors cross-border nicotine disclosure thresholds affecting import licensing. Alexandria and Port Said industrial zones process leaf inputs for Mediterranean export corridors confronting EU Green Deal packaging sustainability benchmarks.
Morocco
North African manufacturers serving European-adjacent markets face wholesale redesigns of packaging substrates and leaf sourcing protocols under extraterritorial EU Green Deal influence. Casablanca processing facilities document recyclable substrate content and carbon footprint across Mediterranean supply corridors. Tangier logistics hubs coordinate with Spanish and French distribution networks where sustainability compliance determines market access.
Middle East and Africa Smokeless Tobacco Market Competitive Landscape
Capital-heavy leaf processors compete with asset-light brand licensors across the Middle East and Africa smokeless tobacco market. Gulf-based logistics specialists and European multinational tobacco conglomerates dominate shelf space through divergent capability investments. Three archetypes define competitive positioning: integrated leaf-to-brand operators, regional distribution specialists, and reduced-risk product innovators. Incumbents defend position through SFDA compliance certification and cold-chain infrastructure expansion.
Within the integrated multinational tier, British American Tobacco Plc and Swedish Match AB exemplify divergent strategic postures—one anchoring regional portfolio through established moist snuff formulations, the other specializing in reduced-risk product narratives. Orchid Tobacco Dubai occupies the regional logistics specialist archetype, leveraging its Gulf hub to sustain distribution reach across Levant and Horn of Africa territories where cold-chain infrastructure remains uneven.
| Leading Market Players |
|---|
| Orchid Tobacco Dubai |
| Altria Group, Inc. |
| British American Tobacco Plc |
| Japan Tobacco International |
| Swedish Match AB |
| AL MATUCO TOBACCO COMPANY |
| KINGS TOBACCO FZ-LLC |
| Imperial Brands PLC |
| Gulbahar Tobacco |
| Others |
Supply & Pricing Matrix
Modified-atmosphere packaging adoption across Gulf Cooperation Council retail networks is compressing refrigeration-dependent distribution costs while concentrating procurement leverage among barrier-layer substrate suppliers. This dual shift simultaneously expands margin pools for compliant manufacturers and hardens entry barriers for ambient-format incumbents facing EU Green Deal compliance deadlines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Middle East and Africa smokeless tobacco transactions, with moisture-retention certification and SFDA import licensing status serving as primary price differentiation drivers. Cost compression in economy-tier segments is intensifying because Kenya and Nigeria ad-valorem excise escalations are pricing out budget-sensitive consumers. Former smokers seeking discrete dissolvable formats in Dubai and Riyadh corporate districts exhibit the lowest price sensitivity, while rural chewing tobacco users in Ethiopia and Tanzania represent the most price-elastic buyer cohort.
Supply Chain Analysis
Single-source vulnerability sits with Zimbabwe and Malawi cured leaf belts where climate stress and seasonal volatility concentrate input risk for regional processors. Supply draws from Mediterranean packaging substrate corridors and Gulf cold-chain logistics hubs, with leaf curing facilities, barrier-layer manufacturers, and temperature-controlled transport providers forming critical dependencies. Tariff exposure through EU Green Deal extraterritorial sustainability mandates threatens North African export viability. Distribution runs through convenience store networks with expanding chilled storage capacity across Saudi Arabia and UAE metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle East and Africa smokeless tobacco functions as a regulatory compounder where SFDA import licensing and EU Green Deal packaging mandates are accelerating compliance investment thresholds and filtering supplier bases toward certified incumbents.
For Market Incumbents: Anticipate plain-packaging compliance timelines in South Africa by accelerating packaging line retooling and securing alternative brand equity vehicles through flavor innovation portfolios. Cold-chain infrastructure expansion into Horn of Africa territories offers defensive positioning against logistics spoilage risks that threaten ambient-format competitors. Vertical integration into leaf curing operations in Zimbabwe and Malawi reduces input volatility exposure. For New Entrants and Emerging Players: Convenience store networks in Ethiopia and Tanzania rural trade networks represent the most penetrable white-space corridor, with chewing tobacco format education requirements creating incumbent blind spots. Dissolvable tobacco positioning for professional districts in secondary Gulf cities bypasses saturated Dubai and Riyadh shelf space. Partner with regional logistics specialists to access MOHAP-GCC harmonized compliance certification without direct regulatory navigation burden. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution specialists lacking cold-chain asset depth but holding Levant and Horn of Africa channel relationships. Long-term viability hinges on regulatory compliance scalability across five-member GCC standardization frameworks. Watch SFDA licensing backlog clearance rates as inflection signal for market access velocity and shelf space concentration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modified-Atmosphere Packaging Adoption | Gulf retailers reduce refrigeration dependency while extending moist snuff shelf integrity across ambient-temperature Levant corridors. |
| SFDA Import Licensing Certification | Compliant suppliers concentrate Riyadh and Jeddah shelf space as substandard entrants face filtered market access. |
| East African Rural Distribution Expansion | First-mover positioning in Ethiopia and Tanzania chewing tobacco networks captures format education-dependent demand. |
| EU Green Deal Compliance Repositioning | Moroccan and Egyptian processors document recyclable substrates to sustain Mediterranean export corridor viability. |
| Dissolvable Format R&D Investment | Discrete nicotine delivery captures former smokers in workplace-restricted Dubai and Riyadh professional districts. |
Research Methodology
Direct dialogue with smokeless tobacco brand managers, Gulf logistics operators, SFDA regulatory consultants, and convenience store category buyers grounded qualitative findings, cross-referenced against customs trade databases, MOHAP disclosure filings, EU Green Deal technical documentation, and Nielsen retail audit data covering GCC convenience channels. Bottom-up demand modeling triangulated against top-down macroeconomic projections across the analysis window.
Bottom-up volume construction aggregated product-type, end-user, and distribution channel segments with moisture-content processing tiers and regulatory compliance clusters as cross-cutting dimensions. Top-down validation incorporated GDP per capita elasticity coefficients and tobacco excise policy trajectories. CAGRs derived from segment-level growth rate distributions applied across the projection horizon, with cold-chain infrastructure buildout schedules and SFDA licensing throughput serving as industry-specific forecast inputs.
Revisions become necessary when GCC standardization harmonization timelines shift, EU Green Deal packaging enforcement intensifies, or Zimbabwe and Malawi leaf harvests deviate from climate-adjusted baselines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Tobacco Films Market
Tobacco
US Tobacco Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
Heat-Not-Burn Market
Tobacco
Egypt Tobacco Market
Tobacco
Organic Tobacco Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
North America Tobacco Market
Tobacco
North America Cigarette Market
Tobacco
Cigarette Paper Market