
 Tobacco Films Market | 2026-2036
Tobacco Films Market Size, Share, and Industry Trends Forecast 2026-2036
Tobacco Films Market Analytics
Consolidation among cigarette brands is realigning procurement volumes toward fewer, larger contract holders. Toray Industries leverages its polymer science heritage to dominate high-clarity cellulose film supply for premium wrappers. SRF Limited anchors South Asian production capacity with backward integration into polyester resin operations. Taghleef Industries competes through geographic diversification across multiple manufacturing hubs.
Tobacco films are thin-gauge polymer or regenerated cellulose substrates engineered with controlled moisture transmission rates between 5 and 50 g/m²/day, serving primarily as barrier layers that preserve tobacco aroma and prevent dehydration during shelf storage. Polypropylene films retain the largest volume share due to their cost efficiency and heat-seal compatibility with high-speed packaging lines. Biodegradable films represent the fastest-expanding category as cigarette brands face mounting pressure to eliminate conventional plastic components from their supply chains. Composite films command premium positioning where multilayer barrier performance justifies higher unit economics.
The European Commission's F-Gas Regulation and REACH restrictions on phthalate plasticizers are forcing reformulation of conventional film chemistries, while FDA guidance on modified risk tobacco products creates parallel compliance obligations in the United States. ISO 9001 and ISO 14001 certifications have become baseline qualifications for supplier qualification programs at major tobacco manufacturers. Stakeholders must monitor evolving biodegradability certification standards and pre-position alternative material platforms before regulatory deadlines eliminate incumbent technologies from approved supplier lists.
Market Dynamics
Biodegradable film formulations are compressing the addressable market for conventional polypropylene substrates as EU Green Deal compliance deadlines force cigarette manufacturers to eliminate petroleum-derived packaging components from approved supplier lists.
Growth Catalysts
- EU Green Deal packaging mandates:The European Commission's 2030 single-use plastic reduction targets compel tobacco manufacturers to source compostable film alternatives for outer wrappers and overwrap applications.
- Cellulose regeneration technology:Advanced solvent recovery processes are reducing production costs for high-clarity regenerated cellulose films, enabling broader adoption across mid-tier cigarette brands.
- Germany:German tobacco manufacturers are consolidating procurement volumes toward REACH-compliant film suppliers with verified biodegradability certification, concentrating demand in Western Europe's largest production hub.
Market Restraints
- Wood pulp price volatility:Regenerated cellulose film margins remain exposed to softwood commodity swings, with dissolving pulp accounting for substantial raw material cost exposure.
- Specialized coating equipment:Moisture-barrier cellulose films require capital-intensive metallization or PVDC coating lines that few converters outside Japan and Italy currently operate.
- REACH phthalate restrictions:ECHA's expanding list of restricted plasticizers is forcing reformulation of conventional plasticized films before alternative chemistries achieve scale validation.
Strategic Opportunities
- India:Domestic cigarette manufacturers are accelerating local film sourcing to reduce import dependency, creating openings for regional converters with BIS-certified production.
- Heat-not-burn devices:Specialized barrier films for heated tobacco sticks command premium positioning as PMI and BAT expand device penetration across Asian markets.
- ISO 17088 certification:Early attainment of industrial compostability standards is creating supplier lock-in advantages as major tobacco OEMs pre-qualify film vendors for 2027 sustainability targets.
Industry Challenges
- Migration testing protocols:Film suppliers face extended validation timelines as tobacco manufacturers implement enhanced substance migration testing for novel biodegradable chemistries.
- Legacy heat-seal line compatibility:Biodegradable films exhibit narrower processing windows than polypropylene, requiring converter retraining and line speed adjustments that compress effective capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tobacco Films Market |
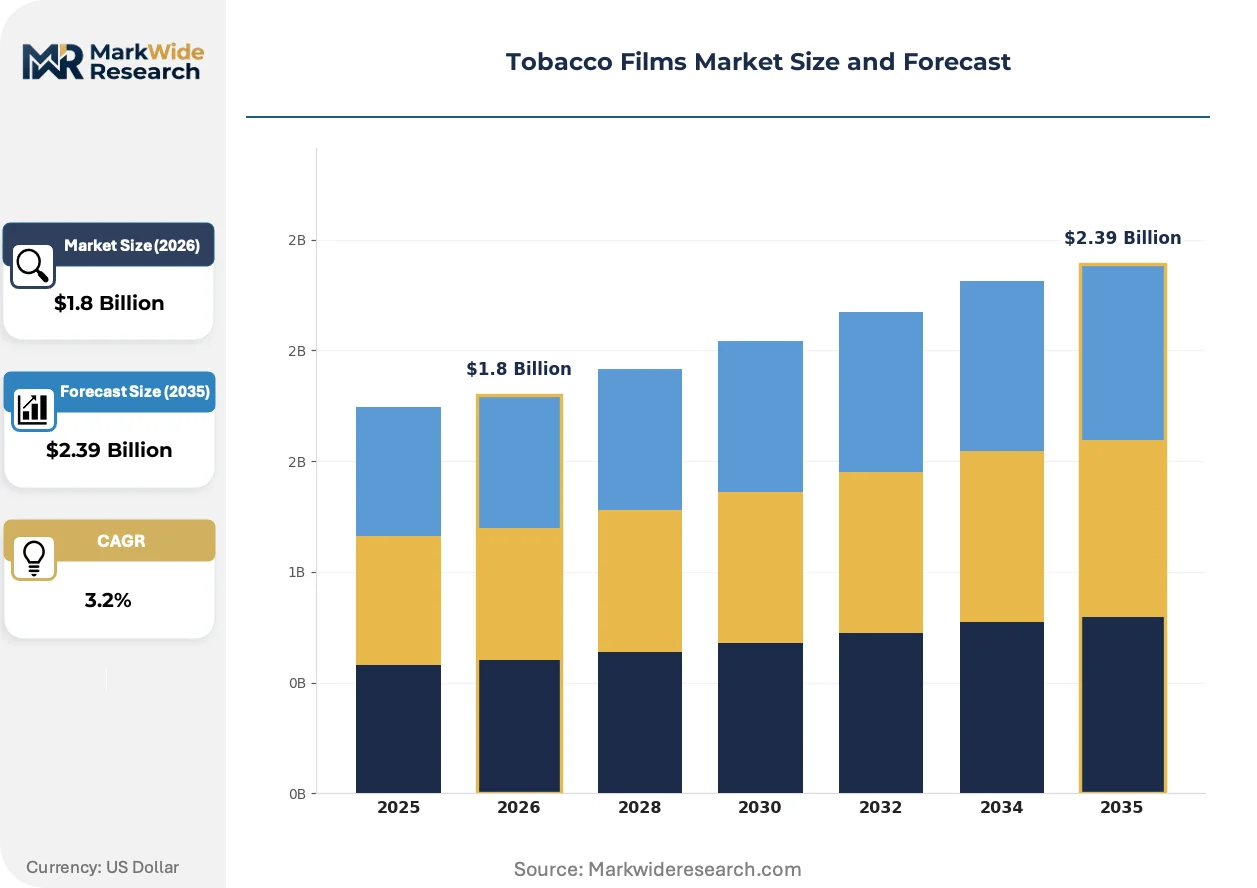
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose Films, Biodegradable Films, Composite Films, Polypropylene Films Thickness: Thin Films, Medium Films, Thick Films, Extra-Thick Films Application: Cigarette Wrappers, Rolling Papers, Pouches, Filters End User: Tobacco Manufacturers, Cigarette Brands, Online Retailers, Wholesalers |
| Companies Covered | Toray Industries, Polyplex Corporation, Cosmo Films, Treofan Group, SRF Limited, Innovia Films by CCL Industries, Uflex Limited, SIBUR, Taghleef Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tobacco Films Market Evolving Landscape
Material science breakthroughs and regulatory compression timelines are converging to redefine competitive advantage around sustainability verification rather than conventional cost-performance metrics.
Regenerated cellulose films with controlled moisture transmission rates between 5 and 50 g/m²/day are overtaking biaxially oriented polypropylene in premium cigarette wrapper applications. European manufacturers are accelerating qualification timelines for these substrates ahead of 2027 EU packaging waste directives. The shift is compressing demand for conventional petroleum-derived films while elevating supplier premiums for certified compostable alternatives.
REACH restrictions on phthalate plasticizers are forcing wholesale reformulation of conventional film chemistries across European supply chains. Industrial consequences include accelerated R&D spending on citrate and bio-based plasticizer alternatives. Premium cigarette segments are absorbing higher unit costs for compliant films, while economy brands face margin compression or supply discontinuation.
Consolidated procurement at major tobacco OEMs is compressing supplier qualification cycles and elevating certification requirements. Direct contracting with film manufacturers is displacing distributor-mediated purchasing across Western European markets. German and Swiss headquarters operations are centralizing global film sourcing decisions, reducing regional procurement autonomy.
Tobacco Films Market Segmentation
Tobacco film procurement decisions hinge on regulatory compliance timelines and packaging line compatibility. Material specifications vary sharply across cigarette price tiers and regional sustainability mandates. Understanding segment interdependencies enables suppliers to prioritize R&D investments and capacity allocation.
Product Type:
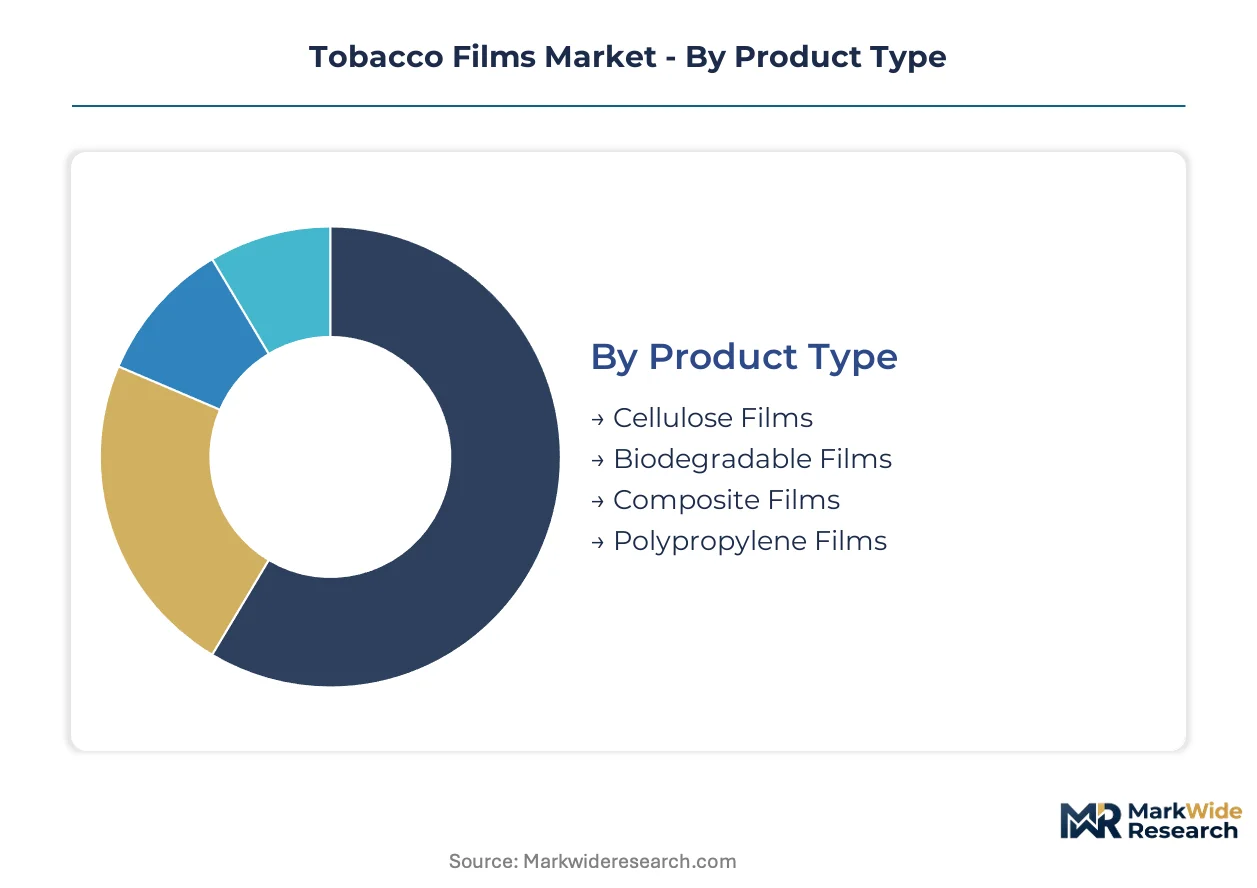
Cost tier determines material selection, with premium brands absorbing cellulose premiums while economy segments cling to polypropylene.
- Cellulose Films:Regenerated wood-pulp substrates deliver controlled moisture transmission between 5 and 50 g/m²/day. German cigarette manufacturers concentrate procurement here to satisfy EU Green Deal packaging mandates ahead of compliance deadlines.
- Biodegradable Films:Compostable polymer formulations eliminate petroleum-derived components. Demand concentrates in Western Europe where REACH restrictions on conventional plasticizers are forcing wholesale supply chain conversion, climbing the fastest among all product categories.
- Composite Films:Multilayer constructions combining cellulose with barrier coatings for premium aroma retention.
- Polypropylene Films:Biaxially oriented substrates retain heat-seal compatibility with legacy high-speed packaging lines across Asia-Pacific manufacturing hubs.
Polypropylene films lead on scale; biodegradable films lead on momentum.
Thickness:
Application mechanics dictate gauge selection, with high-speed wrappers demanding thin profiles and structural pouches requiring heavier substrates.
- Thin Films:Sub-20 micron gauges optimize material yield for high-volume outer wrappers. Cigarette brands in India specify these for cost-competitive domestic production under BIS certification requirements.
- Medium Films:20-35 micron range balances barrier performance with heat-seal energy efficiency across European packaging lines.
- Thick Films:Heavy-gauge substrates provide puncture resistance for pouch applications in moist snuff and chewing tobacco formats.
- Extra-Thick Films:Specialized gauges above 50 microns serve filter assembly applications requiring dimensional stability during high-speed insertion.
Thin films dominate volume throughput; extra-thick films command the steepest premium expansion trajectory.
Application:
Packaging line speed requirements separate wrapper specifications from slower secondary applications.
- Cigarette Wrappers:Primary packaging films require precise moisture barrier and dead-fold characteristics. Toray Industries anchors supply for premium Japanese and European brands demanding optical clarity.
- Filters:Acetate tow overwrap films need controlled porosity for ventilation zone engineering. Heat-not-burn device manufacturers specify specialized barrier grades as PMI and BAT expand Asian market penetration.
- Rolling Papers:Thin-gauge substrates for hand-rolled cigarette formats prioritize burn rate consistency.
- Pouches:Moist snuff and nicotine pouch films require grease resistance and flavor barrier properties.
Cigarette wrappers absorb the largest procurement volumes; filters generate the fastest technology upgrade cycles.
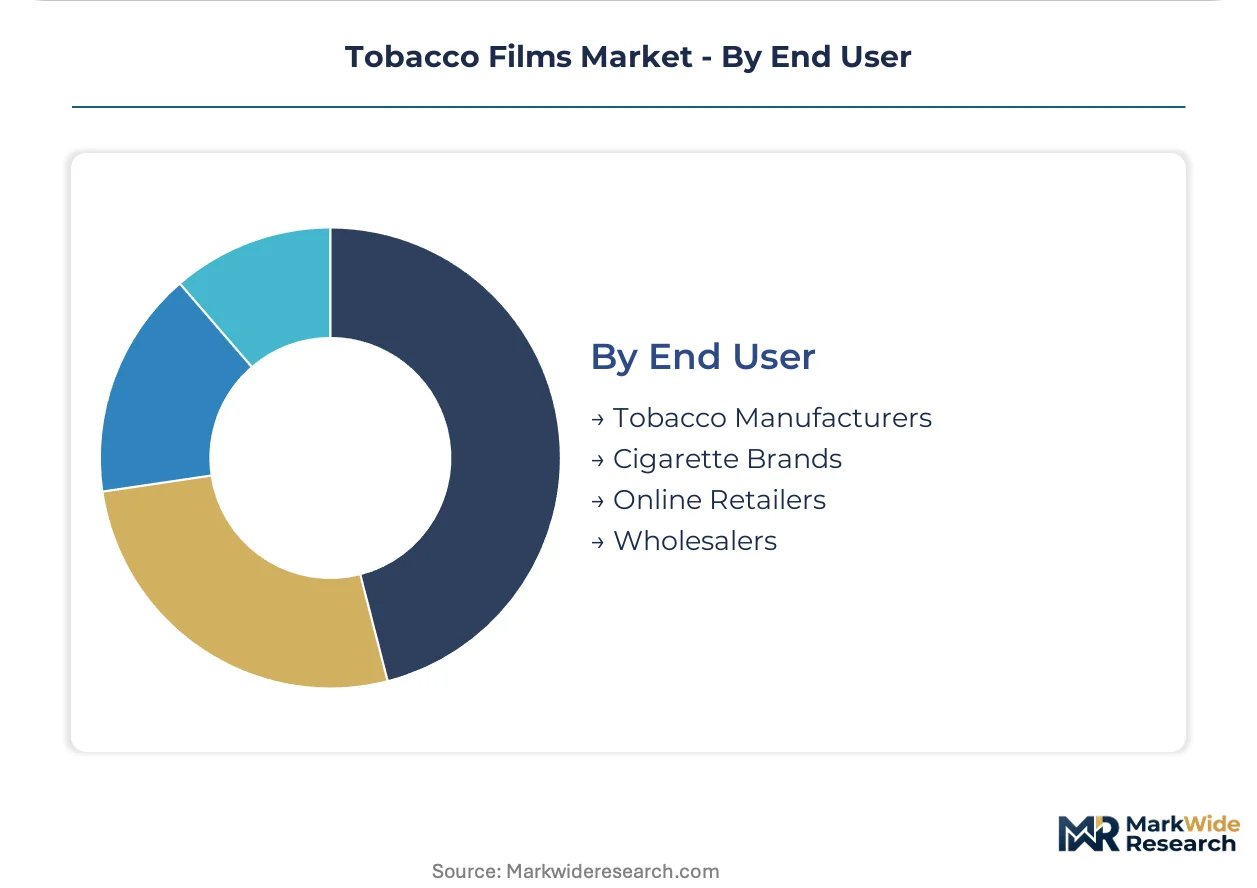
End User:
Procurement centralization patterns separate direct manufacturer contracting from distributor-mediated wholesale purchasing.
- Tobacco Manufacturers:Integrated producers like BAT and PMI operate centralized film sourcing from Swiss and German headquarters, consolidating global supplier qualification programs.
- Cigarette Brands:Brand-owning entities without manufacturing assets contract toll converters, creating demand fragmentation across regional packaging service providers.
- Online Retailers:E-commerce channels for rolling papers and accessory films prioritize SKU breadth over volume commitment.
- Wholesalers:Distributor intermediaries serve smaller regional brands with limited direct supplier access, particularly across Eastern European and Southeast Asian markets.
Tobacco manufacturers concentrate procurement scale; online retailers are gaining share fastest in niche accessory segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates procurement volumes for REACH-compliant films while India accelerates domestic sourcing to reduce import dependency. The divergence reflects broader regional patterns where regulatory stringency in Western Europe contrasts with supply chain localization in emerging Asian markets.
Germany
Tobacco manufacturers in Hamburg and Berlin consolidate film procurement toward verified biodegradability certification under EU Green Deal packaging mandates. ECHA's phthalate restrictions are forcing wholesale reformulation of conventional plasticized films. The Rhine-Ruhr industrial corridor hosts specialized converters with metallization and PVDC coating capabilities for moisture-barrier cellulose grades.
United States
Heat-not-burn device expansion by PMI and BAT drives specialized barrier film demand across American manufacturing facilities. FDA guidance on modified risk tobacco products creates parallel compliance obligations for film suppliers alongside state-level packaging waste regulations. The Southeast tobacco belt—North Carolina and Virginia—maintains legacy polypropylene consumption for conventional cigarette production.
India
Domestic cigarette manufacturers accelerate BIS-certified local film sourcing to reduce import dependency from European and Japanese suppliers. The country's national standards body enforces quality specifications that regional converters must meet for qualification. Maharashtra and Gujarat host emerging packaging film clusters where backward integration into polyester resin operations anchors South Asian production capacity.
Japan
Premium cigarette brands specify high-clarity regenerated cellulose films with precise moisture transmission control for wrapper applications. METI's sustainability guidelines pressure domestic manufacturers toward biodegradable alternatives ahead of international compliance deadlines. The Kanto region around Tokyo concentrates advanced solvent recovery processes for cost-competitive cellulose regeneration.
Switzerland
Swissmedic oversight of tobacco product quality intersects with centralized global sourcing decisions by BAT and PMI headquarters operations in Basel and Lausanne. Swiss manufacturers demand ISO 17088 industrial compostability certification from pre-qualified film vendors. The Zurich packaging technology cluster develops specialized coating equipment for narrow-processing-window biodegradable substrates.
Tobacco Films Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Consolidated procurement at major tobacco OEMs compresses supplier qualification cycles and elevates certification requirements. Three strategic archetypes dominate: integrated polymer producers with captive resin supply, specialized cellulose converters with coating capabilities, and regional packaging film specialists with BIS or REACH compliance. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms position alternative material platforms before regulatory deadlines eliminate incumbent technologies.
Among Japanese industrial conglomerates, Toray Industries occupies a position exemplifying polymer science heritage applied to high-clarity cellulose supply. SRF Limited anchors South Asian production capacity through upstream control over polyester resin operations. Taghleef Industries sits within the geographic diversification archetype, competing through manufacturing hub distribution across multiple jurisdictions rather than single-location scale concentration.
| Leading Market Players |
|---|
| Toray Industries |
| Polyplex Corporation |
| Cosmo Films |
| Treofan Group |
| SRF Limited |
| Innovia Films by CCL Industries |
| Uflex Limited |
| SIBUR |
| Taghleef Industries |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging mandates are compressing procurement timelines toward certified biodegradable suppliers, forcing converters to absorb cellulose premium costs while cigarette manufacturers consolidate volumes toward fewer contract holders with verified ISO 17088 credentials.
Pricing Analysis
Capacity additions in India and Germany are reshaping price floors for conventional polypropylene grades while elevating premiums for REACH-compliant cellulose alternatives. Three-tier pricing structure across premium, standard, and economy levels separates optical-clarity regenerated cellulose from metallized barrier grades and commodity biaxially oriented substrates. Price differentiation hinges on biodegradability certification tier and backward integration into dissolving pulp supply. Cost compression in economy polypropylene segments is intensifying because of wood pulp price volatility, while premium cigarette brands exhibit lowest price sensitivity due to sustainability-driven procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements from BAT and PMI headquarters operations are compelling film suppliers to maintain parallel production qualifications across multiple jurisdictions. Raw material supply draws from softwood pulp operations in Canada and Scandinavia, dissolving pulp facilities in South Africa, and petrochemical feedstocks in the Middle East. Supply chain risk centers on single-source vulnerability for specialized PVDC coating equipment concentrated in Japan and Italy. Distribution runs through direct manufacturer contracting that is displacing distributor-mediated purchasing across Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in tobacco films rests on solvent recovery technology cost-down curves and the premium-tier shift toward compostable cellulose substrates that command supplier lock-in advantages.
For Market Incumbents: Extend coating capability investments ahead of 2027 EU packaging waste directive deadlines to capture stranded demand from non-compliant competitors. Secure backward integration into dissolving pulp supply to insulate margins from softwood commodity swings. Defend against emerging Asian converters by pre-qualifying capacity expansions with centralized procurement teams at Swiss and German headquarters operations. For New Entrants and Emerging Players: Enter via BIS-certified production in Maharashtra and Gujarat to serve Indian cigarette manufacturers accelerating domestic sourcing. Target heat-not-burn device barrier films as the most penetrable premium segment where PMI and BAT expansion creates qualification openings. Pursue toll manufacturing arrangements with European brand-owning entities lacking in-house converting assets. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cellulose converters possessing metallization capabilities and verified industrial compostability certification. Five-to-ten year viability favors suppliers with solvent recovery process patents and established relationships with centralized tobacco OEM procurement functions. Watch for ECHA phthalate restriction expansion timelines as the inflection signal that eliminates conventional plasticized film competitors from approved supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Captive softwood supply insulates Toray Industries and SRF Limited from commodity volatility exposure. |
| ISO 17088 Certification Investment | Early attainment creates supplier lock-in with BAT and PMI sustainability procurement programs. |
| Solvent Recovery Process Scale-Up | Advanced regeneration technology enables cost-competitive cellulose supply to mid-tier cigarette brands. |
| Geographic Manufacturing Diversification | Taghleef Industries spreads regulatory risk across multiple jurisdictions rather than single-location concentration. |
| Heat-Not-Burn Barrier Film Development | Specialized grades for heated tobacco sticks command premium positioning in PMI and BAT Asian expansion markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tobacco procurement directors, film converter plant managers, regulatory affairs specialists at ECHA, and sustainability certification auditors with secondary validation. Sources included customs trade data for biaxially oriented polypropylene and regenerated cellulose film shipments, REACH restriction proposal documents, ISO certification registry databases, and SEC filings from listed packaging material suppliers. Bottom-up volume modeling from individual production facilities was triangulated against top-down demand estimates derived from cigarette manufacturer packaging line capacity disclosures.
Historical reference periods anchored volume and value trajectories across the analysis window, with projections calibrated to regulatory compliance deadline schedules and technology adoption curves. Segmentation dimensions modeled encompassed product type, thickness gauge, application format, and end-user procurement centralization level. CAGRs were computed from fitted trend lines adjusted for step-change disruptions from EU Green Deal implementation. Industry-specific forecast inputs included dissolving pulp price indices and heat-not-burn device market penetration assumptions.
Inputs from ECHA regulatory filings and ISO certification bodies were available through the study window; gaps in real-time cigarette manufacturer inventory build rates introduce uncertainty bands around near-term volume estimates. Deviation in EU packaging waste directive enforcement timelines or accelerated REACH phthalate restriction implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
Cigarette Paper Market
Tobacco
US Tobacco Market
Tobacco
Heat-Not-Burn Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Organic Tobacco Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
Middle East and Africa Smokeless Tobacco Market
Tobacco
North America Tobacco Market
Tobacco
North America Cigarette Market
Tobacco
Egypt Tobacco Market