
 Cigarette Paper Market | 2026-2036
Cigarette Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Cigarette Paper Market Analysis
Market Overview
European specialty paper producers is restructuring capacity toward thin-gauge and additive-free grades to meet downstream filter and rolling specifications. SWM International leverages its North American flax fiber supply chain to sustain premium positioning in ultra-thin segments. Delfort Group AG anchors Central European manufacturing scale through integrated pulp-to-reel operations across Austria and Germany. Miquel y Costas & Miquel S.A. dominates Mediterranean markets with specialized watermarking and burn-rate control technologies.
Technical and Segment Dynamics
Cigarette paper constitutes a highly engineered tissue-grade product, typically manufactured from flax, hemp, or wood pulp fibers with controlled porosity between 15-80 CU (Coresta Units) to regulate air dilution and burn rate. Its primary commercial purpose is to contain tobacco while delivering consistent combustion characteristics and tar retention specified by machine-made and hand-rolled cigarette producers. White paper occupies the largest volume share across machine-made applications where uniform appearance and standardized porosity command stable margin pools. Brown unbleached paper represents the fastest-growing material category as consumers in Western Europe and North America migrate toward perceived natural and additive-free alternatives. Hemp-based rolling paper concentrates margin capture within specialty channels and boutique tobacco retailers serving connoisseur segments.
Regulatory Environment and Outlook
The U.S. FDA and EPA impose emissions testing and paper additive disclosure requirements that directly constrain formulation flexibility and lengthen product qualification cycles. E.U. REACH and the Tobacco Products Directive mandate ingredient transparency and restrict certain flame-retardant or flavor-carrying coatings, reshaping R&D priorities across European mills. China's SAMR enforces national GB standards for paper heavy-metal content and burn residue that govern import access and domestic production licensing. Stakeholders must monitor evolving combustible tobacco regulations in Indonesia and Brazil as these jurisdictions consider aligning with OECD-style emissions frameworks that would alter specification demand across export-oriented supply chains.
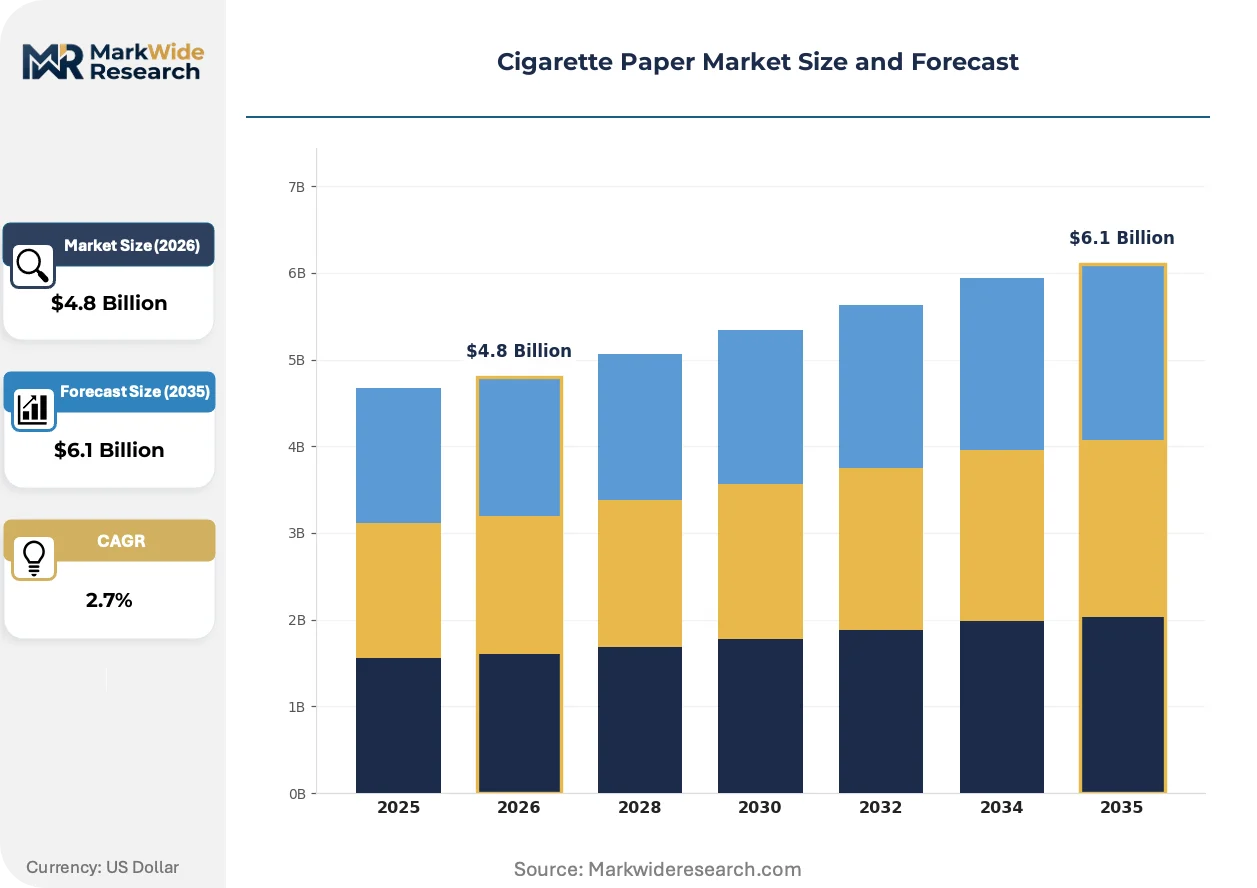
Market Dynamics
Flax fiber supply concentration in France and Belgium is compressing input cost predictability for ultra-thin cigarette paper manufacturers, forcing mills to restructure long-term procurement contracts or absorb margin volatility.
Growth Catalysts
- E.U. Tobacco Products Directive:Mandates for reduced ignition propensity are accelerating demand for specialty papers with controlled porosity and burn-rate engineering in machine-made segments.
- Hemp fiber processing:Decortication and refining advances are lowering production costs for natural-fiber rolling papers, opening connoisseur channels previously blocked by price premiums.
- Indonesia:Domestic specialty paper capacity expansion is creating regional export hubs serving Southeast Asian markets with localized specification compliance.
Market Restraints
- Flax supply concentration:Western European fiber harvest volatility exposes mills to input cost spikes that cannot be passed through in contract-renewal cycles with major tobacco manufacturers.
- REACH compliance costs:E.U. chemical disclosure and additive restriction requirements are extending qualification timelines for new paper formulations by 18-24 months.
- Cellulose acetate alternatives:Non-combustible nicotine delivery systems are displacing traditional cigarette consumption in urban centers across North America and Western Europe.
Strategic Opportunities
- Brazil:Potential alignment with OECD emissions frameworks would create first-mover advantage for mills pre-qualified to E.U. standards in a high-volume import market.
- Additive-free certification:Premium positioning through third-party verified "natural" claims commands 40-60% price multiples in boutique retail channels.
- Direct-to-consumer e-commerce:Rolling paper brands are bypassing traditional tobacco distribution monopolies to capture margin and consumer data in hand-rolled segments.
Industry Challenges
- Porosity control engineering:Maintaining 15-80 CU specification bands across humidity and altitude variations requires specialized talent pools concentrated in Central European technical institutes.
- Multi-jurisdiction compliance:Simultaneous qualification to FDA additive disclosure, REACH ingredient transparency, and SAMR heavy-metal standards fragments R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cigarette Paper Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
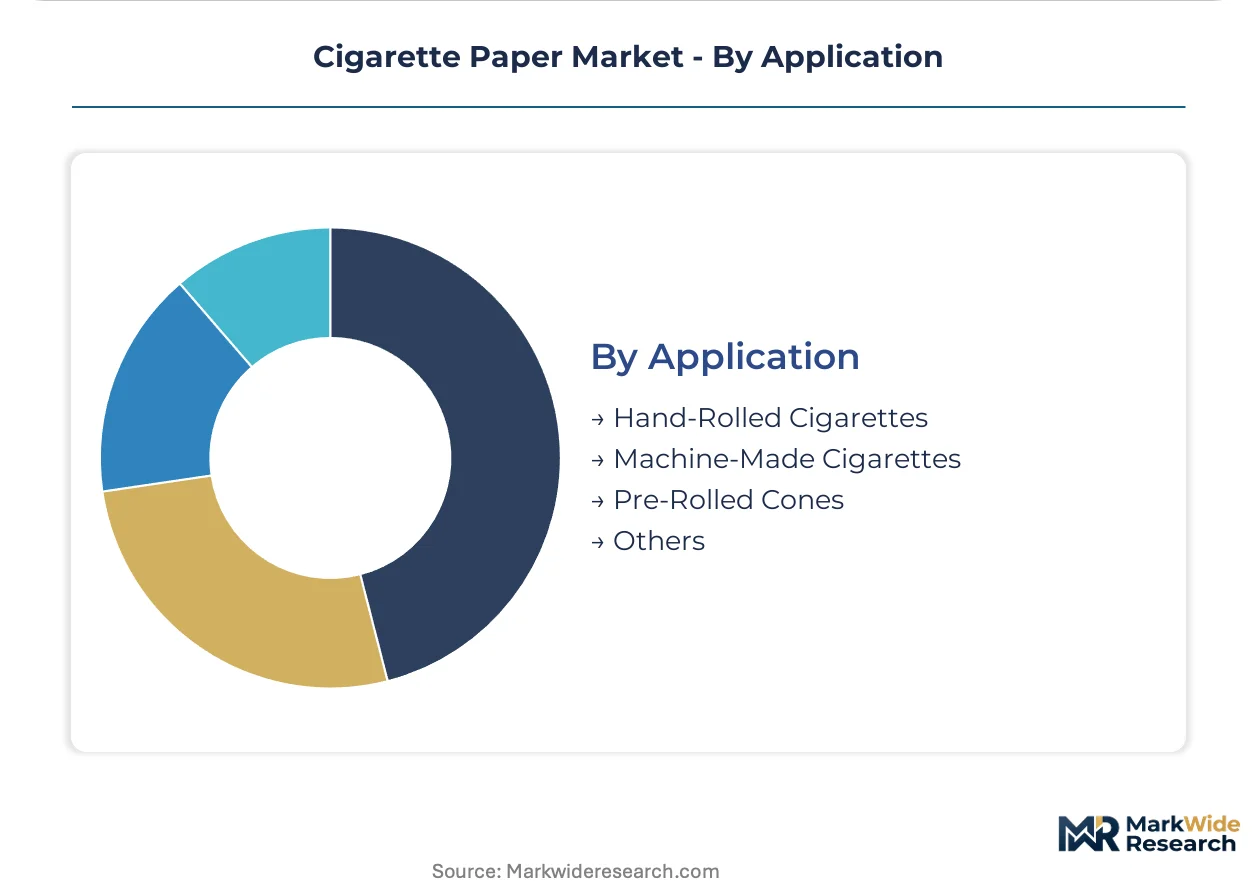
| Segmentation | Product Type: White Paper, Brown Paper, Flavored Paper, Rolling Paper Material: Hemp, Wood Pulp, Rice, Recycled Fibers Thickness: Thin, Medium, Thick, Ultra-Thin Application: Hand-Rolled Cigarettes, Machine-Made Cigarettes, Pre-Rolled Cones, Others |
| Companies Covered | SWM International, Delfort Group AG, Miquel y Costas & Miquel S.A., Republic Technologies, The Rolling Paper Company, Nippon Paper Papylia Co. Ltd., Glatz Feinpapiere, BMJ, Mudanjiang Hengfeng Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cigarette Paper Market Emerging Trajectories
Material science advances and regulatory disclosure mandates are converging to redefine cigarette paper as a specification-intensive component rather than a commodity input, with burn-rate precision and additive transparency becoming primary competitive differentiators.
Watermarked security papers with embedded authentication features are expanding into tax-stamp integration and anti-counterfeiting applications for state-controlled tobacco markets. Government procurement offices in Italy and Spain are mandating these specifications for domestic machine-made production. The technology is expanding into revenue-protection contracts that bundle paper supply with track-and-trace system integration.
REACH ingredient transparency requirements are forcing mills to restructure coating formulations and eliminate legacy flame-retardant chemistries from production lines. European manufacturers face 12-18 month reformulation cycles to maintain E.U. market access. Brown unbleached grades with minimal processing are capturing specification share as additive-free alternatives with simpler compliance pathways.
Urban millennial and Gen-Z consumers are migrating toward hand-rolling rituals as premium experiences, displacing machine-made volume in metropolitan retail. Boutique tobacco shops in London, Berlin, and Amsterdam are curating hemp and flax paper assortments with origin storytelling. Specialty channels now command margin multiples that offset volume concentration in traditional manufacturing contracts.
Cigarette Paper Market Segmentation
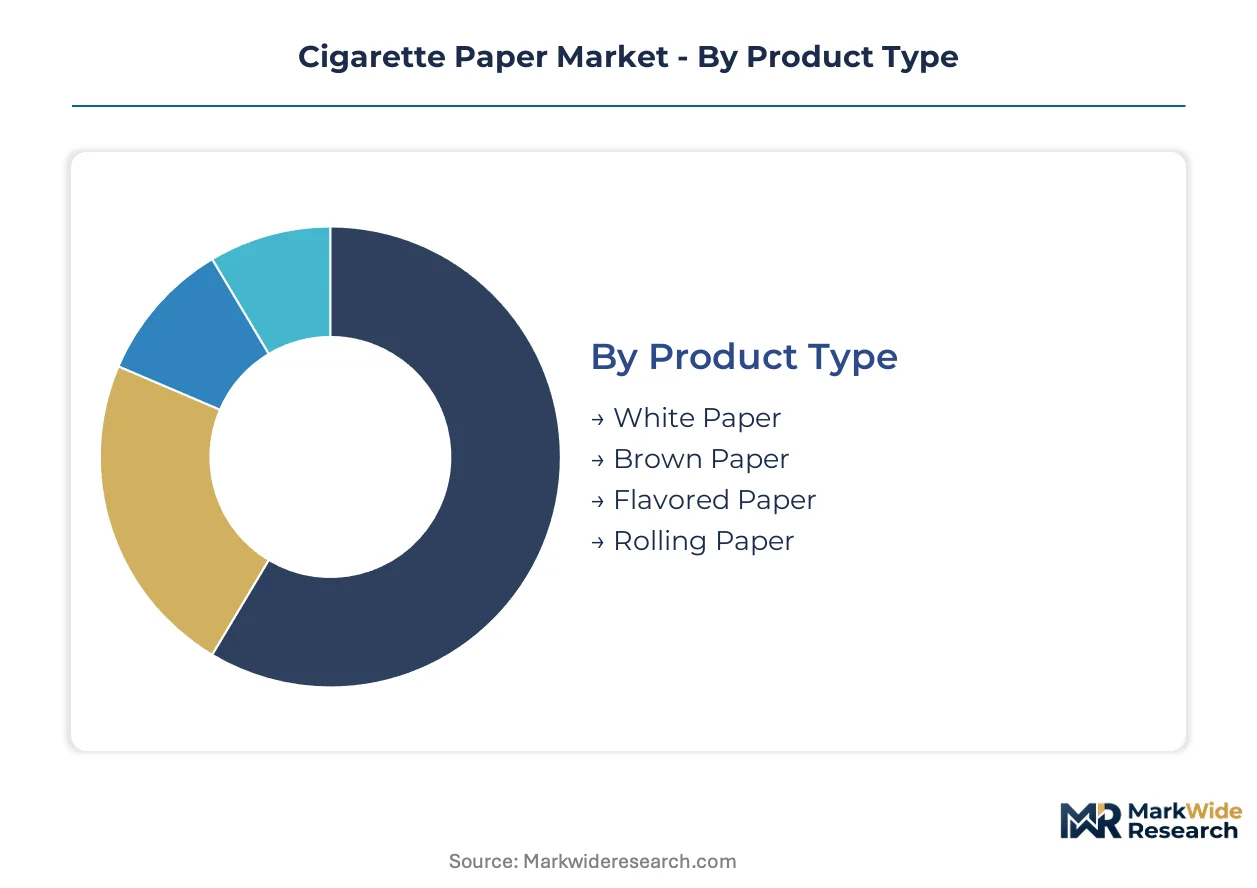
Cigarette paper segmentation reflects divergent engineering requirements between mass-production machine formats and artisanal hand-rolling channels. Specification bands for porosity, burn rate, and additive content vary sharply across these use cases, creating distinct margin pools and qualification barriers.
Product Type:
White paper dominates embedded systems within machine-made manufacturing, while brown and specialty grades serve standalone consumer markets with distinct positioning strategies.
- White Paper:Manufactured from bleached flax or wood pulp with standardized 20-40 CU porosity for consistent tar retention and combustion control. Demand concentrates in high-volume machine-made production across Indonesia and Poland where uniform appearance commands contract stability with multinational tobacco manufacturers.
- Brown Paper:Unbleached kraft-grade material retaining natural lignin content for perceived additive-free positioning. Western European consumers in Germany and the Netherlands are migrating toward this category as E.U. REACH disclosure mandates elevate transparency preferences in boutique retail channels.
- Flavored Paper:Encapsulated additive carriers for menthol or fruit profiles, now restricted under FDA flavor bans in the United States and facing E.U. additive prohibitions.
- Rolling Paper:Pre-cut sheets for hand-rolling rituals, typically ultra-thin at 12-15 g/m² basis weight with gum arabic adhesive strips.
Volume placements concentrate in White Paper; the faster expansion belongs to Brown Paper.
Material:
Input fiber selection determines compliance pathways and premium positioning across regulatory jurisdictions with divergent heavy-metal and chemical disclosure standards.
- Hemp:Bast fiber from Cannabis sativa stalks processed through decortication and refining for natural-fiber positioning. Amsterdam and Barcelona specialty retailers curate hemp assortments with origin storytelling for millennial connoisseurs.
- Wood Pulp:Softwood kraft fibers from Scandinavian or Canadian sources providing cost-efficient basis for high-volume white paper grades. China's SAMR GB standards for heavy-metal content constrain import sourcing for domestic manufacturers.
- Rice:Cellulosic material from Oryza sativa straw offering ultra-thin gauge capability and slow burn characteristics prized in Japanese hand-rolling traditions.
- Recycled Fibers:Post-consumer pulp streams with variable contamination profiles that complicate REACH and FDA additive disclosure compliance.
Wood Pulp anchors volume throughput; Hemp climbs the fastest on premium positioning.
Thickness:
Gauge specification directly correlates with air dilution engineering and tar delivery profiles, creating tiered qualification barriers for mill technical capability.
- Ultra-Thin:Sub-20 g/m² basis weight requiring specialized wet-end forming and calendering equipment concentrated in Austrian and German integrated pulp-to-reel operations. E.U. Tobacco Products Directive ignition propensity mandates are accelerating specification demand for controlled porosity in this gauge band.
- Thin:20-25 g/m² standard for premium machine-made segments balancing structural integrity with air dilution performance.
- Medium:25-30 g/m² utility grade for emerging market price-sensitive production.
- Thick:Above 30 g/m² for specialty cigarillo and pipe-hybrid formats with extended burn duration requirements.
Thin grades dominate current volume; Ultra-Thin posts the steepest expansion trajectory.
Application:
End-use channel structure determines distribution pathways, with machine-made formats captive to tobacco manufacturer procurement and hand-rolled segments opening direct-to-consumer e-commerce.
- Machine-Made Cigarettes:Continuous reel supply to high-speed tipping and rolling equipment with 15-80 CU porosity bands specified by brand formulation. SWM International and Delfort Group AG anchor supply contracts with Philip Morris International and British American Tobacco manufacturing networks across Poland and the United States.
- Hand-Rolled Cigarettes:Consumer-cut sheets or booklet formats bypassing traditional tobacco distribution monopolies. London, Berlin, and Amsterdam boutique channels are capturing margin multiples through curated hemp and flax assortments with third-party additive-free certification.
- Pre-Rolled Cones:Factory-formed paper tubes for commercial filling operations serving convenience retail in North American cannabis-adjacent markets.
- Others:Specialty formats including pipe filters and herbal smoking blends with niche volume profiles.
Machine-Made Cigarettes retain volume concentration; Hand-Rolled Cigarettes gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flax fiber harvests in France and Belgium anchor raw-material supply for ultra-thin cigarette paper manufacturing, creating geographic concentration that shapes procurement patterns across downstream markets.
United States
FDA additive disclosure mandates and EPA emissions testing requirements constrain formulation flexibility for domestic manufacturers. The U.S. market exhibits accelerating displacement of traditional combustible tobacco by non-combustible nicotine delivery systems in urban centers. Chicago and Los Angeles specialty retailers curate hemp-based rolling paper assortments targeting millennial and Gen-Z connoisseur segments.
Germany
E.U. REACH compliance costs extend qualification timelines for new paper formulations by 18-24 months, reshaping R&D priorities across Central European mills. The Tobacco Products Directive mandates for reduced ignition propensity accelerate demand for specialty papers with controlled porosity. Integrated pulp-to-reel operations in Lower Saxony and Baden-Württemberg sustain manufacturing scale for premium machine-made segments.
Indonesia
Domestic specialty paper capacity expansion creates regional export hubs serving Southeast Asian markets with localized specification compliance. Machine-made cigarette production concentrates in Java-based manufacturing corridors aligned with multinational tobacco procurement networks. Jakarta and Surabaya anchor distribution infrastructure for both local consumption and cross-border supply to Philippines and Vietnam.
China
SAMR enforces national GB standards for paper heavy-metal content and burn residue that govern import access and domestic production licensing. Wood pulp sourcing from Scandinavian and Canadian origins faces compliance scrutiny under heavy-metal thresholds. Shanghai and Guangdong manufacturing clusters balance cost-efficient volume production with evolving export qualification requirements.
Netherlands
Amsterdam boutique tobacco channels capture margin multiples through curated hemp and flax paper assortments with third-party additive-free certification. Urban millennial consumers migrate toward hand-rolling rituals as premium experiences, displacing machine-made volume in metropolitan retail. Rotterdam distribution infrastructure supports re-export positioning across North European connoisseur segments.
Cigarette Paper Market Vendor Landscape
Global majors compete with regional champions across specification engineering and procurement contract stability, creating tiered competitive dynamics where scale-driven reel suppliers coexist with boutique channel specialists. Market structure consolidates around integrated pulp-to-reel operators with captive fiber supply chains and independent converters serving hand-rolled segments. Three archetypes dominate: European integrated manufacturers with backward fiber control, Asian volume producers serving machine-made contracts, and specialty brands bypassing traditional distribution through direct-to-consumer channels. Competitive moves center on capacity restructuring toward thin-gauge grades and third-party certification investments for additive-free positioning.
Within the integrated manufacturing tier, SWM International and Delfort Group AG exemplify archetypes of fiber-integrated scale, with the former leveraging North American flax supply positioning and the latter anchoring Central European pulp-to-reel operations. Miquel y Costas & Miquel S.A. occupies a specialist position representing Mediterranean-market watermarking and burn-rate control capabilities. These three entities collectively illustrate how geographic fiber access and regulatory pre-qualification create defensive positioning across contract-renewal cycles with multinational tobacco manufacturers.
| Leading Market Players |
|---|
| SWM International |
| Delfort Group AG |
| Miquel y Costas & Miquel S.A. |
| Republic Technologies |
| The Rolling Paper Company |
| Nippon Paper Papylia Co. Ltd. |
| Glatz Feinpapiere |
| BMJ |
| Mudanjiang Hengfeng Paper |
| Others |
Supply Flow & Price Mechanics
Flax fiber spot pricing in Western Europe cascades through cigarette paper supply chains into three distinct procurement tiers, with ultra-thin grades commanding premium multiples while standard machine-made reels absorb contract volatility through annual price-adjustment clauses.
Pricing Analysis
Service bundling separates qualified supply contracts from spot-market transactions, with multinational tobacco manufacturers purchasing multi-year reel supply agreements that embed technical support and burn-rate calibration. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with E.U. REACH-compliant additive-free papers capturing the widest spreads. Pricing pressure stems from flax harvest volatility in France and Belgium that mills cannot fully pass through to machine-made contract holders. Boutique retail channels exhibit the lowest price sensitivity, while emerging-market volume producers face the tightest margin compression.
Supply Chain Analysis
Dual-sourcing mandates from Philip Morris International and British American Tobacco require mills to maintain qualified production across at least two integrated pulp-to-reel facilities. Geographic supply concentration centers on Austria, Germany, and Indonesia, with raw material dependencies spanning French flax bast, Scandinavian softwood pulp, and Chinese hemp fiber decortication. Single-source vulnerability in Western European flax harvesting exposes mills to input cost spikes during poor weather cycles. Distribution runs through direct mill-to-manufacturer reel supply for machine-made segments, while hand-rolled channels bypass traditional tobacco monopolies via direct-to-consumer e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where E.U. REACH ingredient transparency mandates erect qualification barriers that protect pre-certified integrated manufacturers from commodity competition.
For Market Incumbents: Anticipate cellulose acetate filter alternatives and non-combustible nicotine systems eroding machine-made volume in North American and Western European urban centers. Defensive positioning requires deepening backward integration into French flax supply contracts and accelerating third-party additive-free certification investments for boutique channel access. Capacity restructuring toward ultra-thin gauge production in Austrian and German integrated mills sustains contract renewal leverage with multinational tobacco procurement networks. For New Entrants and Emerging Players: Direct-to-consumer e-commerce routes unlock margin capture and consumer data ownership in hand-rolled segments previously blocked by traditional tobacco distribution monopolies. White-space targets include hemp-based rolling paper assortments for Amsterdam, Berlin, and London boutique retailers, plus additive-free certification positioning for Western European connoisseur channels. Go-to-market execution should prioritize third-party verified natural claims that command 40-60% price multiples over standard grades. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated pulp-to-reel operators with captive fiber supply chains in Central Europe, where REACH compliance costs have extended qualification timelines and weakened undercapitalized competitors. Long-term viability over a multi-year horizon hinges on regulatory pre-qualification moats rather than pure manufacturing scale. The inflection signal to watch is alignment announcements from Brazil or Indonesia with OECD-style emissions frameworks, which would redirect specification demand toward E.U.-pre-qualified supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flax Fiber Supply | Captive sourcing from French and Belgian harvests stabilizes input cost predictability for ultra-thin grades. |
| Third-Party Additive-Free Certification | Verified natural claims unlock 40-60% price multiples in Amsterdam, Berlin, and London boutique channels. |
| Ultra-Thin Gauge Capacity Expansion | E.U. Tobacco Products Directive ignition propensity mandates accelerate specification demand for sub-20 g/m² production. |
| Direct-to-Consumer E-Commerce Launch | Bypassing traditional tobacco distribution monopolies captures margin and consumer data in hand-rolled segments. |
| Multi-Jurisdiction Regulatory Pre-Qualification | Simultaneous FDA, REACH, and SAMR compliance creates defensive positioning for contract renewal cycles. |
Methodological Framework
Trade association filings, customs and import-export databases, and SEC 10-K disclosures from publicly traded paper manufacturers formed the secondary backbone of this analysis. Primary interviews with specialty paper mill technical directors, multinational tobacco procurement managers, boutique tobacco retail buyers, and E.U. regulatory affairs consultants validated secondary findings. Bottom-up and top-down triangulation reconciled production capacity estimates with end-use consumption patterns across machine-made and hand-rolled segments.
Historical trendline analysis established baseline growth trajectories across white, brown, and specialty paper grades, with segmentation modeling across material type, thickness gauge, and application channel. CAGRs were derived through regression analysis of volume and value outputs across the projection horizon. Industry-specific forecast inputs included flax fiber harvest yields, E.U. Tobacco Products Directive implementation timelines, and Indonesia domestic capacity expansion announcements.
The model holds under stable regulatory implementation schedules; deviation in REACH enforcement intensity or accelerated OECD alignment in Brazil and Indonesia would shift specification demand and regional competitive positioning materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco
US Tobacco Market
Tobacco
Egypt Tobacco Market
Tobacco
Tobacco Cutting Machines Market
Tobacco
Tobacco Films Market
Tobacco
Low Tar Cigarette Paper Market
Tobacco
Cigarette Rolling Paper Market
Tobacco
North America Tobacco Market
Tobacco
North America Cigarette Market
Tobacco
Organic Tobacco Market
Tobacco
Heat-Not-Burn Market
Tobacco
Middle East and Africa Smokeless Tobacco Market