
 Horizontal Strapping Machine Market | 2026-2036
Horizontal Strapping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Strapping Machine Market Foresight
Aftermarket service revenue is reshaping profit pools away from pure equipment sales toward lifecycle contracts. Signode Industrial Group leverages its global parts network to capture recurring maintenance spend. FROMM Packaging Systems anchors its position through field service density in European logistics corridors. Dynaric Inc specializes in retrofit automation kits that extend existing machine life.
A horizontal strapping machine applies tensioned bands around boxes, pallets, or bundles using a horizontally oriented arch or head, typically processing PET, PP, or steel strap at speeds from 20 to 60 cycles per minute for load containment in shipping and warehousing. The automatic segment leads unit volume as warehouse labor costs push facilities toward unattended palletizing lines. Semi-automatic equipment retains share among mid-tier electronics contract manufacturers with variable batch sizes. Food and beverage end users increasingly specify stainless steel construction to meet washdown requirements.
Germany's Packaging Act and the EU Green Deal shape material choices by penalizing non-recyclable strapping in cross-border freight. FDA and USDA requirements in the United States enforce hygienic design standards for machines contacting food-contact packaging surfaces. Stakeholders must monitor how evolving extended producer responsibility rules alter total cost of ownership calculations across regional supply chains.
Market Dynamics
Lifecycle service contracts are displacing equipment-only transactions as warehouse operators seek predictable maintenance spend and maximum uptime guarantees across automated fulfillment lines.
Growth Catalysts
- E-commerce fulfillment automation:Parcel volume surges through Shanghai and Guangzhou distribution hubs are mandating unattended strapping at palletizing terminals.
- EU Green Deal packaging mandates:Penalties on non-recyclable transport materials are accelerating PET strap conversion from steel in cross-border freight corridors.
- Stainless steel washdown specifications:Food and beverage processors are retrofitting existing lines to meet FDA and USDA hygienic design standards for food-contact surfaces.
Market Restraints
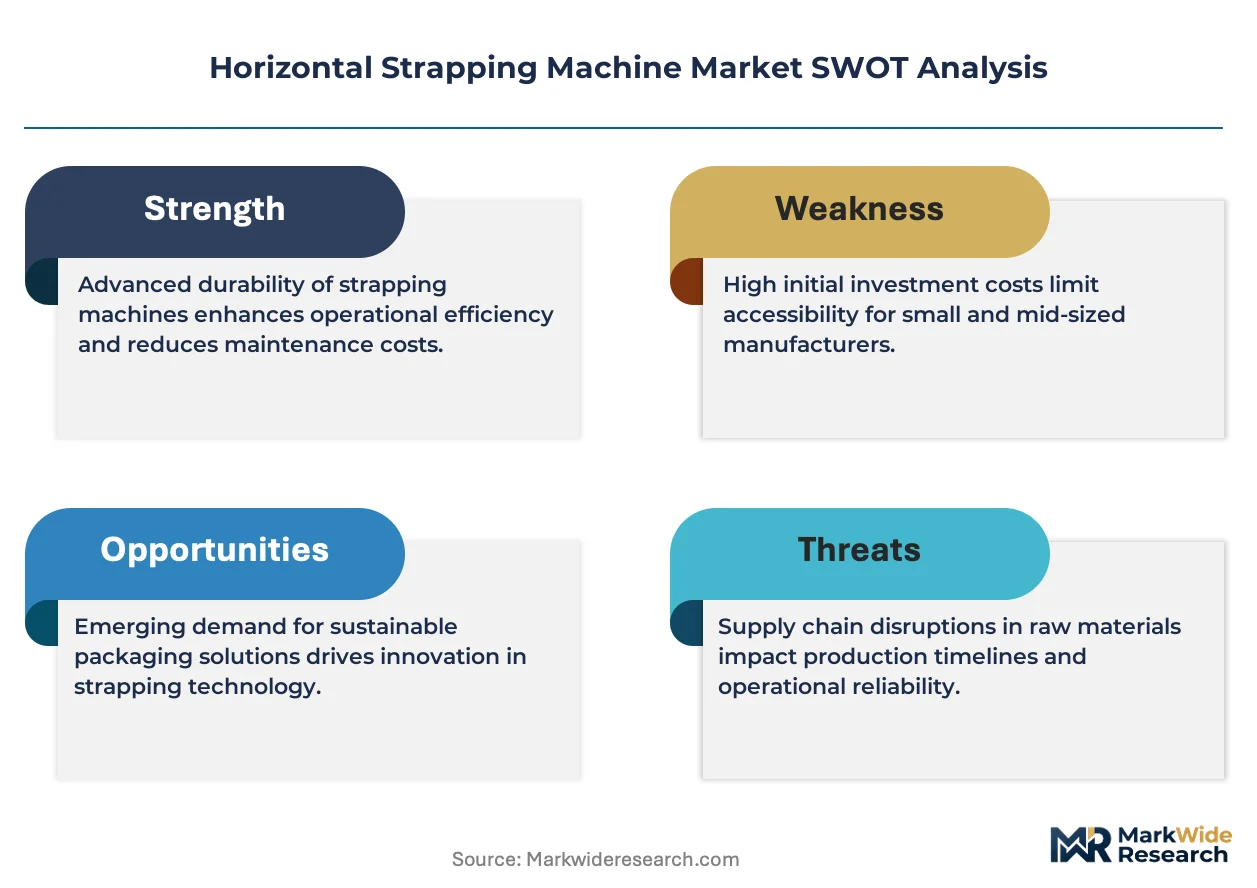
- Steel strap price volatility:Raw material input swings compress margin predictability for manufacturers serving heavy-load industrial segments.
- Regional supply concentration:Arch welding and tension head fabrication capacity clusters in Germany's industrial belt, creating geographic vulnerability.
- Technical speed ceilings:Mechanical arch cycling limits constrain throughput below 60 cycles per minute regardless of downstream conveyor velocity.
Strategic Opportunities
- Indian logistics modernization:Cold chain infrastructure buildout under PLI scheme incentives creates first-mover positioning for automated strapping at pharmaceutical distribution centers.
- Battery supply chain localization:Cell and pack manufacturers in Michigan and South Carolina require specialized strap containment for lithium-ion pallet shipments.
- Retrofit automation kits:Semi-automatic equipment bases in mid-tier electronics contract manufacturing represent addressable upgrade volume without greenfield capex.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of servo-driven tension systems requires cross-trained personnel combining mechanical and PLC diagnostics capabilities.
- Legacy integration complexity:Brownfield warehouse management system interfaces demand custom middleware development for real-time cycle signaling.
- Extended certification timelines:USDA hygienic design validation for food-contact machine surfaces adds quarters to product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horizontal Strapping Machine Market |
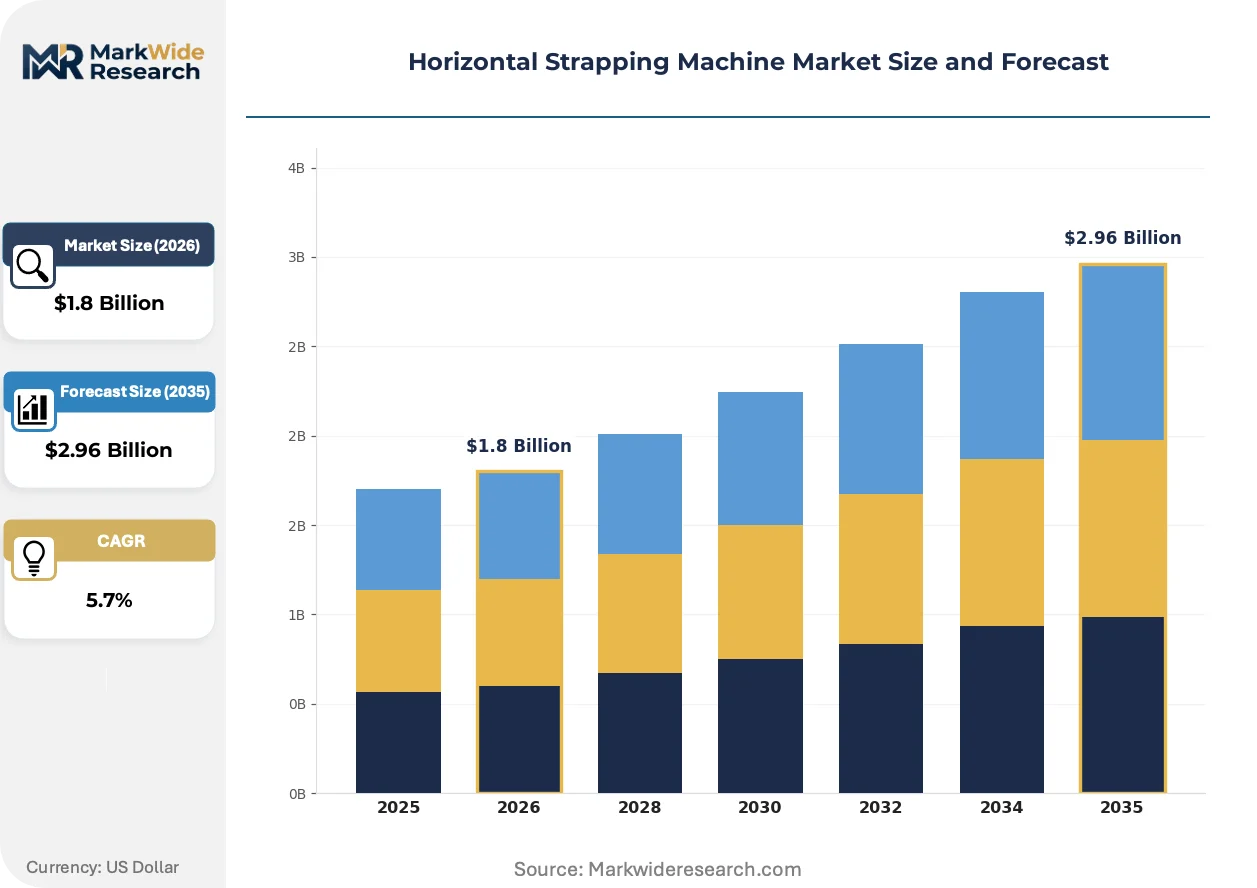
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
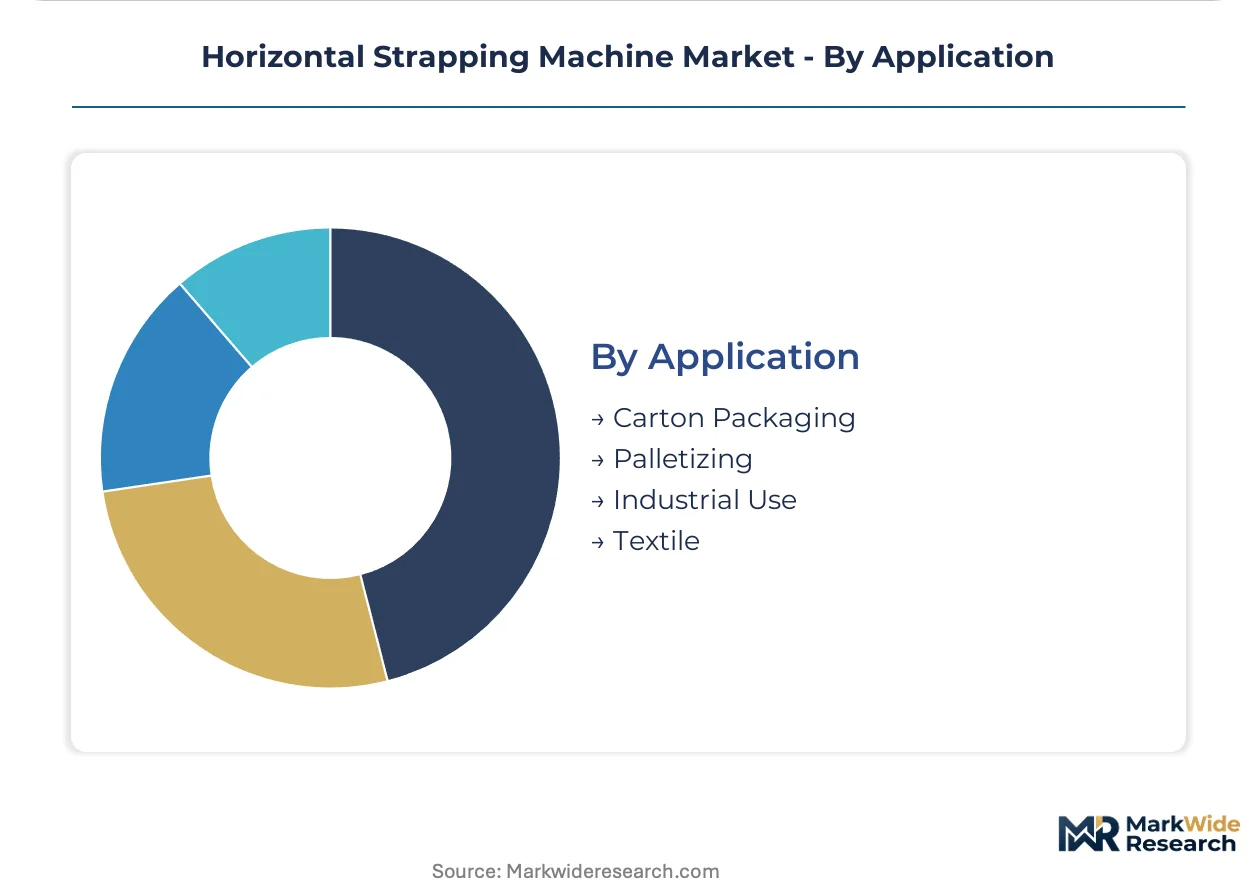
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Customized End User: Aerospace, Electronics, Packaging, Food & Beverage Material: PET, PP, Steel, Aluminum Application: Carton Packaging, Palletizing, Industrial Use, Textile |
| Companies Covered | Signode Industrial Group, Dynaric Inc, FROMM Packaging Systems, Transpak Equipment Corp, M.H. Packaging, Mosca GmbH, Cyklop International, Messersì Packaging S.r.l., StraPack Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Strapping Machine Market Shifts & Advancements
Digitalization of maintenance workflows and material science advances in recycled-content strapping are compressing total cost of ownership calculations while reshaping supplier-customer relationships.
Ultrasonic welding heads are collapsing the mechanical complexity of traditional heat-seal and friction-weld systems. Pharmaceutical and electronics contract manufacturers are specifying these units for cleanroom-adjacent operations where particulate generation must be minimized. The technology is collapsing differentiation between premium and mid-tier equipment tiers as reliability curves converge.
Germany's Packaging Act enforcement is tightening material traceability requirements for transport packaging entering the circular economy. Industrial users must now document strap polymer composition and recycling pathway eligibility. Food and beverage exporters are most exposed, with many accelerating supplier audits to preempt compliance penalties.
Service unbundling is fragmenting traditional equipment-plus-maintenance bundles into discrete subscription tiers. Third-party logistics operators in the Netherlands and Belgium are piloting usage-based contracts where per-cycle fees replace capital expenditure. This shift concentrates bargaining power with multi-site fleet operators capable of standardizing across facilities.
Horizontal Strapping Machine Market Segmentation
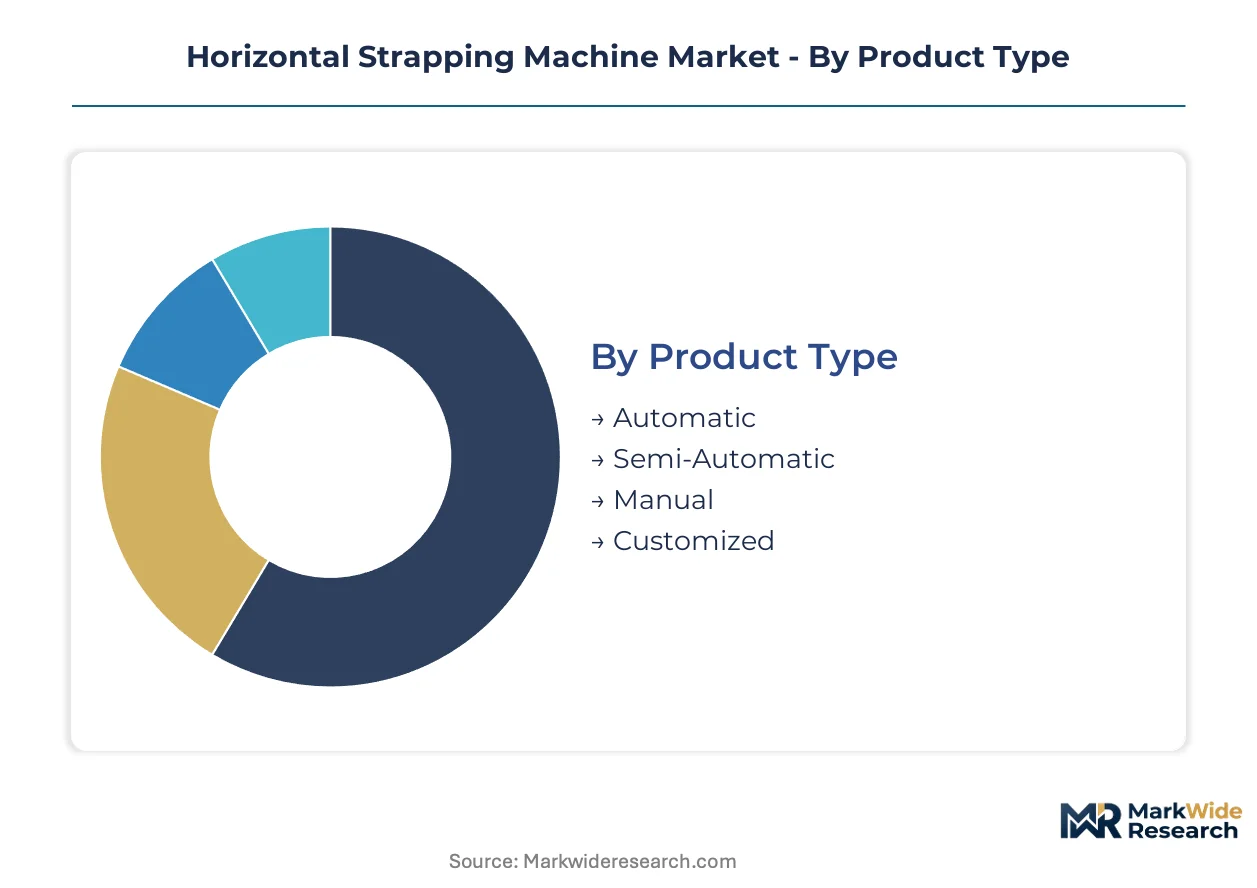
Horizontal strapping machines serve divergent operational profiles across fulfillment velocity tiers and material handling environments. Equipment specification, strap chemistry, and arch cycling speed must align precisely with pallet throughput requirements and downstream conveyor integration.
Product Type:
Cost tier differentiation separates unattended high-volume installations from operator-dependent batch processing environments.
- Automatic:Servo-driven tension systems cycle at 40-60 straps per minute with PLC-coordinated conveyor signaling. Warehouse labor cost pressures in Shanghai and Guangzhou distribution hubs are accelerating procurement for palletizing terminal integration.
- Semi-Automatic:Operator-fed strap threading with motorized tensioning accommodates variable batch sizes without full automation capex. Mid-tier electronics contract manufacturers in Shenzhen retain this equipment for fluctuating production schedules.
- Manual:Hand-cranked tensioning with mechanical sealing suits low-volume repair shops and field service operations.
- Customized:Modified arch dimensions and strap width accommodation address non-standard load geometries in aerospace component packaging.
Automatic equipment commands the established base. The steepest expansion runs through Semi-Automatic retrofit automation kits.
End User:
Application-specific contamination control and load security requirements shape stainless steel specification and tension calibration protocols.
- Food & Beverage:USDA and FDA hygienic design mandates enforce 304 or 316 stainless steel construction with sloped surfaces for washdown compatibility. Processors in California's Central Valley are retrofitting existing lines to meet food-contact surface validation.
- Electronics:Cleanroom-adjacent operations specify ultrasonic welding heads to eliminate particulate generation from friction-weld debris. Contract manufacturers in Taiwan and South Korea prioritize strap containment integrity for semiconductor shipment protection.
- Packaging:Third-party logistics operators standardize across multi-site fleets with usage-based per-cycle contracting replacing capital expenditure.
- Aerospace:Non-marring strap materials and calibrated low-tension settings prevent surface damage to precision-machined components.
Food & Beverage anchors procurement volume. Electronics is climbing the fastest on cleanroom specification premiums.
Material:
Polymer chemistry and metallurgical grade determine recyclability credentials, tensile strength, and cross-border freight compliance exposure.
- PET:Post-consumer recycled content grades satisfy EU Green Deal traceability requirements for circular economy eligibility. Germany's Packaging Act enforcement is accelerating conversion from steel in cross-border corridors.
- PP:Lower density and cost position this material for lightweight carton containment where ultimate tensile strength is secondary.
- Steel:High-tensile zinc-coated grades retain dominance in heavy-load industrial segments despite raw material price volatility.
- Aluminum:Corrosion-resistant lightweight specification serves chemical and pharmaceutical exports with moisture-exposure risk.
Steel strap commands the established base. PET is gaining share fastest on regulatory compliance premiums.
Application:
Load geometry and downstream handling intensity dictate arch configuration, strap width, and cycle speed requirements.
- Palletizing:Full-automatic arch systems with conveyor integration secure unitized loads at 20-60 cycles per minute for high-velocity fulfillment lines.
- Carton Packaging:Semi-automatic and automatic variants seal individual boxes prior to palletization with width-adjustable heads.
- Industrial Use:Heavy-gauge steel strapping contains metal coils, lumber bundles, and construction materials with calibrated high-tension settings.
- Textile:Low-tension specification prevents compression damage to fabric rolls and garment bales during export preparation.
Palletizing commands the established base. Carton Packaging is expanding most quickly on e-commerce parcel volume surges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German manufacturers prioritize regulatory-compliant PET conversion, while Chinese operators optimize for velocity at e-commerce hubs, and US food processors drive stainless steel specification premiums.
United States
FDA and USDA hygienic design mandates are accelerating stainless steel retrofit demand among California Central Valley food processors. The Inflation Reduction Act's domestic manufacturing incentives are reshaping capital equipment sourcing patterns. Michigan and South Carolina battery supply chain localization is creating specialized demand for lithium-ion pallet containment systems.
Germany
The Packaging Act's escalating recycling rate targets are forcing rapid PET strap conversion from steel in cross-border freight corridors. ECHA chemical registration requirements are tightening material traceability documentation. Industrial belt concentration around Stuttgart and Munich is driving arch welding and tension head fabrication capacity expansion.
China
Shanghai and Guangzhou distribution hubs are mandating unattended automatic strapping at palletizing terminals to match e-commerce parcel velocity. MIIT smart logistics initiatives are accelerating PLC-integrated equipment procurement. Yangtze River Delta manufacturing clusters are standardizing on servo-driven tension systems for export packaging compliance.
India
PLI scheme incentives for cold chain infrastructure are creating first-mover positioning opportunities at pharmaceutical distribution centers. BIS certification requirements for industrial machinery are extending equipment validation timelines. Maharashtra and Gujarat logistics modernization projects are specifying automated strapping for temperature-controlled export corridors.
Japan
METI carbon neutrality roadmaps are pressuring steel strap users toward polymer alternatives in automotive component exports. JIS standards for packaging machinery are enforcing precision tolerances on tension calibration. Kansai region electronics contract manufacturers are specifying ultrasonic welding heads for cleanroom-adjacent semiconductor shipment protection.
Horizontal Strapping Machine Market Competitive Landscape
Capability concentration sits with specialized European fabricators; scale advantage sits with diversified industrial conglomerates. The vendor base organizes into three tiers: integrated strapping system houses with global parts networks, regional machinery specialists with dense field service coverage, and component-focused retrofit automation providers. Consolidation pressure runs through lifecycle service contract bundling, while differentiation shifts toward material science partnerships and digital maintenance platform integration.
Among North American equipment providers, Signode Industrial Group and Dynaric Inc exemplify contrasting strategic positions. Signode represents the integrated system house archetype with extensive aftermarket infrastructure. Dynaric occupies the retrofit specialization tier, anchoring its market presence through automation kit development rather than greenfield equipment sales. FROMM Packaging Systems, with its European GmbH structure, sits within the regional specialist category, leveraging geographic proximity to German logistics corridors for service density advantages.
| Leading Market Players |
|---|
| Signode Industrial Group |
| Dynaric Inc |
| FROMM Packaging Systems |
| Transpak Equipment Corp |
| M.H. Packaging |
| Mosca GmbH |
| Cyklop International |
| Messersì Packaging S.r.l. |
| StraPack Inc. |
| Others |
Supply & Pricing Matrix
Steel strap price volatility compresses margin predictability for manufacturers serving heavy-load industrial segments, forcing three-tier pricing stratification across premium servo-driven systems, standard automatic equipment, and economy semi-automatic variants while simultaneously concentrating arch welding and tension head fabrication capacity in Germany's industrial belt.
Pricing Analysis
Long-term lifecycle service contracts now dominate procurement relationships, displacing spot equipment transactions as warehouse operators seek predictable maintenance spend and maximum uptime guarantees. Price differentiation hinges on stainless steel certification grade for food-contact surfaces and the density of field service coverage in logistics corridors. Cost compression in mid-tier electronics contract manufacturing intensifies as variable batch sizes delay full automation capex. Third-party logistics operators exhibit lowest price sensitivity due to usage-based per-cycle contracting, while mid-tier electronics manufacturers face acute pressure from fluctuating production schedules.
Supply Chain Analysis
Extended payment terms from European OEM procurement teams are reshaping supplier financing structures, particularly for arch welding subcontractors in Stuttgart and Munich industrial clusters. Component fabrication draws from Germany, China, and Italy, with servo motors and PLC controllers resting on semiconductor supply from Taiwan and South Korea. Single-source vulnerability concentrates in specialized tension head assemblies where regional fabrication capacity lacks redundancy. Distribution feeds from integrated system houses with captive aftermarket parts networks through regional machinery specialists with dense field service coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as FDA and USDA hygienic design validation requirements and EU Green Deal material traceability mandates create multi-quarter barriers to product launch for unqualified competitors.
For Market Incumbents: Pre-empt emerging retrofit automation specialists by accelerating backward integration into ultrasonic welding head production and expanding stainless steel fabrication capacity in Michigan to serve battery supply chain localization. Lock in lifecycle service contract renewals before third-party logistics operators consolidate multi-site fleet standardization. Prioritize certification investment for USDA hygienic design validation to extend regulatory entrenchment.
For New Entrants and Emerging Players: Pursue pharmaceutical distribution center automation in India where PLI scheme cold chain infrastructure buildout creates first-mover positioning without incumbent service density. Target semi-automatic retrofit kits for mid-tier electronics contract manufacturers in Shenzhen seeking variable batch flexibility without greenfield capex. Anchor go-to-market strategy through PLC-integrated equipment partnerships with MIIT smart logistics initiative beneficiaries.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional machinery specialists with dense field service coverage and material science partnerships. Long-term viability rests on capturing recurring aftermarket revenue streams rather than equipment-only transactions. Acquisition targets should demonstrate ultrasonic welding head capabilities or stainless steel hygienic design certification. Watch for inflection in extended producer responsibility enforcement intensity across EU member states.
| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contract Bundling | Captures recurring maintenance spend from Signode Industrial Group's global parts network model. |
| Ultrasonic Welding Head Development | Eliminates particulate generation for Taiwan semiconductor contract manufacturers' cleanroom specifications. |
| Stainless Steel Capacity Expansion | Addresses FDA and USDA mandates for California Central Valley food processor retrofit demand. |
| PET Strap Material Partnership | Satisfies Germany's Packaging Act traceability requirements for circular economy eligibility. |
| Retrofit Automation Kit Launch | Unlocks upgrade volume from Shenzhen electronics manufacturers without greenfield capital expenditure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across maintenance directors at e-commerce fulfillment centers, plant engineers in food and beverage processing, OEM procurement teams at battery cell manufacturers, aftermarket service heads at integrated system houses, and technical R&D directors at strapping material suppliers. Secondary validation drew from SEC 10-K filings, customs and trade data for strapping equipment imports, FDA and USDA equipment validation databases, and EU ECHA chemical registration records. Bottom-up equipment shipment tallies and top-down industrial capital expenditure estimates were triangulated to anchor market sizing.
Calibration against historical procurement patterns and regulatory implementation timelines shaped the analytical framework across the modeling period. Segmentation dimensions included product type tier, end-use industry vertical, strap material chemistry, and arch cycling speed specification. CAGRs were derived from equipment replacement cycles, e-commerce parcel velocity trajectories, and regulatory compliance deadline clustering. Industry-specific inputs incorporated MIIT smart logistics initiative procurement schedules and PLI scheme cold chain infrastructure rollout pacing.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or acquisition moves by diversified industrial conglomerates would shift outcomes beyond modeled parameters. Macroeconomic deviation in steel and polymer input costs, regulatory acceleration in extended producer responsibility enforcement, or technological breakthrough in friction-weld alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Side Sealer Machines Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Glazing Machine Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Injection Blow Molding Machine Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Deblistering Machines Market