
 Household Sewing Machines Market | 2026-2036
Household Sewing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Household Sewing Machines Market Analytics
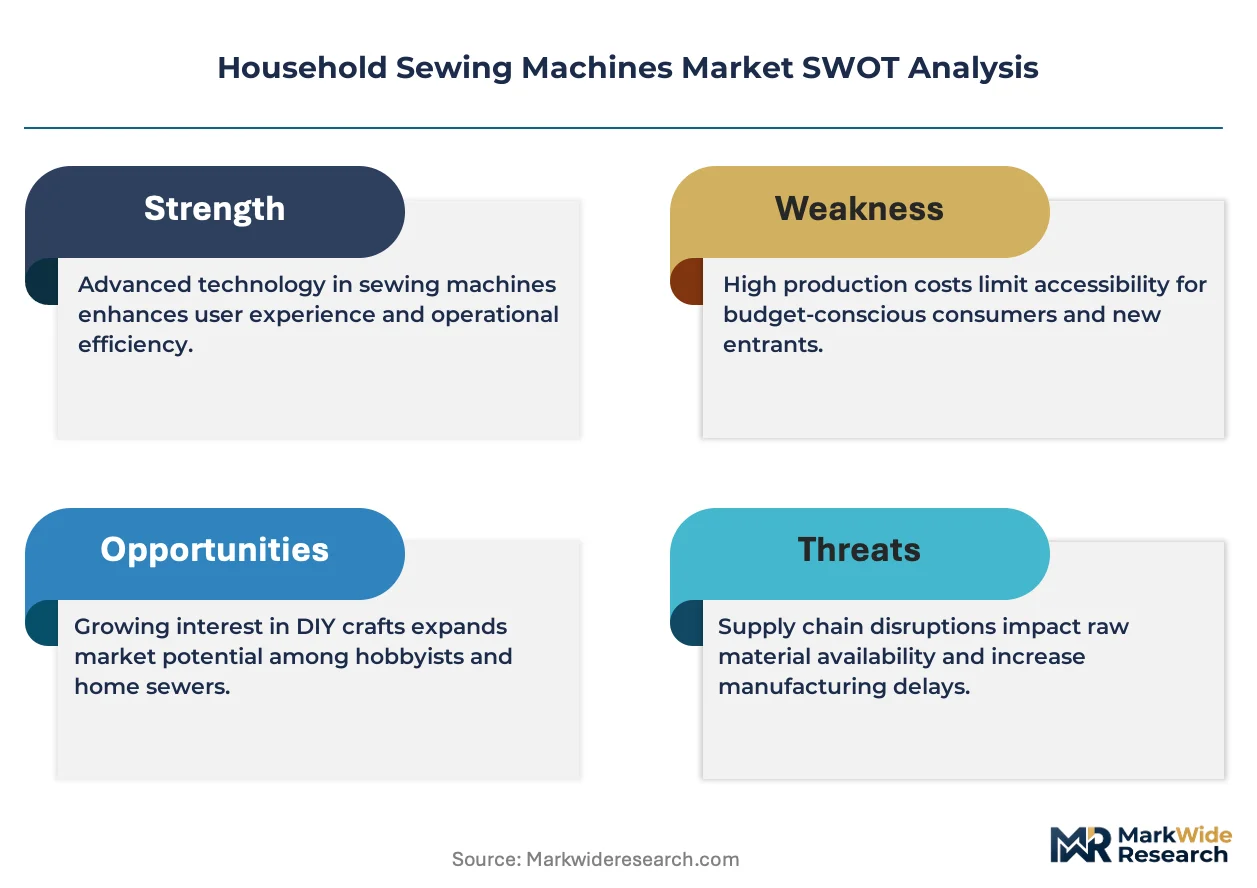
REACH substance restrictions on chromium and nickel alloys in metal components is realigning the cost-of-entry calculus for European-market household sewing machines, forcing suppliers to certify alternative materials or absorb expensive third-party testing. Brother Industries leverages its captive motor manufacturing in Zhuhai to sustain margin control despite these compliance burdens. Bernina International anchors its premium positioning through Swiss-based final assembly and vertically integrated stitch-pattern software development. JUKI Corporation competes aggressively in the heavy-duty portable segment, where industrial-grade reliability commands pricing power among serious hobbyists and small tailoring operations.
Household sewing machines constitute motorized fabric-joining appliances designed for non-industrial use, typically operating at stitch speeds between 300 and 1,500 stitches per minute through lockstitch, chain stitch, or overlock mechanisms, with primary commercial purpose centered on garment construction, home textile fabrication, and craft-based entrepreneurship. Electronic and computerized product types now capture the dominant share of value generation, as programmable stitch libraries and touchscreen interfaces justify premium pricing against declining mechanical unit sales. Hobbyist and designer end users represent the fastest-expanding demand pool, with social commerce platforms enabling direct monetization of custom apparel and quilted goods that rewards feature-rich machine investments.
The EU F-Gas Regulation and Ecodesign Directive increasingly govern motor efficiency and refrigerant-based cooling systems in computerized units, while the US Consumer Product Safety Commission enforces cord-safety and tip-over standards that shape domestic product liability exposure. Japan's METI maintains JIS standards for electromagnetic compatibility that constrain feature integration timelines for brands targeting that market. Stakeholders must monitor how divergent efficiency mandates across Brussels, Washington, and Tokyo fragment certification requirements and determine whether regional SKU specialization or unified global platforms better serve cost structures.
Market Dynamics
Social commerce monetization is restructuring household sewing machine demand, as hobbyists and micro-entrepreneurs on resale platforms require feature-rich electronic units capable of professional-grade output for craft-based income generation.
Growth Catalysts
- EU F-Gas Regulation:Motor efficiency mandates for computerized units are accelerating R&D investment in brushless DC motor architectures, pulling upgrade cycles from mechanical to electronic product categories.
- DIY apparel entrepreneurship:Resale platform economics reward custom garment production, expanding the addressable base beyond traditional domestic sewing into revenue-generating maker operations.
- Vietnam-Indonesia contract assembly:Scaled manufacturing clusters for Japanese and European brands are compressing landed costs for mid-tier electronic machines in Southeast Asian retail channels.
Market Restraints
- REACH substance restrictions:Chromium and nickel alloy limitations in metal components force costly material recertification or third-party testing for European-market entry.
- GB standards compliance:China's stricter household appliance energy efficiency rules raise certification burdens for imported electronic and computerized models.
- Mechanical unit substitution:Low-cost manual machines from unbranded Asian suppliers underprice electronic alternatives in price-sensitive developing markets.
Strategic Opportunities
- Indonesia domestic market:Underpenetrated middle-class households present white space for computerized machine adoption as contract manufacturing familiarity builds local brand recognition.
- Stitch-pattern software convergence:Integration of touchscreen interfaces with cloud-downloadable design libraries creates recurring revenue models beyond hardware sales.
- Social commerce distribution:Direct-to-maker sales channels bypass traditional retail markups while capturing demand from platform-native entrepreneurs.
Industry Challenges
- Electromagnetic compatibility certification:Japan's METI JIS standards constrain feature integration timelines for brands targeting that market, extending product development cycles.
- Multi-jurisdiction SKU fragmentation:Divergent efficiency mandates across Brussels, Washington, and Tokyo force decisions between regional specialization and compromised global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Sewing Machines Market |
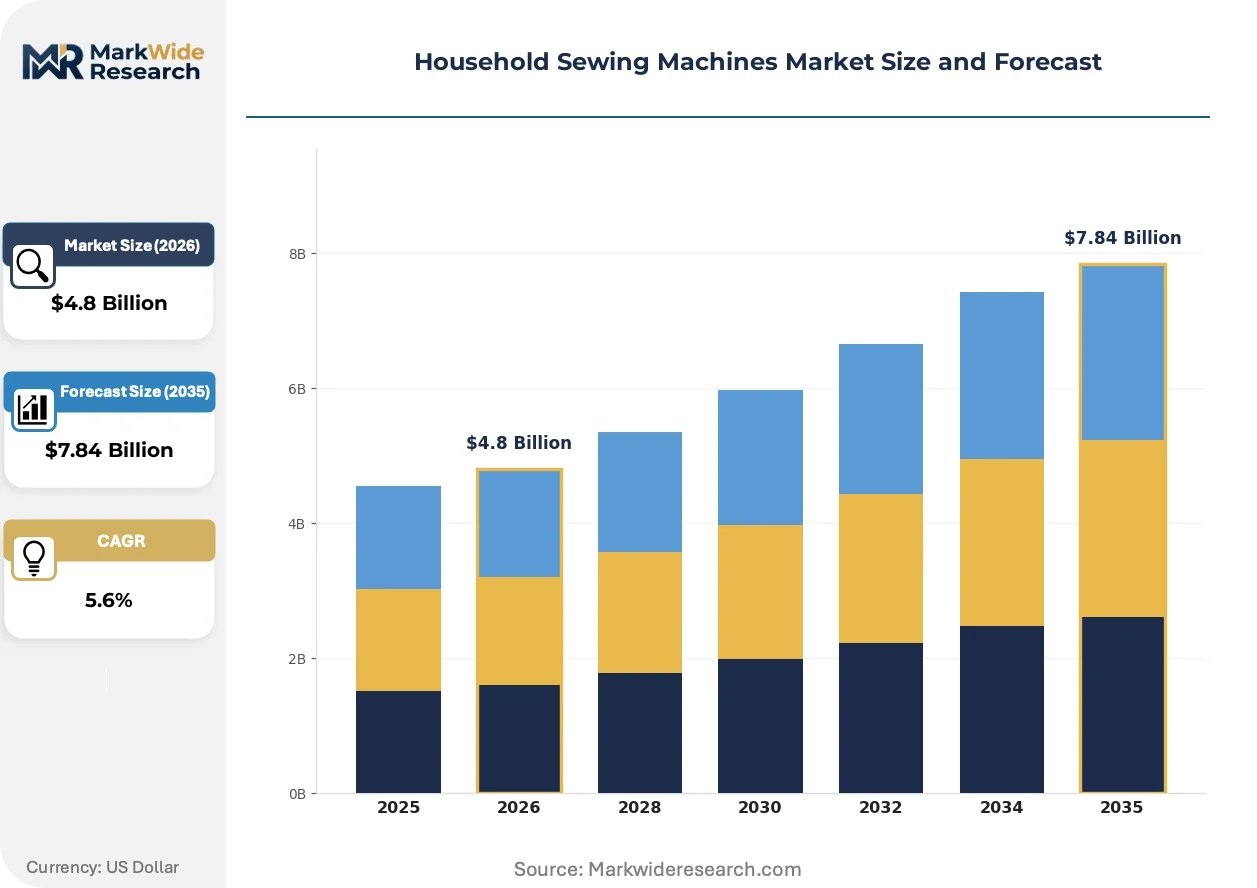
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Computerized, Overlock End User: Hobbyists, Tailors, Designers, Beginners Brand: Singer, Brother, Janome, Bernina Feature: Portable, Multi-Function, Heavy-Duty, Beginner-Friendly |
| Companies Covered | Janome Sewing Machine, Husqvarna, SVP Worldwide, Elna, Toyota Industries, Brother Industries, Bernina International, Pfaff, JUKI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Sewing Machines Market Evolving Landscape
Programmable automation and connected design ecosystems are displacing mechanical simplicity as the core value proposition, while regulatory pressure on materials and efficiency accelerates hardware architecture turnover.
Computerized stitch automation is automating pattern execution through servo-controlled needle positioning and programmable feed mechanisms. Serious hobbyists and small tailoring operations are adopting these systems fastest, compressing the skill barrier for complex decorative and functional stitching. This capability expansion is automating what previously required manual technique, enabling novice users to produce output quality that previously demanded years of training.
REACH substance restrictions on chromium and nickel alloys in metal components are forcing material substitutions across European-market supply chains. Suppliers must certify alternative alloys or absorb expensive third-party testing, raising effective cost-of-entry for new competitors. Electronic and computerized units with higher metal component counts face disproportionate compliance burden compared to simplified mechanical alternatives.
Platform-native craft entrepreneurs are unbundling after-sales service expectations, prioritizing video-based troubleshooting and peer community support over traditional dealer networks. This behavioral shift is disrupting established distribution models in North American and Western European markets where authorized retailer relationships previously dominated. Social commerce sellers specifically favor brands with robust online knowledge bases and direct parts availability over legacy service infrastructure.
Household Sewing Machines Market Segmentation
Household sewing machine purchasing decisions diverge sharply across technical sophistication, income-driven use cases, and maker-entrepreneur ambitions. Understanding these fault lines reveals where feature-rich electronic units command premium pricing versus where mechanical simplicity retains cost advantage.
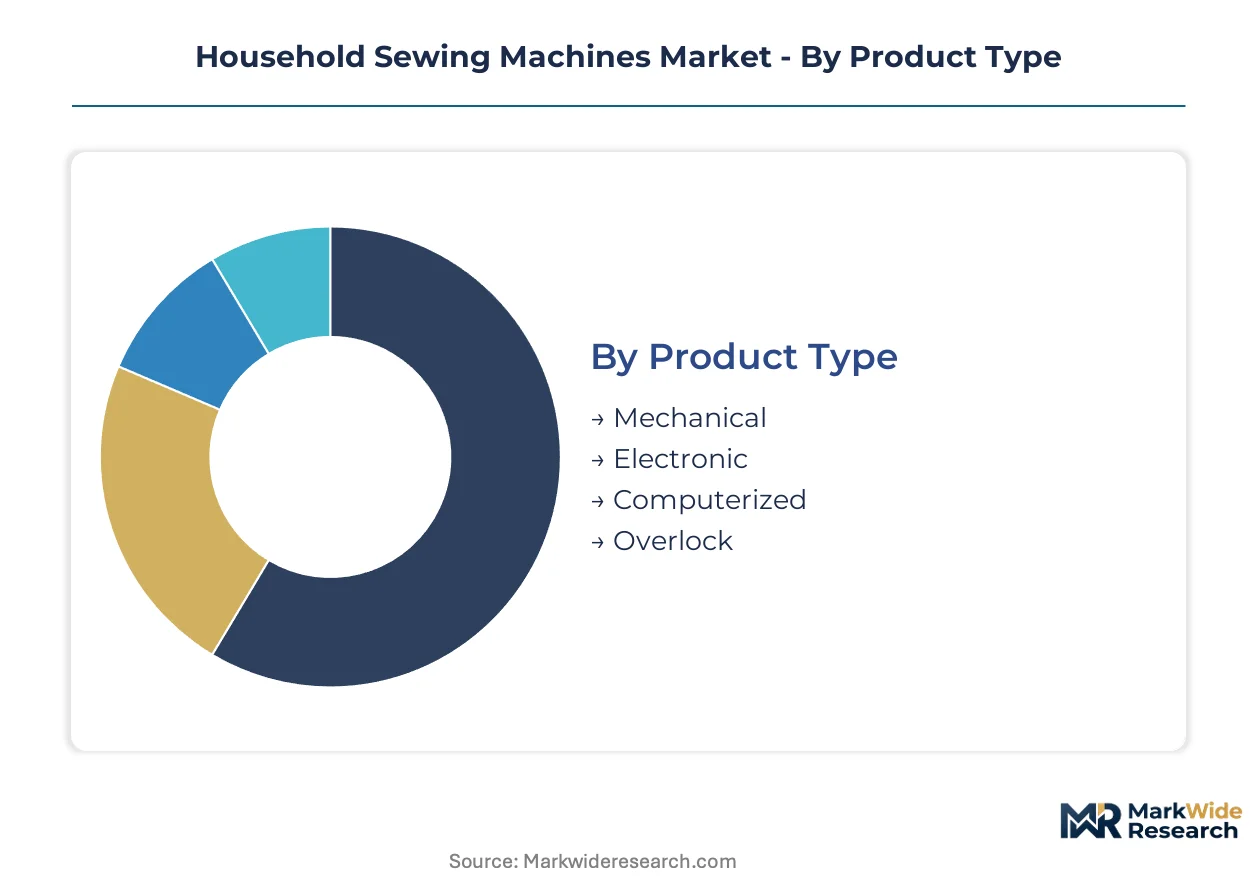
Product Type:
Cost tier separates casual domestic users from revenue-generating makers and professional-grade hobbyists.
- Mechanical:Spring-tension stitch control and manual feed mechanisms dominate entry-level price bands. Demand concentrates in rural India and Southeast Asian provinces where electrification remains intermittent and repair infrastructure favors mechanical simplicity.
- Electronic:Push-button stitch selection and LED displays bridge mechanical reliability with programmable convenience. Hobbyists monetizing craft output on resale platforms drive fastest expansion here, requiring professional-grade results without industrial floor space.
- Computerized:Touchscreen interfaces and USB-imported embroidery patterns justify premium positioning.
- Overlock:Three- and four-thread serging mechanisms serve garment finishing for micro-entrepreneurs.
Volume sits with Mechanical units in developing markets; growth tilts toward Electronic models among platform-native craft sellers.
End User:
Application intensity determines feature requirements and replacement frequency across buyer archetypes.
- Hobbyists:Weekend garment construction and quilt piecing demand versatile stitch libraries without industrial throughput. Social commerce monetization is reshaping this segment fastest, as Instagram and TikTok visibility rewards complex decorative techniques.
- Designers:Prototype development and small-batch production require precision feed systems and heavy-duty motor capacity. Independent fashion labels in Berlin, Milan, and Tokyo anchor demand concentration here.
- Tailors:Alteration services and custom fitting operations prioritize speed and durability over decorative functions.
- Beginners:First-time buyers favor automated threading and jam-resistant bobbin systems to reduce learning curves.
Revenue concentration favors Designers for margin per unit; steepest expansion trajectory belongs to monetizing Hobbyists.
Brand:
Customer type and geography dictate brand loyalty patterns more than raw feature comparisons.
- Singer:Heritage recognition and dealer network density sustain mechanical segment dominance in North American and Latin American markets.
- Brother:Captive motor manufacturing in Zhuhai enables cost-competitive electronic and computerized portfolios across Asian retail channels.
- Janome:Japanese engineering reputation commands loyalty among precision-focused quilters in Australia and New Zealand.
- Bernina:Swiss final assembly and proprietary stitch-pattern software anchor ultra-premium positioning for atelier-grade users.
Market share clusters with Brother for volume; margin capture tilts toward Bernina.
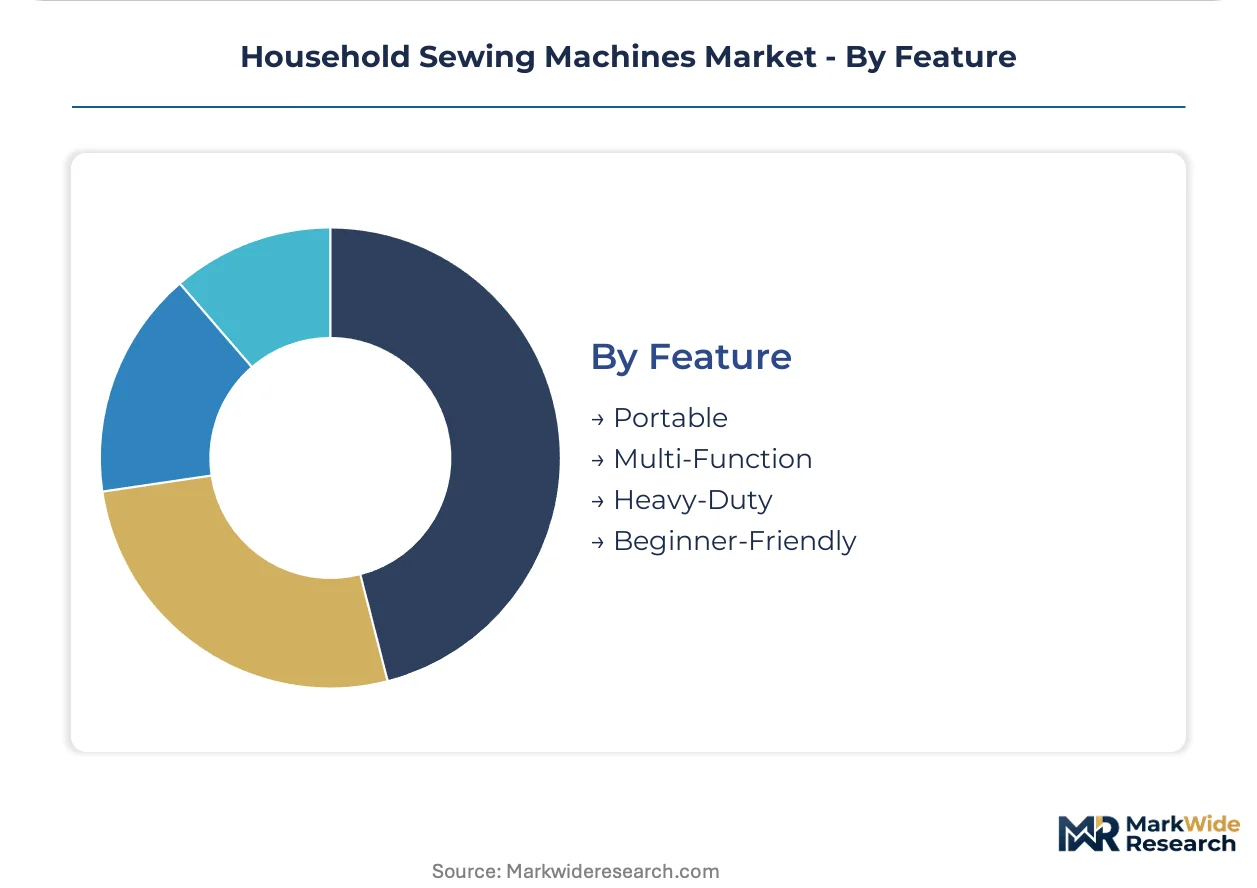
Feature:
Volume scale and use environment shape which capability bundles justify price premiums.
- Portable:Lightweight chassis and carrying cases serve apartment dwellers and maker-space renters. Urban Japan and South Korea show strongest demand concentration where living space constraints dominate purchase criteria.
- Heavy-Duty:Reinforced feed dogs and high-torque motors handle denim, canvas, and leather without slippage. Small tailoring operations in Istanbul, Mexico City, and Ho Chi Minh City drive replacement cycles here.
- Multi-Function:Combined sewing and embroidery capabilities reduce equipment footprint for home-based businesses.
- Beginner-Friendly:Automated tension adjustment and speed limiters reduce error rates for novice users.
Shipment volume aligns with Portable units; value expansion favors Heavy-Duty specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Southeast Asia are concentrating contract assembly capacity for Japanese and European brands, while domestic demand clusters in urban middle-class households across Indonesia and Vietnam.
China
GB standards for household appliance energy efficiency are tightening compliance requirements for imported electronic and computerized sewing machines. The MIIT enforces electromagnetic compatibility testing that extends product development timelines. Manufacturing activity concentrates in Zhuhai, where captive motor production supports cost-competitive electronic portfolios for Asian retail channels.
Japan
Precision-focused quilters and atelier-grade users drive premium-tier demand for heavy-duty portable specifications. METI maintains JIS standards that constrain feature integration timelines for brands targeting domestic consumers. Tokyo and Osaka anchor demand concentration, with Kansai-based operations serving small tailoring businesses requiring industrial-grade reliability.
Indonesia
Underpenetrated middle-class households present expansion opportunity as contract manufacturing familiarity builds local brand recognition. The country's national standards body implements appliance safety certification that shapes import dynamics. Jakarta and Surabaya host scaled assembly operations for European and Japanese brands, compressing landed costs for mid-tier electronic machines.
Vietnam
Rapid urbanization and rising craft-based entrepreneurship are expanding the addressable base beyond traditional domestic sewing. The Ministry of Industry and Trade oversees energy labeling requirements that influence product mix decisions. Ho Chi Minh City drives replacement cycles for heavy-duty specifications serving small garment finishing operations.
United States
Platform-native craft entrepreneurs on resale sites are reshaping distribution expectations toward direct-to-maker channels. The Consumer Product Safety Commission enforces cord-safety and tip-over standards that shape domestic product liability exposure. Urban maker spaces in Brooklyn, Austin, and Portland favor portable units with cloud-downloadable design libraries.
Household Sewing Machines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price bands. The vendor base clusters around three strategic archetypes: heritage brands with dealer network density, vertically integrated manufacturers with captive component production, and premium-positioned specialists with proprietary software ecosystems. Competitive moves concentrate on portfolio diversification into computerized segments and geographic expansion through contract assembly partnerships in Southeast Asian manufacturing clusters.
Among Japanese industrial conglomerates, Brother Industries and JUKI Corporation exemplify scale-driven manufacturing archetypes with upstream control over critical components. Bernina International occupies the ultra-premium tier through Swiss-based positioning. These three anchors demonstrate how geographic origin and organizational structure shape competitive positioning without requiring identical strategic playbooks.
| Leading Market Players |
|---|
| Janome Sewing Machine |
| Husqvarna |
| SVP Worldwide |
| Elna |
| Toyota Industries |
| Brother Industries |
| Bernina International |
| Pfaff |
| JUKI Corporation |
| Others |
Value Network & Pricing Analysis
REACH substance restrictions on chromium and nickel alloys in metal components are forcing European-market suppliers to certify alternative materials or absorb expensive third-party testing, compressing margins on electronic and computerized units while elevating entry costs for new competitors. This regulatory-driven specification change concentrates pricing power among incumbents with established compliance infrastructure and captive testing capabilities.
Pricing Analysis
Short lead-time premiums for European-market electronic units compress as contract assembly in Vietnam and Indonesia scales, while spot inventory discounts widen for mechanical alternatives in price-sensitive developing channels. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-assembled computerized machines with proprietary software ecosystems from mid-tier Asian-manufactured electronic units and entry-level manual alternatives. Cost compression in the mechanical tier intensifies because unbranded Asian suppliers underprice electronic alternatives, though hobbyists monetizing craft output on resale platforms show lowest price sensitivity for feature-rich computerized specifications.
Supply Chain Analysis
Workforce availability constraints in Zhuhai and Shenzhen are elevating labor costs for captive motor manufacturing, while Vietnam and Indonesia offer expanding technical labor pools for Japanese and European brand contract assembly. Supply draws from precision-machined metal components, brushless DC motors, and touchscreen interface modules. Single-source vulnerability concentrates in Swiss-based final assembly for ultra-premium positioning and Chinese motor production for cost-competitive portfolios. Distribution runs through authorized dealer networks in North America and Western Europe, direct-to-maker channels for platform-native entrepreneurs, and traditional retail markups in Southeast Asian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over stitch-pattern software development and captive motor manufacturing determines margin capture against compliance-burdened competitors.
For Market Incumbents: Extend proprietary software ecosystem lock-in through cloud-downloadable design libraries that generate recurring revenue beyond hardware sales, while consolidating contract assembly partnerships in Indonesia to compress landed costs for mid-tier electronic machines. Social commerce distribution disruption threatens traditional dealer network value, making direct-to-maker channel investment the priority defensive lever. For New Entrants and Emerging Players: The gap between premium computerized specifications and economy mechanical units creates white space for electronic models with professional-grade output at accessible price points. Indonesia's underpenetrated middle-class households present the most penetrable geography as contract manufacturing familiarity builds local brand recognition. A social commerce-native go-to-market angle bypasses legacy dealer infrastructure while capturing platform-native craft entrepreneurs. For Investors and Strategic Acquirers: The window for entry favors vertically integrated manufacturers with captive component production and established regulatory compliance infrastructure across multiple jurisdictions. Long-term viability hinges on software-hardware convergence capabilities and Southeast Asian manufacturing scale. Watch for consolidation signals when REACH compliance costs force smaller European-market players to seek strategic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive production in Zhuhai insulates margin control from component cost volatility and compliance burdens. |
| Cloud-Connected Design Library Launch | Recurring software revenue models offset hardware margin compression from regulatory certification costs. |
| Contract Assembly Scale-Up in Indonesia | Localized production compresses landed costs and builds brand recognition in underpenetrated domestic markets. |
| Direct-to-Maker Distribution Channel | Bypassing traditional retail markups captures platform-native entrepreneurs reshaping purchase expectations. |
| Alternative Alloy Certification Investment | Proactive REACH compliance creates barrier-to-entry against competitors lacking testing infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with product development executives at sewing machine manufacturers, procurement leads at textile micro-enterprises, aftermarket service heads, and channel distribution managers. Secondary validation drew from ECHA REACH substance databases, EU F-Gas Regulation implementation reports, MIIT electromagnetic compatibility filings, and customs import records for household appliance categories. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to reconcile volume and value estimates.
Granularity-level modeling distinguished mechanical, electronic, computerized, and overlock product types; hobbyist, designer, tailor, and beginner end-user archetypes; portable, heavy-duty, multi-function, and beginner-friendly feature bundles; and brand positioning across heritage, vertically integrated, and premium-specialist archetypes. CAGRs were derived from segment-level growth trajectory analysis across the projection horizon. Forecast inputs incorporated social commerce monetization rates, contract assembly capacity expansion in Southeast Asian manufacturing clusters, and divergent efficiency mandate implementation timelines across Brussels, Washington, and Tokyo.
Inputs from regulatory filings and customs records were available through the study window; gaps in real-time social commerce transaction data and contract assembly utilization rates introduce uncertainty bands around hobbyist segment expansion assumptions. Forecasts reflect documented assumptions regarding compliance cost pass-through rates and platform-native entrepreneur adoption curves. Material deviation in REACH enforcement intensity, GB standards implementation timing, or social commerce platform algorithm changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Bathroom Products Market
Household Items
Bagless Vacuum Cleaner Market
Household Items
Smart Pool Skimmer Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Can Opener Market
Household Items
Heated Mattress Pads Market
Household Items
Steam Cleaners Market
Household Items
South Africa Cookware Market
Household Items
Facial Tissue Market
Household Items
Ironing Boards Market
Household Items
Mosquito Repellent Candles Market
Household Items
MENA POU Water Purifiers Market
Household Items
Deodorizer Bag Market
Household Items
Party Supplies Market
Household Items
US Digital Showers Market