
 Therapeutic Diet for Pet Market | 2026-2036
Therapeutic Diet for Pet Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Diet for Pet Market Insights
The gap between premium therapeutic formulations and commodity pet nutrition is realigning around clinical validation standards. Hill's Pet Nutrition leverages decades of veterinary research partnerships to sustain credibility with prescribing clinicians. Royal Canin dominates breed-specific and condition-specific portfolios that anchor its position in European and Asian veterinary channels. Purina Pet Nutrition competes through manufacturing scale and backward integration into ingredient sourcing that controls cost structures across price tiers.
Therapeutic diet for pets denotes clinically formulated nutrition engineered to manage, treat, or prevent specific disease states in companion animals, typically requiring veterinary authorization and manufactured under controlled conditions with precise macronutrient ratios, bioactive compounds, and restricted allergen profiles. These products serve the primary commercial purpose of extending pet healthspan while reducing long-term veterinary intervention costs for chronic conditions. Prescription diet and veterinary diet segments occupy the largest margin pools due to regulatory barriers and clinician gatekeeping, while functional food and supplemented food categories attract growing interest from pet owners seeking preventive health solutions outside formal disease diagnosis. Limited ingredient diet formats address the expanding allergy management application base where novel protein sources command sustained price premiums.
The FDA Center for Veterinary Medicine enforces stringent pre-market review for health claims that shapes product development timelines and elevates R&D thresholds for market entry. AAFCO nutrient profiles and state-level veterinary feed directives further constrain formulation flexibility while protecting therapeutic integrity claims. The EU's FEDIAF nutritional guidelines and national veterinary pharmaceutical regulators in Germany, France, and Italy impose parallel compliance burdens that favor established multinationals with dedicated regulatory affairs capacity. Stakeholders must monitor evolving televeterinary prescription channels and direct-to-consumer platform regulations that threaten to bypass traditional clinic-controlled distribution architectures.
Market Dynamics
Veterinary gatekeeping over prescription nutrition is tightening as telemedicine platforms erode clinic-controlled distribution, forcing manufacturers to rebuild compliance architectures around direct-to-consumer channels without sacrificing clinical credibility.
Growth Catalysts
- Aging companion animal demographics:Extended pet lifespans in the United States, Germany, and Japan expand the addressable population for chronic disease management diets requiring sustained veterinary oversight.
- FDA Center for Veterinary Medicine enforcement:Rigorous pre-market review of health claims elevates barriers that protect incumbent formulation expertise and justify premium positioning against commodity alternatives.
- Televeterinary platform expansion:Remote consultation services broaden geographic access to prescription authorization, unlocking rural and underserved markets previously constrained by clinic density.
Market Restraints
- Novel protein sourcing concentration:Insect and hydrolyzed protein supply chains cluster in specific European and Southeast Asian processing regions, exposing formulations to input volatility and trade disruption.
- AAFCO nutrient profile rigidity:Prescriptive macronutrient floors and ceilings constrain innovation in condition-specific formulations targeting emerging metabolic research.
- Human nutraceutical substitution:Pet owners increasingly repurpose human-grade supplements for companion animals, bypassing veterinary channels and eroding prescription diet adherence.
Strategic Opportunities
- Preventive functional food white space:Non-prescription segments targeting early-life microbiome establishment and cognitive aging capture pet owners seeking clinical-grade nutrition outside disease diagnosis.
- EU FEDIAF guideline harmonization:Converging nutritional standards across Germany, France, and Italy reduce multi-market registration burdens for formulations meeting elevated European baselines.
- Microbiome sequencing integration:Combining fecal analysis services with personalized diet recommendations creates stickier veterinary relationships and recurring revenue architectures.
Industry Challenges
- Veterinary nutritionist scarcity:Board-certified specialists capable of translating clinical research into commercial formulation protocols remain concentrated in academic and multinational R&D centers, constraining mid-tier manufacturer capability building.
- Legacy ERP integration with traceability mandates:Batch-level ingredient tracking requirements under FDA and FEDIAF frameworks force costly system overhauls for established producers with decades of accumulated technical debt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Diet for Pet Market |
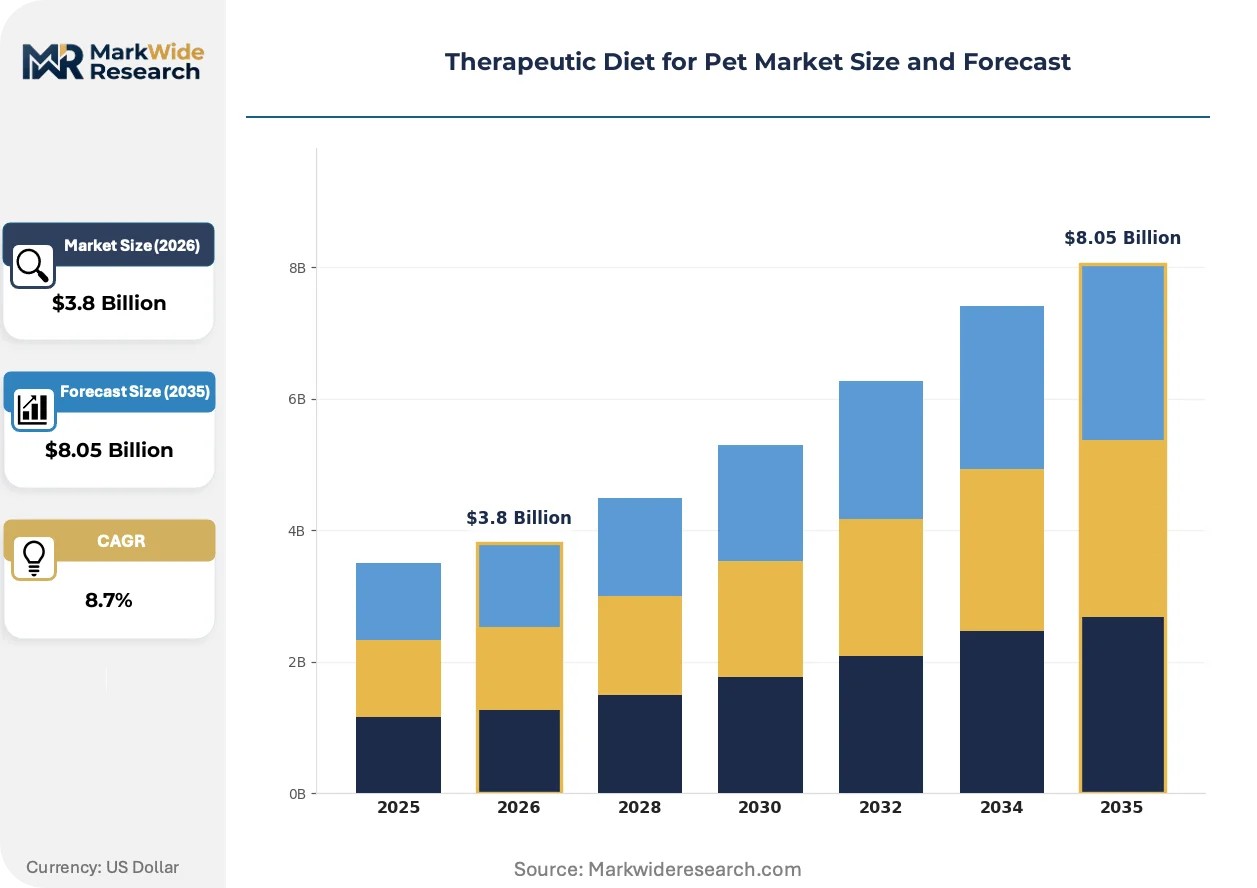
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Diet, Veterinary Diet, Functional Food, Supplemented Food, Limited Ingredient Diet Application: Weight Management, Renal Support, Digestive Health, Allergy Management, Diabetes Care End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Specialty Pet Stores Distribution Channel: Online Retailers, Veterinary Pharmacies, Pet Specialty Retailers, Direct Sales |
| Companies Covered | Purina PetCare, Hill's Pet Nutrition, Royal Canin, Blue Buffalo, Virbac, Farmina Pet Foods, Diamond Pet Foods, JustFoodForDogs, Wellness Pet Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Diet for Pet Market Trends and Innovations
Precision fermentation and cellular agriculture are rewriting protein economics for therapeutic formulations, while regulatory frameworks race to accommodate novel ingredient safety verification without choking innovation pipelines.
Precision fermentation of allergen-free proteins is electrifying the limited ingredient diet category. Veterinary dermatology practices in the United States and Germany are adopting these ingredients at accelerating rates for elimination diet protocols. This technology is compressing reliance on exotic animal protein sourcing that has historically constrained supply security and price stability.
The EU's FEDIAF nutritional guidelines are tightening disclosure requirements for bioactive compound sourcing and stability data. Manufacturers must now submit extended shelf-life verification for condition-specific formulations targeting renal and hepatic support. European veterinary channels are responding by consolidating supplier relationships toward partners with dedicated regulatory affairs infrastructure.
Subscription-based replenishment models are displacing episodic clinic purchasing for chronic condition diets. Digital pharmacy platforms and veterinary practice management software integrations are capturing recurring revenue streams previously fragmented across retail and prescription channels. This shift is most visible in United States metropolitan markets where pet owner convenience expectations have compressed traditional 30-day resupply cycles to automated 14-day intervals.
Therapeutic Diet for Pet Market Segmentation
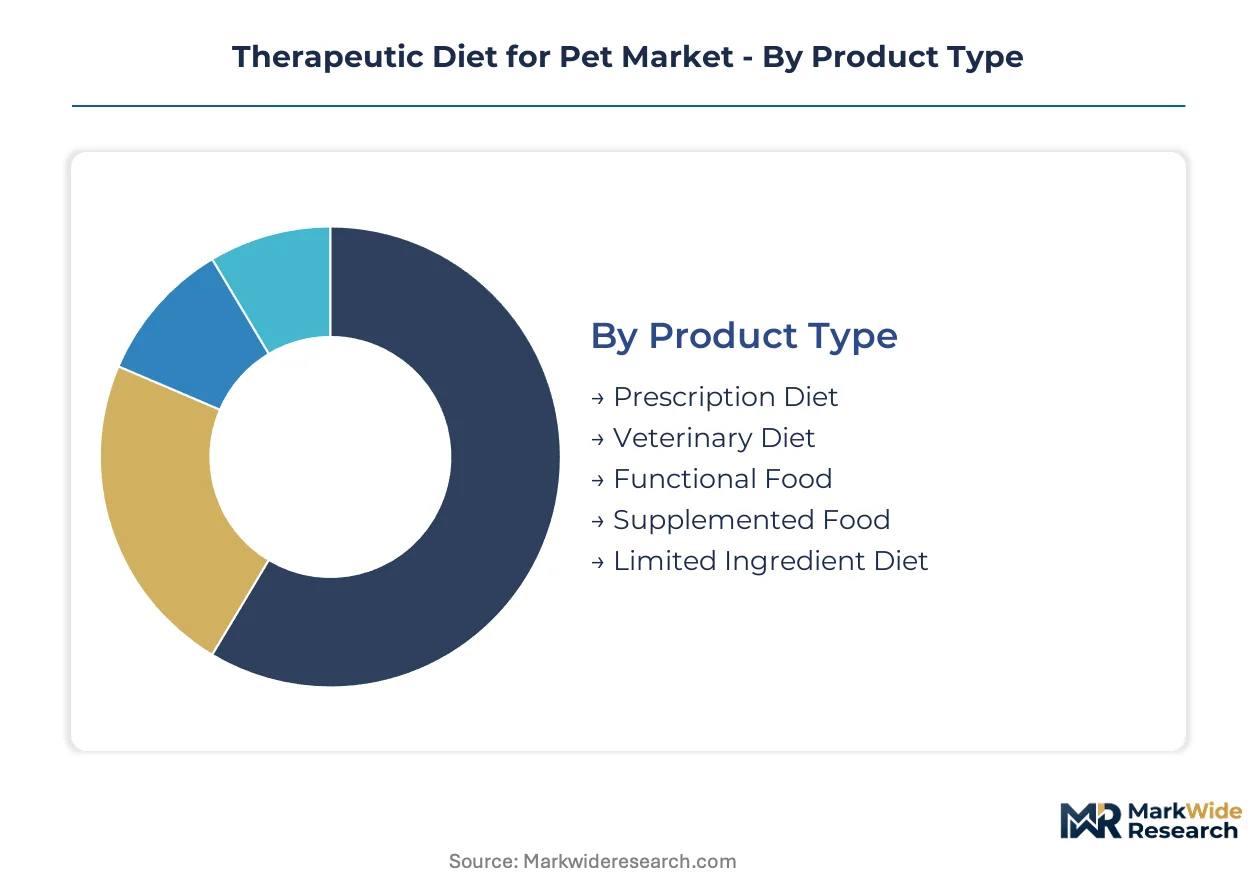
Therapeutic pet nutrition segments around clinical authorization intensity and disease specificity. Purchase decisions pivot on veterinary involvement level, chronic condition prevalence, and distribution channel accessibility.
Product Type:
Price tier and regulatory gatekeeping intensity shape manufacturer portfolio allocation and margin capture across formulation categories.
- Prescription Diet:Clinically validated formulations requiring veterinary authorization with precise macronutrient ratios for disease management. Demand concentrates in United States metropolitan veterinary practices where FDA Center for Veterinary Medicine enforcement elevates compliance costs but protects premium positioning against commodity alternatives.
- Veterinary Diet:Condition-specific nutrition manufactured under controlled conditions with bioactive compound standardization. Germany and Japan sustain category expansion through aging pet populations and high clinical channel density that reinforces veterinarian recommendation authority.
- Functional Food:Preventive nutrition targeting microbiome establishment and cognitive aging outside formal diagnosis.
- Supplemented Food:Commodity base enhanced with targeted additives for wellness-oriented pet owners.
- Limited Ingredient Diet:Novel protein formulations for elimination protocols and allergen restriction.
Volume sits with Prescription Diet; growth tilts toward Functional Food.
Application:
Disease state prevalence and treatment protocol duration determine formulation development priorities and recurring revenue potential.
- Weight Management:Calorie-controlled formulations with satiety-enhancing fiber profiles addressing obesity-related metabolic syndrome. United States veterinary clinics drive substantial volume as pet owner awareness of diabetes prevention elevates long-term adherence to portion-controlled feeding regimens.
- Renal Support:Restricted phosphorus and enhanced omega-3 formulations for chronic kidney disease progression delay. Japan's geriatric companion animal population sustains category leadership with nephrology-specialized veterinary practices prescribing extended-duration protocols.
- Digestive Health:Hydrolyzed protein and prebiotic-enhanced diets for gastrointestinal sensitivity management.
- Allergy Management:Novel protein and limited antigen formulations for atopic dermatitis and food hypersensitivity.
- Diabetes Care:Low glycemic index formulations with complex carbohydrate profiles for glucose regulation.
Volume concentrates in Weight Management; Allergy Management climbs the fastest on precision fermentation protein adoption.
End User:
Channel control and recommendation authority determine pricing power and customer acquisition economics across the value chain.
- Veterinary Clinics:Primary prescription authorization points with direct patient relationship continuity.
- Animal Hospitals:Emergency and specialty referral centers for acute condition diagnosis and diet initiation.
- Pet Owners:Final decision-makers influenced by convenience expectations and digital information access.
- Specialty Pet Stores:Curated non-prescription therapeutic alternatives with trained staff consultation.
Revenue concentrates with Veterinary Clinics; volume expansion tilts toward Pet Owners via televeterinary platform integration.
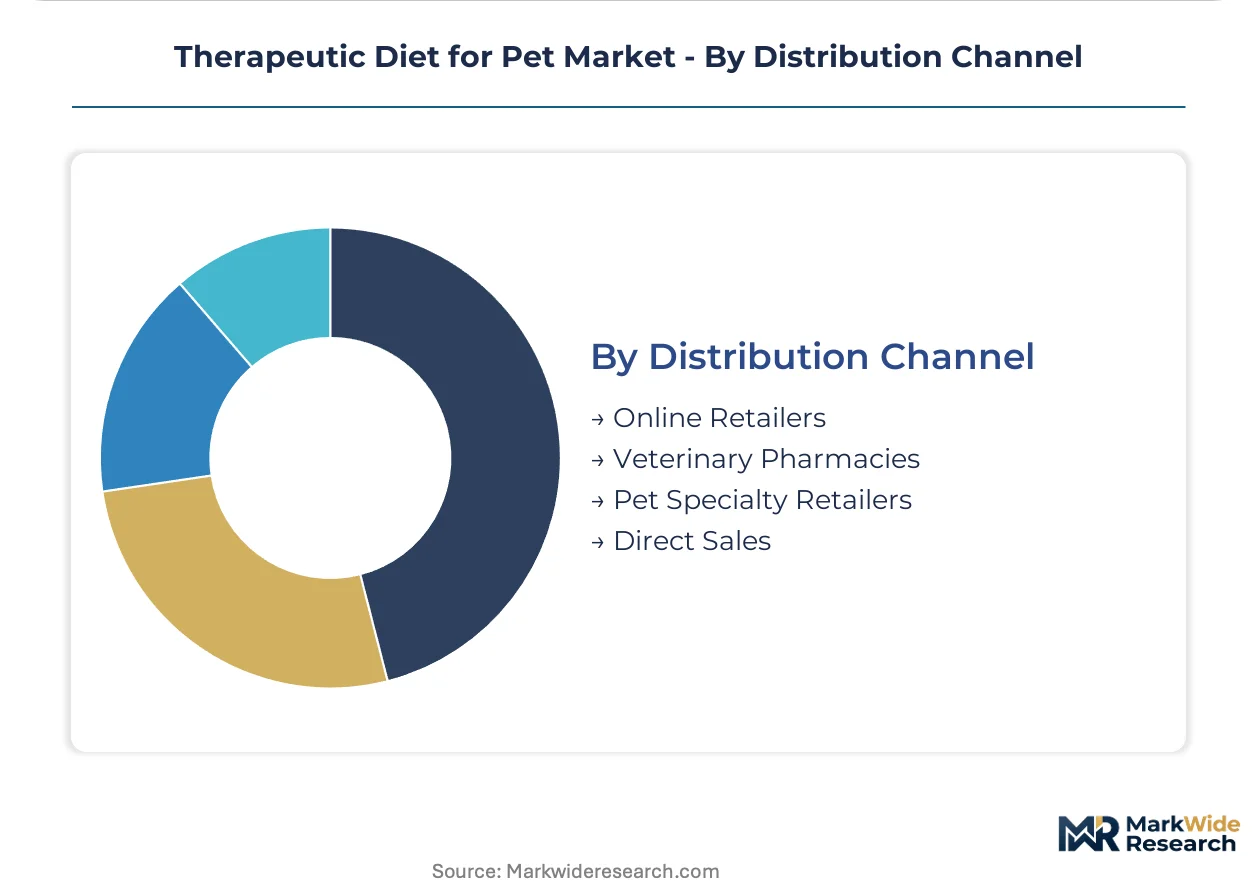
Distribution Channel:
Supply chain configuration and regulatory compliance architecture shape channel economics and geographic reach.
- Online Retailers:Subscription-based replenishment platforms capturing recurring revenue through automated resupply cycles. United States metropolitan markets compress traditional 30-day cycles to 14-day intervals as pet owner convenience expectations reshape purchasing patterns.
- Veterinary Pharmacies:Clinic-integrated dispensing with prescription verification and patient record linkage. Germany's national veterinary pharmaceutical regulators enforce traceability mandates that favor established distributors with dedicated compliance infrastructure.
- Pet Specialty Retailers:Physical consultation points for non-prescription functional and supplemented food categories.
- Direct Sales:Manufacturer-controlled relationships bypassing intermediaries for institutional and high-volume accounts.
Transaction volume sits with Veterinary Pharmacies; channel expansion gains share fastest through Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kansas City metropolitan corridor anchors North American therapeutic pet nutrition manufacturing, hosting formulation R&D centers and veterinary distribution hubs that supply clinic networks across the Midwest and beyond.
United States
Aging companion animal populations in Florida and Arizona expand demand for renal support and weight management diets. The FDA Center for Veterinary Medicine enforces pre-market health claim verification that elevates compliance costs for new entrants. Greater Boston's veterinary teaching hospitals pioneer microbiome-guided personalized nutrition protocols.
Germany
Geriatric pet demographics in Bavaria and North Rhine-Westphalia sustain prescription diet volumes through specialized veterinary practices. The country's national veterinary pharmaceutical regulator enforces batch-level traceability mandates under EU FEDIAF guidelines. Munich's veterinary nutrition research cluster attracts formulation partnerships from multinational manufacturers.
Japan
Extended feline lifespans in Tokyo and Osaka metropolitan areas drive chronic kidney disease diet adherence. METI guidelines on functional food labeling shape preventive nutrition product development. The Kansai region's pet food manufacturing belt concentrates hydrolyzed protein processing capacity for allergy management formulations.
United Kingdom
London's high-density veterinary clinic networks sustain premium prescription diet dispensing volumes. The Veterinary Medicines Directorate enforces parallel import restrictions that protect authorized distribution channels. The Southeast England corridor hosts European regulatory affairs headquarters for several multinational pet nutrition firms.
France
Parisian veterinary dermatology practices accelerate adoption of precision fermentation proteins for elimination diets. ANSM oversight of veterinary health products converges with EU FEDIAF nutritional disclosure requirements. The Lyon-Grenoble corridor clusters novel ingredient safety testing laboratories serving European formulation developers.
Therapeutic Diet for Pet Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the therapeutic pet nutrition landscape. The market structure consolidates around three multinational conglomerates with captive veterinary research networks, while mid-tier specialists occupy condition-specific niches. Strategic archetypes include clinic-integrated prescription formulators, novel protein technology licensors, and direct-to-consumer preventive nutrition platforms. Competitive intensity manifests through veterinary practice management software integrations and subscription-based replenishment model proliferation.
Within the clinic-integrated prescription tier, Hill's Pet Nutrition, Royal Canin, and Purina PetCare exemplify scale-driven archetypes with decades of veterinary research partnerships. Hill's represents the academic collaboration model with teaching hospital affiliations. Royal Canin occupies a position emphasizing breed-specific and condition-specific portfolio depth. Purina anchors the manufacturing efficiency vector through backward integration into ingredient sourcing and continental production scale.
| Leading Market Players |
|---|
| Purina PetCare |
| Hill's Pet Nutrition |
| Royal Canin |
| Blue Buffalo |
| Virbac |
| Farmina Pet Foods |
| Diamond Pet Foods |
| JustFoodForDogs |
| Wellness Pet Company |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation of allergen-free proteins is compressing cost structures for novel protein sourcing while simultaneously concentrating processing capacity in the Kansai region of Japan and select European biotechnology clusters. This technological transition elevates formulation economics for limited ingredient diets but creates dependency on specialized fermentation infrastructure that few manufacturers control directly.
Pricing Analysis
Clinical outcome anchoring ties prescription diet pricing to measurable disease progression delay and reduced veterinary intervention frequency. Three-tier pricing structure across premium, standard, and economy levels stratifies by veterinary authorization intensity and bioactive compound standardization. Pricing pressure stems from human nutraceutical substitution as pet owners repurpose unregulated supplements. Price-sensitive buyers concentrate in the supplemented food category, while prescription diet purchasers exhibit low elasticity due to clinician recommendation authority and pet health urgency.
Supply Chain Analysis
Dual-sourcing requirements for novel proteins mandate qualification of both precision fermentation suppliers and traditional hydrolyzed protein processors to mitigate single-source vulnerability. Supply concentrates in Japan for hydrolyzed protein processing, Germany for regulatory-compliant manufacturing, and the United States for veterinary distribution infrastructure. Raw material dependencies include insect protein meal, cellular agriculture-derived proteins, and pharmaceutical-grade omega-3 fatty acids. Tariff exposure on novel protein imports from Southeast Asian processing regions threatens margin stability. Distribution runs through veterinary pharmacy integrations and subscription-based online platforms with automated replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
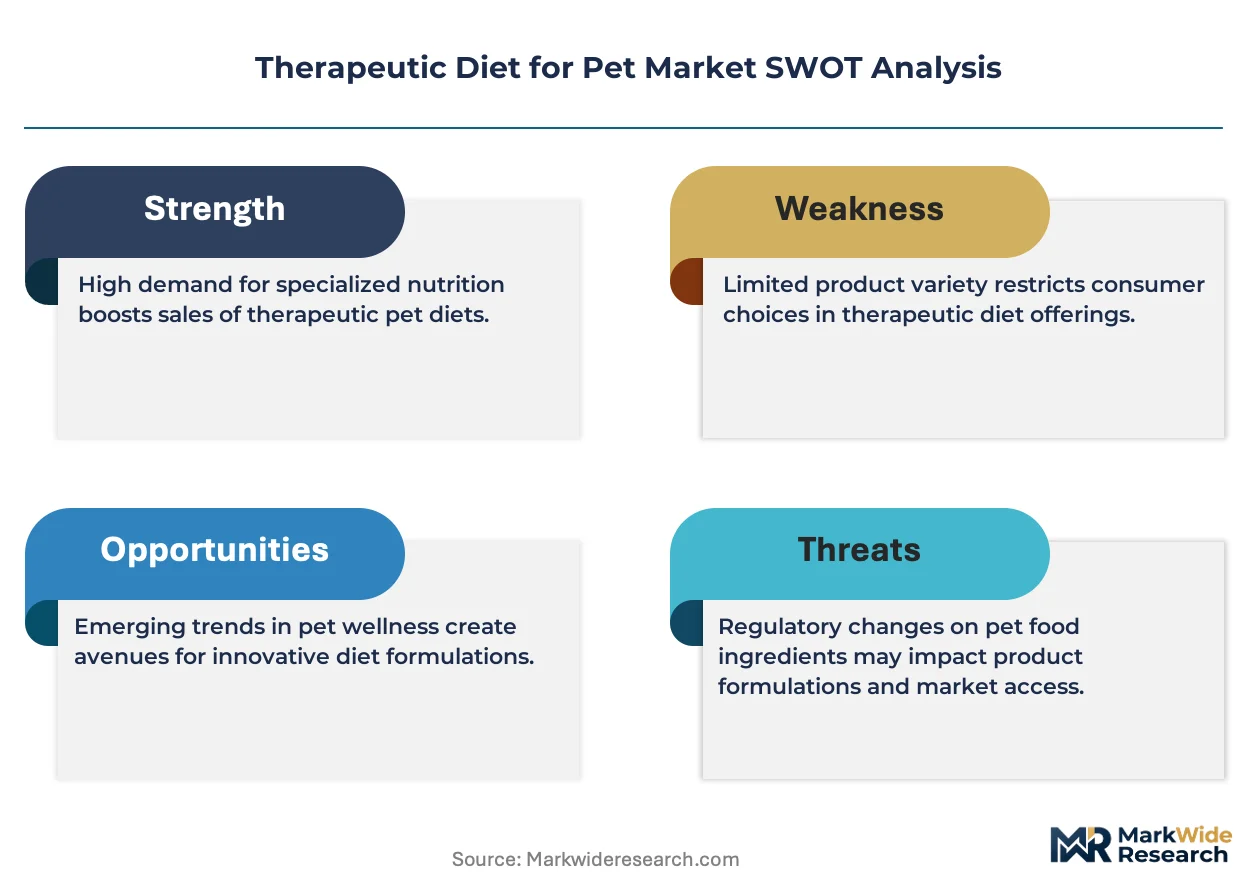
This market represents a consolidation play as FDA Center for Veterinary Medicine pre-market review costs and FEDIAF traceability mandates force sub-scale formulators toward exit or acquisition.
For Market Incumbents: Cement clinic-controlled distribution architectures against televeterinary platform erosion by integrating practice management software with automated replenishment systems. Deepen backward integration into precision fermentation capacity to secure novel protein supply against single-source concentration in Japanese processing clusters. Prioritize regulatory affairs infrastructure investment to sustain premium positioning as EU disclosure requirements tighten.
For New Entrants and Emerging Players: Enter via preventive functional food white space targeting microbiome establishment and cognitive aging outside formal disease diagnosis. Target underserved rural markets in the United States where televeterinary platforms now enable prescription authorization without legacy clinic density. Pursue direct-to-consumer subscription models with veterinary teleconsultation bundling to bypass incumbent channel control.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational conglomerates seeking condition-specific portfolio depth and captive veterinary research networks. Long-term viability favors targets with board-certified veterinary nutritionist teams and established regulatory affairs capacity across FDA and FEDIAF jurisdictions. Watch precision fermentation protein cost curves as the inflection signal for novel ingredient economics tipping toward mainstream adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Practice Management Software Integration | Captures recurring revenue through embedded prescription authorization and automated replenishment workflows. |
| Precision Fermentation Capacity Buildout | Reduces dependency on exotic animal protein sourcing exposed to trade disruption and input volatility. |
| Microbiome Sequencing Service Launch | Creates stickier veterinary relationships through personalized diet recommendations tied to fecal analysis. |
| Regulatory Affairs Infrastructure Expansion | Accelerates FDA Center for Veterinary Medicine pre-market review timelines for condition-specific formulations. |
| Televeterinary Platform Partnership | Unlocks rural and underserved markets previously constrained by physical clinic density limitations. |
Research Methodology
Document review covered FDA Center for Veterinary Medicine filings, EU FEDIAF nutritional guideline submissions, and veterinary pharmaceutical regulator records from Germany, France, and Japan, complemented by interviews with veterinary nutritionists, regulatory affairs directors at multinational pet nutrition firms, clinic practice managers, and specialty pet retail buyers. Secondary validation drew from AAFCO nutrient profile databases, customs trade data on novel protein imports, and veterinary practice management software adoption statistics. Bottom-up segmentation modeling triangulated against top-down market sizing from prescribing clinician density and pet population demographics.
Output metrics across the projection horizon reflect modeled interactions between aging companion animal prevalence, televeterinary platform penetration rates, and precision fermentation protein cost trajectories. Segmentation dimensions included product authorization intensity, disease state specificity, distribution channel configuration, and regional regulatory cluster alignment. CAGRs were derived from trend extrapolation of veterinary prescription volumes and pet owner willingness-to-pay for clinical-grade nutrition. Industry-specific inputs incorporated renal support diet adherence rates in Japan's geriatric feline population and weight management protocol duration in United States metropolitan veterinary practices.
Revisions become necessary when televeterinary prescription regulations materially restrict direct-to-consumer channel expansion, precision fermentation protein yields fail to achieve projected cost thresholds, or human nutraceutical substitution accelerates beyond modeled erosion rates. Deviation in FDA enforcement intensity for health claim verification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Automatic Dog Feeder Market
Pet Care Products
Dog Pad Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
South America Dog Food Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
China Cat Litter Market
Pet Care Products
US Pet Food Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
Cat Condos and Indoor Houses Market
Pet Care Products
Japan Organic and Natural Pet Food Market