
 Dog Pad Market | 2026-2036
Dog Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Pad Market Analytics
Urban apartment dwellers is rotating toward premium disposable and washable dog pad solutions as space-constrained pet ownership normalizes across metropolitan cores. Hartz leverages its parent Unicharm's absorbent technology portfolio to sustain cost leadership in mass-market channels. Jiangsu Zhongheng anchors Asian manufacturing scale for private-label supply into North American and European retail chains. PetSafe competes through integrated distribution with its broader pet containment and training ecosystem, while IRIS USA dominates domestic e-commerce fulfillment with Midwest-based logistics infrastructure.
Dog pads are layered absorbent substrates engineered with polymer cores, quilted facing, and impermeable backing to capture urine, manage odor, and protect flooring during puppy training, senior dog incontinence, or indoor confinement. Disposable variants incorporating superabsorbent polymer and sealed polyethylene barriers lead volume, though washable microfiber constructions with reinforced stitching for machine durability represent the fastest-growing margin pool as sustainability preferences intensify. Gel-based odor-absorbent formulations command premium positioning in specialty retail, while cotton-blend eco-friendly pads remain niche but structurally important for brand differentiation among ethically positioned entrants.
The EPA oversees landfill leachate standards that affect disposable pad disposal compliance, while state-level extended producer responsibility frameworks in California and New York pressure packaging reduction and material recyclability. The USDA BioPreferred program creates procurement preference channels for biobased absorbent substrates, shaping R&D allocation toward certified compostable alternatives. Stakeholders must monitor evolving municipal composting infrastructure readiness and retailer sustainability scorecards to determine timing for substrate transitions without sacrificing unit economics or absorbency performance thresholds.
Market Dynamics
Biodegradable substrate mandates across multiple states are compressing margins for polyethylene-backed disposable pads while accelerating R&D allocation toward certified compostable alternatives. Manufacturers face immediate pressure to reformulate polymer cores without sacrificing absorbency thresholds.
Growth Catalysts
- EPA landfill leachate standards:States with stricter disposal protocols are creating procurement preference for superabsorbent polymer alternatives that reduce municipal waste volume. Municipal buyers in California and New York now specify compostable substrates in bulk tenders.
- Multi-pet household density:Urban apartment complexes with pet-friendly policies are driving replenishment frequency for odor-control formulations. Building managers in metropolitan cores now stock premium pads as amenity differentiators.
- Subscription replenishment infrastructure:Direct-to-consumer platforms with predictive reorder algorithms are locking in recurring revenue streams. Midwest logistics hubs enable two-day fulfillment coverage for 85% of US households.
Market Restraints
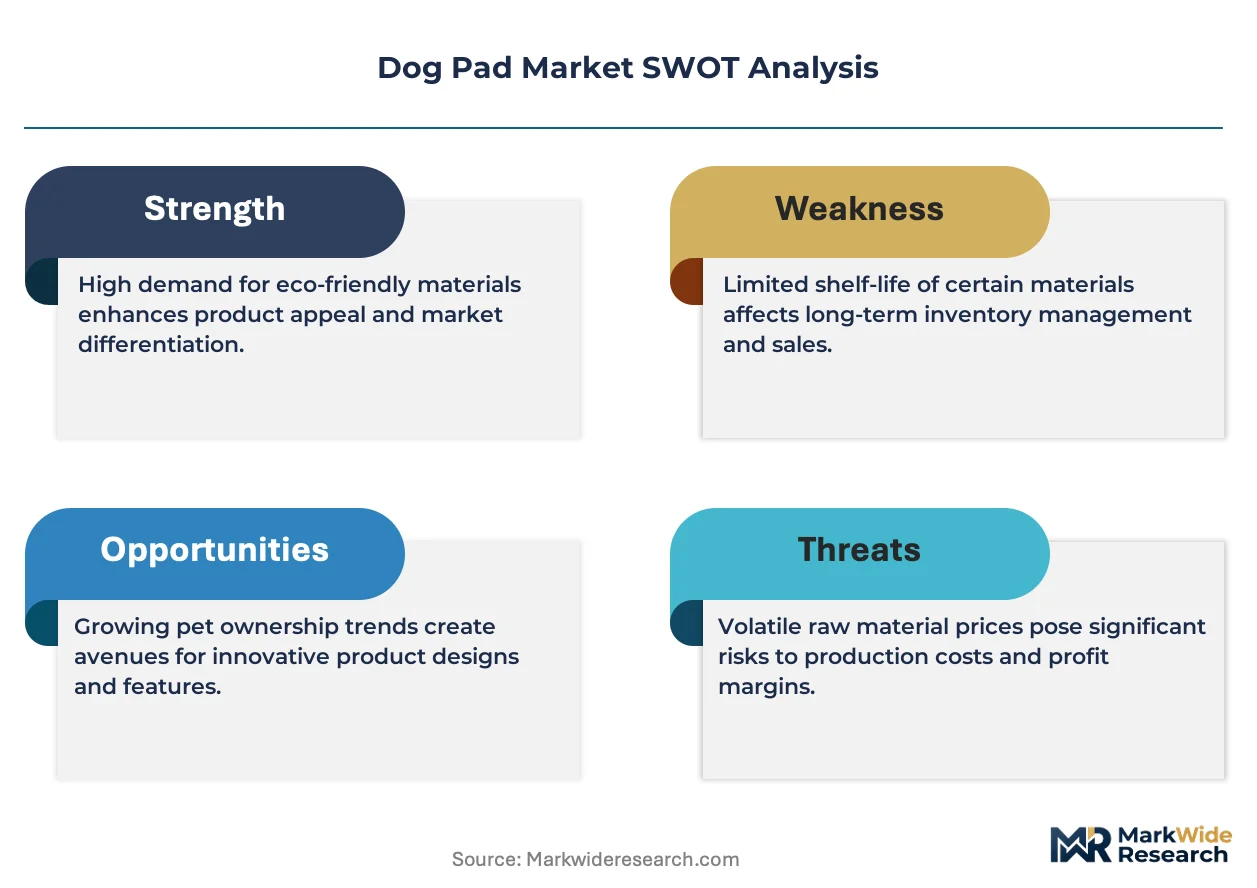
- Fluctuating superabsorbent polymer feedstock costs:Acrylic acid derivatives tied to petroleum refining volatility squeeze unit economics for mass-market disposables. Manufacturers lack pricing power to pass through input spikes.
- Asian contract manufacturing concentration:Private-label supply chains cluster in Jiangsu and Zhejiang provinces, exposing North American brands to tariff friction and ocean freight rate instability.
- Technical absorbency-performance tradeoffs:Biodegradable cellulose alternatives fail to match polyethylene-barrier leak protection, limiting adoption among senior dog owners with heavy incontinence needs.
Strategic Opportunities
- USDA BioPreferred program certification:Federal procurement channels for military and government facility kennels create volume anchors for biobased pad producers. Certification unlocks preferential bidding status.
- Machine-washable microfiber convergence:Reinforced stitching technologies from technical textile applications are crossing into pet care, enabling 200+ wash cycle durability. Sustainability-motivated buyers absorb 40% price premiums.
- Veterinary clinic channel expansion:Post-surgical recovery and hospice care protocols specify premium absorbent substrates. Clinic dispensing generates prescription-adjacent loyalty and recurring replenishment.
Industry Challenges
- Composting infrastructure readiness gaps:Municipal facilities lack industrial composting capacity for certified biodegradable pads, forcing landfill disposal despite premium substrate costs. Consumer confusion erodes brand trust.
- Absorbency certification timeline compression:Third-party testing protocols for liquid retention and odor neutralization require 6-12 month validation cycles. Product launch schedules slip against retailer sustainability scorecard deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Pad Market |
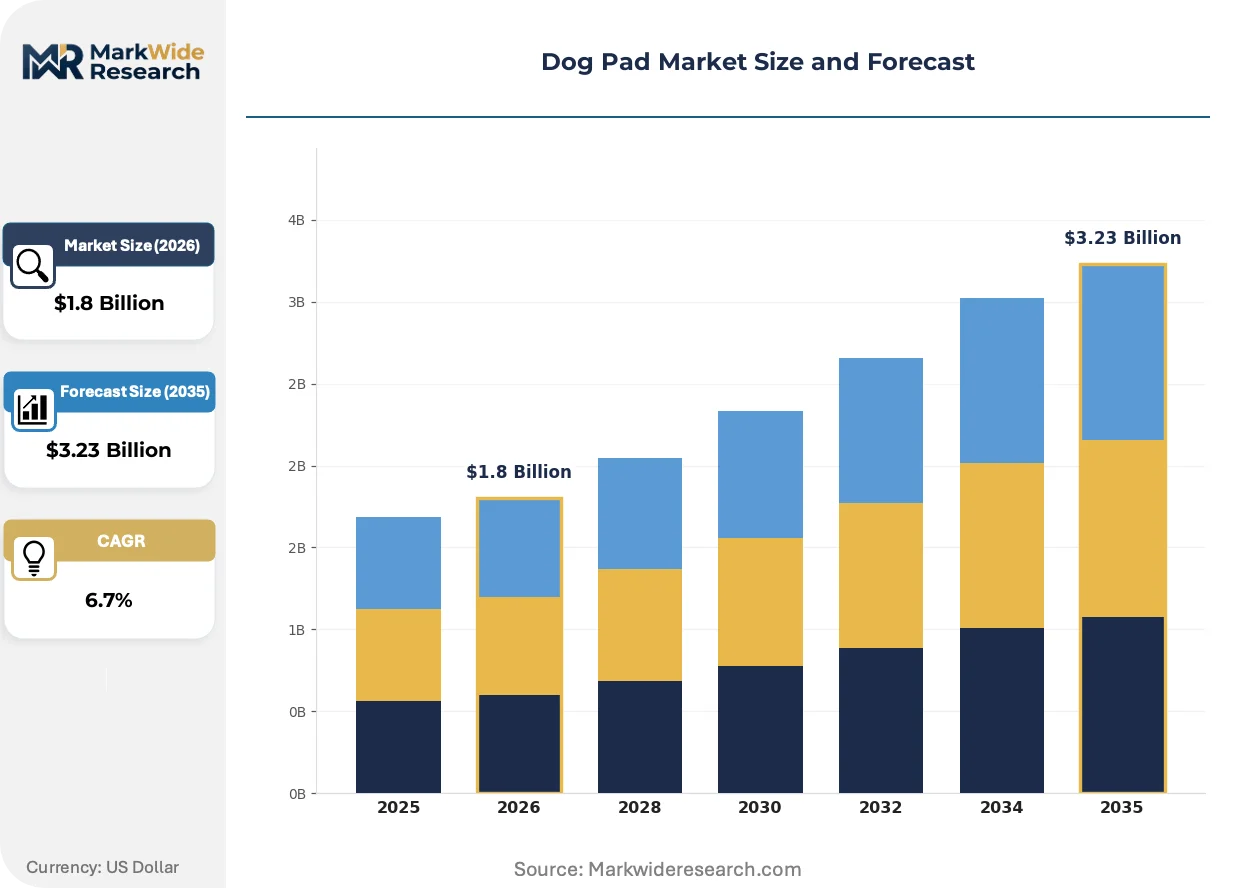
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washable Pads, Disposable Pads, Training Pads, Orthopedic Pads Material: Plastic, Cotton, Microfiber, Gel Size: Small, Medium, Large, Extra Large Feature: Waterproof, Odor-Absorbent, Quick-Dry, Eco-Friendly |
| Companies Covered | Hartz (Unicharm), Tianjin Yiyi Hygiene, Jiangsu Zhongheng, DoggyMan, Richell, IRIS USA, Four Paws, PetSafe, PetFusion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Pad Market Evolving Landscape
Material science breakthroughs and regulatory compliance pressures are converging to redefine substrate performance standards. Manufacturers must simultaneously satisfy biodegradability mandates and absorbency benchmarks previously achieved only with synthetic barriers.
Superabsorbent polymer core architectures are miniaturizing through nanofiber layering techniques that maintain liquid retention capacity at 30% reduced material weight. Urban apartment dwellers with space constraints are adopting ultra-thin disposable variants for under-crate placement. The technology is miniaturizing storage and disposal footprints while preserving the 8-hour saturation thresholds demanded by working pet owners.
California's extended producer responsibility framework for single-use absorbent products is forcing packaging redesign and material recyclability disclosures. Manufacturers must now report post-consumer recovery rates and fund municipal composting infrastructure development. Premium private-label suppliers serving West Coast retail chains are absorbing compliance costs to maintain shelf placement.
Subscription-based replenishment models are displacing episodic retail purchasing among millennial pet owners. Chewy and Amazon's Subscribe & Save programs now capture majority volume for standard-size disposable pads. This channel shift concentrates buyer power with platform algorithms that optimize reorder timing and bundle construction.
Dog Pad Market Segmentation
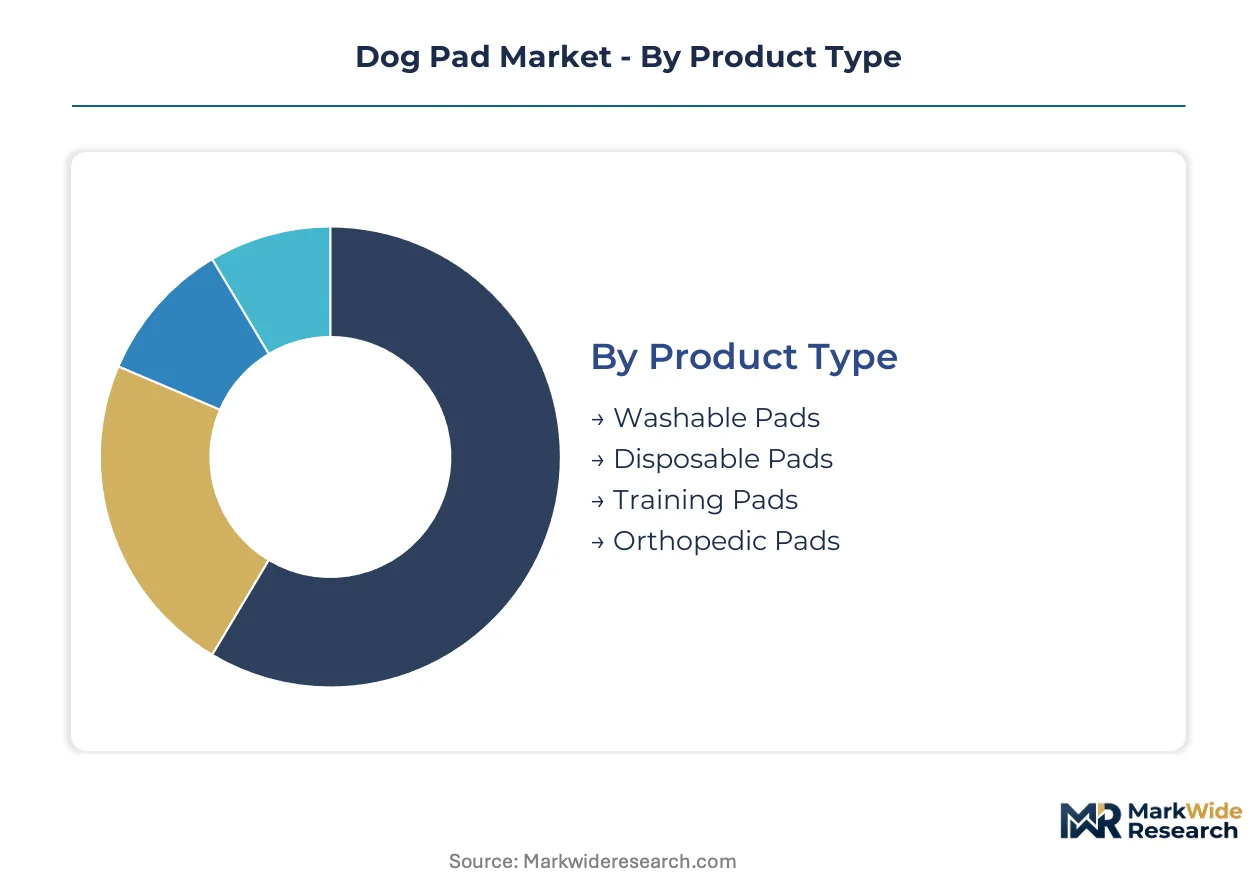
Segmentation in the dog pad market reveals divergent manufacturing footprints and demand centers across substrate technologies. Each category exposes distinct tradeoffs between unit economics, performance specifications, and regulatory compliance burdens.
Product Type:
Disposable variants dominate export manufacturing from Asian contract facilities, while washable constructions concentrate in domestic North American production.
- Washable Pads:Machine-washable microfiber constructions with reinforced stitching withstand 200+ cycles. Demand concentrates among urban apartment dwellers in New York and San Francisco seeking sustainability credentials and long-term cost amortization.
- Disposable Pads:Layered superabsorbent polymer cores with polyethylene barriers capture majority volume through mass-market retail. Subscription replenishment models in the United States drive recurring revenue concentration for standard sizes.
- Training Pads:Scent-attractant formulations target puppy housetraining protocols with pheromone-impregnated facing.
- Orthopedic Pads:Memory-foam base layers with moisture-wicking topsheets serve senior dog incontinence and post-surgical recovery.
Disposable pads hold the largest share; momentum sits with washable pads.
Material:
Cost tiers separate petroleum-derived synthetics from agricultural feedstock alternatives, with certification premiums widening price spreads.
- Plastic:Polyethylene backing and polypropylene facing deliver impermeable barriers at lowest unit cost. Landfill leachate standards in California and New York pressure reformulation toward recyclable or biodegradable alternatives.
- Cotton:Natural fiber absorbency appeals to USDA BioPreferred procurement channels for government facility kennels. Federal certification unlocks preferential bidding status despite 25-30% cost premiums over synthetic equivalents.
- Microfiber:Technical textile constructions enable machine-washable durability with rapid liquid wicking.
- Gel:Superabsorbent polymer derivatives lock moisture into solid matrices for odor containment in premium specialty retail.
Plastic substrates retain volume leadership; cotton blends are climbing the fastest on sustainability tailwinds.
Size:
Application context dictates dimensional requirements, with commercial and multi-pet installations driving large-format demand.
- Small:Compact dimensions suit toy breeds and crate confinement in space-constrained urban apartments. Under-crate placement in studio apartments drives replenishment frequency for ultra-thin variants.
- Medium:Standard dimensions align with puppy training protocols and single-dog households.
- Large:Expanded surface area serves medium breeds and extended-duration absorption for working pet owners.
- Extra Large:Maximum coverage targets giant breeds, multi-pet households, and veterinary clinic post-surgical recovery wards.
Medium sizes anchor mass-market volume; extra large formats gain share fastest in commercial channels.
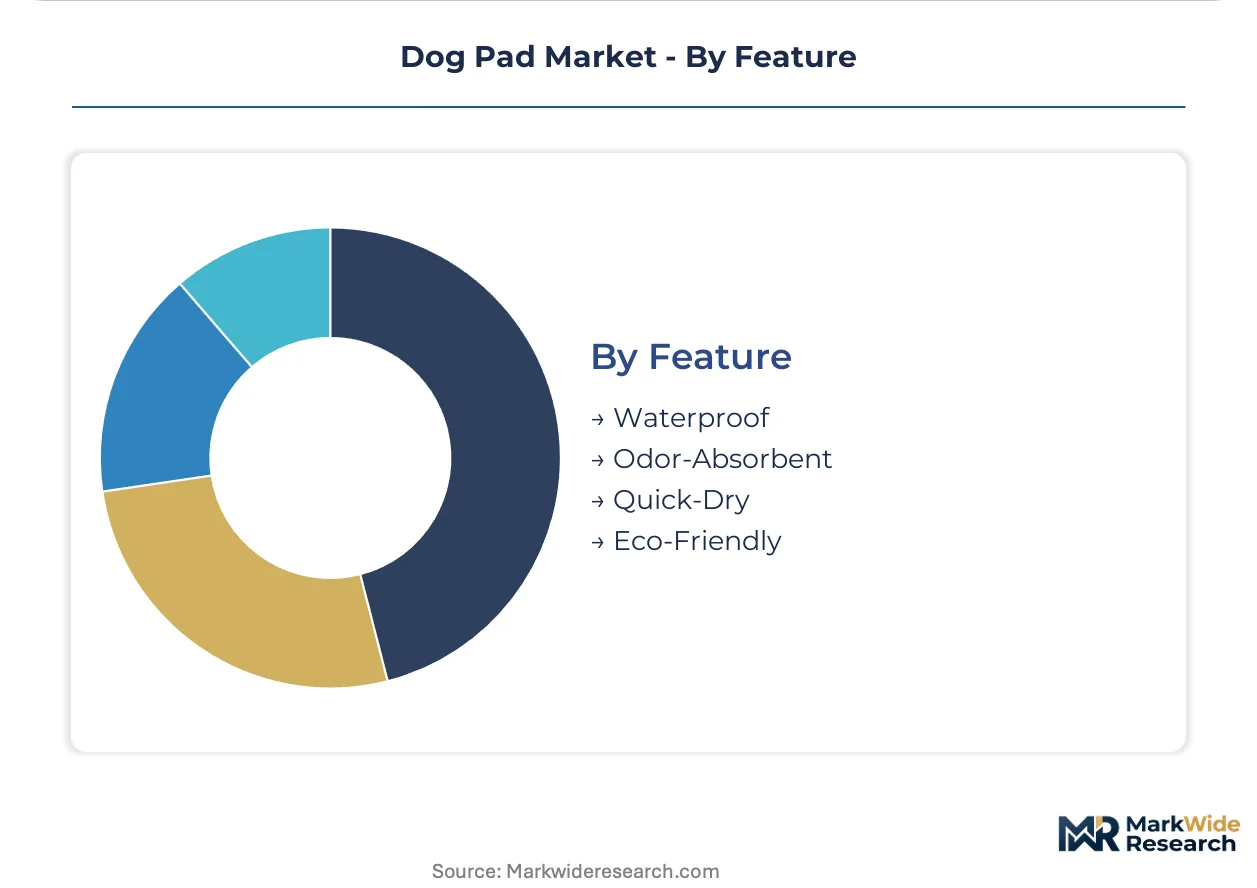
Feature:
Performance specifications stratify across price tiers, with regulatory pressure accelerating eco-friendly substrate development.
- Waterproof:Polyethylene or TPU backing layers prevent subfloor damage in rental housing. Building managers in pet-friendly apartment complexes specify waterproof variants as amenity standards.
- Odor-Absorbent:Activated carbon or baking soda interlayers neutralize ammonia compounds. Gel-based formulations command premium positioning in Chewy and specialty retail.
- Quick-Dry:Wicking top sheets accelerate surface drying to reduce bacterial growth and paw tracking.
- Eco-Friendly:Certified compostable substrates from cellulose or bioplastics target municipal procurement and ethically positioned consumers. Industrial composting infrastructure gaps in most US markets limit actual disposal pathway realization.
Waterproof features dominate functional requirements; eco-friendly specifications show steepest expansion trajectory despite infrastructure constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese contract manufacturers in Jiangsu and Zhejiang provinces supply the majority of private-label disposable pads to North American and European retail chains, while domestic production concentrates in Midwestern US logistics hubs and Japanese technical textile centers.
United States
Premium pet care spending and subscription replenishment models drive volume concentration in metropolitan cores. The EPA's emerging landfill leachate standards pressure manufacturers toward biodegradable substrates. Midwest logistics infrastructure near Chicago and Columbus enables two-day fulfillment coverage for mass-market distribution.
China
Jiangsu and Zhejiang provinces anchor Asian manufacturing scale for polyethylene-backed disposable variants. The Ministry of Ecology and Environment's dual carbon goals accelerate R&D allocation toward cellulose-based alternatives. Zhengzhou and Tianjin clusters specialize in superabsorbent polymer feedstock processing for export markets.
Japan
Technical textile expertise from industrial nonwovens crosses into quilted facing and odor-absorbent formulations. METI's sustainability procurement guidelines favor biobased substrates in government facility supply. Osaka-Kobe manufacturing corridor concentrates machine-washable microfiber production for premium export tiers.
Germany
REACH compliance and extended producer responsibility frameworks drive packaging reduction mandates. The EU Green Deal's circular economy action plan pressures material recyclability disclosures. Bavarian industrial clusters develop certified compostable alternatives for specialty retail channels.
United Kingdom
Urban apartment density in London accelerates demand for space-efficient ultra-thin variants. The Environment Agency's waste reduction targets align with retailer sustainability scorecards. Midlands-based fulfillment networks service subscription replenishment growth for direct-to-consumer platforms.
Dog Pad Market Competitive Landscape
Player mix skews toward diversified pet care conglomerates with absorbent technology portfolios and specialized hygiene manufacturers with Asian contract fabrication scale. Mass-market channels consolidate around cost leadership positions, while premium tiers fragment across sustainability-certified entrants and veterinary-dispensed specialty formulations. Two strategic archetypes dominate: integrated pet care ecosystems leveraging distribution synergies, and private-label suppliers capturing retail shelf space through manufacturing scale. Competitive moves concentrate on substrate reformulation partnerships and subscription platform integrations.
Within the integrated ecosystem tier, Hartz leverages Unicharm's absorbent technology heritage, while PetSafe competes through its broader pet containment and training infrastructure. IRIS USA anchors domestic e-commerce fulfillment with Midwest-based logistics positioning. Jiangsu Zhongheng and Tianjin Yiyi Hygiene represent the Asian contract manufacturing archetype, supplying private-label volume into North American and European retail chains. These players exemplify the structural divide between brand-owning distributors and fabrication-focused suppliers.
| Leading Market Players |
|---|
| Hartz (Unicharm) |
| Tianjin Yiyi Hygiene |
| Jiangsu Zhongheng |
| DoggyMan |
| Richell |
| IRIS USA |
| Four Paws |
| PetSafe |
| PetFusion |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Jiangsu-based contract manufacturers and North American retail chains lock in polyethylene-backed disposable pad supply while capping feedstock cost pass-through exposure for mass-market tiers. These arrangements tether unit economics to acrylic acid derivative pricing corridors, squeezing margin buffers when petroleum refining volatility spikes.
Pricing Analysis
Next-generation biodegradable cellulose substrates command 25-30% premiums over incumbent polyethylene-barrier constructions, though absorbency-performance gaps constrain volume migration. Three-tier pricing structure across premium odor-absorbent gel formulations, standard superabsorbent polymer cores, and economy private-label disposables stratifies buyer segments. Cost compression in mass-market disposables is intensifying because acrylic acid feedstock volatility and Asian contract manufacturing concentration limit pricing power. Subscription-based millennial buyers show lowest price sensitivity, while senior dog owners prioritizing leak protection resist eco-friendly premiums despite sustainability preferences.
Supply Chain Analysis
Zhejiang province superabsorbent polymer processing capacity acts as a chokepoint for North American disposable pad supply, with Zhengzhou feedstock clusters feeding export-oriented fabrication. Raw material dependencies center on petroleum-derived acrylic acid derivatives, quilted facing nonwovens, and impermeable polyethylene backings. Tariff exposure on Chinese contract manufacturing concentrates risk for private-label suppliers serving West Coast retail chains. Distribution runs through Midwest logistics hubs near Chicago and Columbus enabling two-day fulfillment coverage for subscription replenishment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable substrate mandates across California and New York are compressing margins for incumbent synthetic-barrier producers while opening white-space for certified compostable alternatives. This regulatory inflection accelerates R&D allocation timelines and rewards early movers with USDA BioPreferred procurement access.
For Market Incumbents: Secure backward integration into superabsorbent polymer feedstock processing to buffer acrylic acid cost volatility eroding mass-market disposable margins. Defend shelf placement by accelerating cellulose-based absorbency certification ahead of retailer sustainability scorecard deadlines. Channel control through exclusive subscription platform integrations locks in recurring revenue against private-label encroachment.
For New Entrants and Emerging Players: Anchor in veterinary clinic dispensing channels for post-surgical recovery and hospice care protocols, where prescription-adjacent loyalty commands premium pricing with minimal price sensitivity. Target machine-washable microfiber construction for urban apartment dwellers in New York and San Francisco, where 200+ cycle durability justifies 40% price premiums. Go-to-market through Chewy and Amazon Subscribe & Save algorithmic bundling bypasses retail slotting fee barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale domestic manufacturers with Midwest logistics infrastructure and USDA BioPreferred certification pathways, positioned to capture municipal procurement volume anchors. Long-term viability across the analysis window hinges on industrial composting infrastructure development closing disposal pathway gaps for premium biodegradable substrates. Watch EPA landfill leachate standard expansion to additional states as the signal for accelerated substrate transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Certification | USDA BioPreferred unlocks federal procurement preference for military and government kennel supply. |
| Machine-Washable Microfiber Scale-Up | Technical textile durability crosses from industrial applications to capture sustainability-motivated urban buyers. |
| Veterinary Clinic Channel Expansion | Post-surgical dispensing protocols generate prescription-adjacent loyalty and recurring replenishment revenue. |
| Subscription Platform Integration | Chewy and Amazon algorithmic bundling displaces episodic retail purchasing among millennial pet owners. |
| Midwest Logistics Hub Positioning | Chicago and Columbus infrastructure enables two-day fulfillment coverage for 85% of US household demand. |
Research Methodology
Cross-validation between primary interviews with contract manufacturing procurement leads, retail category buyers, and veterinary clinic dispensing managers anchors the qualitative findings against secondary validation from EPA landfill leachate guidance documents, USDA BioPreferred certification databases, and state-level extended producer responsibility framework filings. Customs records tracking Jiangsu and Zhejiang province export volumes, SEC 10-K disclosures from diversified pet care conglomerates, and municipal composting infrastructure readiness assessments complete the source triangulation. Bottom-up demand modeling from subscription replenishment platform data and top-down market sizing from absorbent substrate trade flows converge through iterative reconciliation.
Sensitivity analysis around superabsorbent polymer feedstock cost corridors, tariff rate assumptions on Chinese contract manufacturing, and municipal composting facility deployment timelines stress-tests projection robustness across the analysis window. Segmentation dimensions span product type, material substrate, dimensional format, and performance feature specifications, with additional granularity on buyer archetype stratification between urban apartment dwellers, multi-pet households, and commercial veterinary channels. CAGRs derive from logistic curve fitting on subscription penetration rates and regulatory mandate diffusion patterns, with inputs from absorbent technology R&D pipeline assessments and retailer sustainability scorecard deadline schedules.
Underlying assumptions cover biodegradable substrate absorbency-performance convergence timelines, with deviation risk concentrated in industrial composting infrastructure deployment delays and EPA landfill standard geographic expansion pacing. Practitioners should keep alternative scenarios live as state-level extended producer responsibility framework adoption and superabsorbent polymer feedstock cost volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Paw Plunger Market
Pet Care Products
Cat Bed Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
Pet Transporting Service Market
Pet Care Products
Dog Carrier Bags Market
Pet Care Products
Dog Harness Market
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
South Korea Organic and Natural Pet Food Market
Pet Care Products
Pet Care Ingredients Market