
 Automatic Dog Feeder Market | 2026-2036
Automatic Dog Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Dog Feeder Market Outlook
Buyer concentration among multi-pet households and urban apartment dwellers is recalibrating how manufacturers allocate R&D budgets and channel investments. PetSafe leverages its established distribution network across North American pet specialty retailers to sustain shelf dominance in programmable and gravity feed categories. Petlibro anchors its competitive position through direct-to-consumer digital channels, while WOPET specializes in app-integrated camera feeders that appeal to tech-forward pet owners seeking remote monitoring capabilities.
An automatic dog feeder is an electromechanical or gravity-driven dispensing device engineered to store, measure, and distribute predetermined food quantities at scheduled intervals, typically incorporating timers, load cells, or optical sensors to regulate portion accuracy within five-gram tolerances. These devices serve commercial and residential users by automating canine nutrition management, reducing owner dependency, and supporting veterinary-prescribed feeding regimens for weight management or medication delivery. Smart feeders with IoT-enabled and app-integrated architectures command premium positioning as connectivity becomes a baseline expectation rather than a luxury feature. Sensor-based and timer-controlled variants retain volume leadership in price-sensitive segments, though margin pools increasingly migrate toward subscription-connected ecosystems and AI-driven dietary recommendation engines.
The Federal Communications Commission regulates wireless connectivity modules in US-market smart feeders, while the EU Radio Equipment Directive and REACH chemical safety standards govern product access across European member states. China's GB standards for household electrical appliances and the National Medical Products Administration's oversight of veterinary-adjacent health devices create layered compliance obligations for exporters. Stakeholders must monitor evolving cybersecurity labeling requirements and cross-border data localization rules as connected pet devices collect biometric and behavioral data streams subject to GDPR and emerging state-level privacy statutes.
Market Dynamics
Smart home interoperability mandates and data localization requirements are forcing manufacturers to re-architect connectivity stacks and regionalize cloud infrastructure, compressing margins for exporters while creating compliance moats for domestic incumbents.
Growth Catalysts
- REACH chemical safety standards:EU RoHS and REACH compliance creates certification barriers that favor established players with dedicated regulatory affairs teams, accelerating consolidation among premium-tier suppliers.
- Multi-pet household formation:Urban apartment dwellers with two or more dogs drive demand for portion-controlled, multi-schedule dispensers with separate food compartments.
- AI-driven dietary engines:Machine learning algorithms that adjust portions based on activity data from wearable pet trackers are pulling veterinary clinics into feeder recommendation workflows.
Market Restraints
- Semiconductor supply concentration:WiFi and Bluetooth module sourcing depends heavily on Taiwan and South Korea foundries, exposing manufacturers to geopolitical disruption and allocation rationing.
- FCC certification timelines:US-market wireless device approval cycles stretch 12-16 weeks, delaying product launches and freezing inventory commitments during peak seasonal demand windows.
- Gravity feeder substitution:Low-tech gravity dispensers retain 40% volume share in price-sensitive segments, capping premium smart feeder penetration in emerging markets.
Strategic Opportunities
- Subscription-connected ecosystems:Recurring revenue models integrating fresh food delivery with feeder hardware lock in customer lifetime value and reduce churn.
- EU AI Act compliance:Early alignment with algorithmic transparency requirements positions vendors for preferential treatment in public procurement and veterinary partnership programs.
- Rural underpenetration:Farm and kennel operators in the US Midwest represent an untapped segment for high-capacity commercial feeders with solar power options.
Industry Challenges
- Cybersecurity talent scarcity:Firmware engineering teams lack embedded security specialists capable of implementing GDPR-compliant data encryption and breach notification protocols.
- Legacy system integration:Veterinary practice management software from IDEXX and Covetrus uses proprietary APIs, forcing feeder manufacturers to maintain fragmented integration pipelines.
- Packaging sustainability mandates:California's extended producer responsibility laws require redesign of single-use plastic food hopper liners, complicating supply chain logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Dog Feeder Market |
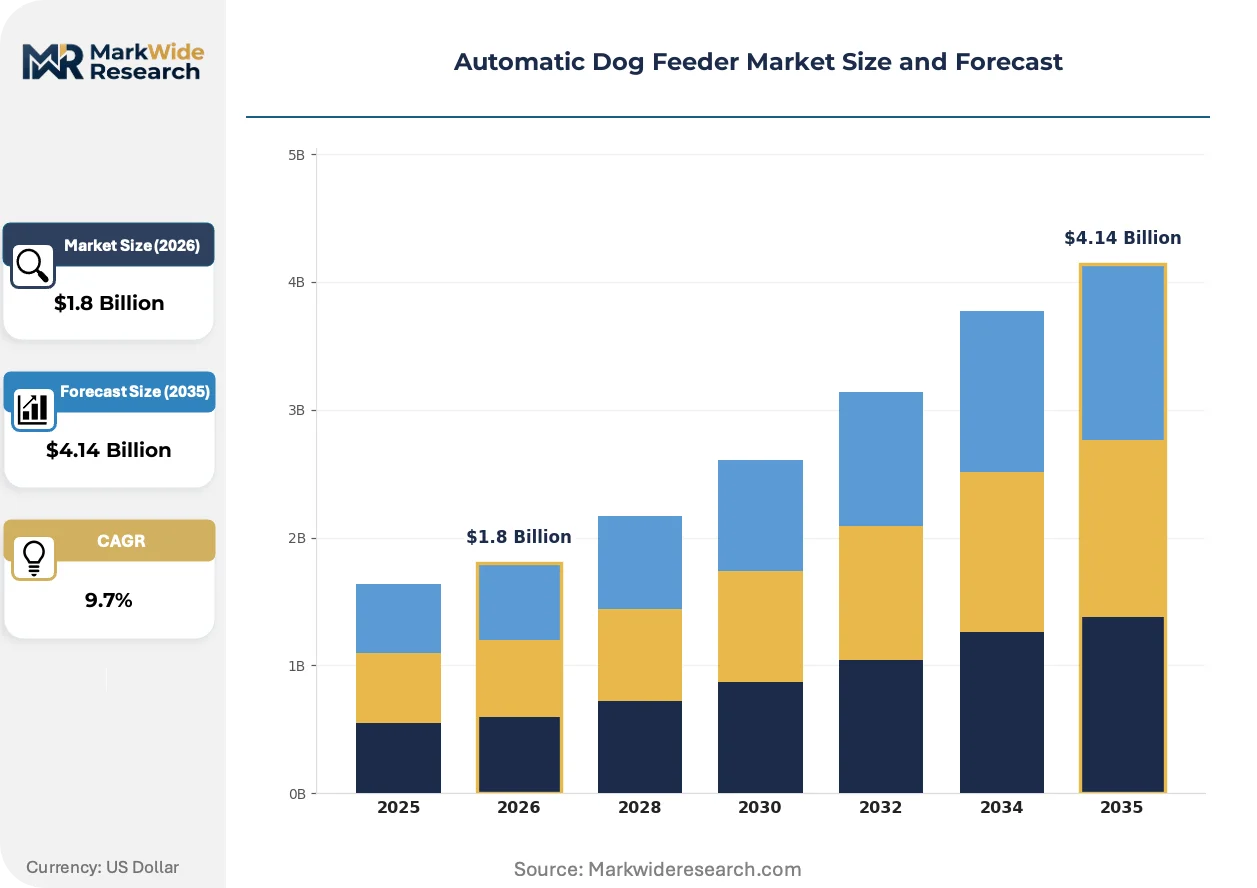
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable, Gravity Feed, Smart Feeders, Portion Control Technology: IoT-Enabled, Sensor-Based, Timer-Controlled, App-Integrated End User: Pet Owners, Veterinarians, Animal Shelters, Dog Trainers Distribution Channel: Online Retail, Pet Specialty Stores, Mass Merchandisers, Direct Sales |
| Companies Covered | PetSafe, Petlibro, Whisker, WOPET, DOGNESS Group, Sure Petcare, Petkit, Arf Pets, Skymee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Dog Feeder Market Strategic Shifts
Feeder hardware architectures are fragmenting into componentized subsystems that third-party developers can reprogram, while regulatory pressure on data handling and buyer expectations of seamless veterinary integration reshape competitive requirements.
Camera-enabled feeding stations with computer vision are modularizing into separate hardware and software layers. Tech-forward pet owners in Germany and the United States adopt these systems fastest, often pairing them with smart collars. This architecture is modularizing the supply chain, allowing white-label camera modules from Shenzhen to integrate with cloud platforms developed in Silicon Valley or Berlin.
GDPR and emerging US state privacy statutes now classify pet behavioral data as personally identifiable information. Manufacturers must regionalize data storage and obtain explicit consent for biometric tracking, adding compliance overhead. Smart feeder vendors with EU-based server infrastructure capture veterinary channel partnerships that competitors with centralized US clouds cannot access.
Veterinary clinics now prescribe specific feeder models as part of weight management protocols, shifting purchase authority from retail consumers to licensed practitioners. Pet specialty retailers respond by hiring certified veterinary technicians as floor staff. This pattern concentrates most visibly in France and the United Kingdom, where insurance-linked wellness programs subsidize connected feeder purchases.
Automatic Dog Feeder Market Segmentation
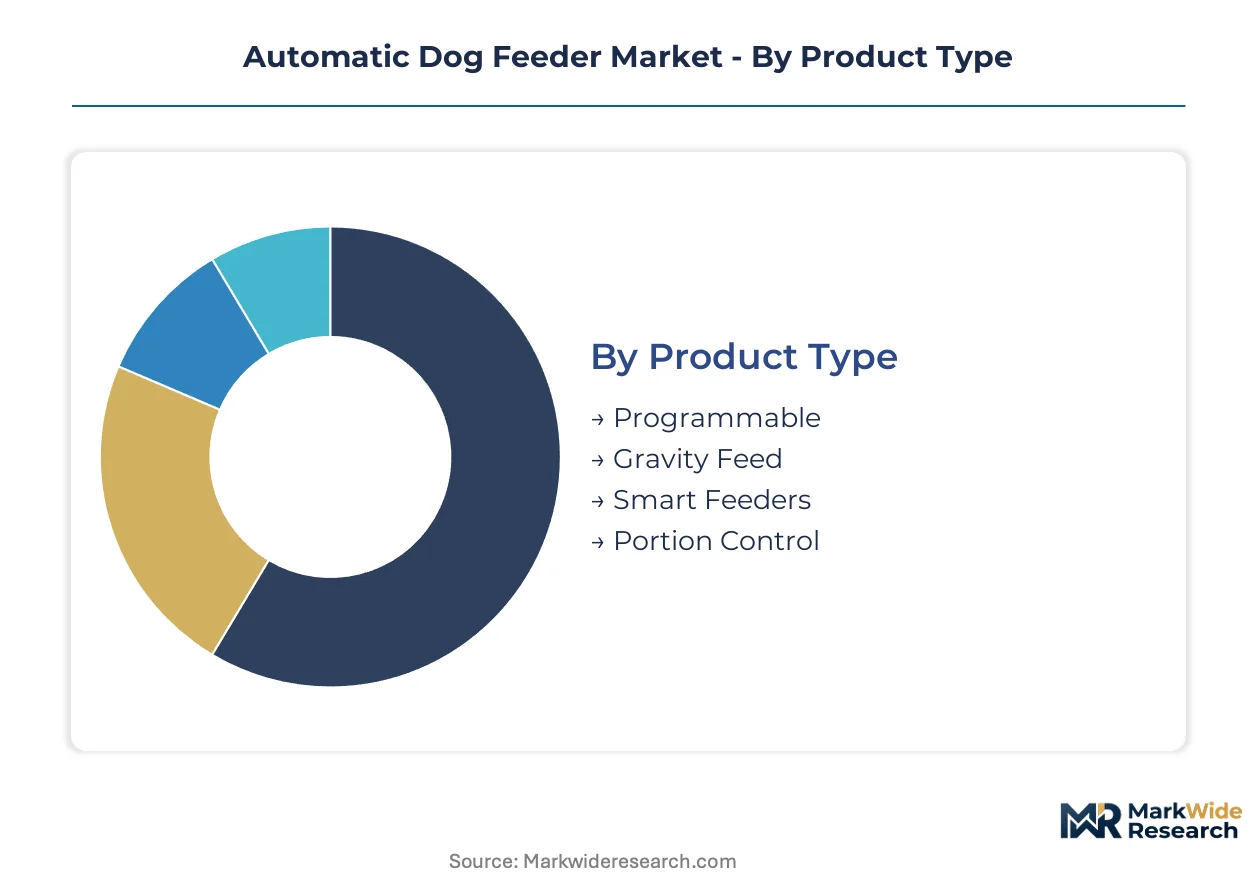
Feeder manufacturers must navigate divergent certification requirements across product architectures, with wireless-enabled systems triggering FCC and EU Radio Equipment Directive obligations that gravity-based alternatives avoid entirely. Segmentation strategy directly shapes compliance spend allocation and go-to-market timing.
Product Type:
Smart feeders with WiFi or Bluetooth modules require FCC Part 15 certification in the United States and CE marking under the EU Radio Equipment Directive, while gravity feed systems face only basic electrical safety testing. Programmable units with digital timers fall between these poles depending on connectivity features.
- Programmable:Electromechanical dispensers with digital timer interfaces and portion calibration dials serve price-conscious households seeking schedule automation without cloud dependency. Demand concentrates in Germany and the United States among working professionals with single-dog households, constrained by battery replacement cycles and limited veterinary data integration.
- Smart Feeders:IoT-enabled architectures with cloud connectivity, camera modules, and mobile app control command premium positioning through subscription revenue potential. Urban apartment dwellers in China and the United States adopt these fastest, pulled by remote monitoring capabilities and integration with wearable pet trackers.
- Gravity Feed:Passive dispensing systems using food weight and mechanical valves require no electromagnetic compliance, minimizing regulatory burden for budget manufacturers.
- Portion Control:Load cell-equipped dispensers with five-gram accuracy tolerances target veterinary-prescribed weight management regimens.
Gravity feed sits at the top of the volume ranking, with smart feeders climbing the fastest.
Technology:
Technology selection determines firmware development costs, with IoT-enabled and app-integrated systems demanding ongoing security patch cycles that timer-controlled alternatives avoid.
- IoT-Enabled:Cloud-connected architectures with MQTT protocol stacks and over-the-air update capabilities enable predictive maintenance and subscription service layering. Demand clusters among tech-forward pet owners in the United States seeking integration with Alexa and Google Home ecosystems.
- App-Integrated:Native iOS and Android applications with real-time video streaming and push notification systems capture veterinary channel partnerships in France and the United Kingdom. GDPR compliance for pet biometric data storage adds infrastructure overhead that fragments vendor competitive position.
- Sensor-Based:Optical or weight-based detection systems trigger dispensing without network connectivity, reducing cybersecurity exposure.
- Timer-Controlled:Standalone microcontroller units with LCD interfaces and battery backup represent the lowest technology cost tier.
Timer-controlled technology maintains the widest installed base, though app-integrated systems are gaining share fastest through veterinary prescription workflows.
End User:
End user type reshapes pricing architecture and channel strategy, with veterinarians and shelters demanding bulk procurement terms that individual pet owners rarely negotiate.
- Pet Owners:Residential consumers purchasing one to two units for household use drive seasonal demand spikes around holiday periods and pet adoption surges. Multi-pet households in urban China represent the fastest-expanding subsegment, requiring dual-compartment dispensers with separate scheduling.
- Veterinarians:Licensed practitioners prescribing specific feeder models as part of weight management protocols shift purchase authority from retail to clinical channels. This pattern concentrates in France and the United Kingdom where insurance-linked wellness programs subsidize connected hardware.
- Animal Shelters:High-volume operators with kennel-scale feeding requirements prioritize durability and cleaning protocols over connectivity features.
- Dog Trainers:Behavioral specialists use timed dispensers for reward-based conditioning programs.
Pet owners dominate absolute unit volume, with veterinarians representing the steepest expansion trajectory through clinical recommendation authority.
Distribution Channel:
Channel selection determines margin capture and customer data ownership, with direct sales offering highest per-unit profitability while mass merchandisers drive volume at compressed returns.
- Online Retail:Amazon and Tmall platforms aggregate price-transparent comparison shopping, forcing manufacturers into advertising spend arms races for search placement. Petlibro and similar direct-to-consumer brands exploit this channel to bypass retail margin stacking.
- Pet Specialty Stores:PetSmart and Petco locations in the United States provide tactile product demonstration and certified veterinary technician staff who influence purchase decisions. Shelf placement fees and promotional calendar alignment constrain smaller manufacturers.
- Mass Merchandisers:Walmart and Target distribution demands high-volume production scales and simplified SKU portfolios.
- Direct Sales:Manufacturer-owned e-commerce sites capture first-party customer data for subscription service conversion.
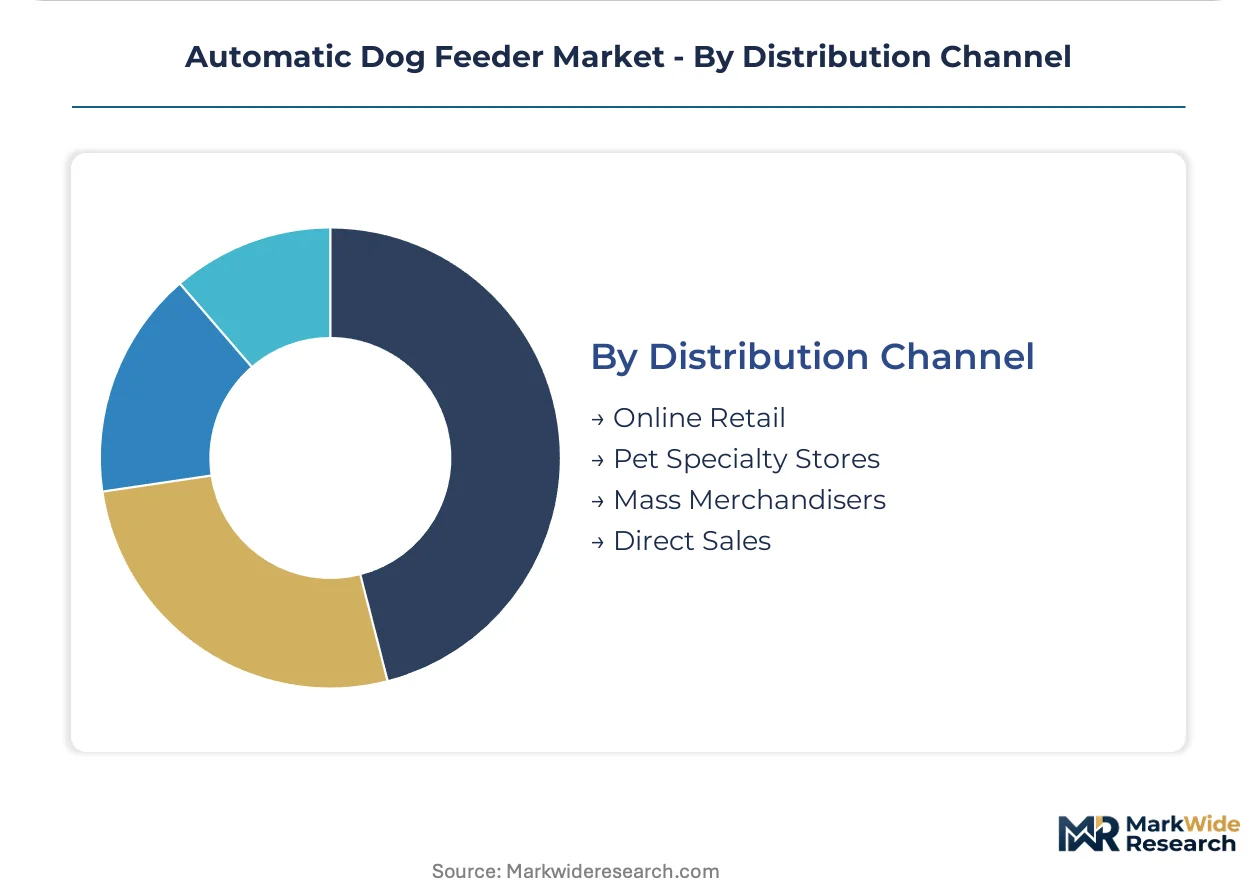
Online retail leads channel volume, with pet specialty stores climbing fastest through experiential merchandising and veterinary staff integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing scale contrasts sharply with Germany's engineering precision in shaping feeder supply chains, while the United States and United Kingdom diverge on data localization requirements that fragment cloud infrastructure strategies.
United States
Multi-pet households in urban apartments drive demand for dual-compartment smart feeders with separate scheduling capabilities. FCC Part 15 certification for wireless modules creates 12-16 week approval bottlenecks that compress seasonal launch windows. San Francisco Bay Area and Austin tech clusters concentrate venture-backed pet tech startups developing AI-driven portion algorithms.
China
GB standards for household electrical appliances and NMPA oversight of veterinary-adjacent devices create layered export compliance obligations for domestic manufacturers. Shenzhen's electronics manufacturing ecosystem supplies white-label camera modules and WiFi chipsets to global brands. Shanghai and Hangzhou host the largest direct-to-consumer pet tech brands leveraging Tmall's platform dominance.
Germany
EU RoHS and REACH chemical safety standards favor established players with dedicated regulatory affairs teams, accelerating premium-tier consolidation. Munich and Stuttgart engineering clusters specialize in precision load cell manufacturing for veterinary-grade portion control systems. Berlin startups focus on GDPR-compliant data architecture for EU-based server infrastructure.
United Kingdom
Insurance-linked wellness programs subsidize connected feeder purchases through veterinary prescription workflows, shifting purchase authority from retail to clinical channels. The UK Medicines and Healthcare products Regulatory Agency's evolving stance on connected health devices creates certification uncertainty. London's fintech-pet tech crossover ecosystem develops subscription billing platforms integrated with feeder hardware.
France
ANSM and CNIL oversight of biometric data collection from camera-enabled feeders mandates explicit consent protocols for pet behavioral tracking. Lyon and Toulouse veterinary research clusters pilot weight management protocols incorporating prescribed feeder models. Paris-based pet specialty retailers employ certified veterinary technicians to influence connected hardware purchase decisions.
Automatic Dog Feeder Market Competitive Environment
United States producers anchor the premium smart feeder tier; Chinese specialists hold volume leadership in component supply and white-label manufacturing. The vendor base structures around three strategic archetypes: established pet product conglomerates with retail shelf dominance, direct-to-consumer digital natives with subscription revenue models, and component suppliers modularizing into separable hardware and software layers. Competitive moves concentrate on M&A for regulatory compliance capabilities and strategic partnerships with veterinary practice management software providers.
Within the premium-tier vector, PetSafe exemplifies retail-channel incumbency through established North American pet specialty distribution, while Petlibro occupies a position as the archetypal direct-to-consumer digital native bypassing traditional retail margin structures. WOPET represents the camera-integrated specialization archetype, sitting within the app-connected segment where remote monitoring capabilities command price premiums. These three anchors illustrate the strategic divergence between physical retail dependency and digital-first customer acquisition models reshaping competitive position.
| Leading Market Players |
|---|
| PetSafe |
| Petlibro |
| Whisker |
| WOPET |
| DOGNESS Group |
| Sure Petcare |
| Petkit |
| Arf Pets |
| Skymee |
| Others |
Value Chain & Pricing Dynamics
Modular camera-vision architectures from Shenzhen are compressing smart feeder hardware costs while fragmenting margin pools toward cloud software layers, simultaneously enabling new entrants to bypass legacy electromechanical supply relationships and forcing incumbents to defend value capture through subscription bundling rather than device premiums alone.
Pricing Analysis
Capacity additions in China's electronics manufacturing clusters are reshaping price floors for WiFi-enabled feeders, eroding the premium once commanded by FCC-certified US-market variants. Three-tier pricing structure across premium, standard, and economy levels separates subscription-integrated smart systems from programmable timer units and passive gravity dispensers. Pricing pressure stems from white-label component availability and direct-to-consumer channel bypass. Urban apartment dwellers with multi-pet households exhibit lowest price sensitivity; rural farm operators and budget-conscious single-pet owners drive economy-tier volume.
Supply Chain Analysis
FCC Part 15 and EU Radio Equipment Directive certification gates concentrate viable finished-goods assembly among China, Vietnam, and Mexico facilities with established electromagnetic compliance testing partnerships. Load cells and optical sensors draw from German and Japanese precision component suppliers; WiFi modules and camera subsystems rest on Taiwan and South Korea semiconductor foundries. Single-source vulnerability in Bluetooth chipset allocation from Taiwan exposes manufacturers to geopolitical disruption. Distribution runs through Shenzhen contract manufacturers to direct-to-consumer platforms and North American pet specialty retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on software-subscription layering and veterinary channel capture, with component cost compression from modular camera architectures creating headroom for premium-tier reinvestment.
For Market Incumbents: Lock in veterinary practice management software integrations with IDEXX and Covetrus to defend against direct-to-consumer disintermediation, while backward integration into load cell manufacturing secures supply continuity against Taiwan semiconductor allocation rationing. FCC certification timeline compression through pre-submission testing investments protects seasonal launch windows from 12-16 week approval bottlenecks. For New Entrants and Emerging Players: AI-driven dietary recommendation engines that ingest wearable pet tracker data offer a technology-first wedge into veterinary prescription workflows, where purchase authority shifts from retail consumers to licensed practitioners. Rural farm and kennel operators in the US Midwest represent the most penetrable white-space segment, accessible through solar-powered high-capacity commercial feeder development and agricultural supply channel partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among white-label component suppliers with modular camera-module capabilities and GDPR-compliant EU cloud infrastructure, as regulatory moats widen against US-centralized competitors. Long-term viability favors vendors with subscription-connected ecosystems and veterinary channel lock-in over pure hardware plays. The signal to watch is insurance-linked wellness program expansion in France and the United Kingdom subsidizing connected feeder prescriptions.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Practice Management Integration | API partnerships with IDEXX shift purchase authority from retail to clinical channels in insurance-subsidized markets. |
| GDPR-Compliant EU Cloud Infrastructure | Berlin-based server architecture unlocks veterinary partnerships blocked from US-centralized data storage. |
| Subscription-Connected Fresh Food Delivery | Recurring revenue models with Petlibro-style direct-to-consumer bundling reduce customer churn and lift lifetime value. |
| Modular Camera-Vision Hardware Layering | Shenzhen white-label module integration enables rapid product iteration without captive manufacturing investment. |
| EU AI Act Algorithmic Transparency Alignment | Early compliance positions vendors for preferential treatment in public procurement and veterinary partnership programs. |
Study Parameters
Direct dialogue with pet tech product managers, veterinary clinic procurement leads, FCC certification consultants, and pet specialty retail category buyers combined with secondary validation against FCC equipment authorization databases, EU CE marking registries, and Tmall/Amazon sales rank data. Bottom-up unit economics modeling triangulated against top-down market sizing from customs trade records and pet industry association membership surveys.
Segment-level projections across product type, connectivity architecture, end user category, and distribution channel fed into a consolidated analytical framework over the projection horizon. CAGRs derived from regression analysis of replacement cycle dynamics, pet humanization trend indices, and smart home penetration rates. Veterinary prescription workflow adoption curves and multi-pet household formation rates served as industry-specific demand drivers.
The model holds under stable FCC certification timelines and continued semiconductor foundry allocation; deviation in Taiwan geopolitical conditions or EU data localization enforcement stringency would shift cloud infrastructure cost assumptions and regional competitive positioning. A model refresh is warranted upon material change in insurance-linked wellness program subsidy policies or cybersecurity labeling mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Global Pet Companion Robots Market
Pet Care Products
Pet Grooming Market
Pet Care Products
Pet Supplement Market
Pet Care Products
Germany Pet Food Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Dog Food Market
Pet Care Products
Dog Perfume Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Germany Pet Training Services Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Dog Safety Leash Market
Pet Care Products
Aquarium Market
Pet Care Products
Smart Connected Pet Collar Market
Pet Care Products
Dog Brush Market
Pet Care Products
Pet Gadgets Market