
 Philippines Pet Food Market | 2026-2036
Philippines Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Pet Food Market Insights
Single-serve pouch bundling is restructuring how Filipino households purchase wet food, shifting volume from bulk bags toward trial-sized multipacks. Mars Incorporated leverages its veterinary clinic partnerships to anchor premium positioning in Metro Manila, while Royal Canin Philippines specializes in breed-specific therapeutic formulations for the expanding small-dog population. Nestlé Purina PetCare competes through supermarket shelf-space dominance, extending its reach into provincial capitals beyond the National Capital Region.
Philippines pet food comprises nutritionally formulated feed products manufactured to specific protein, fat, fiber, and moisture specifications for domestic animal consumption, typically processed through extrusion for dry kibble or retort sterilization for wet formulations. Dry food occupies the largest volume share due to shelf stability and lower per-kilogram cost, yet wet food and treats capture disproportionate margin pools as humanization trends intensify. Online retail represents the fastest-growing distribution channel, though veterinary clinics retain premium pricing power for prescription diet segments.
The Philippines Department of Agriculture's Bureau of Animal Industry enforces feed safety standards, while the Food and Drug Administration evaluates veterinary health claims on therapeutic products. BIS nutritional labeling requirements are forcing reformulation investments among domestic manufacturers, and the ASEAN Harmonized Regulatory Scheme shapes import protocols for multinational suppliers. Stakeholders must monitor how evolving pet ownership demographics in secondary cities alter channel mix and product premiumization trajectories.
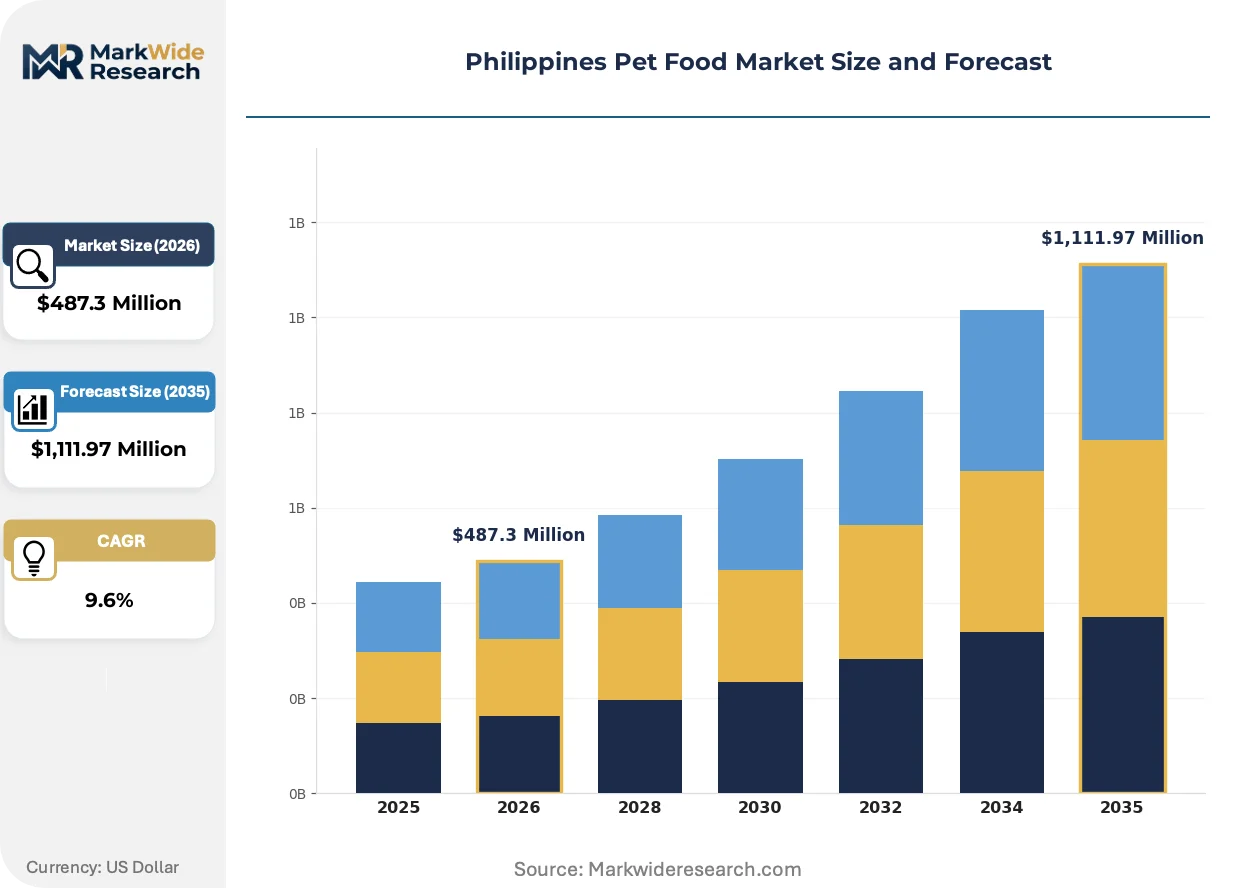
Market Dynamics
BIS nutritional labeling requirements are forcing domestic manufacturers to reformulate product portfolios, while single-serve pouch bundling restructures household purchasing patterns across Metro Manila and Cebu City. These dual pressures are compressing margins for legacy dry-food producers while opening premium positioning for veterinary-aligned brands.
Growth Catalysts
- Urban pet humanization:Metro Manila's expanding small-dog population drives breed-specific therapeutic demand, with veterinary clinics capturing premium pricing power through prescription diet anchoring.
- Bureau of Animal Industry enforcement:The Philippines Department of Agriculture's feed safety standards are elevating formulation quality floors, disqualifying informal imports and consolidating share among compliant domestic producers.
- E-commerce channel acceleration:Online retail is unifying provincial access beyond National Capital Region supermarket dominance, enabling direct-to-consumer trial-sized multipack distribution into secondary cities.
Market Restraints
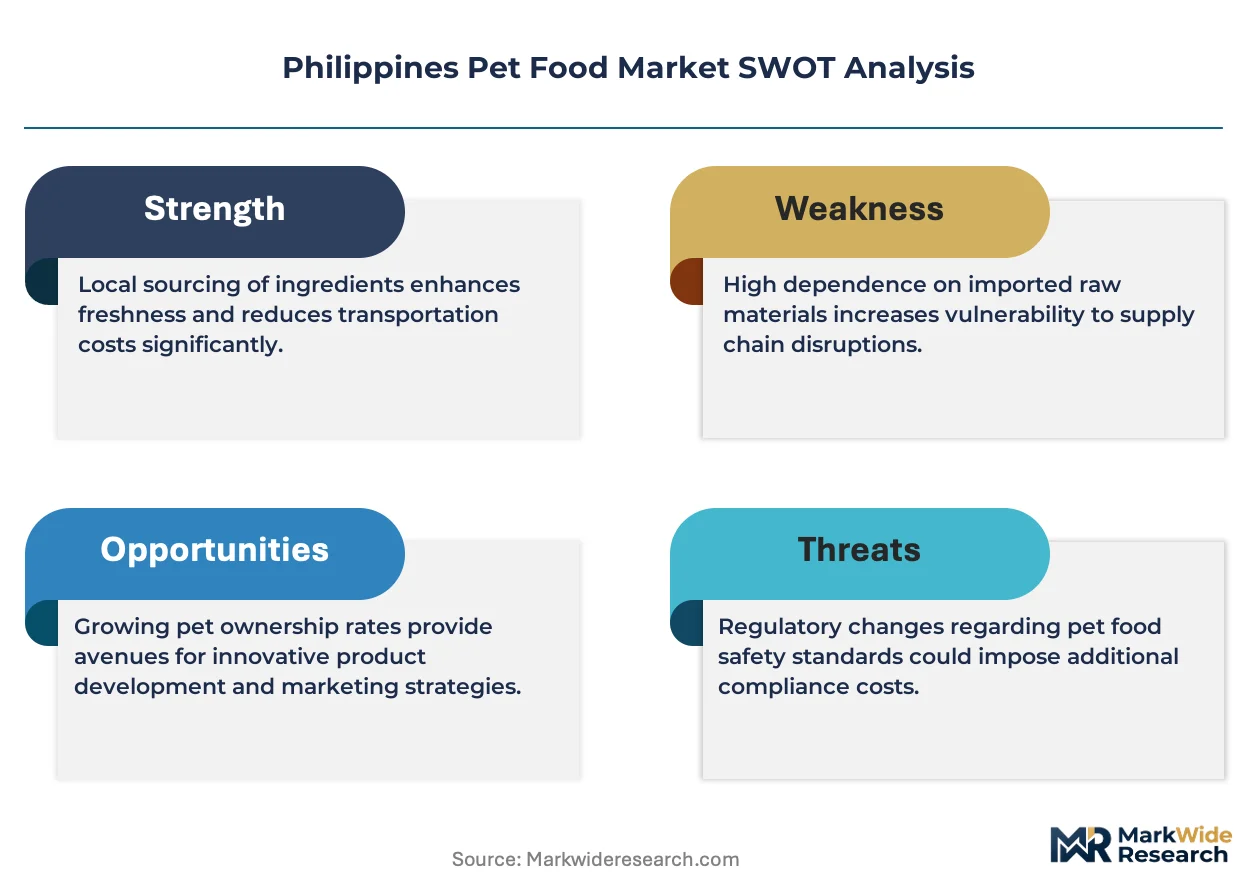
- Input cost volatility:Imported protein meal and vitamin premix prices fluctuate with peso-dollar exchange rates, compressing gross margins for extrusion-dependent dry kibble manufacturers.
- Supply concentration risk:Retort sterilization capacity clusters in Luzon-based facilities, creating geographic vulnerability for wet food distribution to Visayas and Mindanao.
- Regulatory friction:ASEAN Harmonized Regulatory Scheme import protocols delay multinational therapeutic product registrations, limiting veterinary diet availability during formulation transition periods.
Strategic Opportunities
- Davao City and Cagayan de Oro penetration:Underdeveloped veterinary clinic networks in southern Philippines present first-mover positioning for breed-specific therapeutic brands establishing provincial specialist partnerships.
- Functional treat convergence:Humanization trends are unifying nutritional supplementation with reward behavior, creating white space for dental health and joint support formats beyond traditional kibble-wet bifurcation.
- Food and Drug Administration tailwind:Streamlined veterinary health claim evaluation pathways for locally manufactured products incentivize domestic production investment over import-dependent models.
Industry Challenges
- Formulation talent scarcity:Veterinary nutritionist expertise concentrates in multinational headquarters, forcing domestic manufacturers to rely on external technical service agreements for BIS-compliant label development.
- Legacy extrusion asset reconfiguration:Existing dry-food production lines require capital-intensive modification to achieve moisture and protein specifications demanded by premiumization trajectories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Pet Food Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,111.97 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Animal Type: Dogs, Cats, Birds, Small Mammals Distribution Channel: Supermarkets, Pet Stores, Online Retail, Veterinary Clinics Packaging Type: Bags, Cans, Pouches, Bulk |
| Companies Covered | Colgate-Palmolive Company, Archer Daniels Midland Company, Mars Incorporated, Royal Canin Philippines, General Mills Inc, Nestlé Purina PetCare, San Miguel Corporation, Pet Express Philippines, Charoen Pokphand Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Pet Food Market Trends and Innovations
Retort pouch technology and nutritional transparency requirements are converging to reshape product architecture, with implications for manufacturing investment, channel strategy, and consumer communication across the Philippine archipelago.
Cold-fill retort pouch systems are unifying wet food shelf stability with portion-controlled convenience. Urban dog owners in Metro Manila are adopting trial-sized multipacks at accelerating velocity, compressing bulk bag volume share while expanding margin pools for manufacturers capable of flexible packaging line investments.
The Food and Drug Administration's veterinary health claim evaluation protocols are tightening evidentiary standards for therapeutic positioning. Domestic manufacturers face extended registration timelines for condition-specific formulations, while multinational suppliers leverage pre-approved ASEAN dossiers to accelerate market entry for renal and weight management diets.
Subscription-based replenishment models are displacing supermarket bulk purchasing among high-income households. Online platforms capture recurring dry food orders previously fulfilled by Nestlé Purina's provincial shelf-space dominance, with auto-delivery incentives locking in brand loyalty before veterinary clinic referral influence activates.
Philippines Pet Food Market Segmentation
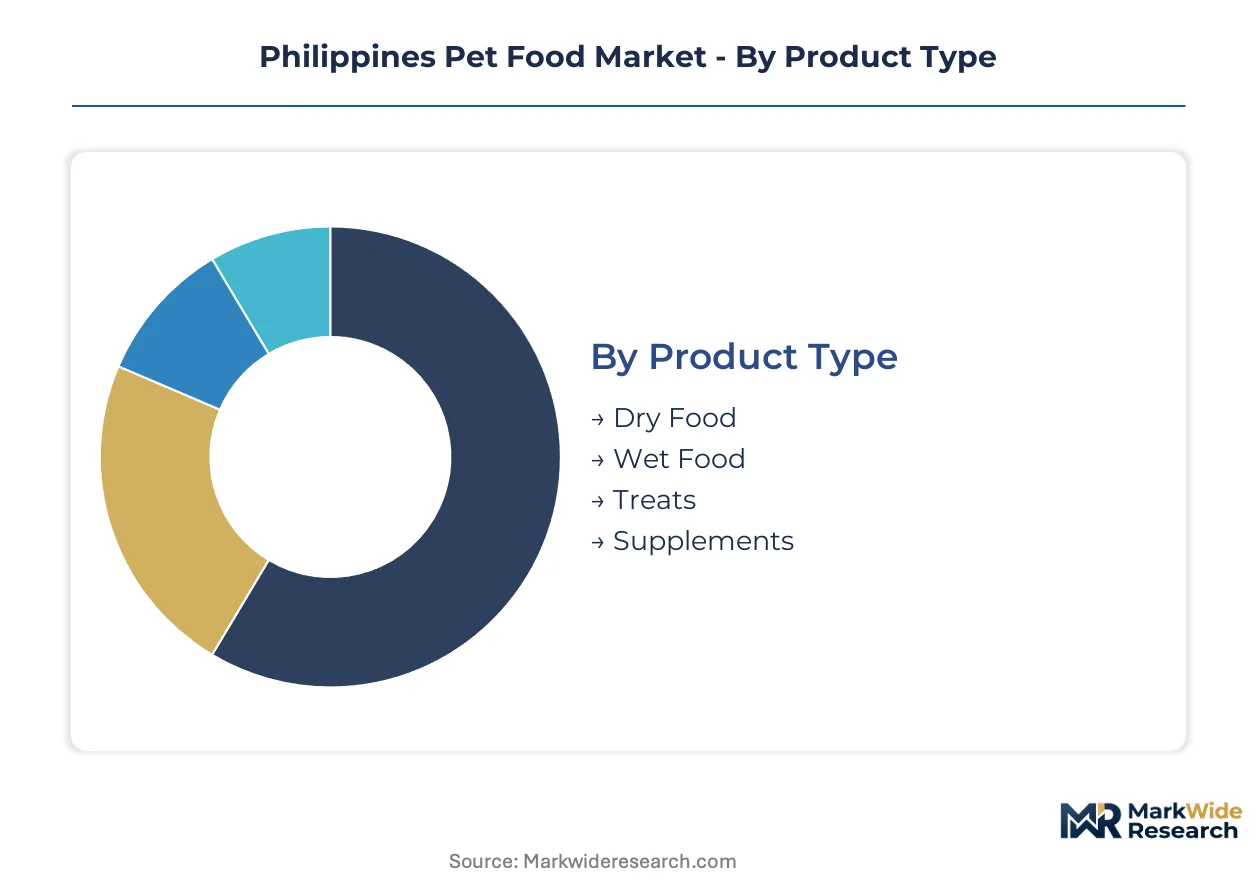
Philippines pet food segmentation reveals how channel architecture and packaging innovation reshape purchasing economics. Manufacturers align formulation investments with animal-specific nutritional requirements while navigating regulatory enforcement from the Bureau of Animal Industry.
Product Type:
Standalone consumption formats dominate household purchasing, while embedded nutritional systems require veterinary integration for therapeutic activation.
- Dry Food:Extrusion-processed kibble delivers shelf-stable protein-fat-fiber specifications at lowest per-kilogram cost. Volume concentrates in Metro Manila bulk purchasing, though margin compression from peso-dollar exchange rate volatility constrains manufacturer flexibility.
- Wet Food:Retort-sterilized formulations achieve higher moisture content and palatability thresholds. Demand clusters in urban small-dog households, with single-serve pouch bundling restructuring trial behavior across Cebu City and Davao City.
- Treats:Functional reward formats unify supplementation with behavioral conditioning.
- Supplements:Veterinary-directed nutritional add-ons require prescription anchoring for premium positioning.
Volume placements concentrate in Dry Food; the faster expansion belongs to Wet Food.
Animal Type:
Companion animal economics diverge sharply from ornamental or utility species, with regulatory scrutiny intensifying for food-producing categories.
- Dogs:Breed-specific therapeutic demand from Metro Manila's expanding small-dog population drives veterinary clinic premium capture. Royal Canin Philippines specializes in size-specific formulations, while Mars Incorporated leverages clinic partnerships for prescription anchoring.
- Cats:Renal and urinary health positioning gains traction among urban households, with wet food preference exceeding dog categories due to obligate carnivore hydration requirements.
- Birds:Seed and pellet formulations serve ornamental aviculture with limited premiumization potential.
- Small Mammals:Rabbit and guinea pig segments remain underdeveloped outside specialty pet store channels.
Commercial gravity centers on Dogs; Cats are climbing the fastest among companion animals.
Distribution Channel:
Channel selection determines pricing power, with credential-dependent segments commanding structural premiums over mass-market alternatives.
- Supermarkets:Nestlé Purina PetCare dominates shelf-space allocation, extending provincial reach beyond National Capital Region concentration.
- Pet Stores:Specialty retailers capture enthusiast demand for premium and import-positioned brands.
- Online Retail:Subscription replenishment models displace bulk purchasing among high-income households, with auto-delivery incentives locking loyalty before veterinary referral influence activates.
- Veterinary Clinics:Prescription diet anchoring captures premium pricing power through therapeutic claim authorization, with BIS nutritional labeling requirements reinforcing clinic gatekeeper status.
Supermarkets retain volume dominance; Online Retail is gaining share fastest through direct-to-consumer trial distribution.
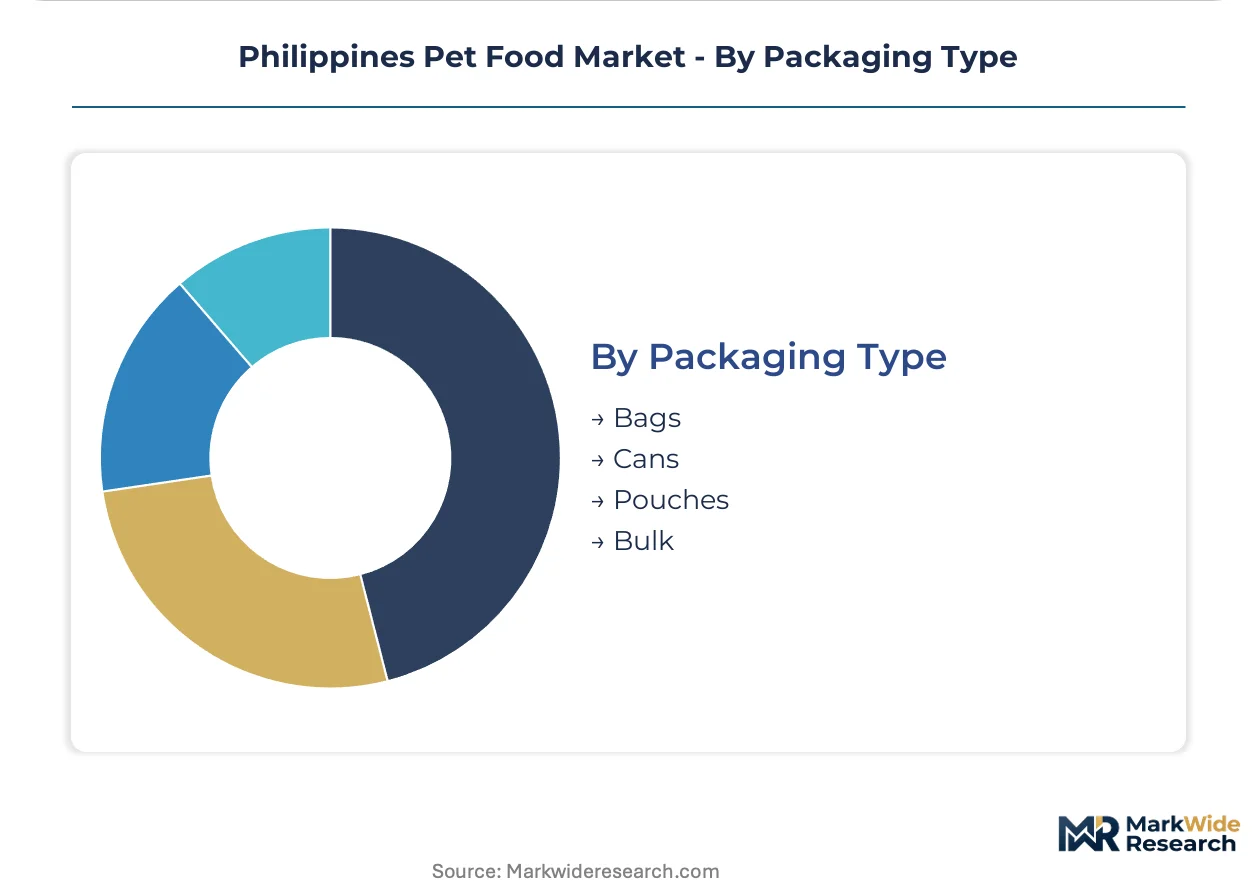
Packaging Type:
Packaging economics reflect manufacturing asset location and logistics constraints across the Philippine archipelago.
- Bags:Multi-layer polymer structures dominate dry food distribution, with extrusion-dependent producers optimizing for shelf stability and transport efficiency.
- Cans:Metal packaging retains wet food volume despite weight penalties in Visayas and Mindanao distribution.
- Pouches:Cold-fill retort systems unify portion control with convenience, compressing bulk bag share as Metro Manila households adopt trial-sized multipacks.
- Bulk:Institutional and multi-pet household formats face margin pressure from single-serve premiumization trends.
Bag placements lead absolute volume; Pouch formats show steepest expansion trajectory among urban consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philippines pet food production clusters in Luzon-based extrusion and retort facilities, while consumption concentrates in Metro Manila, Cebu City, and emerging southern metros where veterinary clinic networks and e-commerce penetration diverge sharply.
Metro Manila
Metro Manila's expanding small-dog population drives breed-specific therapeutic demand, with Mars Incorporated leveraging veterinary clinic partnerships for prescription anchoring. The Food and Drug Administration evaluates therapeutic health claims from its central office in Manila, creating regulatory proximity for multinational registrants. Quezon City and Makati concentrate the densest veterinary clinic networks, capturing premium pricing power through BIS nutritional labeling gatekeeping.
Cebu City
Cebu City's urban households are adopting single-serve wet food pouches at accelerating velocity, compressing bulk bag volume share. The Bureau of Animal Industry maintains regional feed safety enforcement capacity through its Central Visayas office, elevating compliance floors for imported products. Mandaue City's retort sterilization facilities serve Visayas distribution, though geographic vulnerability persists for Mindanao-bound shipments.
Davao City
Davao City's underdeveloped veterinary clinic networks present first-mover positioning for breed-specific therapeutic brands establishing provincial specialist partnerships. The Department of Agriculture's regional field office administers feed safety inspections with limited therapeutic nutrition expertise. Davao del Sur's emerging pet ownership demographics alter channel mix as online retail platforms unify provincial access.
Cagayan de Oro
Cagayan de Oro's northern Mindanao location positions it as a logistics hub for wet food distribution to underserved southern markets. The Bureau of Animal Industry's Northern Mindanao office enforces import documentation requirements with variable consistency. Misamis Oriental's supermarket and pet store channels retain traditional bulk purchasing patterns despite e-commerce penetration in higher-income segments.
Philippines Pet Food Market Competitive Landscape
The competitive structure tilts toward multinational brand dominance anchored by veterinary clinic partnerships and supermarket shelf-space allocation. Tiered concentration separates prescription-aligned therapeutics from mass-market dry kibble, with domestic manufacturers occupying mid-tier positions constrained by formulation expertise scarcity. Three archetypes define positioning: veterinary-anchored premium brands, supermarket-dominant mass-market suppliers, and import-dependent specialty distributors. Capacity expansion in retort sterilization and strategic partnerships with provincial clinic networks constitute the dominant competitive moves reshaping market access.
Within the multinational tier, Mars Incorporated, Nestlé Purina PetCare, and Royal Canin Philippines exemplify divergent channel strategies. Mars Incorporated occupies a position anchored by veterinary clinic integration. Nestlé Purina PetCare sits within supermarket shelf-space dominance extending into provincial capitals. Royal Canin Philippines represents breed-specific therapeutic specialization for small-dog demographics. Domestic players including San Miguel Corporation and Charoen Pokphand Group occupy mid-tier manufacturing positions constrained by BIS-compliant label development requirements.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Archer Daniels Midland Company |
| Mars Incorporated |
| Royal Canin Philippines |
| General Mills Inc |
| Nestlé Purina PetCare |
| San Miguel Corporation |
| Pet Express Philippines |
| Charoen Pokphand Group |
| Others |
Pricing and Supply Chain Analysis
Veterinary-prescription anchoring versus supermarket mass-market bifurcation structures Philippine pet food economics across divergent margin pools, with clinic-gated therapeutic tiers commanding structural premiums while peso-denominated bulk kibble faces relentless cost compression from imported input exposure.
Pricing Analysis
Margin tightening in mass-market dry kibble reflects peso-dollar exchange rate volatility pressuring imported protein meal and vitamin premix costs, while subscription-based replenishment models displace traditional bulk purchasing among high-income Metro Manila households. Three-tier pricing structure across premium therapeutic, standard specialty, and economy dry segments stratifies buyer segments, with veterinary clinic networks capturing least price-sensitive demand through prescription authorization and provincial supermarket channels retaining maximum sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for vitamin premix and specialized protein inputs are emerging among quality-focused manufacturers seeking to mitigate concentration risk in Luzon-based extrusion facilities. Raw material dependencies draw from US and Australian protein meal suppliers, Thai vitamin premix specialists, and domestic grain processors, with retort sterilization capacity clustering creating geographic vulnerability for Visayas and Mindanao wet food distribution. Tariff exposure on ASEAN-imported therapeutic formulations compounds regulatory friction, while distribution runs through veterinary clinic networks for premium tiers and supermarket wholesale for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Philippine pet food is transitioning from legacy extrusion-dependent dry kibble dominance toward retort pouch flexibility and veterinary-anchored therapeutic positioning, with cold-fill sterilization technology displacing traditional bulk bag economics across urban household purchasing patterns.
For Market Incumbents: Extend veterinary clinic partnership density in Metro Manila and Cebu City to reinforce prescription anchoring against subscription-based online retail encroachment, while retrofitting Luzon extrusion assets for moisture-flexible production to capture wet food margin expansion without greenfield capital deployment. For New Entrants and Emerging Players: Begin with Davao City and Cagayan de Oro veterinary network white space, where breed-specific therapeutic demand outpaces specialist supply, leveraging direct-to-consumer trial-sized multipack distribution to establish brand recognition before incumbent clinic partnership expansion activates. For Investors and Strategic Acquirers: Exit pathways concentrate in multinational portfolio rationalization of non-core Southeast Asian assets, with mid-tier domestic manufacturers possessing BIS-compliant label capabilities and Luzon production assets representing prime acquisition targets; watch for Bureau of Animal Industry enforcement intensity shifts as inflection signal for compliance-premium capture viability.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Line Investment | Cold-fill sterilization capacity captures wet food margin expansion in Metro Manila and Cebu City. |
| Veterinary Clinic Network Expansion | Provincial specialist partnerships in Davao City and Cagayan de Oro anchor prescription pricing power. |
| Subscription Platform Launch | Auto-delivery incentives lock loyalty before veterinary referral influence activates among high-income households. |
| BIS Label Compliance Investment | Bureau of Animal Industry nutritional transparency requirements disqualify informal import competitors. |
| Provincial E-Commerce Penetration | Direct-to-consumer trial distribution bypasses Nestlé Purina's supermarket shelf-space dominance beyond National Capital Region. |
Research Methodology
Independent corroboration across Bureau of Animal Industry enforcement officials, veterinary clinic procurement managers, and supermarket category buyers underwrites the qualitative findings, with secondary validation drawing from FDA veterinary health claim filings, Department of Agriculture feed safety inspection records, and e-commerce platform transaction disclosures, combining bottom-up channel volume estimates with top-down production capacity assessments.
Rate-of-change decomposition across the analysis window segments expansion by product type, animal species, distribution channel, and regional metropolitan cluster, with CAGRs derived from historical trajectory analysis adjusted for BIS regulatory implementation timelines and peso exchange rate sensitivity modeling, incorporating veterinary clinic network density and retort sterilization capacity utilization as industry-specific forecast inputs.
Regulatory enforcement intensity, peso-dollar exchange rate volatility, and veterinary nutritionist talent availability are the dominant revision risks; deviation in Bureau of Animal Industry inspection frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
Pet Sitting Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Pet Clothing Market
Pet Care Products
Pet Collar Market
Pet Care Products
Robotic Pets Market
Pet Care Products
Pet Pens Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Pet Apparel Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
India Pet Food Market
Pet Care Products
Dog Food for Small Breeds Dogs Market