

Outdoor Apparel and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Apparel and Accessories Market Insights
Multi-source material procurement is realigning how outdoor brands manage supply resilience and cost exposure. Patagonia leverages its vertically integrated supply chain to control recycled nylon sourcing from ocean plastics. Columbia Sportswear anchors its competitive position through scale manufacturing across diversified Asian production bases. Arc'teryx Equipment differentiates via in-house lamination expertise for waterproof-breathable membranes.
Outdoor apparel and accessories encompass technical garments, footwear, and equipment engineered with specified hydrostatic head ratings, moisture vapor transmission rates, and denier-weighted fabrics for environmental protection during human-powered recreation. These products serve commercial purposes spanning hazard mitigation, thermoregulation, and load carriage across variable terrain and weather conditions. Jackets command the largest margin pool due to complex lamination and seam-sealing requirements, while trail running footwear represents the fastest-expanding product type as urban consumers migrate toward hybrid outdoor-athletic use cases. Backpacks built from high-denier nylon with internal frame suspension systems sustain premium pricing in climbing and extended trekking segments.
REACH chemical restrictions in Europe and state-level PFAS prohibitions in the US are forcing reformulation of durable water repellent chemistries across the supply base. The EU Green Deal's textile circularity requirements and California's Safer Consumer Products regulations are reshaping material certification demands and market access conditions. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance cost allocation and sourcing region selection.
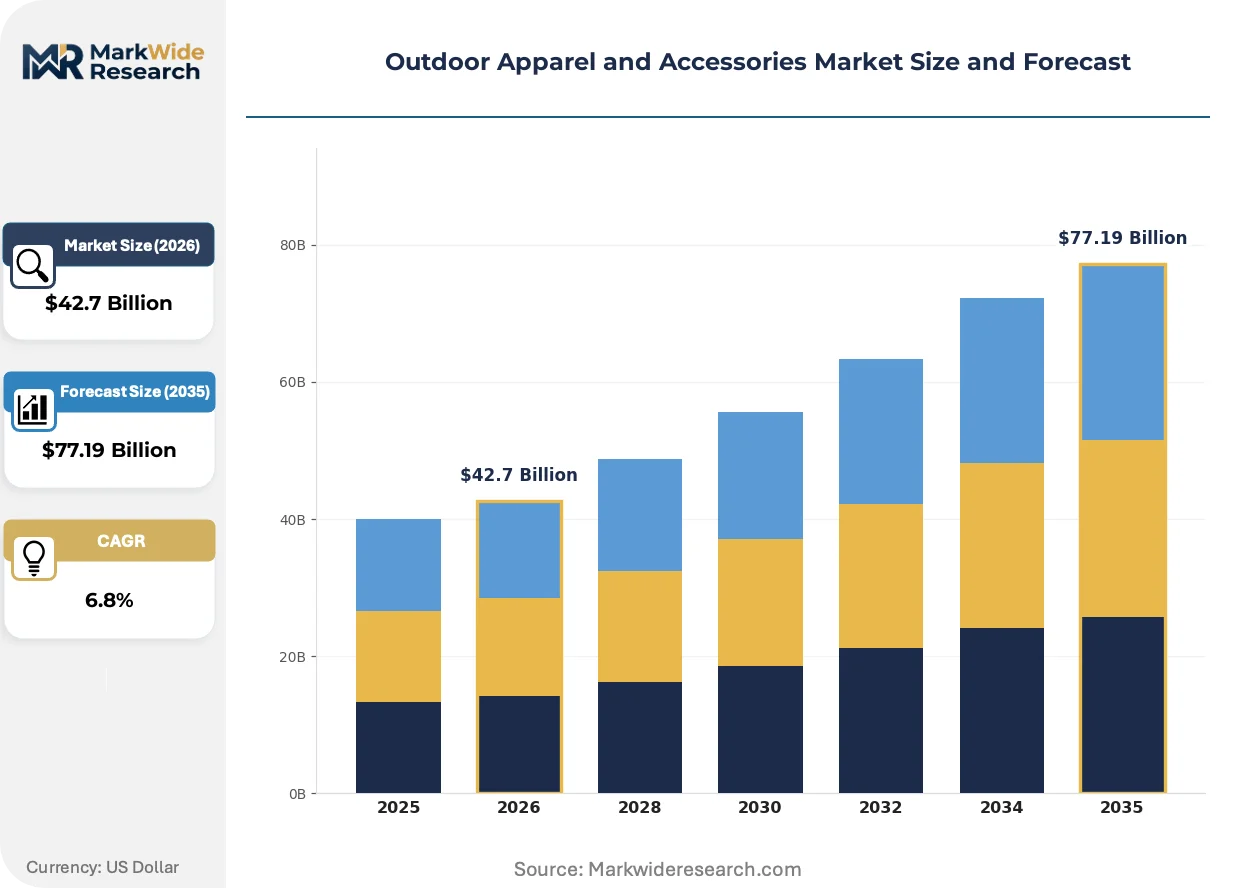
Market Dynamics
REACH chemical restrictions and state-level PFAS prohibitions are forcing wholesale reformulation of durable water repellent chemistries across the outdoor supply base, compressing margins while opening first-mover advantages for compliant material innovators.
Growth Catalysts
- EU Green Deal textile circularity mandates:Mandatory recycled content thresholds are accelerating certified recycled polyester capacity expansion across European supply chains.
- Trail running footwear demand:Urban consumers migrating toward hybrid outdoor-athletic use cases are pulling technical performance specifications into daily wear categories.
- Bio-based membrane R&D:Polyurethane alternatives derived from castor oil and algae are achieving hydrostatic head ratings competitive with petroleum-based laminates.
Market Restraints
- Fluorinated chemistry dependency:Legacy DWR formulations face phased elimination under EPA PFAS guidance and Maine state prohibitions, straining performance parity timelines.
- Recycled nylon supply concentration:Ocean plastic collection networks cluster in Southeast Asian coastal zones, exposing brands to monsoon season collection volatility.
- Seam-sealing labor intensity:Waterproof-breathable jacket production requires skilled technician pools concentrated in Guangdong and Fujian provinces.
Strategic Opportunities
- Repair and resale platforms:Patagonia's Worn Wear model demonstrates margin recovery from post-consumer garment streams while building lifetime customer value.
- Rental and subscription channels:Specialized alpine equipment for intermittent use cases is migrating toward REI and regional co-op rental networks.
- California Safer Consumer Products regulations:Early compliance with chemical disclosure requirements opens preferential retail placement in the state's outdoor specialty channel.
Industry Challenges
- Lamination technician scarcity:In-house waterproof-breathable membrane production requires specialized heat-press calibration expertise concentrated in legacy Japanese and Canadian facilities.
- Multi-jurisdiction certification lag:OEKO-TEX and bluesign approvals for reformulated DWR chemistries extend 18-24 months, delaying product launches.
- Legacy ERP integration:Material traceability requirements for EU Digital Product Passports clash with decades-old inventory systems at mid-tier manufacturers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Apparel and Accessories Market Trends and Innovations
Material science breakthroughs and regulatory compliance automation are compressing product development cycles while fragmenting competitive advantage sources across the value chain.
Mechanically recycled polyester from post-consumer PET bottles is converging with bio-based elastane in four-way stretch woven fabrics, enabling trail running apparel that meets both performance and circularity specifications. Marathon and ultra-running cohorts in Germany and Colorado are adopting these hybrid constructions at premium price points. The convergence is displacing virgin nylon in mid-layer categories where moisture management and packability converge.
ECHA's restriction proposal for microplastic release from synthetic textiles is mandating filtration attachments on domestic washing machines across EU member states. Industrial laundries serving rental and subscription channels must retrofit membrane bioreactor systems to capture fiber fragments. Alpine jacket categories with high polyester face fabric content face the steepest compliance cost escalation in Germany and Austria.
Direct-to-consumer resale platforms are capturing post-warranty garment flows that previously terminated in landfill or informal secondhand markets. Arc'teryx and REI are building proprietary authentication and repair infrastructure to defend margin capture from independent resale channels. This channel shift concentrates in urban coastal markets where sustainability preference intensity and logistics density overlap.
Outdoor Apparel and Accessories Market Segmentation
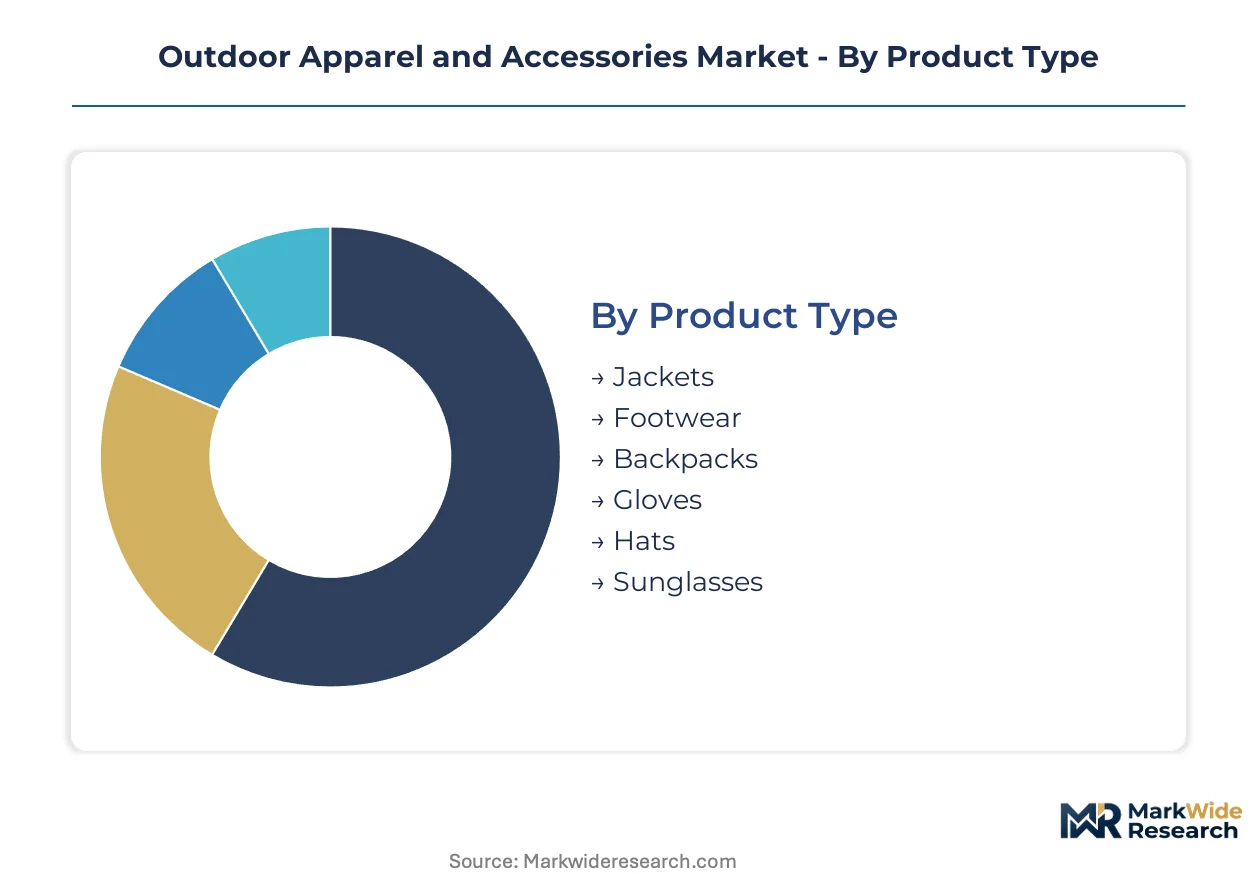
Segmentation in outdoor apparel reveals how capital deployment, technical specifications, and channel economics fragment competitive advantage across the value chain. Manufacturers must align production infrastructure with the specific performance tiers and material requirements of each segment cluster.
Product Type:
Capital intensity peaks in segments requiring lamination equipment and seam-sealing labor pools, while accessory categories run on lighter tooling investments.
- Jackets:Complex lamination and seam-sealing requirements demand heat-press calibration expertise and hydrostatic head rating certification. Demand concentrates in Germany where alpine sports culture converges with EU Green Deal chemical compliance mandates, compressing margins for non-compliant suppliers.
- Footwear:Trail running specifications are pulling technical performance requirements into daily wear categories. Urban consumers in Colorado and Germany are adopting hybrid outdoor-athletic constructions at premium price points, displacing virgin nylon in mid-layer applications.
- Backpacks:High-denier nylon with internal frame suspension systems sustains premium pricing in climbing and extended trekking segments.
- Gloves:Touchscreen-compatible membrane integration and insulated layering drive specification complexity for cold-weather end uses.
- Hats:Merino wool and synthetic blends compete on moisture management and packability metrics across hiking and trail running cohorts.
- Sunglasses:Polarized lens technology and lightweight frame materials serve high-altitude glare protection requirements.
Most installed capacity flows through Jackets. Expansion is steepest in Footwear.
End Use:
Application intensity varies sharply between intermittent recreational users and dedicated athletes requiring certified performance specifications.
- Hiking:Day-trip and multi-day trekkers demand layered systems combining waterproof-breathable shells with moisture-wicking base layers.
- Camping:Seasonal equipment purchases concentrate in spring retail windows across North American and European markets.
- Fishing:Wader construction and UV-protective apparel require specialized membrane compatibility with prolonged water immersion.
- Climbing:Technical harness integration and abrasion-resistant fabrics command the highest material specification thresholds in the category. Boulder and alpine disciplines in Germany and Colorado drive demand for four-way stretch woven constructions with bio-based elastane content.
- Trail Running:Marathon and ultra-running cohorts are adopting mechanically recycled polyester constructions that meet both performance and circularity specifications. This end use is climbing the fastest as urban consumers migrate toward hybrid outdoor-athletic use cases.
- Cycling:Aerodynamic fit systems and weather-adaptive layering distinguish road and mountain bike apparel segments.
Volume concentrates in Hiking. Technical specification intensity peaks in Climbing.
Material:
Supply chain configuration determines which material platforms can achieve scale certification under tightening chemical disclosure regimes.
- Gore-Tex:Proprietary expanded polytetrafluoroethylene membranes face reformulation pressure under EPA PFAS guidance and Maine state prohibitions.
- Fleece:Polyester knit constructions are converging with recycled content thresholds mandated by EU textile circularity requirements.
- Merino Wool:Natural fiber sourcing from Australian and New Zealand rangelands competes on odor resistance and thermoregulation metrics.
- Nylon:High-denier face fabrics in alpine jackets face steepest compliance cost escalation from ECHA microplastic release restrictions in Germany and Austria.
- Polyester:Mechanically recycled post-consumer PET bottle feedstock is displacing virgin material in mid-layer categories. Certified recycled polyester capacity is expanding across European supply chains to meet mandatory content thresholds.
- Canvas:Heavy cotton duck and waxed treatments serve heritage aesthetic segments with lower technical performance requirements.
Certification investment flows through Polyester. Reformulation urgency concentrates in Gore-Tex.
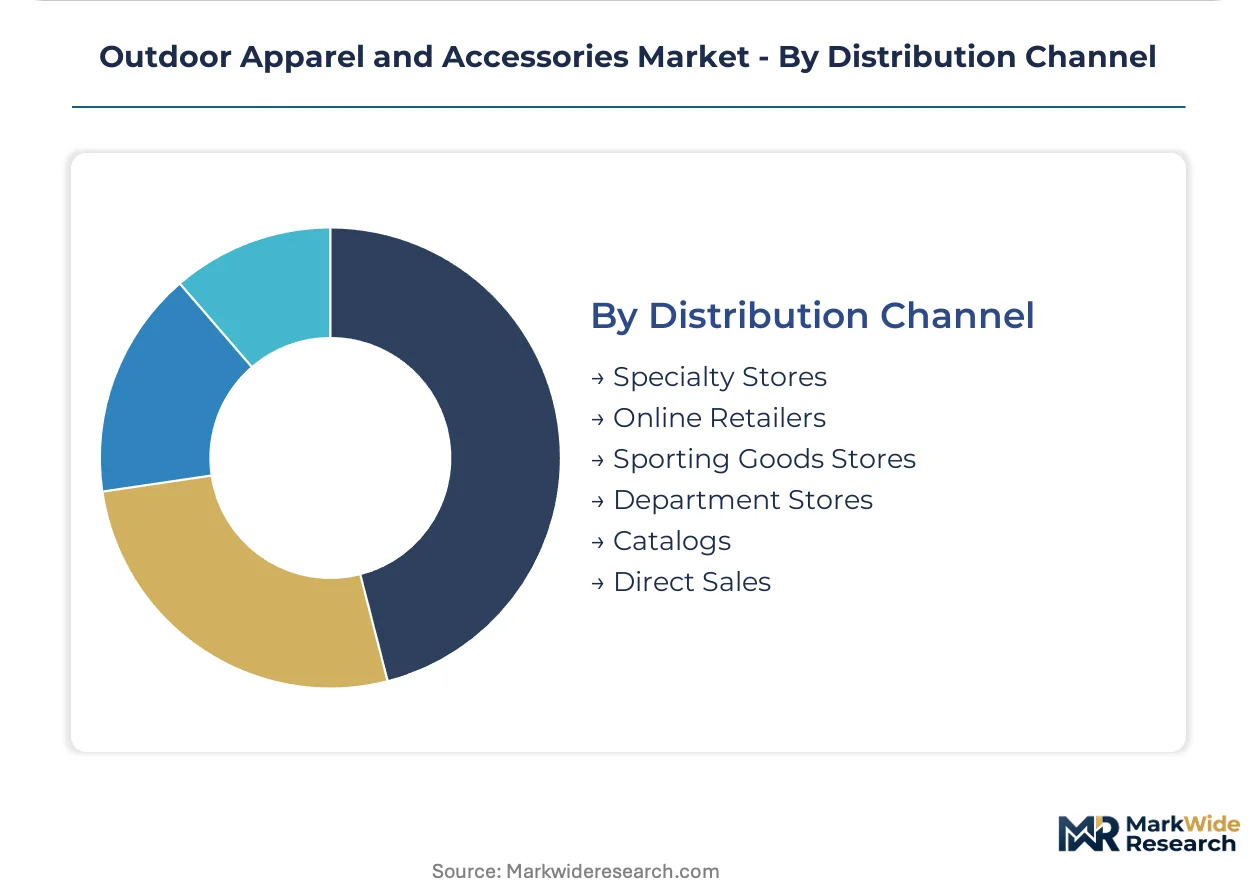
Distribution Channel:
Channel economics fragment between high-touch specialty consultation and scalable digital fulfillment infrastructure.
- Specialty Stores:Staff technical expertise and fit consultation defend margin capture in alpine equipment categories requiring sizing precision.
- Online Retailers:Return logistics complexity and authentication infrastructure requirements concentrate investment in urban coastal markets.
- Sporting Goods Stores:Seasonal inventory cycles and brand placement fees structure competitive access in mass-market performance tiers.
- Department Stores:Entry-level price positioning and reduced technical specification depth serve casual recreational users.
- Catalogs:Niche endurance sports and expedition-grade equipment maintain direct mail relevance among older demographic cohorts.
- Direct Sales:Repair and resale platforms capture post-warranty garment flows through proprietary authentication infrastructure. This channel is expanding most quickly as Arc'teryx and REI build lifetime customer value from post-consumer streams.
Transaction volume concentrates in Online Retailers. Margin recovery potential peaks in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting lamination capacity and recycled material sourcing toward regions with clearer certification pathways. Production migration follows regulatory clarity rather than labor arbitrage alone.
Germany
Alpine sports culture and EU Green Deal mandates converge in Bavaria and Baden-Württemberg. ECHA microplastic release restrictions are accelerating domestic washing machine filtration retrofits. Munich and Stuttgart host the densest clusters of bluesign-certified fabric finishing operations.
United States
Trail running adoption in Colorado and California pulls technical specifications into daily wear. EPA PFAS guidance and Maine state prohibitions are forcing DWR reformulation timelines. Seattle and Denver anchor repair and resale platform expansion for post-consumer garment recovery.
China
Guangdong and Fujian provinces concentrate seam-sealing technician pools for waterproof-breathable jacket production. Dual carbon goals are pressuring textile mills toward renewable energy procurement. Shenzhen and Dongguan house the largest certified recycled polyester weaving capacity serving European export orders.
Japan
Legacy heat-press calibration expertise for membrane lamination remains concentrated in Nagoya and Osaka manufacturing corridors. METI standards for chemical disclosure are tightening ahead of EU Digital Product Passport alignment. Domestic brands are backward integrating into bio-based polyurethane R&D.
Canada
Vancouver and Montreal serve as North American hubs for alpine equipment design and testing. Health Canada chemical regulations are tracking EPA PFAS guidance with 12-18 month lag. British Columbia's repair infrastructure supports cross-border warranty service for US market entrants.
Outdoor Apparel and Accessories Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue circular business models and rental channel penetration. The vendor base clusters around three strategic archetypes: vertically integrated material innovators, scale manufacturers with diversified Asian production bases, and specialty retailers building proprietary repair infrastructure. Competitive moves concentrate on M&A for certified recycled material capacity and strategic partnerships for bio-based membrane co-development.
Within the vertically integrated tier, Patagonia exemplifies supply chain control through captive recycled nylon sourcing, while Columbia Sportswear represents scale manufacturing across diversified production bases. Arc'teryx Equipment occupies a position defined by in-house lamination expertise. These three anchors illustrate how competitive advantage fragments across material control, manufacturing scale, and technical specialization vectors.
| Leading Market Players |
|---|
| The North Face |
| Patagonia |
| Columbia Sportswear |
| Arc'teryx Equipment |
| REI Co-op |
| Salomon |
| Black Diamond Equipment |
| Helly Hansen |
| Eddie Bauer |
| Others |
Pricing and Supply Chain Analysis
Seam-sealing technician pools concentrated in Guangdong and Fujian provinces compress labor-cost differentials between premium waterproof-breathable jackets and economy-tier alternatives. REACH chemical restrictions and PFAS prohibitions are forcing DWR reformulation investments that widen spreads between compliant and non-compliant product tiers.
Pricing Analysis
Distributor margins in the specialty retail channel absorb certification cost premiums for bluesign-approved fabric finishing. Three-tier pricing structure across premium, standard, and economy levels separates Gore-Tex-laminated alpine shells from recycled polyester mid-layers and entry-level non-laminated options. Price differentiation hinges on hydrostatic head rating certification and seam-sealing labor intensity. Cost compression in the standard tier is intensifying because recycled nylon supply volatility from ocean plastic collection networks strains margin buffers. Casual recreational users in department store channels exhibit highest price sensitivity; technical climbers and alpine athletes demonstrate lowest sensitivity due to performance-critical specifications.
Supply Chain Analysis
Single-source vulnerability sits with ocean plastic collection networks clustered in Southeast Asian coastal zones, exposing recycled nylon feedstock to monsoon season disruption. Manufacturing concentration spans China, Vietnam, and Bangladesh for cut-and-sew operations, while Japan and Canada retain legacy lamination expertise. Raw material dependencies center on petroleum-based polyurethane membranes, mechanically recycled PET bottle feedstock, and high-denier nylon face fabrics. Tariff exposure on Chinese textile imports into the US and EU carbon border adjustments threaten cost structures. Distribution runs through direct-to-consumer resale platforms, specialty outdoor retailers, and regional co-op networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal textile circularity mandates accelerate certified recycled content demand across European supply chains.
For Market Incumbents: Deploy captive recycled material sourcing to lock in certified polyester capacity ahead of mandatory content thresholds. Arc'teryx-style in-house lamination expertise defends margin capture against Asian contract manufacturers. Incumbents must secure bluesign-certified finishing partnerships in Germany and Austria before ECHA microplastic restrictions escalate compliance costs. Capacity addition in Vietnam and Bangladesh diversifies tariff exposure from China-dominant production.
For New Entrants and Emerging Players: Rental and subscription channel partners offer the most penetrable entry vector for intermittent-use alpine equipment. Trail running footwear presents white-space opportunity as urban consumers migrate technical specifications into daily wear. New entrants should pursue bio-based membrane co-development partnerships with Japanese polyurethane R&D clusters. Direct-to-consumer authentication infrastructure captures post-warranty garment flows that established brands have ceded to informal resale markets.
For Investors and Strategic Acquirers: Specialty retailers with proprietary repair infrastructure are the most active acquirer in this space, consolidating lifetime customer value from post-consumer streams. Long-term viability favors vertically integrated material innovators over pure-brand plays dependent on contract manufacturing. Acquisition target archetype: mid-tier manufacturers with legacy ERP systems ripe for Digital Product Passport compliance retrofitting. Signal to watch: OEKO-TEX approval timelines for reformulated DWR chemistries as inflection indicator for first-mover advantage realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Material Sourcing | Patagonia's ocean plastic nylon sourcing demonstrates margin control and supply resilience. |
| Bio-Based Membrane Co-Development | Castor oil and algae-derived polyurethane R&D in Japan achieves petroleum-competitive hydrostatic ratings. |
| Repair and Resale Platform Buildout | REI and Arc'teryx authentication infrastructure captures post-warranty flows from landfill diversion. |
| Bluesign Certification Investment | German and Austrian fabric finishing operations defend EU market access under tightening chemical disclosure. |
| Rental Channel Partnership Expansion | Alpine equipment co-ops address intermittent-use economics while building customer lifetime value. |
Research Methodology
Bottom-up trail running and climbing end-use modeling reconciled against top-down lamination capacity and recycled material supply tracking forms the analytical core. Primary interviews with brand sustainability officers, textile mill procurement directors, specialty retail buyers, and repair platform operators combined with secondary validation from customs trade data, bluesign and OEKO-TEX certification registries, and EU ECHA regulatory filings. Triangulation across stakeholder inputs and supply-side databases ensures segment-level precision.
Input-output matrices map hydrostatic head rating demand to certified lamination capacity across Germany, Japan, and Canada. Segmentation dimensions span product type, end-use intensity, material certification tier, and distribution channel economics. CAGRs were derived from elasticity-adjusted adoption curves across the projection horizon. Industry-specific forecast inputs include ECHA microplastic restriction implementation timelines and EPA PFAS guidance phase-out schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between EU and US chemical disclosure regimes, ocean plastic collection network disruptions, and washing machine filtration retrofit adoption rates. Forecasts reflect documented assumptions regarding recycled polyester capacity expansion and bio-based membrane technical parity achievement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.