
 Europe Second-Hand Apparel Market | 2026-2036
Europe Second-Hand Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Second-Hand Apparel Market Foresight
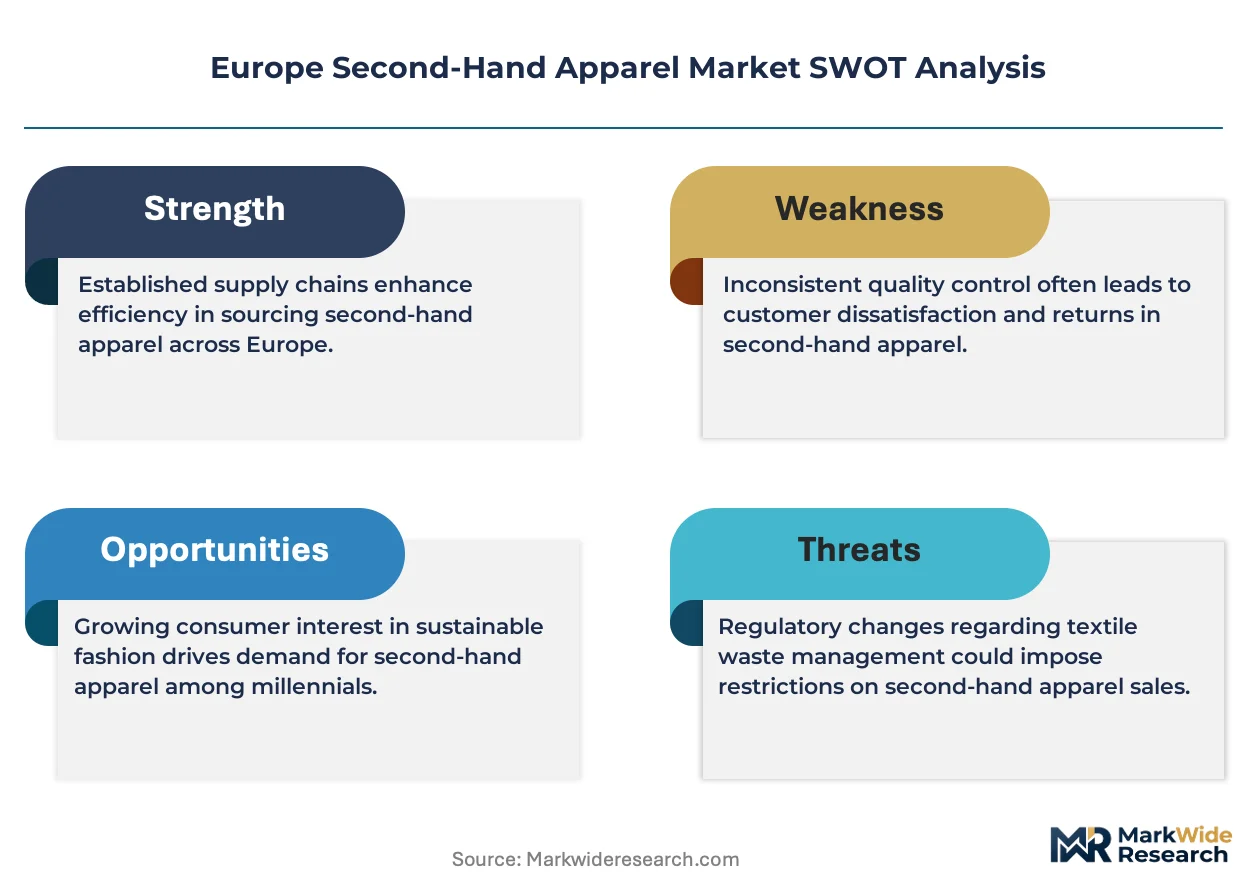
The capital-intensity divergence between peer-to-peer platforms and curated resale operators is redrawing competitive boundaries in European second-hand apparel. Vinted leverages its community-driven model to sustain low customer acquisition costs across the Baltic-to-France corridor. Vestiaire Collective differentiates through authenticated luxury positioning, anchoring premium commission structures that compete with primary retail margins.
Europe second-hand apparel encompasses pre-owned garments, footwear, and accessories reintroduced to consumption cycles through resale, rental, or donation channels, typically graded by visual condition, fabric integrity, and brand provenance before re-listing. The category serves dual commercial purposes: diverting textile waste from incineration while capturing latent value in depreciated fashion inventories. Clothing dominates transaction volume as the most liquid product type, though accessories command superior unit economics due to authentication premiums and lower return rates. Online retail channels absorb the fastest growth, displacing thrift store foot traffic as mobile-first discovery reshapes how eco-conscious shoppers source pre-owned inventory.
The EU Green Deal's textile strategy and France's AGEC law impose extended producer responsibility obligations that reshape how brands manage post-consumer garments. ECHA's REACH compliance and the EU's forthcoming digital product passports for textiles will standardize material disclosure requirements across resale platforms. Stakeholders must decide whether to build proprietary authentication infrastructure or outsource verification to specialized third parties as regulatory complexity intensifies.
Market Dynamics
EU Green Deal textile directives and France's AGEC law are forcing brands to internalize end-of-life garment costs, accelerating platform investments in authentication infrastructure and reverse logistics networks across Paris, Berlin, and Amsterdam.
Growth Catalysts
- ECHA REACH compliance:Chemical disclosure mandates for textiles entering resale channels standardize material grading protocols, reducing buyer friction in cross-border transactions.
- Gen Z purchasing concentration:Digital-native consumers in France, Germany, and the UK normalize pre-owned luxury acquisition, expanding addressable market depth for authenticated platforms.
- Reverse logistics automation:AI-powered condition assessment and pricing algorithms compress listing-to-sale timelines, improving inventory velocity for high-volume sellers.
Market Restraints
- Authentication labor costs:Manual verification of luxury goods requires trained specialists, creating margin pressure as transaction volumes scale.
- Cross-border VAT complexity:Divergent national treatment of second-hand goods within the EU fragments pricing consistency and compliance overhead.
- Synthetic fiber degradation:Polyester-dominated fast fashion inventories lose structural integrity faster than natural fibers, limiting re-listing potential.
Strategic Opportunities
- Eastern European penetration:Poland, Romania, and Czechia exhibit rising platform adoption with underdeveloped local competition, offering first-mover positioning.
- Digital product passports:EU-mandated textile traceability standards create data monetization potential through verified provenance records.
- Rental-to-resale conversion:Subscription wardrobe services generate pre-authenticated inventory streams, reducing acquisition costs for resale platforms.
Industry Challenges
- Authentication talent scarcity:Expertise in luxury brand verification concentrates in Paris and Milan, constraining platform expansion velocity.
- Legacy ERP integration:Established fashion houses operate on systems incompatible with circular inventory tracking, complicating take-back program deployment.
- Standardization delays:Absence of unified condition grading across national markets forces platforms to maintain multiple classification schemas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Second-Hand Apparel Market |
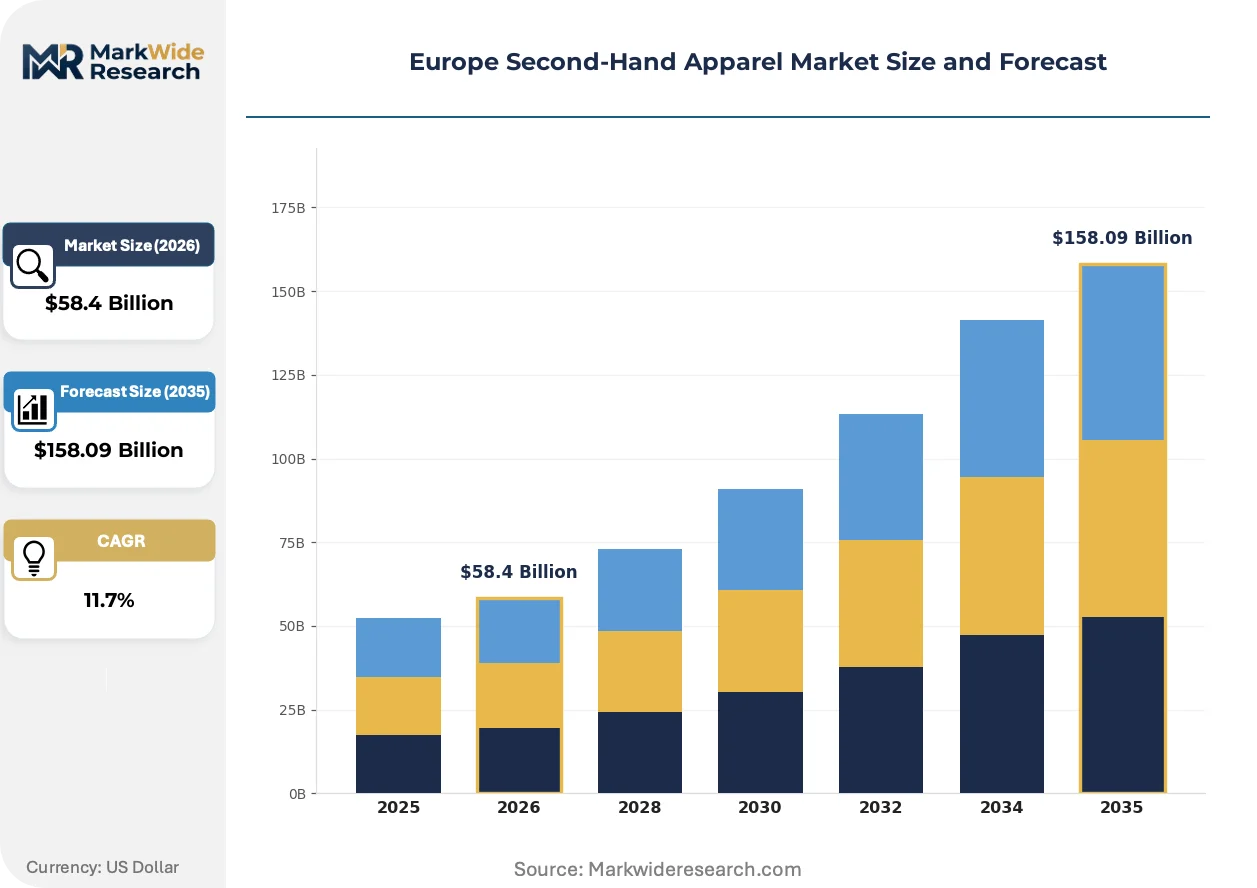
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $158.09 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Footwear, Accessories, Outerwear Sales Channel: Online Retail, Thrift Stores, Consignment Shops, Donations Customer Type: Individuals, Resellers, Vintage Collectors, Eco-conscious Shoppers Condition: Like New, Gently Used, Well-Worn, Damaged |
| Companies Covered | Depop, Zalando, Vinted, eBay, ASOS Marketplace, ThredUP, Vestiaire Collective, Poshmark, The RealReal, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Second-Hand Apparel Market Shifts & Advancements
Mobile-first discovery interfaces and AI-driven personalization engines are compressing the traditional thrift-store browsing experience into algorithmic feed formats, while regulatory pressure on textile waste forces technology investment into traceability infrastructure.
Computer vision authentication is bifurcating the resale landscape between automated mass-market grading and specialist luxury verification. Baltic-platform operators deploy smartphone-camera condition assessment for sub-premium garments, reducing per-unit inspection costs. This capability compression enables price-competitive positioning against traditional charity retail while maintaining trust thresholds.
France's AGEC law and the EU Green Deal's extended producer responsibility framework mandate brand-funded take-back infrastructure. Apparel manufacturers must now finance collection and sorting systems, redirecting capital from marketing into reverse logistics. German and French luxury houses are responding through platform partnerships that externalize compliance costs while capturing resale margin.
Consumption patterns among urban professionals in London and Amsterdam favor access-over-ownership models that blend rental and resale. Wardrobe-as-a-service subscriptions generate predictable inventory inflows, displacing sporadic closet cleanouts as the primary supply source. This shift compresses garment holding periods and accelerates circular velocity for premium outerwear categories.
Europe Second-Hand Apparel Market Segmentation
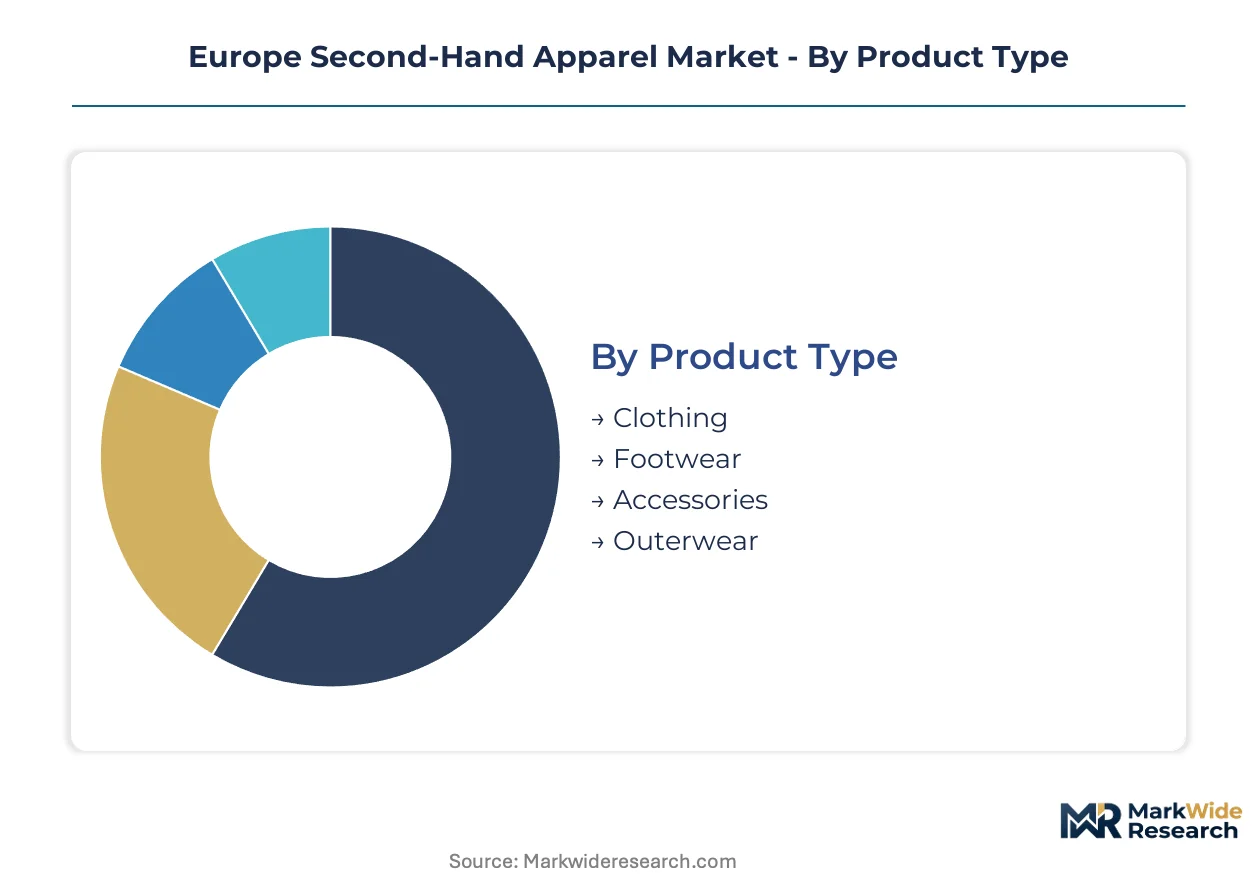
Segmentation in Europe's second-hand apparel market reveals how supply characteristics, channel economics, and buyer motivations create distinct competitive arenas. Understanding these divisions exposes where authentication investments yield returns and which customer relationships sustain platform margins.
Product Type:
Clothing dominates domestic resale flows across France and Germany, while accessories and outerwear concentrate in cross-border luxury channels originating from Paris and Milan.
- Clothing:Shirts, trousers, dresses, and knitwear constitute the highest transaction velocity segment. French and German peer-to-peer platforms process millions of monthly clothing listings. Polyester-blend fast fashion degrades faster than natural fibers, compressing re-listing windows and pressuring condition grading automation.
- Accessories:Handbags, belts, scarves, and jewelry command premium authentication fees. Paris-based specialists concentrate luxury accessory verification expertise. Lower return rates and compact shipping dimensions improve unit economics versus bulky garment categories.
- Footwear:Sneakers and leather boots circulate through dedicated resale channels with standardized sizing reducing fit-related returns. Sole condition grading drives pricing algorithms.
- Outerwear:Coats and jackets retain structural integrity across multiple ownership cycles. Higher average selling prices justify enhanced photography and detailed fabric composition disclosure under ECHA REACH requirements.
Clothing commands the established base. The steepest expansion runs through accessories.
Sales Channel:
Channel selection determines capital intensity, with online retail absorbing platform investment while physical formats persist in price-sensitive segments.
- Online Retail:Mobile-first marketplaces capture Gen Z discovery patterns across the Baltic-to-France corridor. Algorithmic feeds replace thrift-store browsing. AI-powered pricing engines compress listing-to-sale timelines for high-volume sellers.
- Thrift Stores:Charity-operated shops in UK high streets serve budget-conscious demographics. Foot traffic declines as smartphone penetration redirects discovery to digital channels.
- Consignment Shops:Curated physical locations in Amsterdam and Berlin authenticate premium inventory before listing. Commission structures mirror online luxury platforms.
- Donations:Textile banks and charity collection points supply bulk inventory to sorting facilities. France's AGEC law mandates brand-funded take-back infrastructure redirecting garments into formal resale channels.
Online retail captures volume leadership. Physical consignment retains margin concentration in authenticated luxury.
Customer Type:
Buyer sophistication varies sharply, from casual wardrobe refreshers to professional resellers operating multi-channel arbitrage.
- Individuals:Casual sellers liquidate personal wardrobes through peer-to-peer platforms. Low friction listing tools sustain supply inflows without professional photography or pricing expertise.
- Resellers:Professional operators source bulk inventory from estate sales and clearance channels. Berlin and London host concentrated communities of full-time resale entrepreneurs.
- Vintage Collectors:Niche buyers seek period-specific garments with documented provenance. Authentication demands exceed standard platform capabilities, creating specialist broker opportunities.
- Eco-conscious Shoppers:Motivation combines waste diversion with style acquisition. EU Green Deal awareness drives preference for verified circular channels over conventional retail.
Individuals provide supply liquidity. Resellers concentrate value extraction through inventory curation.
Condition:
Standardized grading protocols reduce buyer friction, though cross-platform inconsistency forces European marketplaces to maintain multiple classification schemas.
- Like New:Garments with original tags or minimal wear command prices approaching primary retail. Authentication focuses on counterfeit detection rather than degradation assessment.
- Gently Used:Visible wear without structural damage dominates transaction volume. Computer vision algorithms automate grading for this mid-tier segment.
- Well-Worn:Patina and visible aging attract vintage collectors seeking authentic character. Pricing depends on brand provenance and repair potential.
- Damaged:Stains, tears, or hardware failures limit resale to repair specialists and upcycling artisans. France's extended producer responsibility frameworks increasingly divert this stream to recycling rather than landfill.
Gently used inventory moves fastest. Like new commands price premiums in authenticated channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across European markets. French and German buyers accept authenticated luxury premiums, while Polish and Romanian consumers prioritize unit economics and low-friction peer-to-peer transactions.
France
Paris concentrates Europe's luxury authentication expertise and commands the highest commission rates for verified pre-owned goods. The AGEC law mandates brand-funded take-back infrastructure, redirecting post-consumer garments into formal resale channels. Lyon hosts specialized sorting facilities that supply curated inventory to premium platforms.
Germany
Berlin's resale entrepreneur community drives professional multi-channel arbitrage operations with sophisticated pricing algorithms. ECHA REACH compliance standardizes chemical disclosure for textiles entering resale, reducing cross-border buyer friction. Hamburg logistics clusters support automated reverse logistics networks for high-volume sellers.
United Kingdom
London professionals favor access-over-ownership models blending rental and resale for premium outerwear. Charity-operated thrift shops on UK high streets face declining foot traffic as smartphone penetration redirects discovery to digital channels. Manchester sorting centers process bulk textile donations diverted from landfill by extended producer responsibility frameworks.
Poland
Warsaw exhibits rising platform adoption with underdeveloped local competition, creating first-mover positioning for mobile-first marketplaces. Price-sensitive consumers prioritize peer-to-peer transactions over authenticated luxury channels. Krakow's logistics corridors enable cost-efficient distribution into neighboring Czech and Slovak markets.
Netherlands
Amsterdam consignment shops authenticate premium inventory before listing, mirroring online luxury platform commission structures. Dutch consumers demonstrate high eco-conscious purchasing correlation with EU Green Deal awareness. Rotterdam's port infrastructure facilitates cross-border resale logistics throughout the Baltic-to-France corridor.
Europe Second-Hand Apparel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in European second-hand apparel. The market structures around a consolidated tier of authenticated luxury specialists and a fragmented mass of peer-to-peer community platforms. Two strategic archetypes dominate: algorithmic mass-market operators leveraging computer vision for automated grading, and curated authentication specialists commanding premium commissions through verified provenance. Competitive moves concentrate on geographic expansion into Eastern European markets and proprietary authentication infrastructure investments.
Within the community-driven platform tier, Vinted and Depop exemplify low-friction peer-to-peer models that sustain customer acquisition efficiency across price-sensitive demographics. Vestiaire Collective occupies a position in the authenticated luxury tier, anchoring premium commission structures that compete with primary retail margins. These three entities represent the divergence between volume-scaled automation and expertise-intensive verification as competing paths to market position.
| Leading Market Players |
|---|
| Depop |
| Zalando |
| Vinted |
| eBay |
| ASOS Marketplace |
| ThredUP |
| Vestiaire Collective |
| Poshmark |
| The RealReal |
| Others |
Supply & Pricing Matrix
Platform scale economies in the Baltic-to-France corridor compress per-unit authentication costs while anchoring price floors for peer-to-peer transactions. France's AGEC law mandates brand-funded take-back infrastructure, redirecting capital flows from marketing into reverse logistics networks that reshape supplier economics across Paris and Lyon.
Pricing Analysis
Commission structures on authenticated luxury tiers drive lifetime value for curated resale operators. Three-tier pricing stratifies across authenticated luxury, peer-to-peer standard, and donation-channel economy levels. Authentication labor costs in Paris and Milan intensify margin pressure as transaction volumes scale. Eco-conscious shoppers in Germany and the Netherlands accept premium pricing for verified provenance, while Polish consumers prioritize unit economics.
Supply Chain Analysis
Inventory velocity in automated sorting facilities compresses lead times from collection to re-listing across Berlin and Amsterdam. Supply concentration centers on France, Germany, and the United Kingdom for curated authentication expertise. Raw material flows draw from polyester-blend fast fashion inventories, natural fiber garments, and luxury accessory streams. Single-source vulnerability in manual verification talent constrains platform expansion velocity. Distribution runs through mobile-first marketplaces displacing thrift store foot traffic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe second-hand apparel market is recovering from authentication infrastructure overbuild as EU Green Deal compliance costs stabilize. Extended producer responsibility frameworks function as the cyclical driver normalizing brand-funded reverse logistics investment.
For Market Incumbents: Compound authentication infrastructure investments in Paris and Lyon to capture AGEC law-mandated take-back flows. Deepen proprietary verification capabilities to defend against specialist third-party encroachment. Expand automated condition assessment capacity to offset manual labor cost inflation in luxury tiers.
For New Entrants and Emerging Players: Authentication-as-a-service gaps in Eastern European markets present first-mover positioning in Warsaw and Krakow. Underdeveloped local competition in Poland, Romania, and Czechia offers peer-to-peer platform penetration at lower customer acquisition cost. Target mobile-first discovery interfaces for price-sensitive demographics.
For Investors and Strategic Acquirers: Specialist authentication boutiques with established brand relationships represent consolidation targets as regulatory complexity intensifies. Long-term viability hinges on proprietary verification infrastructure rather than outsourced compliance. Watch ECHA REACH enforcement intensity as inflection indicator for platform margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Authentication Infrastructure Investment | Proprietary verification capabilities capture AGEC law-mandated take-back flows in France. |
| Reverse Logistics Automation | AI-powered condition assessment compresses listing-to-sale timelines for Berlin-based sellers. |
| Eastern European Geographic Expansion | First-mover positioning in Warsaw and Krakow exploits underdeveloped local platform competition. |
| Digital Product Passport Integration | EU-mandated textile traceability creates data monetization through verified provenance records. |
| Rental-to-Resale Channel Conversion | Subscription wardrobe services generate pre-authenticated inventory streams for Amsterdam platforms. |
Research Methodology
Initial hypotheses were tested against primary input from resale platform executives, luxury authentication specialists, reverse logistics operators, and EU regulatory affairs leads and refined through secondary validation. Primary fieldwork combined structured interviews with secondary data from ECHA REACH compliance filings, EU Green Deal textile strategy documents, French AGEC law implementation reports, and customs trade data. Bottom-up transaction volume estimates and top-down market sizing triangulated across the analysis window.
Variance decomposition separated volume growth drivers from price-mix effects across product type, sales channel, customer segment, and condition grade dimensions. CAGRs were derived from segment-level growth trajectories modeled against authentication capacity expansion, regulatory compliance cost curves, and Gen Z adoption patterns. Digital product passport implementation timelines and extended producer responsibility framework rollouts informed scenario weighting.
Forecasts assume regulatory continuity in EU Green Deal textile directives and French AGEC law enforcement; material policy shifts would require re-modeling. Synthetic fiber degradation rates and cross-border VAT harmonization progress represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
Plus Size Women's Clothing Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Vegan Footwear Market
Apparel & Footwear
Luxury Fashion Market
Apparel & Footwear
Bra Market
Apparel & Footwear
Europe Jeans Market
Apparel & Footwear
Europe Denim Jeans Market
Apparel & Footwear
Loungewear Market
Apparel & Footwear
Online Apparel Market
Apparel & Footwear
School Shoes Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Erotic Lingerie Market