
 Driving Apparel Market | 2026-2036
Driving Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Driving Apparel Market Analysis
Multi-source material procurement is hardening as a competitive requirement for premium driving apparel manufacturers. Dainese S.p.A leverages vertical integration across its Italian manufacturing base to control leather quality from tannery to finished jacket. Alpinestars sustains technology leadership in racing suits through intensive R&D investment at its Asolo headquarters. Fox Head Inc. competes aggressively in the off-road segment with specialized motocross gear that commands strong dealer loyalty in North American markets.
Driving apparel encompasses protective garments engineered for motorized vehicle operation, typically constructed from full-grain leather, aramid-reinforced textiles, or perforated synthetic blends with CE-certified armor inserts at shoulders, elbows, knees, and back. These garments must balance abrasion resistance measured in seconds of slide time against breathability metrics exceeding 5,000 g/m²/24hr for summer touring comfort. Jackets dominate product type revenue due to universal wear requirements across all rider categories, while textile materials are gaining share from leather as commuters prioritize weather adaptability over track-grade protection. The enthusiast end-user segment generates the fastest growth as recreational motorcycling participation rebounds post-pandemic, though professional racers anchor margin pools through sponsorship-driven premium pricing.
CE marking under the EU PPE Regulation mandates third-party certification for impact protectors, driving R&D investment toward modular armor systems. The U.S. Consumer Product Safety Commission maintains voluntary standards that create a regulatory gap between American and European product specifications, fragmenting design requirements for multinational manufacturers. NHTSA's motorcycle safety campaigns indirectly stimulate protective gear purchases through rider education programs. Stakeholders must monitor evolving e-mobility adoption patterns, as electric motorcycle torque characteristics may necessitate revised abrasion standards and thermal management features in future apparel designs.
Market Dynamics
CE marking requirements under the EU PPE Regulation are tightening certification standards for impact-resistant materials, forcing manufacturers to reconfigure supply chains and accelerate R&D spending on modular armor systems that balance track-grade protection with commuter breathability demands.
Growth Catalysts
- Track-day expansion:Motorsport participation is accelerating in Germany and the United States, driving demand for professional-grade racing suits with CE-certified back protectors and knee sliders.
- E-mobility torque characteristics:Electric motorcycles generate instant acceleration profiles that necessitate enhanced abrasion-resistant textiles and thermal management layers in protective garments.
- REACH compliance:Chemical safety standards are pushing manufacturers toward chrome-free tanning processes for full-grain leather used in premium jacket production.
Market Restraints
- Raw material concentration:Italian tannery clusters around the Alpine foothills control premium hide supply, creating geographic single-source risk for leather-dependent manufacturers.
- Regulatory fragmentation:NHTSA voluntary standards diverge from EU CE marking mandates, forcing dual-SKU production runs that inflate per-unit certification costs.
- Aramid fiber price volatility:Synthetic textile alternatives face input cost swings tied to petroleum feedstock markets, compressing margin stability for mid-tier apparel lines.
Strategic Opportunities
- Urban commuter penetration:Underpenetrated city rider segments in France and Spain present white space for textile jackets with integrated hydration pockets and reflective piping.
- Direct-to-rider digital channels:Brand-owned e-commerce platforms are bypassing traditional powersports dealer networks, capturing margin and first-party data on fit preferences.
- EU Green Deal alignment:Sustainability mandates are creating procurement advantages for manufacturers with certified recycled polyester supply chains and repair-service programs.
Industry Challenges
- Pattern-making talent scarcity:Specialized skills in 3D body-scanning and parametric pattern design for aerodynamic racing suits remain concentrated among Italian technical institutes.
- CE certification timelines:Third-party testing for impact protectors under PPE Regulation Category II protocols extends product development cycles by 8-14 months.
- Legacy sizing fragmentation:Inconsistent measurement standards across American and European fit systems force inventory duplication and elevated return rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driving Apparel Market |
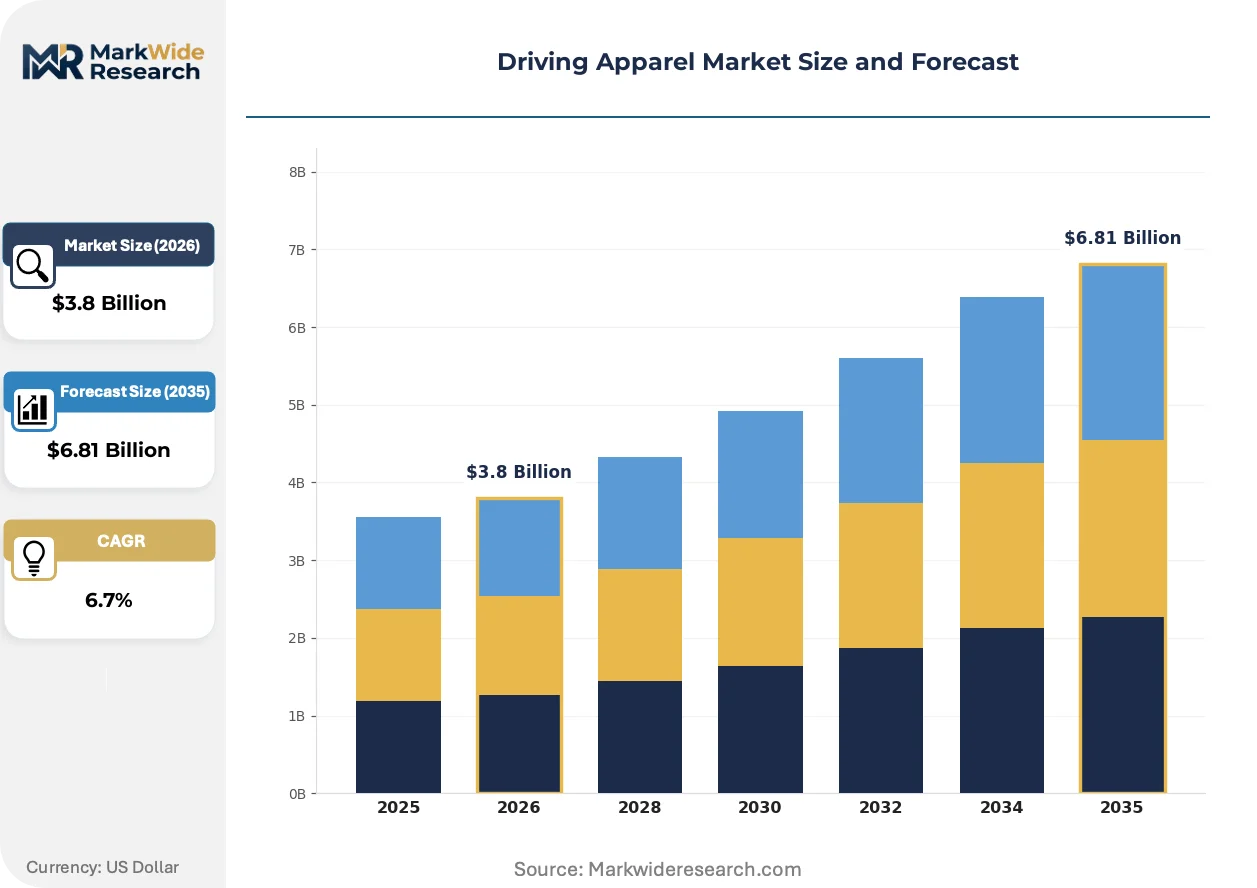
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Gloves, Pants, Footwear Material: Leather, Textile, Synthetic, Mesh End User: Racers, Commuters, Enthusiasts, Professionals Feature: Waterproof, Breathable, Lightweight, Insulated |
| Companies Covered | Dainese S.p.A, Alpinestars, Fox Head Inc., Puma SE, Adidas AG, Nike, Inc., SCOTT Sports SA, Racing Force S.p.A, Leatt Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driving Apparel Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization pressures are compressing product development timelines while elevating performance benchmarks across protection, comfort, and sustainability dimensions.
Smart armor systems incorporating D3O and SAS-TEC viscoelastic polymers are electrifying impact protection design by enabling flexible low-profile inserts that harden on impact. Track-day enthusiasts and professional racers are adopting these systems faster than commuter segments, compressing the performance gap between premium racing suits and everyday touring jackets.
EU PPE Regulation updates are mandating modular armor compatibility standards that force redesigns of existing jacket chassis. Manufacturers serving both European and North American markets face SKU proliferation as they maintain separate product lines for CE-marked and voluntarily compliant territories, with racing-focused brands absorbing the heaviest compliance burden.
Rider education programs sponsored by NHTSA and Germany's KBA are elevating certification awareness among first-time buyers. Dealer loyalty in traditional powersports channels is weakening as digitally native consumers research CE-level ratings independently, shifting purchase influence toward online review platforms and manufacturer direct channels in United States and United Kingdom markets.
Driving Apparel Market Segmentation
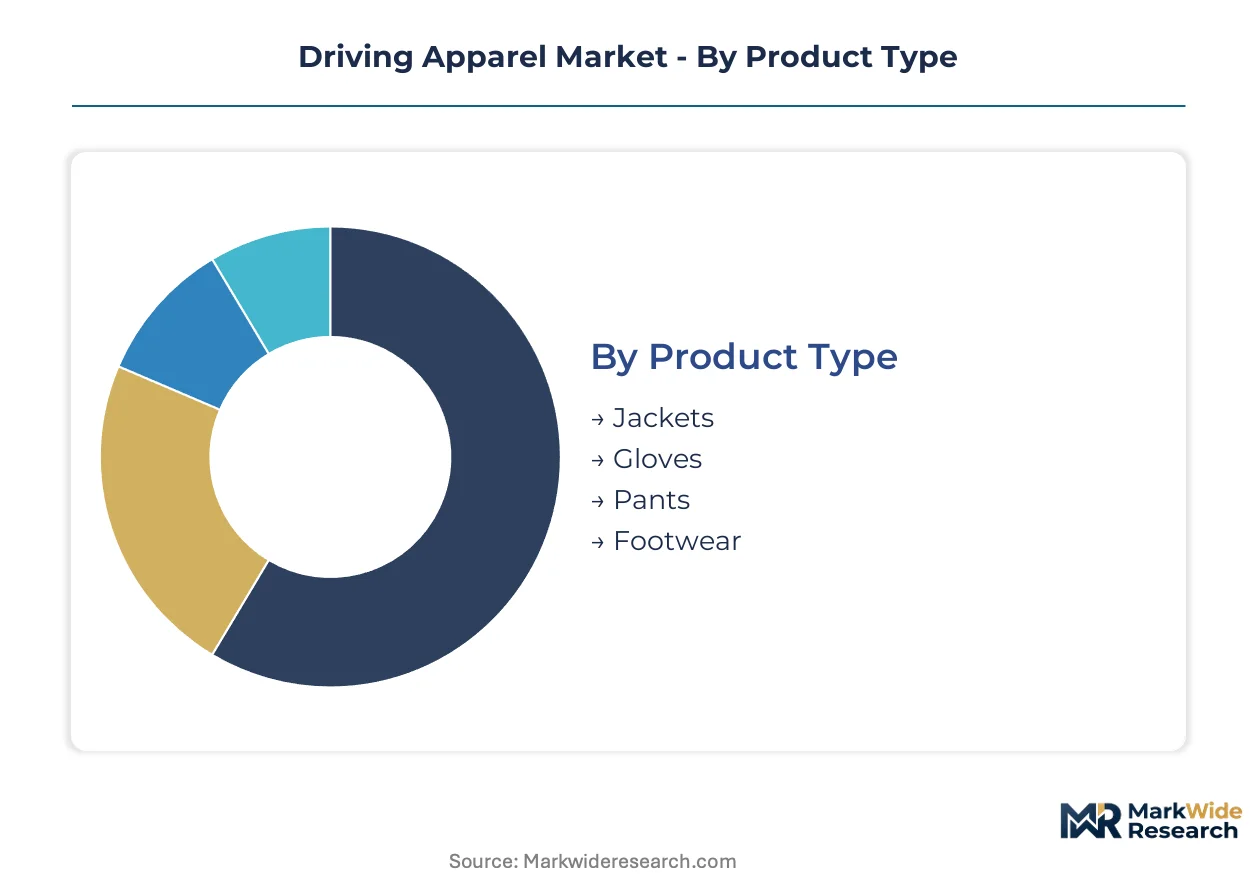
Driving apparel segmentation reflects divergent certification burdens across use cases. CE marking under EU PPE Regulation applies variably by product type and end-user risk exposure, fragmenting compliance costs and R&D allocation across manufacturer portfolios.
Product Type:
Jackets carry the heaviest certification load under CE Category II protocols, while gloves and footwear face lighter testing mandates.
- Jackets:Full-torso garments constructed from full-grain leather or aramid-reinforced textiles with CE-certified armor at shoulders, elbows, and back. Demand concentrates among German and United States track-day participants seeking abrasion resistance exceeding 4 seconds slide time.
- Gloves:Palm and knuckle protection systems utilizing kangaroo leather or synthetic overlays with viscoelastic polymer inserts. Recreational motorcyclists in Italy and Spain drive replacement cycles as crash damage necessitates frequent renewal.
- Pants:Lower-body armor integration with hip and knee protection, typically paired with jacket systems for complete coverage. Urban commuters prioritize textile variants with removable thermal liners for seasonal adaptability.
- Footwear:Ankle-height and full-height boots with reinforced toe boxes and anti-torsion soles. Off-road segments in North American markets command specialized motocross designs with buckled closure systems.
Jackets sit at the top of the volume ranking, with gloves climbing the fastest as replacement frequency outpaces other categories.
Material:
Cost tier stratification runs from premium full-grain leather through economy mesh alternatives, with certification feasibility varying by substrate.
- Leather:Full-grain hides from Italian tannery clusters deliver benchmark abrasion resistance for racing applications. REACH compliance pressures are accelerating chrome-free tanning process adoption among Alpine foothills suppliers.
- Textile:Aramid-reinforced nylon or polyester blends balancing weather adaptability against protection metrics. Commuter demand in France and Spain favors these materials for daily urban mobility.
- Synthetic:Perforated polyurethane or microfiber constructions offering lower entry pricing with modular armor compatibility. Mid-tier manufacturers leverage these substrates to hedge against raw material volatility.
- Mesh:High-ventilation open-weave designs for summer touring comfort, typically sacrificing impact protection for breathability exceeding 8,000 g/m²/24hr. Southern European markets show seasonal concentration.
Leather retains the highest margin tier, with textile materials expanding most quickly as commuter volumes displace enthusiast segments.
End User:
Application severity determines armor specification levels, from professional racing suits through casual urban riding gear.
- Racers:Professional and amateur competitors requiring FIM-homologated suits with integrated airbag systems and full-body coverage. Sponsorship-driven pricing anchors manufacturer margin pools despite low unit volumes.
- Commuters:Daily urban riders prioritizing visibility features and weather sealing over track-grade protection. This segment shows strongest post-pandemic rebound in United States metropolitan areas.
- Enthusiasts:Recreational weekend riders seeking versatile jackets adaptable to touring and occasional track use. Dealer loyalty weakens as digital research shifts purchase influence toward manufacturer direct channels.
- Professionals:Delivery riders, security personnel, and fleet operators requiring durable high-visibility gear with corporate branding integration. Fleet procurement concentrates in German logistics corridors.
Commuters dominate absolute volume, with enthusiasts gaining share fastest as recreational participation normalizes.
Feature:
Climate adaptation and comfort engineering create distinct customer preference clusters across geographic markets.
- Waterproof:Laminated membrane constructions with sealed seams and hydrostatic head ratings exceeding 10,000mm. Northern European and Pacific Northwest markets mandate this specification as baseline.
- Breathable:Moisture-vapor transmission layers managing thermal load during active riding. Summer touring segments in Mediterranean climates prioritize this attribute above impact protection.
- Lightweight:Minimized chassis mass through advanced textile selection and reduced armor profiles. Urban scooter riders in dense city centers favor maneuverability over abrasion resistance.
- Insulated:Removable thermal liners and wind-blocking outer shells for cold-weather operation. Seasonal demand spikes in Alpine regions and Nordic countries drive inventory concentration.
Waterproof specifications anchor baseline expectations, with breathable designs showing steepest expansion trajectory as climate adaptation priorities shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers face divergent compliance costs across jurisdictions, with CE marking timelines stretching product development cycles in Europe while voluntary U.S. standards permit faster market entry. This regulatory-arbitrage dynamic shapes where production capacity expands and which markets attract premium investment.
Germany
KBA-sponsored rider education programs elevate certification awareness among first-time buyers. The country's national automotive regulator maintains voluntary standards that diverge from EU mandates, creating dual-track production requirements for exporters. Manufacturing clusters around Bavaria concentrate on high-performance racing suits with integrated airbag systems.
United States
NHTSA safety campaigns indirectly stimulate protective gear purchases through education initiatives. Track-day participation accelerates in California and Texas, driving demand for professional-grade racing equipment. Domestic distribution networks in the Southeast prioritize dealer loyalty programs for off-road segments.
Italy
Alpine foothills tannery clusters control premium hide supply for full-grain leather production. REACH compliance pressures accelerate chrome-free tanning process adoption among regional suppliers. Technical institutes in Veneto concentrate specialized skills in 3D body-scanning for aerodynamic pattern design.
France
Urban commuter penetration presents white space for textile jackets with integrated hydration features. The country's national consumer safety authority enforces PPE Regulation standards for imported protective equipment. Manufacturing activity concentrates in Auvergne-Rhône-Alpes for weather-adaptable touring gear.
Spain
Recreational motorcyclists drive replacement cycles for crash-damaged gloves and accessories. Mediterranean climate conditions prioritize breathable designs with moisture-vapor transmission layers. Industrial activity clusters around Catalonia for summer touring equipment with high-ventilation specifications.
Driving Apparel Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent lifestyle apparel crossover opportunities. The vendor base stratifies across three performance tiers based on certification depth and material sourcing control. Premium-tier specialists concentrate in Italian manufacturing clusters, while scale-driven competitors optimize synthetic textile supply chains. Strategic moves center on direct-to-rider digital channel expansion and sustainability certification alignment with EU Green Deal procurement preferences.
Within the premium-tier specialist archetype, Dainese S.p.A and Alpinestars occupy positions anchored by Italian manufacturing heritage and racing pedigree. Among diversified sportswear conglomerates, Puma SE and Adidas AG exemplify lifestyle crossover strategies that leverage brand recognition beyond core motorsport channels. Fox Head Inc. represents the off-road specialization archetype, with positioning tied to North American dealer network density. These named entities collectively illustrate how competitive positioning stratifies across certification depth, geographic manufacturing concentration, and end-user segment focus.
| Leading Market Players |
|---|
| Dainese S.p.A |
| Alpinestars |
| Fox Head Inc. |
| Puma SE |
| Adidas AG |
| Nike, Inc. |
| SCOTT Sports SA |
| Racing Force S.p.A |
| Leatt Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between CE-marked European specifications and voluntary U.S. standards manifests in parallel pricing ladders and dual-source supply configurations that inflate per-unit costs for multinational manufacturers serving both jurisdictions. Italian tannery clusters command premium positioning for full-grain leather while synthetic textile alternatives compete on cost stability against petroleum-linked aramid fiber volatility.
Pricing Analysis
Distributor margins of 35-45 percent in traditional powersports channels compress to 15-20 percent for direct-to-rider digital sales, with pricing stratifying across premium racing suits, standard touring jackets, and economy commuter gear based on armor certification level and brand heritage. Cost compression in mid-tier synthetic lines is intensifying because aramid fiber price volatility erodes margin stability, while professional racers show least price sensitivity due to sponsorship-driven procurement and urban commuters exhibit highest elasticity as discretionary safety spending.
Supply Chain Analysis
Full-grain leather supply rests on Italian Alpine foothills tannery clusters, aramid fiber production centers on U.S. and Japanese specialty chemical producers, and finished garment assembly concentrates in Romania and Tunisia for European market access. Critical dependencies span kangaroo leather for racing gloves, D3O viscoelastic polymers for smart armor systems, and REACH-compliant chrome-free tanning agents. Single-source vulnerability in Italian hide supply creates geographic concentration risk. Distribution runs through manufacturer-owned flagships, powersports dealer networks, and pure-play e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Driving apparel has entered late-cycle quality competition where recreational enthusiasts are trading up to CE-certified modular armor systems, rewarding manufacturers with certification depth and Italian manufacturing heritage.
For Market Incumbents: Anchor racing pedigree through FIM-homologated airbag suit development at Italian technical institutes while tightening captive supply of full-grain leather from Alpine foothills tanneries to defend against synthetic textile disruptors eroding premium positioning. For New Entrants and Emerging Players: Urban scooter riders in French and Spanish metropolitan areas represent an underserved buyer archetype with minimal incumbent loyalty, penetrable through textile jackets with integrated hydration and reflective safety features sold via direct-to-rider digital channels bypassing dealer markup. For Investors and Strategic Acquirers: Consolidation pressure builds where CE certification timelines stretch 8-14 months and pattern-making talent concentrates among Veneto technical institutes, favoring acquisition of mid-cap specialists with modular armor IP and established Notified Body relationships as the signal to watch for inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Certification Acceleration | Notified Body partnerships in Italy and Germany compress 14-month testing timelines for Category II PPE protocols. |
| Chrome-Free Tanning Transition | REACH-compliant tannery investments in Alpine foothills secure premium leather supply for racing applications. |
| Direct-to-Rider Digital Launch | Manufacturer-owned e-commerce in United States and United Kingdom captures first-party fit data and margin expansion. |
| Smart Armor R&D Partnership | D3O and SAS-TEC polymer integration enables flexible protection systems hardening on impact for track-day segments. |
| Urban Commuter Product Line | Textile jackets with removable thermal liners penetrate underpenetrated French and Spanish city rider markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with product development directors at Italian racing apparel specialists, procurement leads at North American powersports distributors, regulatory affairs managers navigating CE marking protocols, and technical directors at tannery clusters with secondary validation against EU PPE Regulation filings, REACH compliance databases, NHTSA safety campaign disclosures, and customs trade records for leather and synthetic textile inputs. Bottom-up SKU-level demand modeling and top-down category spend analysis provided cross-verification.
Historical reference periods anchored volume and value trajectories across the modeling period, with segmentation dimensions spanning product type, material substrate, end-user application severity, and feature specification. CAGRs were derived from fitted growth curves applied to certification-driven replacement cycles and post-pandemic recreational participation normalization. Industry-specific forecast inputs incorporated electric motorcycle torque characteristic impacts on abrasion standards and thermal management requirements.
Inputs from Notified Body certification databases and tannery cluster production records were available through the study window; gaps in real-time track-day participation metrics and electric motorcycle adoption curves introduce uncertainty bands. Forecasts reflect documented assumptions regarding regulatory harmonization pressures and raw material price stability. A small set of triggers—CE marking timeline extensions, aramid fiber supply disruptions, and e-mobility standard revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Global Sleepwear and Loungewear Market
Apparel & Footwear
Global Shirt Market
Apparel & Footwear
Football Kits Market
Apparel & Footwear
Athletic and Sports Socks Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Asia Pacific Swimwear Market
Apparel & Footwear
Sailing Jackets Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
Sequins Apparels Market
Apparel & Footwear
Outdoor Apparel Market
Apparel & Footwear
Menswear Market
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Global Adaptive Clothing Market