
 Network Bandwidth Management Software Market | 2026-2036
Network Bandwidth Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Network Bandwidth Management Software Market Foresight
Enterprise IT departments are bifurcating from service providers as the dominant procurement channel for bandwidth management platforms. Cisco Systems Inc. leverages its installed base of routing hardware to bundle software controllers that anchor recurring revenue streams. NetScout Systems Inc. specializes in deep packet inspection for performance monitoring, occupying a defensible niche in financial services verticals.
Network bandwidth management software governs data flow across enterprise and carrier infrastructure through traffic classification, queuing algorithms, and policy enforcement engines operating at Layer 3 through Layer 7 of the OSI model. These systems prioritize latency-sensitive VoIP and video streaming packets while throttling bulk transfers to prevent congestion collapse. Cloud-based deployment is displacing on-premises appliances as organizations seek elastic capacity for web conferencing spikes, though hybrid architectures persist in regulated sectors where data sovereignty mandates local packet processing. Traffic shaping solutions command premium pricing relative to bandwidth provisioning tools because they embed machine learning models that adapt policies to real-time application signatures.
The FCC in the United States enforces net neutrality principles that constrain how service providers throttle consumer traffic, creating compliance demand for audit-ready policy logging. The EU AI Act and GDPR jointly require algorithmic transparency in automated network decisions, pushing vendors to document how their optimization engines classify user behavior. Stakeholders must weigh sovereign cloud mandates against the operational simplicity of centralized SaaS consoles as regulatory fragmentation deepens across jurisdictions.
Market Dynamics
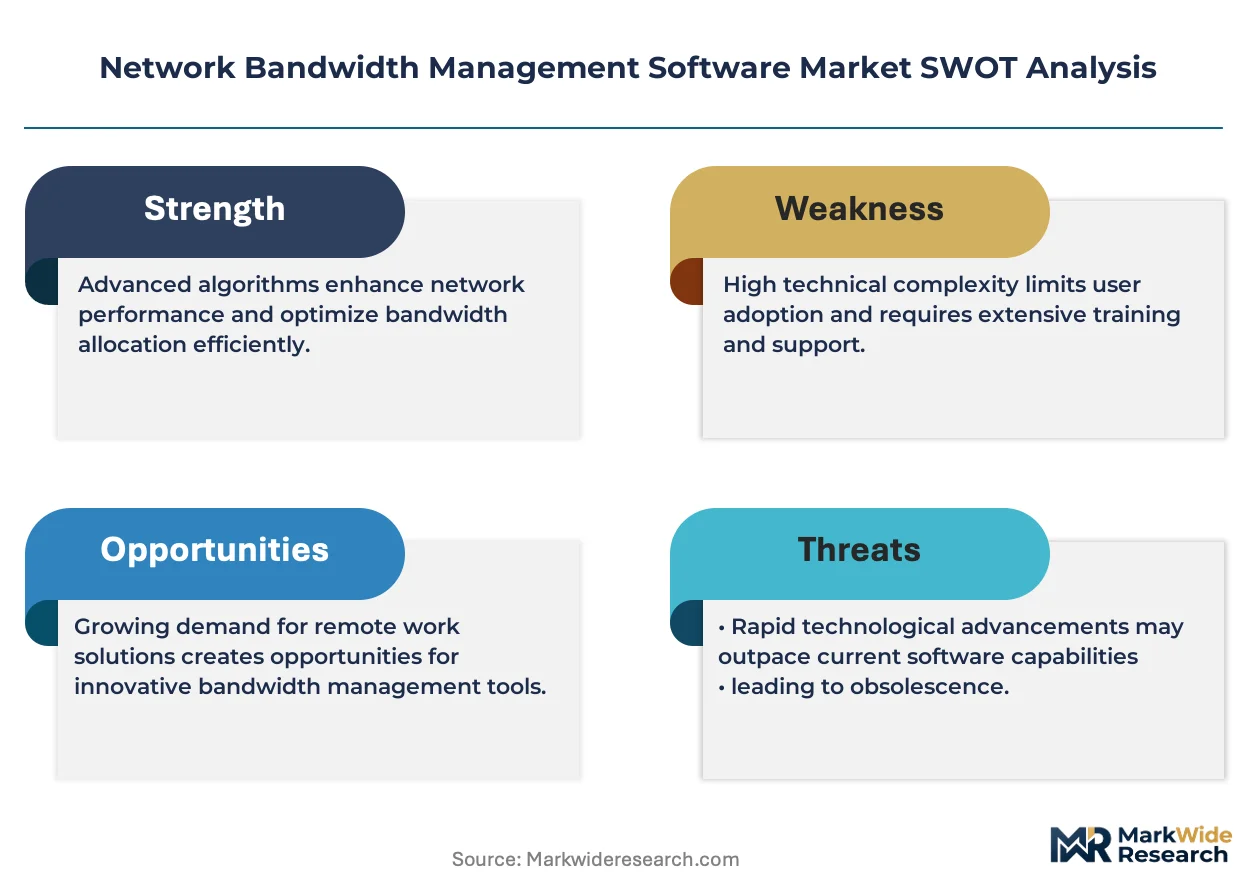
Hybrid work architectures are forcing enterprise IT departments to rebuild traffic engineering from premises-centric to edge-distributed models, compressing procurement cycles and favoring cloud-native controllers over hardware appliances.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated network decisions now require documented classification logic, compelling enterprises to upgrade legacy monitoring stacks.
- 5G backhaul infrastructure buildouts in India:Tower operators are deploying intelligent traffic shaping to manage massive IoT sensor backhaul across smart city deployments.
- Encrypted traffic visibility solutions:Financial services institutions in Germany are procuring deep packet inspection tools to maintain performance monitoring without breaking TLS 1.3 encryption.
Market Restraints
- Semiconductor supply concentration in Taiwan:Custom ASICs for high-throughput packet processing face 18-24 month lead times, constraining appliance vendor output.
- FCC net neutrality audit requirements:Service providers must maintain granular policy logs for consumer traffic throttling, adding operational overhead without revenue recovery.
- Open-source traffic control alternatives:Linux TC and eBPF frameworks are displacing commercial solutions in cloud-native environments, compressing pricing power.
Strategic Opportunities
- Sovereign cloud mandates in France:ANSSI certification requirements for critical infrastructure operators are creating demand for on-premises packet processing that cannot migrate to US-hosted SaaS.
- Convergence of zero trust and traffic shaping:Security vendors are bundling microsegmentation with bandwidth management, opening cross-sell channels into enterprise security budgets.
- Edge computing deployments in manufacturing:German automotive plants are installing local traffic controllers to prioritize robotic control traffic over administrative data.
Industry Challenges
- eBPF and kernel-level programming expertise:Vendors struggle to hire engineers capable of optimizing packet processing pipelines in modern Linux kernels.
- Integration with legacy MPLS networks:Enterprises running hybrid WAN architectures face configuration complexity when bridging SD-WAN controllers with existing provider VPNs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Bandwidth Management Software Market |
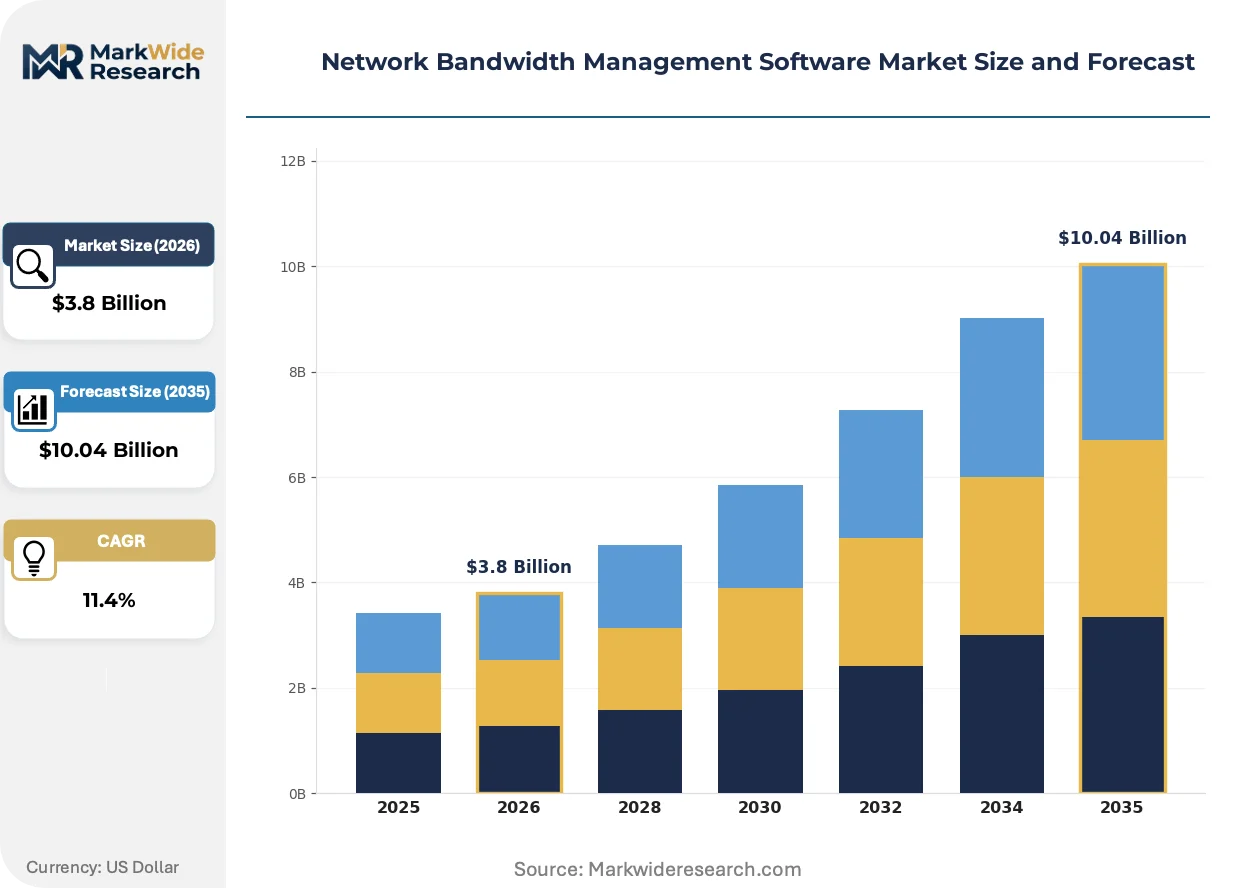
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Enterprises, Service Providers, Educational Institutions, Government Solution: Traffic Shaping, Performance Monitoring, Network Optimization, Bandwidth Provisioning Application: VoIP, Video Streaming, Online Gaming, Web Conferencing |
| Companies Covered | NetScout Systems Inc., Hewlett Packard Enterprise Company, Cisco Systems Inc., ManageEngine, Juniper Networks Inc., SolarWinds Corporation, Broadcom Inc., Auvik Networks Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Bandwidth Management Software Market Shifts & Advancements
Traffic management architectures are fragmenting from monolithic appliances into disaggregated software layers, enabling independent scaling of control plane intelligence and data plane throughput.
Kernel-bypass networking using DPDK and SmartNIC offloads is decomposing traditional appliance form factors. Cloud providers are adopting these frameworks to achieve 100Gbps+ per-server throughput without host CPU saturation. This decomposition is collapsing the premium pricing tier for hardware-centric vendors as software-defined data planes commoditize raw forwarding performance.
The EU AI Act's risk classification framework for automated decision systems is forcing vendors to expose their machine learning model training data and feature engineering pipelines. Network optimization vendors must now document how their algorithms classify application traffic to avoid high-risk system designation. Financial services operators in Frankfurt and London are demanding this transparency as a procurement prerequisite.
Enterprise buyers are unbundling traffic shaping from broader SD-WAN contracts, creating standalone procurement categories for specialized performance monitoring. Channel partners are responding with pure-play software resale arrangements that displace bundled hardware maintenance agreements. This pattern is most pronounced in United States healthcare systems where separate capital budgets fund network infrastructure and clinical application optimization.
Network Bandwidth Management Software Market Segmentation
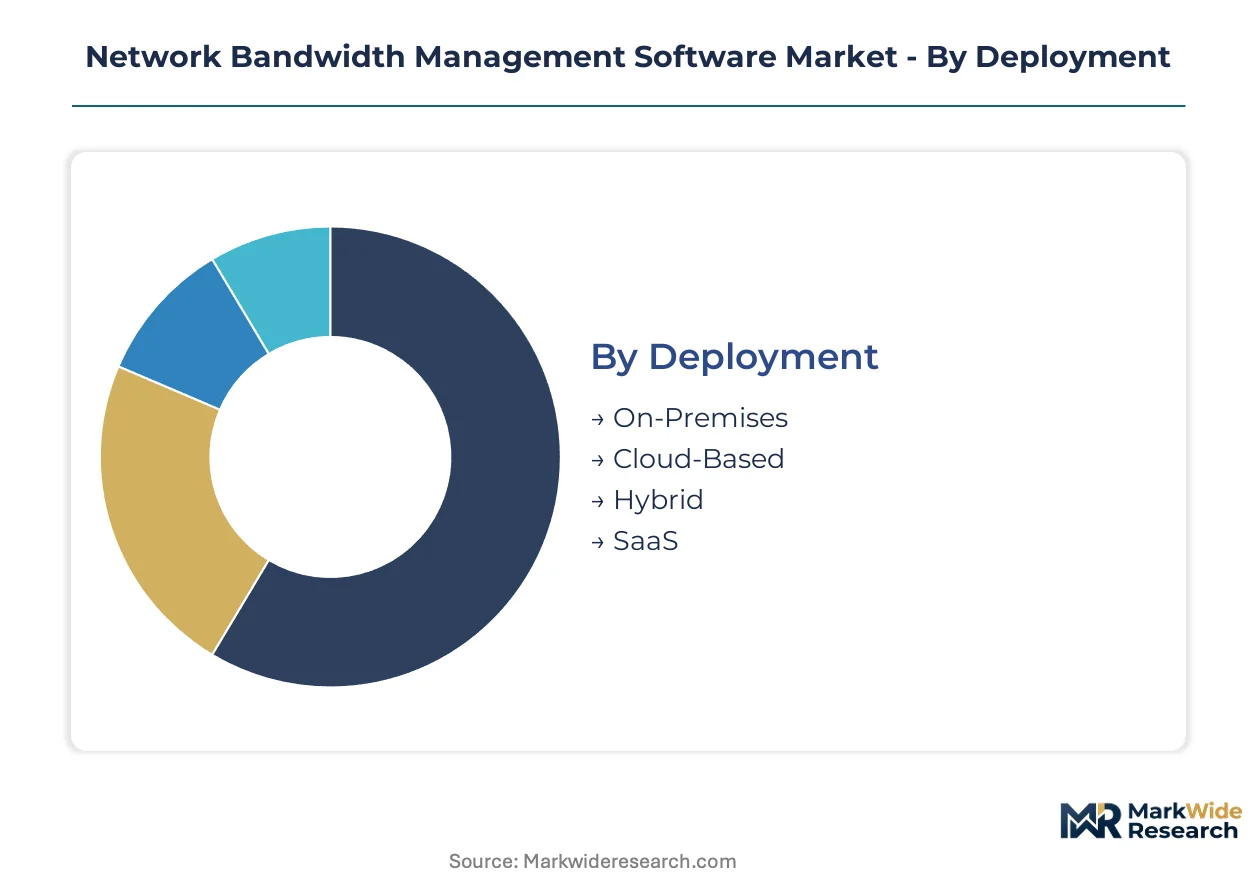
Network bandwidth management software segments diverge sharply by infrastructure ownership and traffic sovereignty requirements. Procurement patterns split between organizations demanding local packet processing for compliance and those prioritizing elastic cloud capacity for distributed workforces.
Deployment:
Domestic data center operators in Germany and France favor on-premises and hybrid models to satisfy ANSSI and GDPR localization mandates, while Indian SaaS adopters and US cloud-native enterprises drive export-led demand for fully managed services.
- On-Premises:Hardware appliances process packets within enterprise or carrier facilities, satisfying data sovereignty requirements in regulated European markets. German financial institutions in Frankfurt deploy these systems to maintain GDPR-compliant traffic inspection without cross-border data flows.
- Cloud-Based:Centralized controllers scale capacity elastically through hyperscaler infrastructure. US healthcare systems and Indian IT services firms adopt these deployments to handle unpredictable web conferencing spikes without capital expenditure.
- Hybrid:Split architectures route sensitive traffic through local appliances while offloading bulk transfers to cloud controllers. French critical infrastructure operators use this model to balance ANSSI certification requirements with operational flexibility.
- SaaS:Fully managed subscriptions eliminate infrastructure ownership, appealing to mid-market enterprises lacking specialized engineering staff. Indian SMEs and US regional hospital networks represent concentrated procurement channels.
On-Premises commands the established base. The steepest expansion runs through Cloud-Based deployment as sovereign cloud exceptions narrow.
End User:
Cost tier segmentation separates capital-rich service providers from budget-constrained educational institutions, with enterprises occupying the mid-tier procurement band where security and performance requirements justify premium pricing.
- Enterprises:IT departments procure standalone traffic shaping and monitoring tools as hybrid work architectures displace bundled SD-WAN contracts. US healthcare systems maintain separate capital budgets for clinical application optimization.
- Service Providers:Carriers deploy intelligent traffic shaping across 5G backhaul and fiber infrastructure to manage consumer and enterprise service tiers. Indian tower operators prioritize these investments for smart city IoT sensor networks.
- Educational Institutions:Universities manage residential network congestion during peak usage periods with limited operational budgets. Campus IT departments favor open-source alternatives where commercial support costs prove prohibitive.
- Government:Agencies mandate encrypted traffic visibility without compromising classified communications, driving specialized procurement in defense and intelligence sectors. German federal and state authorities enforce strict data localization.
Enterprises anchor current revenue concentration. Government verticals are climbing the fastest as sovereign cloud mandates harden.
Solution:
Application maturity varies from commoditized bandwidth provisioning to machine learning-enhanced traffic shaping that commands substantial pricing premiums.
- Traffic Shaping:Adaptive algorithms prioritize latency-sensitive packets while throttling bulk transfers, embedding ML models that classify application signatures in real time. EU AI Act transparency requirements now force vendors to document classification logic for German financial services buyers.
- Performance Monitoring:Deep packet inspection tools maintain visibility into encrypted TLS 1.3 streams without decryption, occupying a defensible niche in Frankfurt and London banking centers.
- Network Optimization:Path selection and congestion avoidance engines improve throughput across hybrid WAN architectures. These solutions face pricing pressure from open-source alternatives in cloud-native environments.
- Bandwidth Provisioning:Capacity allocation tools reserve network resources for guaranteed service levels, functioning as table-stakes infrastructure without differentiation.
Traffic Shaping holds the premium tier. Performance Monitoring is gaining share fastest as encryption mandates spread.
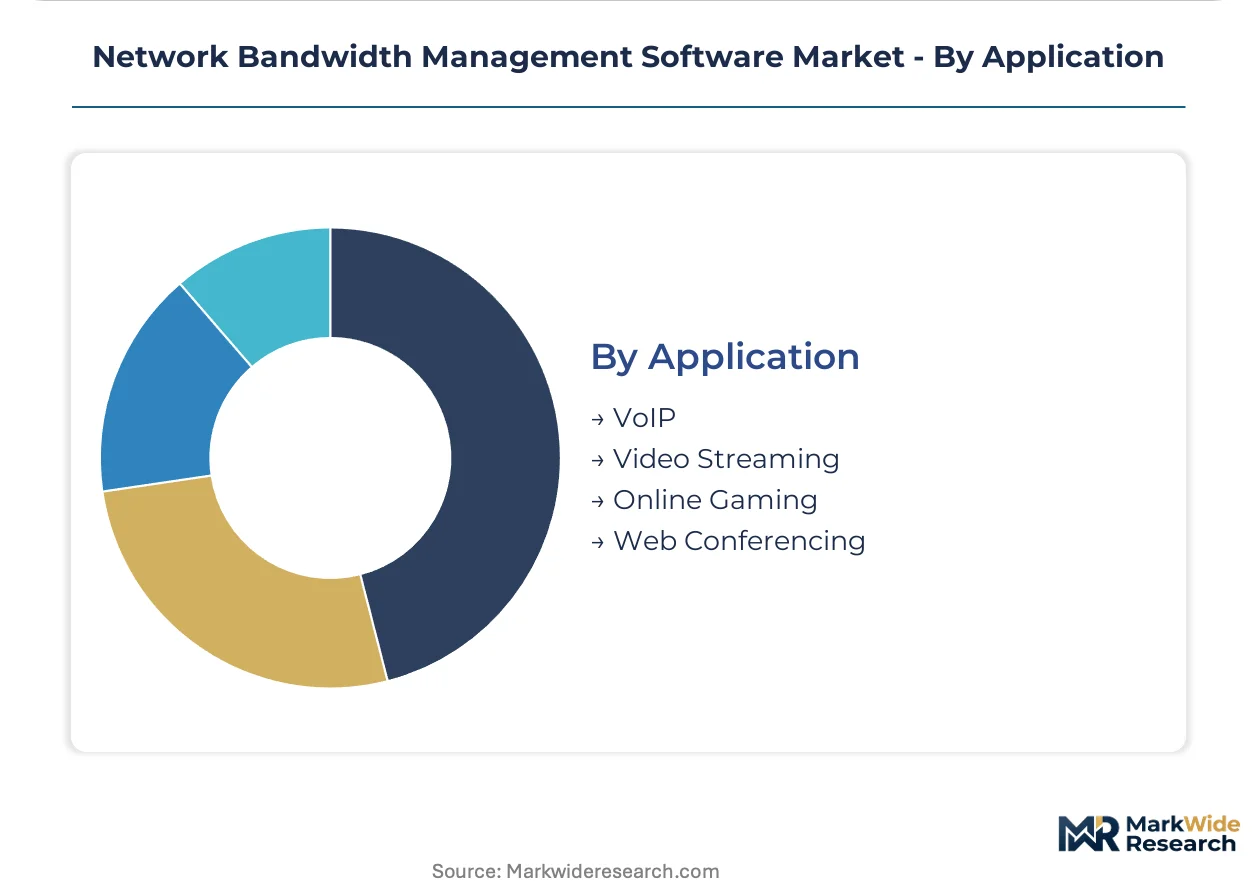
Application:
Volume concentration tracks the shift from premises-centric voice systems to distributed video collaboration and interactive entertainment.
- VoIP:Legacy voice traffic requires consistent sub-150ms latency with minimal jitter, now table-stakes for enterprise communications. These implementations face gradual displacement as unified platforms absorb standalone voice infrastructure.
- Video Streaming:Adaptive bitrate delivery demands dynamic bandwidth allocation across consumer and enterprise contexts. Indian smart city deployments and US remote work architectures drive concentrated procurement.
- Online Gaming:Ultra-low latency requirements below 50ms distinguish this segment from general entertainment traffic. Korean and Japanese markets show particular intensity for edge-optimized routing.
- Web Conferencing:Synchronous video collaboration creates unpredictable bandwidth spikes that strain traditional provisioning models. Hybrid work persistence sustains this as the primary growth vector.
VoIP represents the mature installed base. Web Conferencing shows the steepest expansion trajectory as distributed work architectures normalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IT departments in the United States, Germany, and India concentrate procurement of traffic shaping and performance monitoring platforms. Sovereign cloud mandates and 5G infrastructure buildouts are reshaping deployment patterns across these markets.
United States
Healthcare systems and financial institutions in New York and Chicago drive demand for encrypted traffic visibility solutions. The FCC enforces net neutrality audit requirements that compel service providers to maintain granular policy logs. Silicon Valley cloud providers deploy kernel-bypass networking frameworks to achieve 100Gbps throughput without host CPU saturation.
Germany
Frankfurt banking centers procure deep packet inspection tools to maintain performance monitoring without breaking TLS 1.3 encryption. The EU AI Act and GDPR jointly require algorithmic transparency in automated network decisions. Bavarian automotive plants install local traffic controllers to prioritize robotic control traffic over administrative data flows.
India
Tower operators deploy intelligent traffic shaping to manage massive IoT sensor backhaul across smart city deployments in Mumbai and Bangalore. TRAI regulations govern quality-of-service standards for broadband providers. Karnataka-based IT services firms adopt cloud-based deployments to handle unpredictable web conferencing spikes.
France
Critical infrastructure operators in Paris seek ANSSI-certified on-premises packet processing that cannot migrate to US-hosted SaaS. The EU AI Act risk classification framework forces vendors to expose machine learning model training data. Île-de-France healthcare networks maintain separate capital budgets for clinical application optimization.
United Kingdom
London financial services operators demand transparency in algorithmic traffic classification as a procurement prerequisite. GDPR compliance requirements accelerate investment in encrypted traffic visibility. Thames Valley technology clusters favor hybrid architectures that route sensitive traffic through local appliances while offloading bulk transfers to cloud controllers.
Network Bandwidth Management Software Market Competitive Landscape
Player mix skews toward network infrastructure incumbents with installed hardware bases and specialized performance monitoring vendors. The competitive structure concentrates around two dominant archetypes: routing equipment manufacturers bundling software controllers and pure-play visibility specialists occupying vertical niches. Strategic moves center on unbundling traffic shaping from broader SD-WAN contracts and converging zero trust security with bandwidth management capabilities.
Within the infrastructure incumbent tier, Cisco Systems Inc. and Juniper Networks Inc. exemplify players leveraging routing hardware installed bases to anchor recurring software revenue. NetScout Systems Inc. occupies a defensible specialist position in deep packet inspection for financial services verticals. These three companies represent the core competitive anchors around which channel partners and pure-play software vendors position alternative procurement arrangements.
| Leading Market Players |
|---|
| NetScout Systems Inc. |
| Hewlett Packard Enterprise Company |
| Cisco Systems Inc. |
| ManageEngine |
| Juniper Networks Inc. |
| SolarWinds Corporation |
| Broadcom Inc. |
| Auvik Networks Inc. |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Long-term SaaS subscription contracts with annual indexation clauses lock in recurring revenue visibility for vendors while securing capacity commitments from hyperscaler infrastructure partners. This contract structure concentrates pricing power with established platforms that can bundle traffic shaping with adjacent security modules, compressing margins for pure-play entrants lacking installed-base leverage.
Pricing Analysis
Cost-plus contracts with CPI indexation anchor enterprise procurement of bandwidth management platforms, particularly in German financial services and US healthcare verticals. Three-tier pricing structure across premium ML-enhanced shaping, standard policy engines, and economy monitoring tiers differentiates by algorithmic sophistication and GDPR compliance certification. Pricing pressure stems from open-source eBPF alternatives displacing commercial solutions in cloud-native environments. Educational institutions exhibit highest price sensitivity, while government agencies accept premium tiers for ANSSI-certified local processing.
Supply Chain Analysis
TSMC fabrication capacity for SmartNIC ASICs constitutes a chokepoint constraining high-throughput appliance output across the vendor base. Semiconductor supply concentrates in Taiwan and South Korea, with final assembly anchored in China and Mexico. Custom packet-processing silicon, DPDK-optimized NICs, and TLS 1.3 inspection hardware represent critical input dependencies. Single-source vulnerability in advanced node fabrication exposes vendors to 18-24 month lead time volatility. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and specialized channel partners serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
eBPF kernel programming expertise scarcity constrains vendor R&D velocity and opens acquisition opportunities for firms with captive engineering depth. The gap between cloud-native optimization requirements and legacy appliance skill bases widens competitive moats for specialized talent holders.
For Market Incumbents: Consolidate around zero-traffic-shaping convergence by acquiring microsegmentation specialists with existing enterprise security budgets. Defend installed-base revenue through backward integration into SmartNIC hardware design, reducing TSMC dependency. Channel control investments in ANSSI-certified French deployment partners lock out SaaS-native competitors from critical infrastructure procurement. For New Entrants and Emerging Players: Differentiate on EU AI Act algorithmic transparency documentation as a procurement wedge into Frankfurt and London financial services. Target Indian smart city 5G backhaul deployments where tower operators prioritize IoT traffic shaping over legacy enterprise feature depth. A channel-native go-to-market through hyperscaler marketplaces bypasses entrenched direct sales organizations. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive eBPF engineering teams and existing ANSSI or FedRAMP certification pathways. Long-term viability hinges on regulatory compliance automation capabilities rather than raw throughput performance. Watch for inflection signals in sovereign cloud mandate enforcement intensity across EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of eBPF Specialist Firm | Kernel-level programming talent scarcity in DPDK optimization pipelines constrains incumbent R&D velocity. |
| ANSSI Certification Investment | French critical infrastructure operators mandate on-premises packet processing without US-hosted SaaS migration. |
| Zero Trust Platform Integration | Security budget access opens cross-sell channels beyond traditional network infrastructure procurement cycles. |
| SmartNIC Hardware Backward Integration | TSMC lead time volatility in advanced node fabrication threatens appliance vendor output commitments. |
| Geographic Expansion into Indian 5G | TRAI quality-of-service standards and smart city IoT deployments concentrate tower operator demand. |
Research Methodology
A spread of perspectives from enterprise IT directors, carrier network architects, channel sales executives, and regulatory compliance officers converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory impact assessments, and TRAI enforcement records. Bottom-up deployment model sizing triangulated against top-down IT spending elasticity estimates.
Segmentation dimensions modeled span deployment architecture, end-user vertical, solution capability tier, and application traffic type across the analysis window. CAGRs derive from fitted growth curves anchored to observable procurement cycle compression in hybrid work transitions and sovereign cloud mandate enforcement. Forecast inputs incorporate 5G backhaul buildout schedules, EU AI Act implementation timelines, and eBPF adoption diffusion rates in cloud-native environments.
Material uncertainties — semiconductor supply disruption, open-source displacement acceleration, and regulatory fragmentation across jurisdictions — sit outside the modeled envelope. Forecasts reflect documented assumptions about vendor pricing power retention and enterprise procurement centralization trends. Practitioners should keep alternative scenarios live as ANSSI certification expansion and FCC net neutrality enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Nosql Database Market
Software & Services
Global App Builder Software Market
Software & Services
Custom Software Development Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
HR Saas Market
Software & Services
Board Portal Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Collaborative Office Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Stock Control Software Market
Software & Services
Global Permit Management Software Market
Software & Services
Mobile Application Development Market
Software & Services
Automotive Operating Systems Market
Software & Services
Global Meeting Room Booking System Software Market