
 Switzerland Haircare Market | 2026-2036
Switzerland Haircare Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Haircare Market Analytics
Multi-source ingredient procurement is rebalancing toward regional Swiss botanical suppliers as brands reduce dependency on distant raw material networks. L'Oréal S.A. leverages its Geneva-based innovation hub to anchor premium positioning in professional channels. Procter & Gamble Switzerland Sarl sustains mass-market penetration through dense retail distribution. Rausch AG Kreuzlingen specializes in alpine herb formulations that differentiate its portfolio against standard chemical alternatives.
Switzerland Haircare encompasses formulations for scalp cleansing, conditioning, styling, and therapeutic treatment of hair fiber, typically delivered through surfactant-based emulsions with pH balances between 4.5 and 6.0 to maintain cuticle integrity. These products serve both daily consumer maintenance and professional salon intervention for color-treated or damaged hair. Shampoos and conditioners occupy the core volume base, while treatment applications capture disproportionate margin pools as consumers prioritize damage repair over basic cleansing. Natural and organic ingredient types expand fastest among ingredient categories, though chemical-based formulations still dominate salon professional segments due to performance reliability.
Swissmedic enforces cosmetic safety standards that mandate preservative disclosure and allergen labeling, compelling reformulation investments across domestic manufacturers. REACH compliance through ECHA registration requirements governs imported chemical actives entering Swiss supply chains. Mibelle AG navigates these frameworks by controlling in-house extraction of Edelweiss and Gentian root for compliant natural claims. Stakeholders must monitor evolving EU Green Deal alignment pressures that could extend carbon footprint disclosure obligations to cosmetic packaging and ingredient transport.
Market Dynamics
Swissmedic's tightening cosmetic safety guidelines are forcing domestic manufacturers to restructure ingredient disclosure protocols and reformulate preservative systems, compressing product development timelines while elevating compliance costs across Zurich and Geneva production facilities.
Growth Catalysts
- Swissmedic disclosure mandates:Regulatory pressure for allergen transparency is accelerating clean-label innovation among domestic formulators seeking premium positioning.
- Alpine botanical extraction:Regional suppliers of Edelweiss and Gentian root are capturing procurement share as brands localize raw material sourcing.
- Professional salon channel:Zurich and Geneva stylist networks are expanding treatment service menus, pulling high-margin therapeutic formulations through specialized distribution.
Market Restraints
- Import chemical actives:REACH registration through ECHA creates friction for non-EU suppliers entering Swiss supply chains.
- Preservative system costs:Reformulation to meet Swissmedic disclosure rules elevates R&D expenditure for mid-tier domestic brands.
- Performance gap in naturals:Salon professionals retain preference for synthetic actives due to reliability in color-treated hair applications.
Strategic Opportunities
- Ticino and Basel retail penetration:Underdeveloped urban markets outside Zurich-Geneva axis offer whitespace for organic product line expansion.
- EU Green Deal alignment:Early adoption of carbon footprint disclosure for packaging transport positions Swiss brands for cross-border premium access.
- Direct-to-stylist digital platforms:Bypassing traditional wholesale channels enables margin capture and formulation customization for independent Zurich professionals.
Industry Challenges
- Cosmetic chemist talent scarcity:Specialized formulators capable of bridging natural claims with performance benchmarks command premium compensation in Geneva.
- Legacy ERP integration:Batch-level ingredient tracking for Swissmedic compliance strains outdated manufacturing software at Kreuzlingen facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Haircare Market |
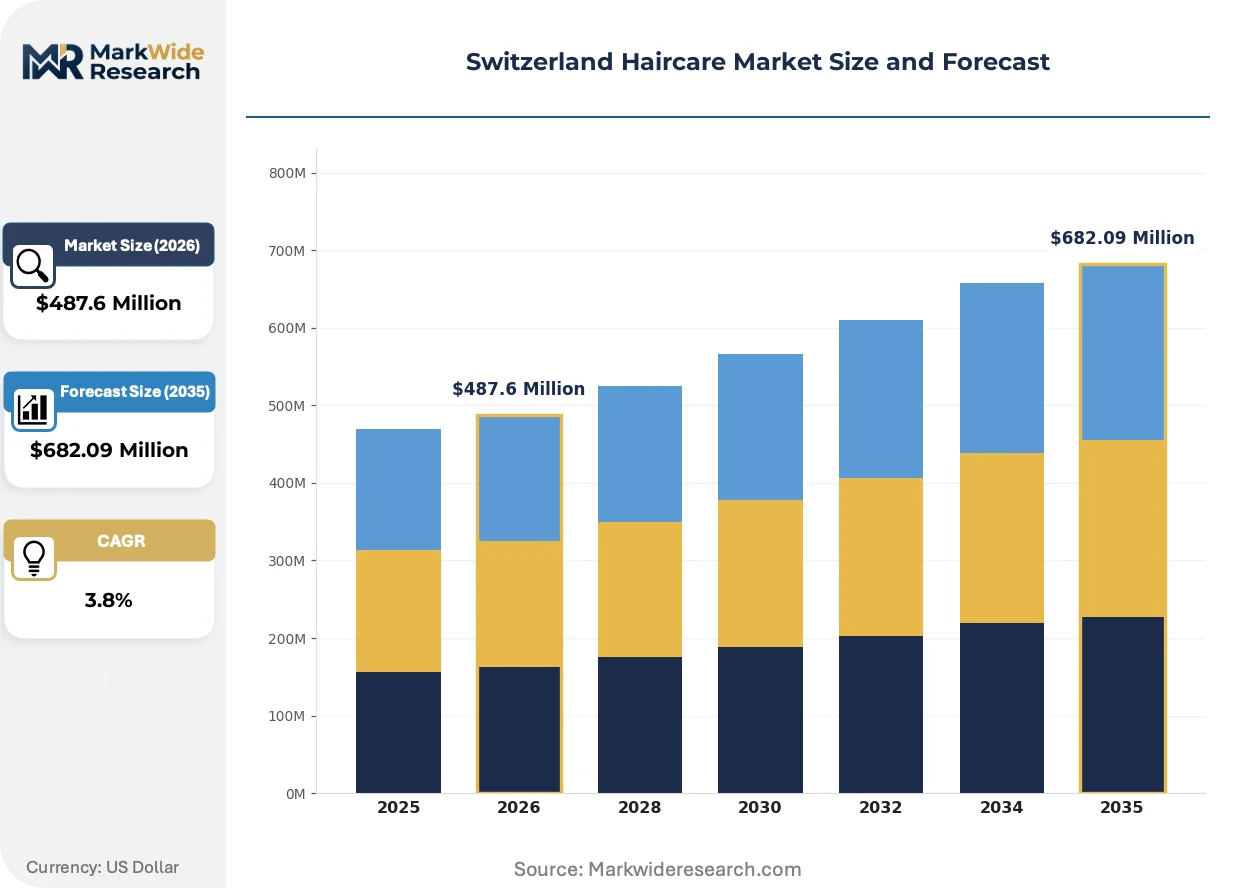
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $682.09 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Styling Products Customer Type: Retail Consumers, Salons, Wholesalers, E-commerce Platforms Ingredient Type: Natural, Organic, Chemical-based, Herbal Application: Daily Care, Treatment, Color Protection, Damage Repair |
| Companies Covered | L'Oréal S.A., Procter & Gamble Switzerland Sarl, Henkel AG & Co. KGaA, Beiersdorf (Switzerland) GmbH, Oriflame Holding AG, Kao Corporation, Wella Company, Rausch AG Kreuzlingen, Mibelle AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Haircare Market Evolving Landscape
Formulation science is pivoting toward bioactive preservation systems as synthetic alternatives face disclosure scrutiny, while distribution channels fragment between professional salon networks and direct digital access models.
Biotechnology-derived preservation systems are absorbing regulatory pressure previously borne by paraben and formaldehyde-releasing chemistries. Geneva-based innovation hubs are piloting peptide-based antimicrobial actives for pH-balanced emulsions. This transition is absorbing shelf-life risk that previously constrained natural claim viability, compressing the performance gap between clean-label and conventional formulations.
Swissmedic cosmetic safety standards now mandate batch-level preservative disclosure with expanded allergen labeling requirements. Domestic manufacturers face 18-24 month reformulation cycles to achieve compliant repositioning. Treatment-grade products targeting damaged hair repair encounter the steepest compliance burden due to complex multi-actives.
Urban consumers in Zurich and Geneva are consolidating purchase decisions around certification-driven preference hierarchies, prioritizing organic and natural claims over basic cleansing efficacy. Specialty retailers are displacing mass-market shelf space with curated botanical assortments. This behavioral shift concentrates margin pools in treatment applications where damage repair commands price premiums.
Switzerland Haircare Market Segmentation
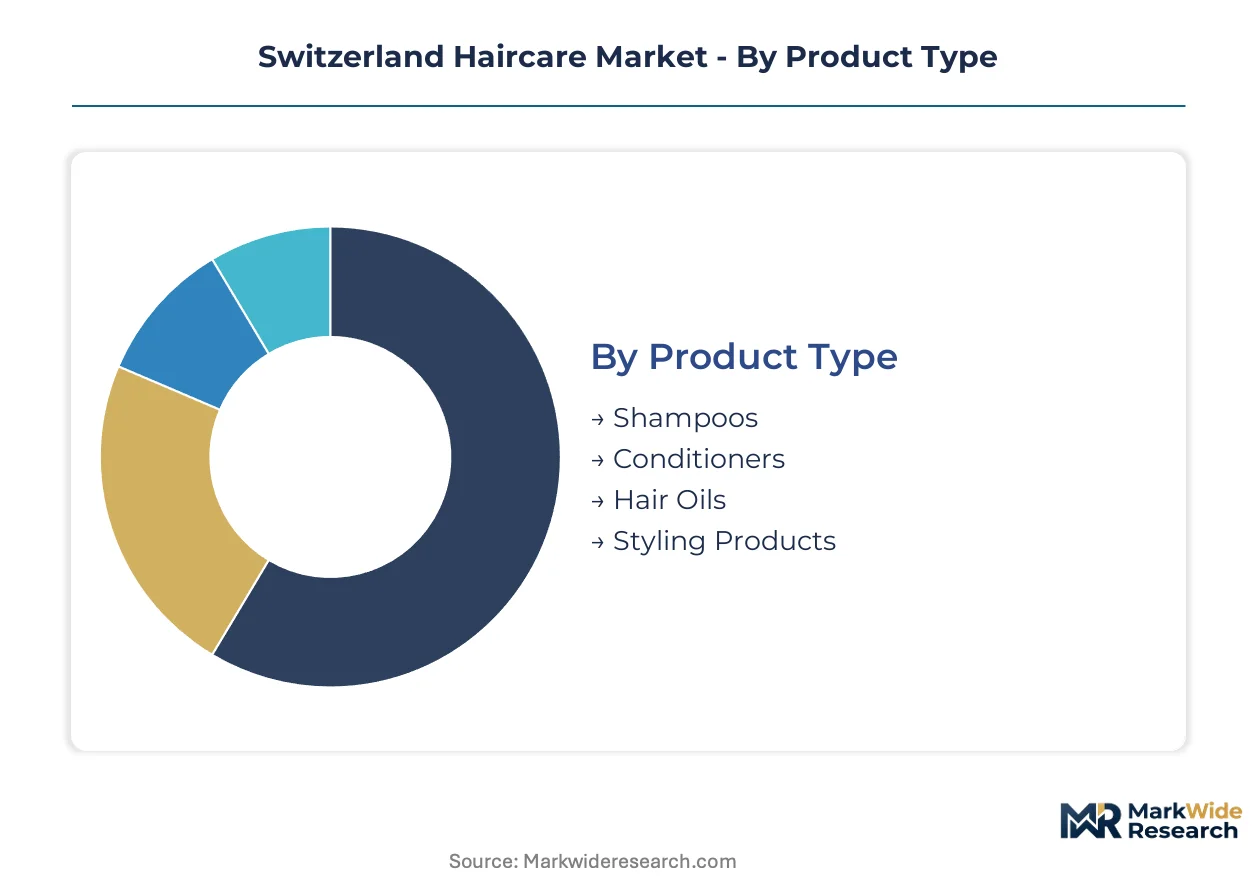
Swissmedic disclosure mandates reshape competitive positioning across haircare segments, with certification burdens varying sharply by formulation chemistry and distribution channel. Brands must navigate divergent compliance timelines depending on whether products target retail shelves or professional salon networks.
Product Type:
Swissmedic preservative disclosure rules impose the heaviest reformulation burden on treatment-grade formulations with complex multi-actives, while basic cleansing products face streamlined compliance pathways.
- Shampoos:Surfactant-based emulsions with pH 4.5-6.0 balance dominate unit volume through daily consumption patterns. Zurich and Geneva retail channels concentrate demand for scalp-cleansing variants as urban consumers prioritize basic maintenance over specialized interventions.
- Conditioners:Cationic conditioning agents deposit on damaged cuticles to restore fiber integrity. Salon professionals in Geneva pull high-margin therapeutic formulations through specialized distribution, though synthetic actives retain preference for color-treated hair reliability.
- Hair Oils:Lipid-based sealants target porosity control in chemically processed hair.
- Styling Products:Film-forming polymers and resins deliver hold and texture modification.
Shampoos sit at the top of the volume ranking, with conditioners climbing the fastest.
Customer Type:
Cost tier stratification separates mass-market retail from premium professional channels, with margin structures diverging by a factor of three between supermarket shelves and Zurich stylist stations.
- Retail Consumers:Certification-driven purchase hierarchies prioritize organic and natural claims over basic cleansing efficacy. Urban shoppers in Zurich and Geneva consolidate decisions around Swissmedic-compliant labeling, displacing mass-market shelf space with curated botanical assortments.
- Salons:Zurich and Geneva stylist networks expand treatment service menus, pulling therapeutic formulations through specialized distribution. Professional channels capture disproportionate margin pools as damage repair commands price premiums over basic cleansing.
- Wholesalers:Traditional distribution intermediaries face margin compression from direct-to-stylist digital platforms.
- E-commerce Platforms:Direct digital access models fragment channel control, enabling formulation customization for independent professionals.
Retail consumers anchor volume demand, with salons expanding most quickly.
Ingredient Type:
Supply concentration in alpine botanical extraction is rebalancing procurement toward regional Swiss suppliers as brands reduce dependency on distant raw material networks.
- Natural:Bioactive preservation systems absorb regulatory pressure previously borne by synthetic alternatives. Geneva-based innovation hubs pilot peptide-based antimicrobial actives, compressing the performance gap between clean-label and conventional formulations.
- Organic:Certification requirements from Swiss-accredited bodies command premium shelf positioning. Urban consumers prioritize these claims, concentrating margin pools in treatment applications where damage repair justifies price elevation.
- Chemical-based:Synthetic actives retain salon professional preference due to reliability in color-treated hair applications.
- Herbal:Alpine herb formulations from regional suppliers differentiate against standard chemical alternatives.
Chemical-based ingredients retain volume leadership, with organic formulations gaining share fastest.
Application:
Maturity gradients separate established daily maintenance routines from emerging therapeutic interventions, with damage repair segments absorbing the steepest Swissmedic compliance investments.
- Daily Care:Basic cleansing and conditioning regimens dominate consumption frequency. These formulations encounter streamlined compliance pathways due to simpler preservative profiles and lower allergen complexity.
- Treatment:Intensive repair formulations for damaged fiber encounter 18-24 month reformulation cycles. Complex multi-actives face the steepest Swissmedic burden, compressing product development timelines while elevating R&D expenditure for mid-tier domestic brands.
- Color Protection:UV filters and antioxidant systems preserve artificial pigment deposits.
- Damage Repair:Protein reconstructors and bond builders target chemically compromised cuticles.
Daily care commands volume primacy, with treatment applications expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zurich-Geneva corridor anchors Swiss haircare demand through concentrated urban retail networks and professional salon infrastructure. Regional variation emerges across linguistic divides and cross-border trade flows.
Zurich Metropolitan Area
Certification-driven consumers in Zurich prioritize Swissmedic-compliant organic claims over basic efficacy. The canton's retail density supports curated botanical assortments displacing mass-market shelf space. L'Oréal's Geneva innovation hub feeds professional-grade formulations into Zurich stylist networks.
Geneva and Vaud
Cross-border shopping from France shapes price sensitivity in Geneva retail corridors. Swissmedic disclosure mandates compress product development timelines for Vaud-based manufacturers. Professional salon channels capture disproportionate margins through damage repair service menus.
Basel and Northwest Switzerland
Pharmaceutical industry spillover elevates technical formulation standards in Basel consumer expectations. Rausch AG Kreuzlingen anchors alpine herb extraction within this sub-region's supply base. Underdeveloped retail penetration relative to Zurich-Geneva creates whitespace for organic line expansion.
Ticino
Italian-speaking consumers in Ticino import preferences from Milan beauty retail trends. Swiss enforcement of REACH-aligned chemical active regulations creates friction for non-EU suppliers entering this southern corridor. Local distribution infrastructure remains thinner than northern urban centers.
Bern and Central Switzerland
Administrative capital status concentrates institutional procurement for hospitality sector haircare in Bern. Mid-tier domestic brands face elevated R&D expenditure from Swissmedic reformulation cycles. Lucerne and Interlaken tourism channels pull travel-size premium formulations through hotel retail.
Switzerland Haircare Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue certified organic positioning through regional botanical sourcing. The market structures around three tiers: multinational mass-market anchors, mid-tier domestic specialists, and niche alpine-herb purveyors. Strategic archetypes include scale-driven retail distributors, innovation-led professional channel suppliers, and vertically integrated botanical extractors. Competitive moves concentrate on direct-to-stylist digital platform development and EU Green Deal alignment for cross-border premium access.
Among multinational anchors, L'Oréal S.A. and Procter & Gamble Switzerland Sarl exemplify divergent channel strategies. L'Oréal occupies a position tied to Geneva-based innovation infrastructure serving professional networks. Procter & Gamble Switzerland Sarl sits within mass-market retail penetration archetypes. Domestic specialists Rausch AG Kreuzlingen and Mibelle AG represent regional botanical integration models. These four entities collectively illustrate the competitive spectrum from global scale to alpine-herb differentiation.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Procter & Gamble Switzerland Sarl |
| Henkel AG & Co. KGaA |
| Beiersdorf (Switzerland) GmbH |
| Oriflame Holding AG |
| Kao Corporation |
| Wella Company |
| Rausch AG Kreuzlingen |
| Mibelle AG |
| Others |
Value Network & Pricing Analysis
EU Green Deal alignment pressures gate qualified supply and premium-tier pricing access for Swiss haircare manufacturers seeking cross-border market entry. Carbon footprint disclosure obligations for packaging transport and ingredient sourcing compress margins for non-compliant mid-tier brands while elevating certified organic lines to price premiums in Zurich and Geneva retail channels.
Pricing Analysis
Input-cost pass-through from alpine botanical extraction runs through treatment-grade formulations most heavily, as Edelweiss and Gentian root procurement commands premium sourcing investments. Three-tier pricing structure across premium, standard, and economy levels separates salon professional channels from mass retail and discount segments. Price differentiation hinges on Swissmedic certification grade and volume scale, with organic claims capturing 2-3x markup over conventional alternatives. Cost compression in mid-tier domestic brands is intensifying because preservative reformulation cycles absorb R&D budgets. Retail consumers in Ticino and Basel exhibit highest price sensitivity, while Zurich stylist networks show least elasticity due to service-menu bundling.
Supply Chain Analysis
Single-source vulnerability sits with French and Italian chemical active suppliers serving Geneva and Ticino corridors under REACH registration constraints. Geographic supply concentration draws from Germany, France, and regional Swiss alpine extraction zones around Kreuzlingen. Raw material dependencies center on surfactant bases, cationic conditioning agents, and bioactive preservation peptides. Regulatory restriction through Swissmedic batch-level disclosure mandates creates compliance friction for imported preservative systems. Distribution runs through professional salon networks in Zurich-Geneva, specialty retailers, and direct-to-stylist digital platforms fragmenting traditional wholesale control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switzerland Haircare functions as a stable compounder anchored by regulatory-driven premiumization that perpetually escalates formulation investment barriers. Urban consumer consolidation around certification hierarchies sustains organic segment expansion regardless of macroeconomic softness.
For Market Incumbents: Deepen backward integration into alpine botanical extraction to defend margin position against regional supplier price escalation. Secure captive supply of Edelweiss and Gentian root through long-term cultivation partnerships in Vaud and Valais. Expand direct-to-stylist digital platform presence in Zurich to bypass wholesale margin compression.
For New Entrants and Emerging Players: Swissmedic disclosure mandates in Switzerland open a window for clean-label positioning without legacy reformulation burden. Target Ticino and Basel retail penetration where organic line saturation remains below Zurich-Geneva thresholds. Pursue certification-first go-to-market angle through Swiss-accredited organic bodies before mass retail distribution.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier domestic specialists with compliant preservative portfolios because Swissmedic cycles have already absorbed their R&D restructuring costs. Long-term viability frames around 5-10 year regulatory premiumization runway. Signal to monitor is EU Green Deal carbon disclosure enforcement extending to cosmetic ingredient transport.
| Strategic Initiative | Industry Significance |
|---|---|
| Alpine Botanical Extraction Integration | Captive supply of Edelweiss and Gentian root secures compliant natural claims against regional supplier concentration. |
| Direct-to-Stylist Digital Platform | Bypassing traditional wholesale channels captures margin and enables formulation customization for Zurich professionals. |
| Swissmedic Compliance Repositioning | Early reformulation completion opens premium shelf access while competitors absorb 18-24 month development cycles. |
| EU Green Deal Alignment | Carbon footprint disclosure for packaging transport positions brands for cross-border premium market entry. |
| Ticino-Basel Retail Expansion | Underdeveloped urban markets outside Zurich-Geneva axis offer whitespace for organic product line penetration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply-side intelligence. Primary engagement captured formulation chemists at Geneva-based innovation hubs, procurement leads at Zurich retail chains, salon owners across the cantonal network, and regulatory affairs specialists navigating Swissmedic compliance. Secondary validation drew from Swissmedic cosmetic safety filings, ECHA REACH registration databases, customs import records for chemical actives, and cantonal business registries tracking manufacturer facility investments. Bottom-up volume builds from product-level consumption patterns triangulated against top-down macroeconomic anchors.
Comparable-period anchoring established baseline consumption patterns against historical regulatory implementation phases. Segmentation modeling spanned product type, customer channel, ingredient chemistry, and application purpose across the projection horizon. CAGRs derived from regression analysis of volume-price elasticities under varying compliance cost assumptions. Industry-specific forecast inputs included Swissmedic reformulation cycle timelines and alpine botanical harvest yield variability.
Revisions become necessary when regulatory enforcement intensity shifts, cross-border trade friction escalates, or consumer certification preferences pivot toward alternative claim hierarchies. Forecasts reflect documented assumptions about compliance cost pass-through rates and professional channel growth sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Hair Gel Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Anti-Acne Facial Serum Market
Beauty & Personal Care
India Cosmetics Products Market
Beauty & Personal Care
Private Label Cosmetics Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
Beauty and Wellness Products Market
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Intensive Conditioner Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Foaming Hand Soaps Market