
 Sunless Tanners Market | 2026-2036
Sunless Tanners Market Size, Share, and Industry Trends Forecast 2026-2036
Sunless Tanners Market Analysis
Buyer concentration among professional salons and spas is recalibrating as independent estheticians and mobile tanning services fragment the traditional channel structure. L'Oréal SA leverages its dermatological research infrastructure to sustain premium positioning across European and North American markets. Bondi Sands anchors its competitive stance through mass-market accessibility and strong pharmacy distribution networks in Australia and the United Kingdom. PZ Cussons Plc competes via specialized formulations targeting darker skin tones, a historically underserved segment.
Sunless tanners constitute topical cosmetic formulations employing dihydroxyacetone (DHA) or erythrulose as active agents, typically at concentrations between three and fifteen percent, to induce melanoidin formation on the stratum corneum without ultraviolet exposure. Their primary commercial purpose centers on providing cosmetic bronzing while eliminating photocarcinogenic risk associated with solar or artificial UV exposure. Lotions occupy the mature volume core of the product type landscape, whereas mousses capture accelerating share among time-constrained consumers seeking rapid-dry, streak-resistant application. The self-tanning application segment leads absolute value generation, though gradual tan formats expand fastest among male end users and first-time adopters seeking controlled color build.
The US FDA governs DHA concentration limits and labeling requirements for sunless tanning products, while the European Commission's Cosmetics Regulation mandates safety assessments through the Scientific Committee on Consumer Safety. REACH compliance pressures manufacturers to substantiate ecotoxicological profiles of synthetic bronzing agents, elevating reformulation costs for smaller suppliers. Stakeholders must monitor evolving clean-beauty certification standards and state-level ingredient disclosure laws to anticipate compliance burdens and first-mover positioning in regulated formulations.
Market Dynamics
Clean-beauty certification standards are fragmenting competitive positioning across the Sunless Tanners Market, as REACH compliance costs and state-level ingredient disclosure laws force reformulation cycles that favor suppliers with dedicated toxicology infrastructure.
Growth Catalysts
- EU Cosmetics Regulation tightening:Ingredient scrutiny under ECHA frameworks accelerates migration toward plant-derived DHA alternatives, opening premium positioning for compliant suppliers.
- Mobile esthetician services:Independent practitioners deploying portable spray-tan systems are capturing appointment volume outside traditional salon footprints.
- Erythrulose blending:Hybrid formulations combining DHA with erythrulose extend wear time and reduce odor complaints, pulling repeat purchase rates among time-constrained professionals.
Market Restraints
- Synthetic bronzer input volatility:Petrochemical feedstock fluctuations for DHA precursors compress margin predictability for mid-tier formulators lacking long-term supply contracts.
- Supplier concentration in China:Bulk DHA manufacturing clusters in Zhejiang and Jiangsu provinces create geographic risk exposure for brands without dual-source qualification.
- Photocarcinogenic substitution threat:Melanotan peptide injections and nasal sprays, though unapproved by FDA and EMA, divert experimental users seeking deeper color permanence.
Strategic Opportunities
- Men's gradual tan formats:Controlled color-build products targeting male first-time adopters remain underdeveloped relative to female-skewed instant-bronze formulations.
- Pharmacy channel expansion:Boots in the United Kingdom and Shoppers Drug Mart in Canada demonstrate untapped shelf space for dermatologist-endorsed variants.
- Clean-beauty certification tailwind:EWG Verified and Leaping Bunny standards create pricing power for brands that complete substantiation ahead of mandatory disclosure laws.
Industry Challenges
- Toxicologist hiring friction:Qualified safety assessors capable of navigating SCCS opinion requirements command compensation premiums that strain emerging brand budgets.
- Legacy ERP integration:Batch record systems designed for conventional cosmetics require reconfiguration to track DHA potency variations across erythrulose-blended production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sunless Tanners Market |
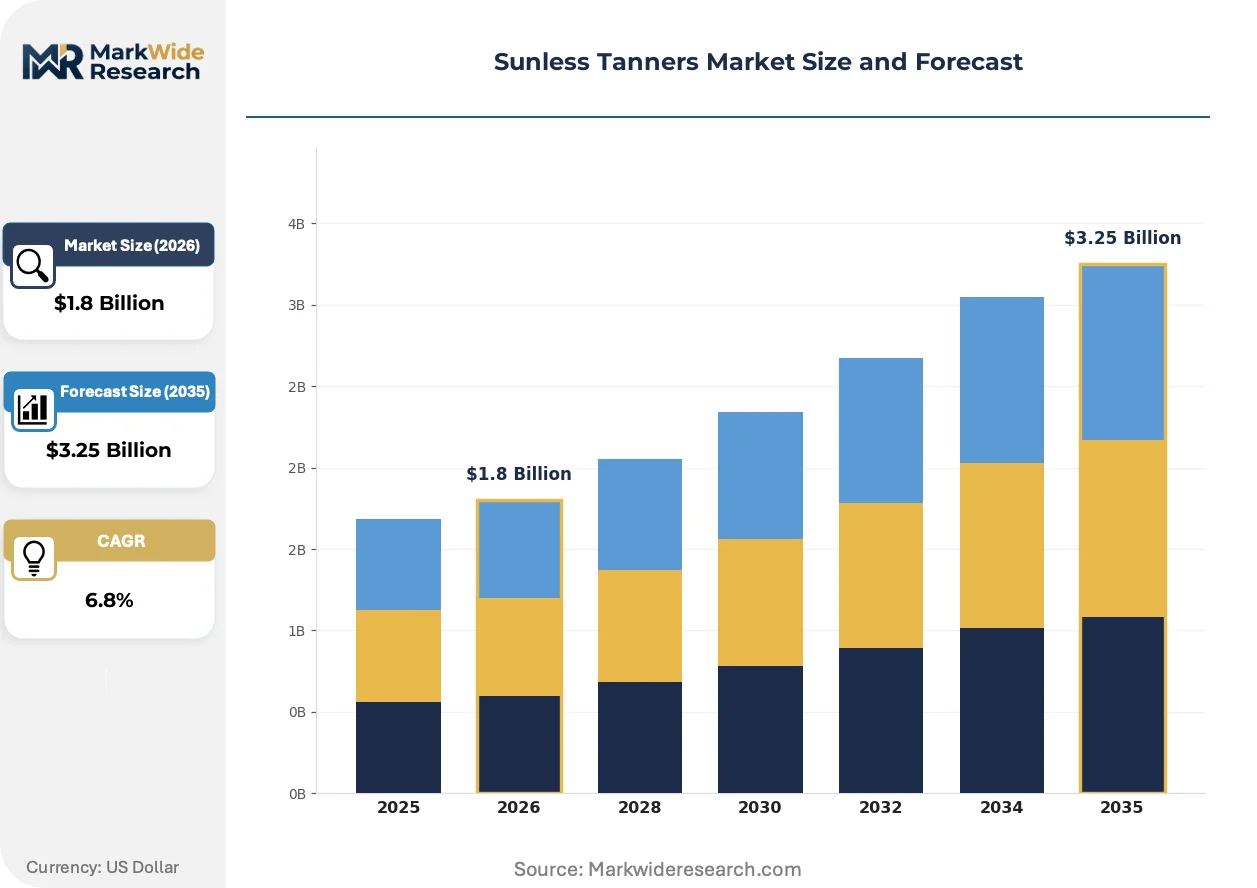
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Lotions, Gels, Mousses Application: Self-Tanning, Gradual Tan, Instant Tan, Pre-Tan End User: Women, Men, Salons, Spas Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | L'Oréal SA, Bondi Sands, PZ Cussons Plc, Clarins Group, Crown Laboratories Inc., Johnson & Johnson Services Inc., Kao Corporation, Tan-Luxe, Dr. Dennis Gross Skincare LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sunless Tanners Market Emerging Trajectories
Formulation chemistry, regulatory architecture, and channel economics are converging to reshape how sunless tanning products reach end users and justify price positioning.
Micro-encapsulated DHA delivery systems are absorbing moisture-triggered release mechanisms that extend color development windows and reduce transfer staining. Professional salons in metropolitan Australia and the United Kingdom are adopting these systems at accelerated replacement cycles for conventional mousse formats. The technology is absorbing premium pricing power from standard lotion formulations by delivering measurable reduction in client complaint rates.
REACH Annex XIV authorization requirements for certain synthetic intermediates are compelling manufacturers to file substitution plans or seek derogations for continued use. The industrial consequence is a bifurcation between large suppliers with dedicated regulatory affairs teams and smaller competitors exiting the European market. Color-cosmetic brands with existing clean-formulation pipelines are capturing shelf space formerly held by conventional sunless tanner suppliers.
Subscription-based replenishment models are displacing pharmacy impulse purchases among established users, with direct-to-consumer platforms capturing recurring revenue from high-frequency applicators. Independent estheticians and mobile technicians are the channel segment most disrupted, as consumers bypass professional application for home-use convenience. This behavioral shift concentrates in the United States, where same-day delivery infrastructure supports just-in-time restocking patterns.
Sunless Tanners Market Segmentation
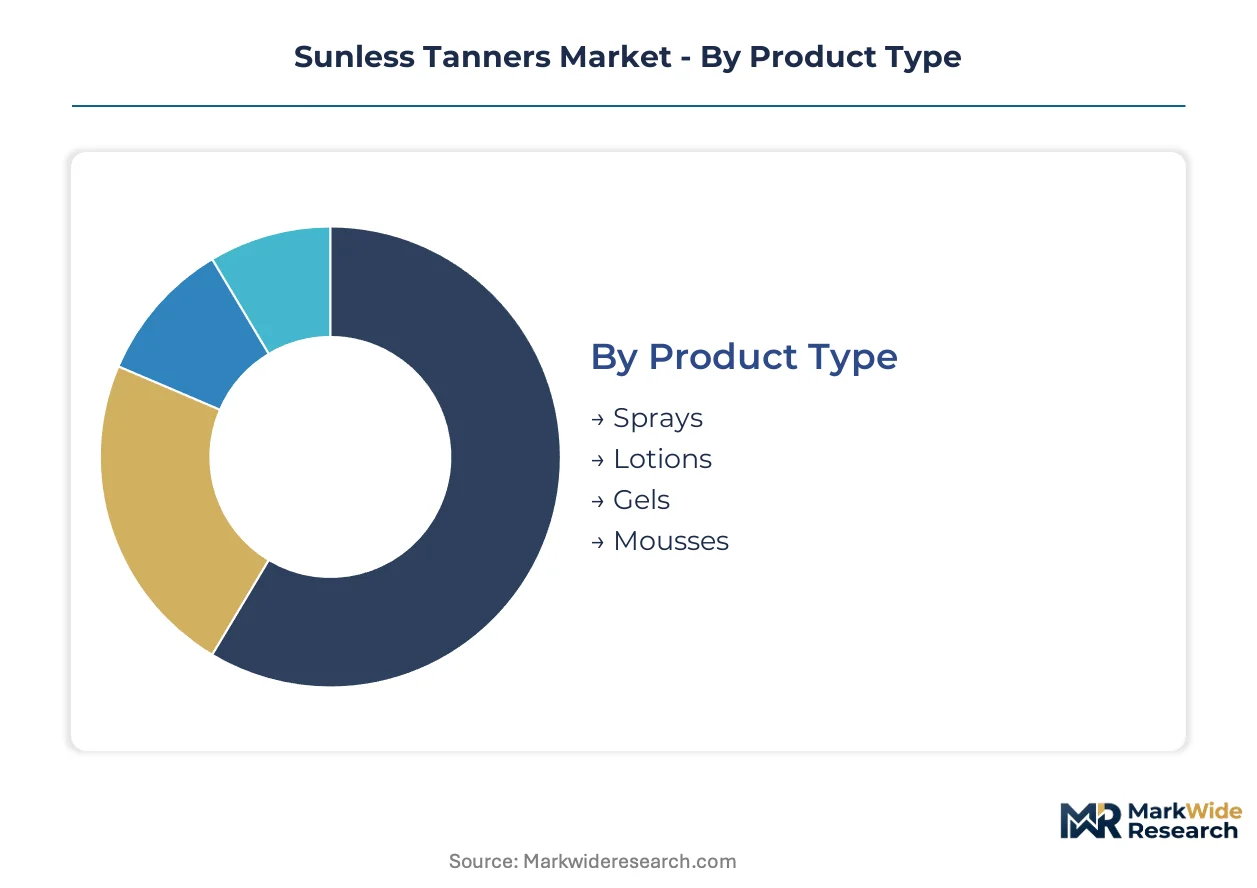
Product formats and application methods segment the Sunless Tanners Market along distinct usage occasions and technical performance requirements. Each category reveals divergent margin structures and channel dependencies that shape supplier strategy.
Product Type:
Standalone application formats dominate home-use scenarios, while embedded professional systems require compatible chemistry for spray-gun deployment.
- Lotions:Cream-based emulsions with three-to-fifteen percent DHA concentration deliver extended working time for even coverage. Demand concentrates in United States pharmacy and mass retail channels where established users prioritize familiarity over speed.
- Mousses:Lightweight foam structures with rapid-dry polymers reduce transfer staining and enable same-day dressing. Faster expansion belongs to time-constrained professionals in Australia and United Kingdom metropolitan markets seeking streak-resistant results.
- Sprays:Aerosol and pump-dispensed formats for difficult-to-reach areas.
- Gels:Transparent, quick-drying formulations favored for facial application and precise control.
Volume placements concentrate in Lotions; the steepest expansion trajectory belongs to Mousses.
Application:
Cost tiering separates immediate-color premiums from buildable economy positioning.
- Self-Tanning:Full-strength DHA formulations delivering visible color within four-to-eight hours represent the revenue core. Demand concentrates in direct-to-consumer subscriptions and United States specialty retail where repeat purchase frequency sustains lifetime value.
- Gradual Tan:Low-concentration daily moisturizers with subtle bronzing agents build color over three-to-five applications. Male first-time adopters in United Kingdom and Australian pharmacy channels drive fastest share gain.
- Instant Tan:Cosmetic bronzers with immediate wash-off color for same-day events.
- Pre-Tan:Exfoliating and pH-balancing treatments optimizing DHA absorption.
Revenue weight sits with Self-Tanning; Gradual Tan climbs the fastest among male demographics.
End User:
Customer type determines formulation complexity and service-versus-product mix.
- Women:Primary purchasers across all formats with established category knowledge and brand loyalty.
- Men:Emerging segment underserved by female-skewed marketing and fragrance profiles.
- Salons:Professional spray-tan operators requiring bulk supply and technical training support.
- Spas:Premium service providers integrating sunless tanning with broader wellness protocols.
Transaction volume concentrates in Women; Men represent the fastest-expanding addressable base.
Distribution Channel:
Supply concentration varies sharply between inventory-heavy retail and asset-light digital fulfillment.
- Online Stores:Direct-to-consumer platforms and marketplace aggregators capture subscription replenishment and discovery-driven trial.
- Supermarkets:Mass-market velocity depends on promotional cadence and shelf-positioning investment.
- Specialty Stores:Beauty retailers like Sephora and Ulta Beauty curate premium and clean-certified assortments.
- Pharmacies:Boots, Shoppers Drug Mart, and CVS anchor trust-based purchasing for sensitive-skin variants.
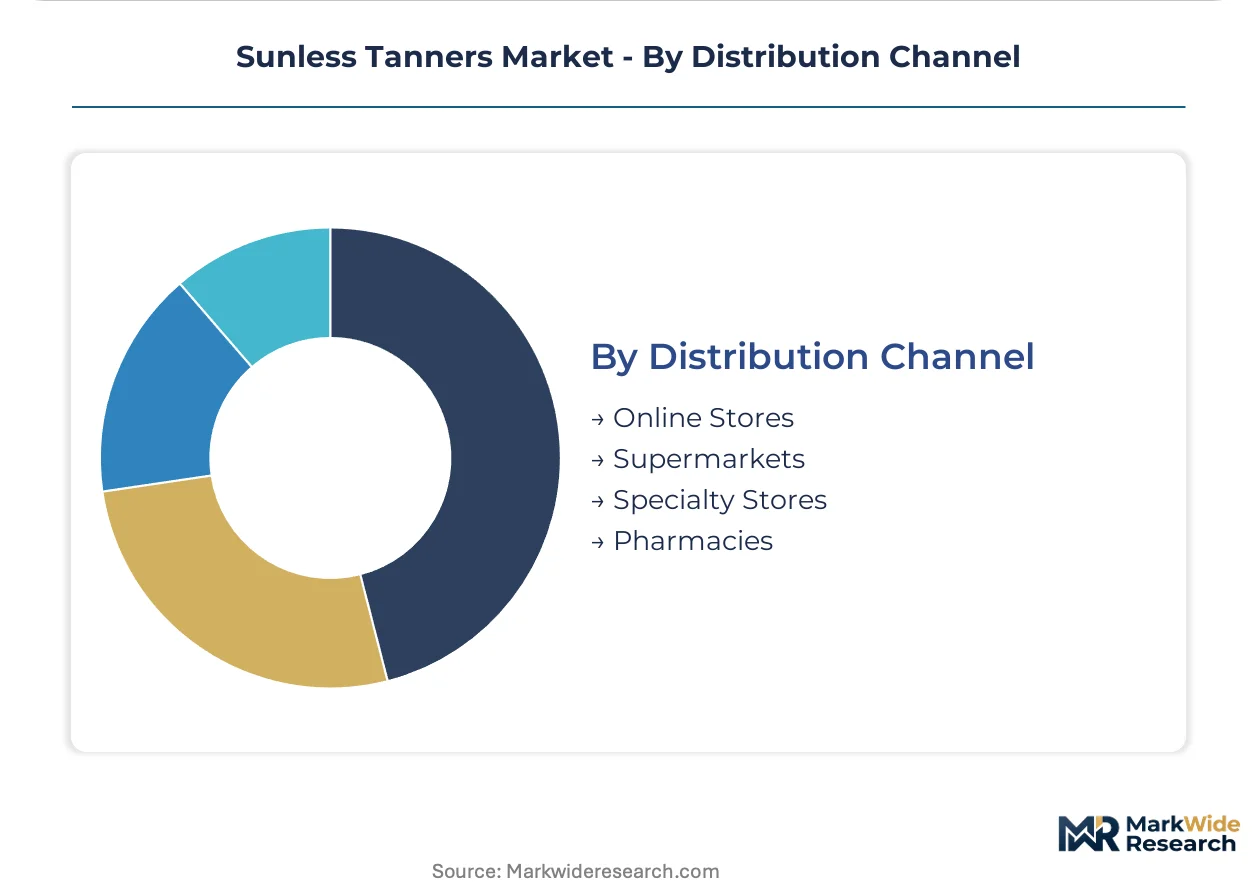
Volume flows through Pharmacies; Online Stores gain share fastest among repeat purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where direct-to-consumer platforms and specialty retail drive volume, while pharmacy networks in the United Kingdom and Australia anchor mass-market penetration. Regulatory divergence between FDA oversight and EU REACH frameworks is fragmenting supplier compliance strategies across jurisdictions.
United States
FDA labeling requirements and DHA concentration limits govern formulation standards, while direct-to-consumer subscription models capture recurring revenue from high-frequency users. California and New York metropolitan areas host the densest concentration of professional spray-tan operators adopting micro-encapsulated delivery systems.
United Kingdom
Boots pharmacy networks demonstrate untapped shelf space for dermatologist-endorsed variants, while male first-time adopters drive gradual tan format expansion. The Scientific Committee on Consumer Safety mandates safety assessments under EU Cosmetics Regulation, elevating substantiation costs for imported formulations. Greater London anchors professional salon density, with mobile esthetician services fragmenting traditional channel structures in Manchester and Birmingham.
Australia
Bondi Sands leverages mass-market accessibility through strong pharmacy distribution, while metropolitan salons in Sydney and Melbourne accelerate adoption of rapid-dry mousse formats. TGA oversight aligns with international cosmetic safety standards, though state-level ingredient disclosure laws vary. Spray-tan equipment manufacturing clusters in Queensland support independent technician proliferation.
Germany
REACH Annex XIV authorization requirements compel manufacturers to file substitution plans for synthetic intermediates, bifurcating the supplier base. Bavaria and North Rhine-Westphalia host dermatological research infrastructure sustaining premium brand positioning. Clean-beauty certification tailwinds from EWG Verified standards create pricing power for substantiated formulations.
China
Bulk DHA manufacturing concentrates in Zhejiang and Jiangsu provinces, creating geographic risk exposure for brands without dual-source qualification. NMPA cosmetic registration requirements and GB standards govern import compliance. Shanghai and Guangzhou serve as formulation R&D hubs for Asia-Pacific market adaptation.
Sunless Tanners Market Vendor Landscape
European producers anchor premium-tier positioning through dermatological research infrastructure; Australian and North American specialists hold mass-market accessibility through pharmacy and direct-to-consumer channels. The vendor base stratifies across three archetypes: multinational beauty conglomerates with toxicology infrastructure, regional pharmacy-channel specialists, and independent clean-beauty challengers. Capacity expansion into plant-derived DHA alternatives and strategic partnerships for dual-source supply qualification represent dominant competitive moves.
Among multinational beauty conglomerates, L'Oréal SA exemplifies premium-tier positioning sustained through dermatological research infrastructure across European and North American markets. Bondi Sands occupies a position within the mass-market accessibility archetype, anchored by pharmacy distribution strength in Australia and the United Kingdom. PZ Cussons Plc represents specialization in historically underserved segments, with formulation focus on darker skin tone adaptation.
| Leading Market Players |
|---|
| L'Oréal SA |
| Bondi Sands |
| PZ Cussons Plc |
| Clarins Group |
| Crown Laboratories Inc. |
| Johnson & Johnson Services Inc. |
| Kao Corporation |
| Tan-Luxe |
| Dr. Dennis Gross Skincare LLC |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock indices for DHA precursors cascade through three-tier pricing structures across premium, standard, and economy levels, compressing margin predictability for mid-tier formulators lacking long-term supply contracts while elevating pricing power for vertically integrated suppliers with captive fermentation capacity.
Pricing Analysis
Volume placements concentrate in mass-market lotions with thin margins, while premium mousses and micro-encapsulated formats capture superior returns. Price differentiation hinges on clean-beauty certification tier and dermatological endorsement level. Cost compression in standard-tier pharmacy channels intensifies because of promotional cadence demands from Boots and CVS. Independent estheticians exhibit highest price sensitivity; professional salon chains demonstrate lowest sensitivity due to service-bundling economics.
Supply Chain Analysis
Direct-to-consumer platforms handle subscription replenishment demand, while pharmacy wholesale and professional distributor networks manage bulk salon procurement. Bulk DHA manufacturing concentrates in China, South Korea, and Germany. Formulation chemistry draws from petrochemical feedstocks, plant-derived sugar substrates, and erythrulose blending stocks. Single-source vulnerability in Zhejiang and Jiangsu province clusters creates geographic risk exposure for brands without dual-source qualification. Distribution runs through pharmacy wholesale, professional beauty distributors, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XIV authorization requirements and escalating toxicologist hiring costs are forcing weaker formulators toward exit, consolidating viable supplier bases around entities with dedicated regulatory affairs infrastructure.
For Market Incumbents: Lock in dual-source qualification for plant-derived DHA alternatives to mitigate Zhejiang concentration risk. Secure exclusive pharmacy shelf-space agreements with Boots and Shoppers Drug Mart before clean-beauty certification mandates tighten. Capacity addition in Bavaria and North Rhine-Westphalia dermatological research clusters sustains premium positioning against peptide injection substitutes. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest customer acquisition friction for gradual tan formats targeting male first-time adopters. White-space concentration sits in dermatologist-endorsed variants for darker skin tone adaptation. Pharmacy channel entry through Boots represents the most penetrable route given untapped shelf space and trust-based purchasing patterns. For Investors and Strategic Acquirers: The window for entry favors regional pharmacy-channel specialists with established clean-formulation pipelines and EWG Verified substantiation. Mid-term viability centers on brands completing REACH compliance ahead of mandatory disclosure laws. Monitor SCCS opinion issuance timelines for synthetic intermediate derogations as inflection indicators for competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Beauty Certification Investment | EWG Verified and Leaping Bunny standards create pricing power ahead of state-level ingredient disclosure laws. |
| Dual-Source Supply Qualification | Zhejiang and Jiangsu province concentration risk demands alternative fermentation capacity in Germany or South Korea. |
| Pharmacy Channel Expansion | Boots and Shoppers Drug Mart shelf space captures trust-based purchasing for sensitive-skin and dermatologist-endorsed variants. |
| Plant-Derived DHA Transition | REACH Annex XIV substitution plans favor bio-fermentation routes over petrochemical precursors for European market access. |
| Mobile Esthetician Equipment Partnership | Queensland spray-tan manufacturing clusters support independent technician proliferation outside traditional salon footprints. |
Methodological Framework
Independent corroboration across formulation chemists, professional salon operators, pharmacy category buyers, and regulatory affairs consultants underwrites the qualitative findings. Primary interviews with R&D directors at multinational beauty conglomerates, procurement leads at Boots and Shoppers Drug Mart, and mobile esthetician service operators captured channel dynamics and ingredient sourcing patterns. Secondary validation drew from ECHA REACH registration databases, FDA cosmetic labeling guidance, EU Cosmetics Regulation SCCS opinions, and pharmacy retail audit data. Bottom-up volume estimates from product-format segmentation triangulated against top-down market value assessments.
Comparable-period anchoring to historical DHA concentration trends and professional salon adoption cycles established baseline trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, application method, end-user demographic, and distribution channel dimensions. CAGRs were derived from regression analysis of volume and value outputs against macroeconomic indicators and regulatory event timelines. Forecast inputs included EWG Verified certification penetration rates and mobile esthetician service proliferation indices.
The model holds under stable REACH authorization timelines and continued FDA DHA concentration limits; deviation in SCCS opinion issuance or state-level ingredient disclosure acceleration would shift supplier viability distributions. Practitioners should monitor ECHA Annex XIV candidate list expansions and California Proposition 65 precedent cases for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
Personal Care Products Market
Beauty & Personal Care
Brazil Cosmetics Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Global Organic Personal Care Products Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market
Beauty & Personal Care
Australia Facial Care Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market