
 Bath Oil Market | 2026-2036
Bath Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Bath Oil Market Analysis
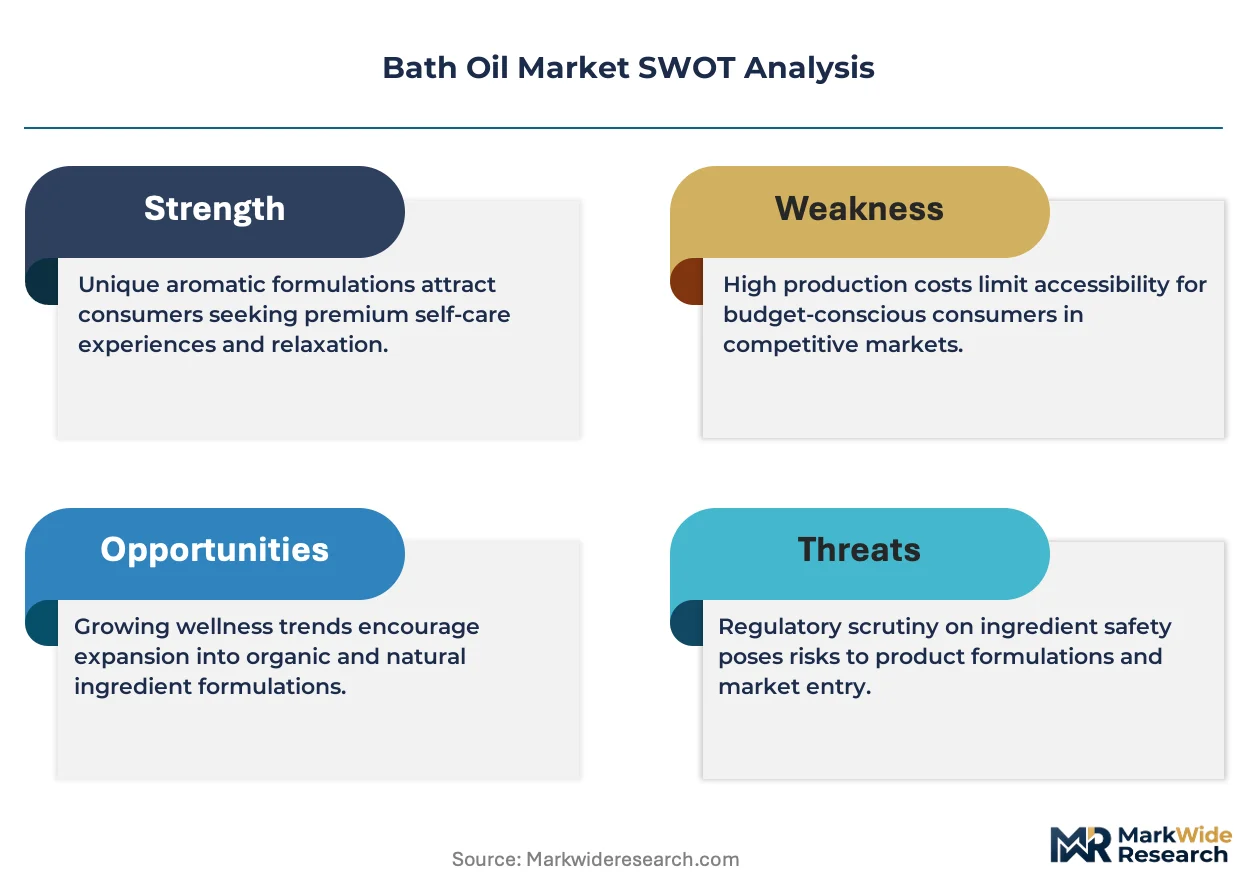
Asset-light contract manufacturing and private-label financing is narrowing the capital barrier for new entrants in bath oil production. Estee Lauder leverages its integrated supply chain to control premium ingredient sourcing across multiple continents. Burt's Bees anchors its market presence through specialized natural positioning that commands shelf space in health stores. Viva Naturals differentiates via direct-to-consumer channel control that bypasses traditional retail markups.
Bath oil comprises lipid-based formulations—typically blending carrier oils such as sweet almond, jojoba, or fractionated coconut with emulsifiers to disperse in bathwater—designed primarily for skin moisturization, aromatherapy delivery, and therapeutic relaxation. Manufacturing involves cold-pressing or solvent-free extraction to preserve volatile compound integrity, followed by stability testing for emulsion performance in heated water. Moisturizing and aromatherapy product types command the dominant revenue share as consumers prioritize dual-function wellness routines, while therapeutic formulations targeted at muscle recovery represent the fastest-growing margin pool. Natural oils and essential oils ingredient categories capture premium pricing through clean-label positioning, though synthetic oils maintain volume leadership in mass-market channels.
Regulatory frameworks including FDA cosmetic labeling requirements, EU REACH substance restrictions, and ECHA allergen disclosure mandates are elevating compliance costs while simultaneously creating market access barriers for uncertified suppliers. The EU Green Deal's chemical sustainability targets are pressuring reformulation away from petrochemical-derived emollients toward plant-based alternatives. Stakeholders must monitor evolving patch-testing and dermatological certification standards as dermatologist endorsement becomes a decisive purchasing trigger.
Market Dynamics
EU REACH substance restrictions and ECHA allergen disclosure mandates are compressing formulation flexibility while simultaneously rewarding certified clean-label producers with pharmacy-channel access in Germany and France.
Growth Catalysts
- Clean-label certification:BDIH and NaTrue standards in Germany unlock pharmacy distribution premiums. Natural cosmetics certification now functions as a gatekeeper to institutional procurement channels.
- Self-care routine institutionalization:Premium spa and wellness centers in the United States are expanding bath oil procurement as affluent consumers integrate therapeutic bathing into preventive health regimens.
- Plant-based emollient substitution:The EU Green Deal's chemical sustainability targets are pressuring reformulation away from petrochemical-derived ingredients toward cold-pressed carrier oils.
Market Restraints
- Raw material concentration:Sweet almond and jojoba oil supply concentrates in California and Argentina, exposing processors to climate-driven harvest volatility and price spikes.
- Compliance cost escalation:FDA cosmetic labeling rules and REACH registration fees are elevating fixed costs disproportionately for small-batch artisan producers.
- Waterless formulation substitution:Solid bath oil bars and shower oil concentrates are capturing shelf space in mass retail, threatening traditional liquid format volume.
Strategic Opportunities
- Dermatological endorsement channel:Patch-testing certification and clinician recommendation programs in France and Germany command 40-60% price premiums over general wellness positioning.
- Direct-to-consumer platform control:Subscription models bypass traditional retail markups while capturing recurring revenue and first-party consumption data.
- Therapeutic muscle recovery positioning:Sports medicine and physical therapy channels represent underpenetrated professional endorsement pathways for menthol and arnica-infused formulations.
Industry Challenges
- Stability testing capacity:Emulsion performance validation in heated water requires specialized equipment and trained formulation chemists that mid-tier producers struggle to retain.
- Cross-border labeling harmonization:Divergent FDA, REACH, and Health Canada disclosure requirements force SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bath Oil Market |
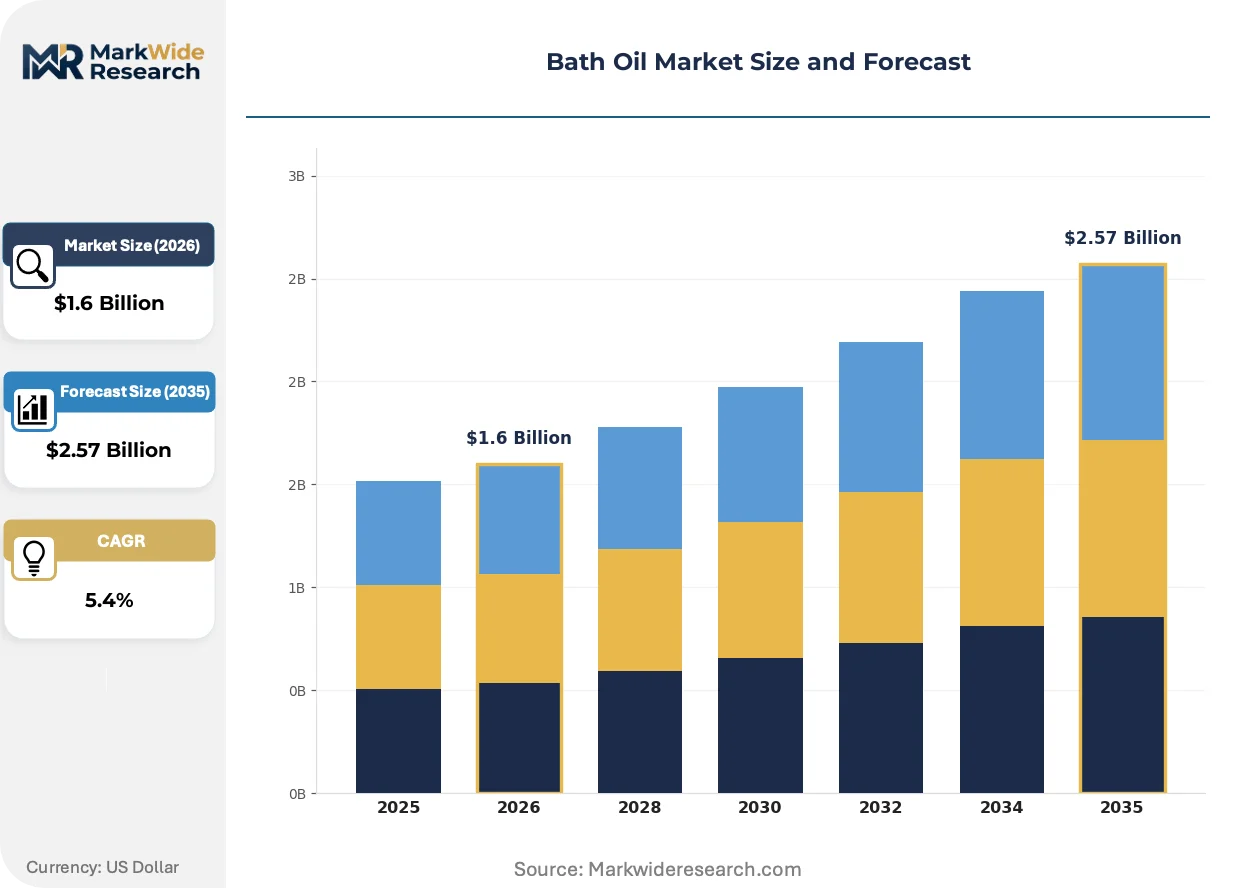
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatherapy, Moisturizing, Therapeutic, Conditioning Ingredient Type: Natural Oils, Essential Oils, Synthetic Oils, Botanical Extracts Package Size: Small Bottles, Medium Bottles, Bulk Containers, Samples Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Stores |
| Companies Covered | Hempz, Neals Yard Remedies, Estee Lauder, Viva Naturals, Burt's Bees, Dr. Teals, Shea Moisture, AG Organica, Avon Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bath Oil Market Emerging Trajectories
Formulation science, compliance architecture, and channel economics are converging to reward vertically controlled producers while marginalizing undifferentiated commodity suppliers.
Near-infrared spectroscopy is digitizing raw material authentication at the ingredient intake stage. Large contract manufacturers in Germany and the United States are deploying portable NIR devices to verify cold-pressed oil integrity without laboratory latency. This technology is digitizing quality assurance workflows, compressing batch release timelines from days to hours while reducing adulteration risk.
REACH substance restrictions are tightening emulsifier approval lists and mandating extended safety data sheets. The European Chemicals Agency's 2024 updates to skin sensitization testing protocols are forcing reformulation of legacy PEG-based dispersants. Specialty chemical suppliers in the Netherlands and Switzerland are accelerating bio-based surfactant R&D to secure pre-registration dossier advantages.
Subscription-based replenishment is displacing episodic retail purchasing among core users. Direct-to-consumer platforms in the United States and United Kingdom are bundling personalized scent profiling with automated delivery schedules. This pattern concentrates lifetime value capture with platform owners while eroding brand loyalty to traditional retail shelf placement.
Bath Oil Market Segmentation
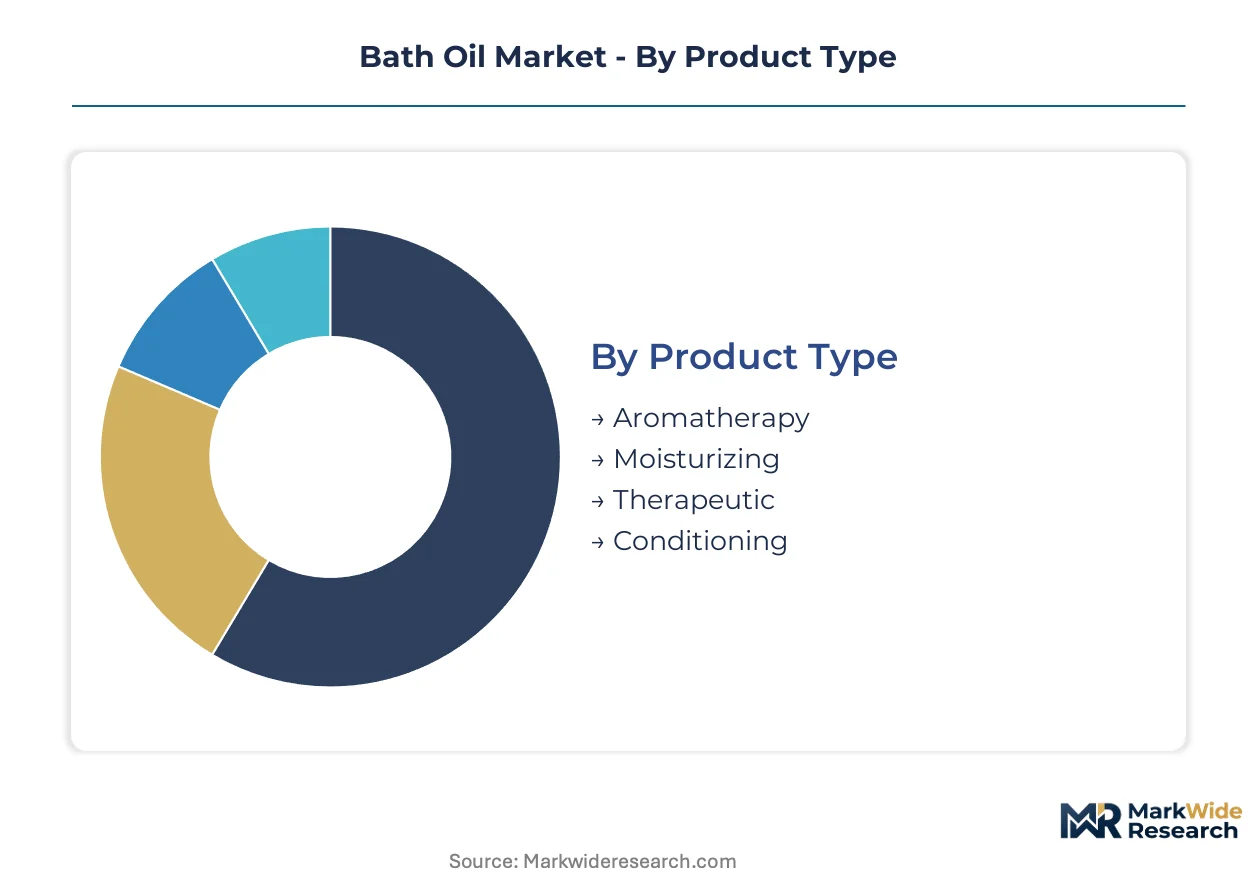
Bath oil segmentation reveals how formulation science, procurement behavior, and channel economics fragment commercial opportunity. Understanding these divides exposes where margin concentrates and which specifications command premium positioning.
Product Type:
Mature dual-function segments dominate revenue while emerging therapeutic applications capture professional endorsement premiums.
- Moisturizing:Lipid-rich carrier oil formulations—blending sweet almond, jojoba, or fractionated coconut—deliver emollient benefits through heated water dispersion. Demand concentrates in premium spa and wellness centers across the United States as affluent consumers institutionalize preventive skin health routines. This segment anchors volume through repeat purchase frequency and broad demographic accessibility.
- Aromatherapy:Volatile compound formulations leverage essential oil integrity preserved via cold-pressing or solvent-free extraction, designed for olfactory-triggered relaxation response. German pharmacy channels reward this positioning with shelf space premiums under BDIH and NaTrue certification standards. The segment benefits from cross-selling with diffuser hardware and sleep hygiene product ecosystems.
- Therapeutic:Functional formulations targeting muscle recovery through menthol, arnica, or magnesium infusion, positioned for sports medicine and physical therapy channel penetration.
- Conditioning:Hair and skin dual-purpose blends emphasizing cuticle softening and scalp treatment, prevalent in salon professional supply chains.
Moisturizing retains volume leadership; therapeutic holds the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates certified clean-label inputs from commodity synthetics, with pharmacy access gating premium tiers.
- Natural Oils:Cold-pressed carrier oils—sweet almond, jojoba, grapeseed—subject to climate-driven harvest volatility from California and Argentina production zones. EU Green Deal chemical sustainability targets are accelerating substitution away from petrochemical-derived emollients toward these plant-based alternatives.
- Essential Oils:Concentrated volatile aromatic compounds requiring batch-specific chromatographic verification; lavender, eucalyptus, and chamomile dominate procurement volumes.
- Synthetic Oils:Mineral oil and silicone-derived emollients maintaining mass-market price competitiveness through supply scale and formulation stability.
- Botanical Extracts:Standardized plant actives—calendula, green tea, oat kernel—positioned for dermatological endorsement and patch-testing certification premiums.
Natural oils command the pricing ceiling; botanical extracts are climbing fastest on clinician recommendation channel expansion.
Package Size:
Volume concentration patterns reflect channel-specific consumption rituals and trial-to-loyalty conversion economics.
- Small Bottles:100-250ml formats dominating specialty store and health store impulse purchase occasions; subscription platforms use these as entry-tier acquisition tools.
- Medium Bottles:500ml standard for core user replenishment, the workhorse format capturing recurring revenue in direct-to-consumer channels.
- Bulk Containers:5L+ professional sizes supplying spa and wellness center institutional procurement; this format concentrates lifetime value with platform owners through contracted replenishment schedules.
- Samples:Single-use sachets and travel minis deployed for scent profiling data capture and subscription conversion funnel optimization.
Medium bottles retain volume leadership; bulk containers hold the steepest expansion curve on institutional procurement growth.
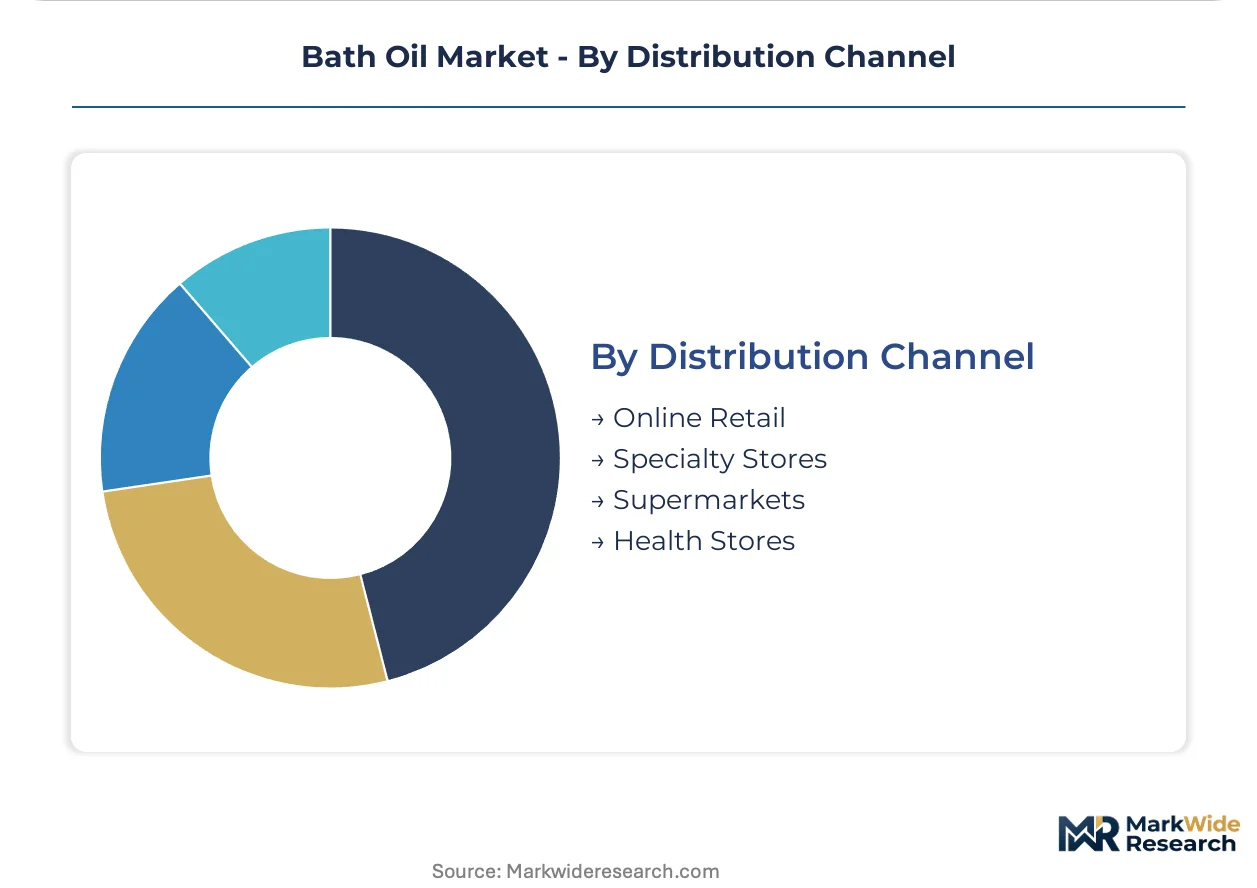
Distribution Channel:
Customer type fragmentation splits between digitally native subscription adopters and certification-dependent physical retail loyalists.
- Online Retail:Direct-to-consumer platforms bypassing traditional retail markups through subscription bundling and automated replenishment; first-party consumption data enables personalized scent profiling and lifetime value concentration.
- Specialty Stores:Curated beauty and wellness retailers where shelf space allocation rewards brand storytelling and ingredient transparency credentials.
- Supermarkets:Mass-market volume channel where synthetic oil formulations compete on price-per-ounce metrics and promotional placement.
- Health Stores:Pharmacy-adjacent positioning in Germany and France where BDIH, NaTrue, and ECOCERT certifications function as procurement gatekeepers to premium consumer segments.
Health stores retain margin leadership; online retail holds the steepest expansion curve on subscription model displacement of episodic purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH substance restrictions and FDA cosmetic labeling rules are compressing formulation flexibility while rewarding certified clean-label producers with pharmacy-channel access across developed markets.
United States
Premium spa and wellness centers in California and New York are expanding institutional procurement as affluent consumers integrate therapeutic bathing into preventive health regimens. FDA cosmetic labeling requirements mandate expanded ingredient disclosure, elevating compliance costs for small-batch producers. Manufacturing clusters in New Jersey and California concentrate cold-pressed extraction capacity serving direct-to-consumer subscription platforms.
Germany
Pharmacy-channel distribution creates premium positioning advantages for BDIH and NaTrue certified formulations in Berlin and Munich metropolitan markets. ECHA allergen disclosure mandates under REACH are forcing reformulation of legacy emulsifiers toward bio-based alternatives. The Baden-Württemberg region hosts specialty chemical suppliers accelerating plant-based surfactant R&D for pre-registration dossier advantages.
United Kingdom
Health store retail chains in London and Southeast England reward ingredient transparency credentials with curated shelf space allocation. Post-Brexit regulatory divergence from EU REACH creates parallel compliance obligations for cross-border suppliers. Subscription platform operators in Manchester and Bristol concentrate first-party consumption data capture through automated replenishment bundling.
France
Dermatological endorsement channels in Paris and Lyon command 40-60% price premiums for patch-testing certified formulations. ANSM oversight of cosmetic safety dossiers maintains stringent documentation requirements for therapeutic positioning claims. The Provence-Alpes-Côte d'Azur region anchors essential oil cultivation clusters supplying volatile compound inputs to premium blenders.
Japan
Specialty beauty retailers in Tokyo and Osaka metropolitan areas emphasize ritualized bathing culture integration for aromatherapy product lines. METI chemical management frameworks govern substance notification requirements for imported cosmetic ingredients. The Kansai region concentrates formulation R&D facilities serving clinical recommendation channel expansion for therapeutic muscle recovery positioning.
Bath Oil Market Vendor Landscape
On the supply side, the industry is fragmented across asset-light contract manufacturers, vertically integrated beauty conglomerates, and direct-to-consumer specialists. Tiered competitive positioning separates pharmacy-certified premium players from mass-market synthetic formulators. Three strategic archetypes dominate: integrated supply chain controllers leveraging multi-continent ingredient sourcing, natural positioning specialists commanding health store shelf space, and platform-native operators capturing subscription recurring revenue. Dominant competitive moves include dermatological certification acquisition for professional channel access and direct-to-consumer platform buildout bypassing traditional retail markups.
Within the integrated conglomerate tier, Estee Lauder exemplifies supply chain control spanning premium ingredient sourcing across multiple continents. Among natural positioning specialists, Burt's Bees and Neal's Yard Remedies occupy positions anchored through specialized clean-label credentials that unlock pharmacy and health store distribution premiums. At the platform-native vector, Viva Naturals represents direct-to-consumer channel control that captures first-party data and recurring revenue streams outside traditional retail structures.
| Leading Market Players |
|---|
| Hempz |
| Neals Yard Remedies |
| Estee Lauder |
| Viva Naturals |
| Burt's Bees |
| Dr. Teals |
| Shea Moisture |
| AG Organica |
| Avon Products |
| Others |
Supply Flow & Price Mechanics
Sweet almond and jojoba oil harvests in California and Argentina concentrate upstream supply, anchoring margin capture with processors who secure multi-year contracts with wellness center procurement teams. REACH compliance costs and FDA labeling requirements feed downstream into tiered pricing spreads that separate pharmacy-certified formulations from mass-market synthetics.
Pricing Analysis
Certification level under BDIH, NaTrue, and ECOCERT standards creates the primary spread between pharmacy-channel premiums and supermarket price-per-ounce competition. Three-tier pricing structure across certified premium, standard natural, and synthetic economy levels reflects ingredient grade, dermatological endorsement, and volume commitment. Cost compression in the synthetic tier is intensifying because waterless solid bar substitutes capture mass retail shelf space. Mass-market consumers show highest price sensitivity; spa and wellness procurement teams accept 40-60% premiums for patch-tested, clinician-recommended positioning.
Supply Chain Analysis
EU REACH substance restrictions and ECHA allergen disclosure mandates function as de facto export controls limiting legacy emulsifier flows into European formulation facilities. Cold-pressed carrier oil supply draws from California, Argentina, and Provence cultivation clusters; essential oil distillation rests on lavender and eucalyptus harvests in France and Australia. Single-source vulnerability concentrates in climate-exposed almond orchards. Distribution runs through direct-to-consumer subscription platforms, German pharmacy networks, and health store retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Therapeutic muscle recovery positioning in sports medicine channels represents early-cycle expansion tailwind as preventive health routines institutionalize among affluent consumers.
For Market Incumbents: Harden pharmacy-channel positioning through accelerated BDIH and NaTrue certification acquisition before ECHA emulsifier restrictions tighten. Deepen backward integration into cold-pressed oil sourcing across multiple cultivation zones to buffer climate-driven harvest volatility. Counter waterless formulation substitution threat by launching concentrated oil formats with comparable sustainability credentials. For New Entrants and Emerging Players: Mid-tier therapeutic formulations for physical therapy and sports medicine channels in France and Germany represent the most penetrable entry point given clinician recommendation premiums and underdeveloped competitive density. Direct-to-consumer subscription bundling with personalized scent profiling offers the cleanest go-to-market angle for first-party data capture and recurring revenue anchoring. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers possessing stability testing capacity and REACH pre-registration dossiers. Five-to-ten year viability hinges on clean-label certification moats and subscription platform ownership rather than retail shelf dependency. Watch dermatological endorsement program expansion rates as the inflection signal for professional channel premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | BDIH and NaTrue credentials unlock pharmacy distribution premiums in Berlin and Munich metropolitan markets. |
| Direct-to-Consumer Platform Buildout | Subscription bundling captures recurring revenue and first-party consumption data outside traditional retail markups. |
| Therapeutic Positioning Expansion | Menthol and arnica-infused formulations penetrate sports medicine channels in Paris and Lyon clinical networks. |
| Backward Integration into Sourcing | Multi-continent cold-pressed oil supply hedges climate volatility in California and Argentina harvest zones. |
| Stability Testing Capacity Addition | Specialized emulsion validation equipment retains formulation chemists and accelerates batch release timelines. |
Methodological Framework
Cross-validation between formulation chemist interviews and customs trade data anchors the qualitative findings on raw material sourcing patterns. Primary discussions with spa procurement directors, pharmacy category managers, contract manufacturing executives, and dermatological testing laboratory heads combined with secondary validation against ECHA substance restriction updates, FDA cosmetic labeling guidance, and EU Green Deal chemical sustainability targets. Bottom-up volume modeling triangulates against top-down category spend estimates.
Calibration against historical certification adoption curves and channel shift patterns shapes the analytical framework across the analysis window. Segmentation dimensions include product type, ingredient category, package size tier, and distribution channel. CAGRs derive from regression against preventive health expenditure trends and wellness center institutional procurement growth. Forecast inputs incorporate REACH emulsifier approval timelines and subscription platform penetration rates.
Macroeconomic conditions sit as an overlay; deviation in discretionary wellness spending or almond oil commodity prices would shift the trajectory. Material shifts in ECHA skin sensitization testing protocols or FDA labeling rule enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Male Grooming Products Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
Anti-Aging Cosmetics Market
Beauty & Personal Care
Refillable Deodorants Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Europe Cosmetics Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market