
 Hair Gel Market | 2026-2036
Hair Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Gel Market Analysis
Travel-size bundling with complementary styling products is shifting buyer choice toward curated kits rather than standalone purchases. L'Oréal S.A. leverages its salon distribution network to anchor professional-grade gel lines in premium channels. Unilever PLC sustains mass-market penetration through dense retail placement and value-tier positioning. Henkel AG & Co. KGaA differentiates via Schwarzkopf-branded technical formulations targeting heat-styling professionals.
Hair gel denotes a viscous, polymer-thickened styling preparation typically comprising carbomer or PVP resins suspended in aqueous or alcoholic bases, designed to confer temporary hold, texture definition, and humidity resistance to keratinous fibers. Water-based formulations lead volume sales due to consumer preference for non-flaking, easy-rinse properties, while organic segments capture expanding margin pools as clean-label claims penetrate mainstream retail. Clay-based variants register the fastest growth trajectory among product types, fueled by matte-finish demand from male grooming cohorts seeking reworkable hold without synthetic shine.
REACH restrictions on volatile organic compounds constrain alcohol-based formulation strategies across European manufacturing sites, while FDA cosmetic labeling requirements mandate ingredient transparency that elevates compliance costs for imported gel products. The U.S. Environmental Protection Agency oversees VOC emissions from aerosolized styling adjuncts, indirectly pressuring gel producers to reformulate companion product lines. ISO 16128 guidelines on natural and organic cosmetic ingredients increasingly shape raw material sourcing criteria for multinational brand portfolios. Stakeholders must monitor evolving state-level chemical disclosure laws and ingredient blacklist expansions to preempt reformulation cycles and secure shelf access.
Market Dynamics
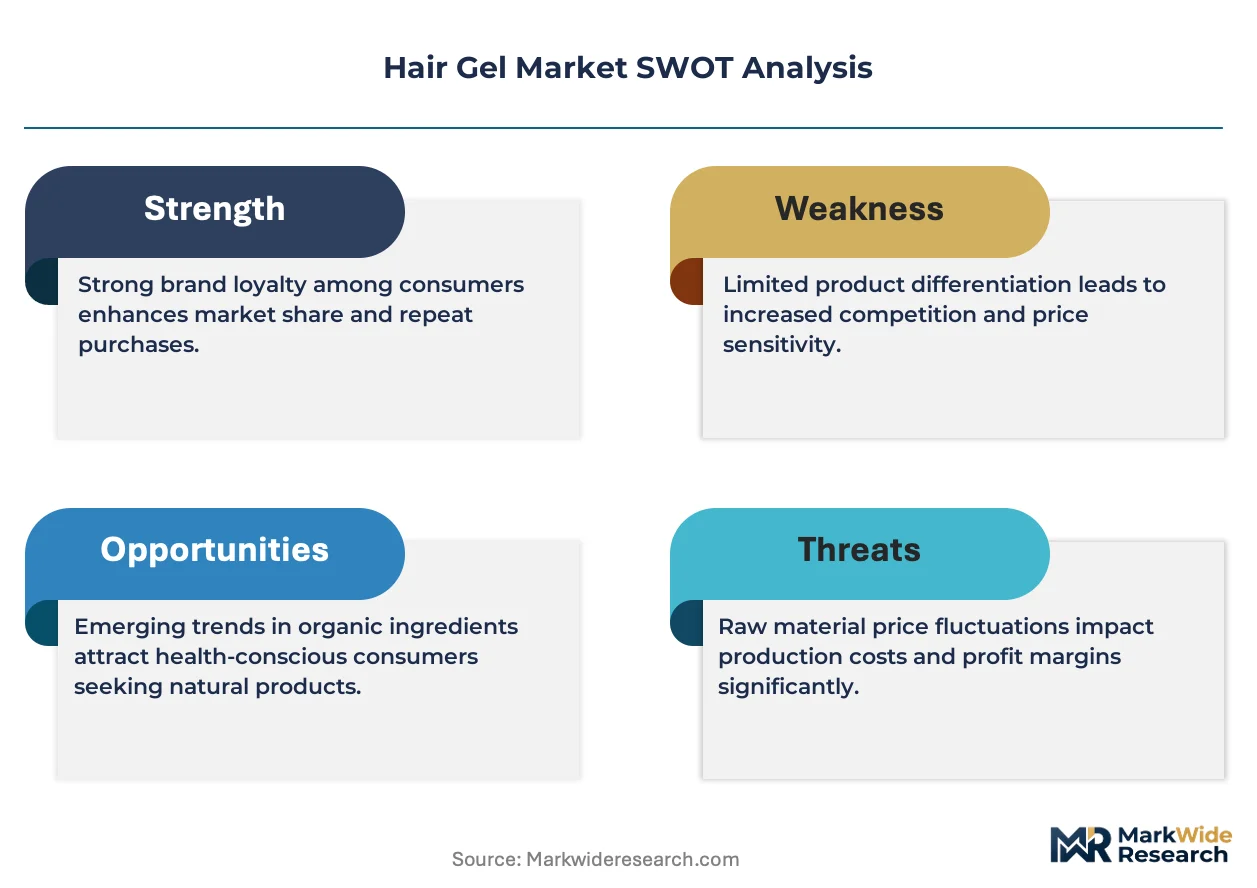
Professional salon channels and ingredient-conscious consumers are bifurcating formulation strategies, forcing manufacturers to maintain dual pipelines for carbomer-based performance gels and clean-label organic alternatives.
Growth Catalysts
- REACH VOC restrictions:Alcohol-based reformulation mandates in European manufacturing are accelerating water-based polymer innovation and expanding compliant SKU portfolios.
- Heat-styling professionals:Salon technicians demand humidity-resistant, reworkable hold properties that command recurring bulk procurement and brand loyalty.
- Clay-based matte finishes:Male grooming cohorts in urban United States and German metropolitan markets are shifting volume toward reworkable, shine-free styling textures.
Market Restraints
- Carbomer supply concentration:Specialty polymer production clusters in Chinese coastal provinces create input vulnerability for aqueous formulation lines.
- FDA cosmetic labeling compliance:Expanded ingredient disclosure requirements elevate documentation costs for imported gel products entering United States distribution.
- Natural wax substitutes:Plant-derived styling balms and pomades are capturing hold-seeking consumers averse to synthetic polymer residues.
Strategic Opportunities
- Travel-size curation:Bundled styling kits combining gel, mousse, and finishing spray are displacing standalone purchases in airport retail and e-commerce subscription channels.
- ISO 16128 natural sourcing:Standardized organic ingredient certification is opening premium shelf placement in German and Japanese department store beauty halls.
- United States state-level chemical disclosure laws:Early compliance with California and New York ingredient blacklist expansions secures preemptive market access ahead of federal harmonization.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise bridging cosmetic science and sustainable raw material integration commands premium compensation and extended hiring cycles.
- Dual-line manufacturing capex:Parallel production infrastructure for conventional and clean-label gels strains capital allocation across mid-tier manufacturers.
- REACH pre-registration timelines:Extended safety data submission windows for novel bio-based thickeners delay European market entry by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Gel Market |
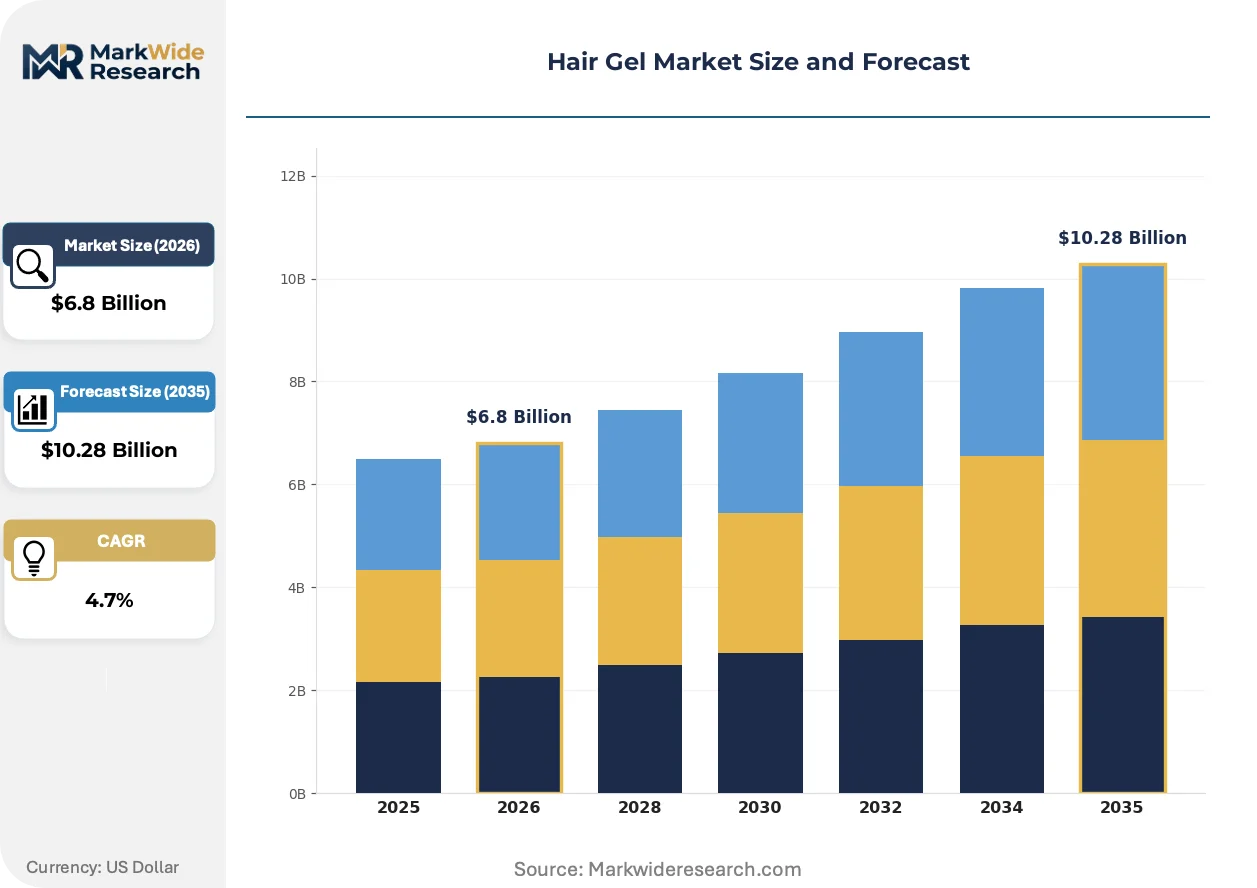
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Alcohol-Based, Silicone-Based, Clay-Based, Organic Application: Styling, Curl Defining, Hair Straightening, Volume Boosting, Scalp Treatment End User: Salons, Professional Stylists, Retail Consumers, Beauty Clinics, Fashion Studios Packaging Type: Tubes, Jars, Bottles, Pump Dispensers, Sachets |
| Companies Covered | L'Oréal S.A., Unilever PLC, The Procter & Gamble Company, Henkel AG & Co. KGaA, The Estée Lauder Companies Inc., Coty Inc., Revlon, Inc., Kao Corporation, Shiseido Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Gel Market Emerging Trajectories
Formulation chemistry and distribution architecture are undergoing simultaneous transformation as water-based polymers displace alcohol carriers and curated product bundles reshape purchase behavior.
Hydrolyzed wheat protein and plant-derived film formers are expanding into professional-grade styling preparations. Salon distributors in Germany and Japan are adopting these bio-based alternatives at accelerating pace to satisfy clean-label procurement mandates from institutional buyers. This ingredient shift is expanding into premium price tiers previously dominated by synthetic PVP resins.
REACH restrictions on volatile organic compounds are forcing alcohol-based gel reformulation across European manufacturing sites. The regulation compresses formulation flexibility for humidity-resistant products while elevating compliance expenditure for multinational brand portfolios. Heat-styling professionals in France and Italy are responding by accepting modified hold properties in exchange for regulatory certainty.
Subscription-based replenishment programs are capturing recurring gel purchases from style-conscious male demographics. United States direct-to-consumer platforms and curated beauty boxes are displacing conventional drugstore replenishment cycles with automated delivery schedules. This channel pivot is most visible in metropolitan coastal markets where convenience positioning overrides price sensitivity.
Hair Gel Market Segmentation
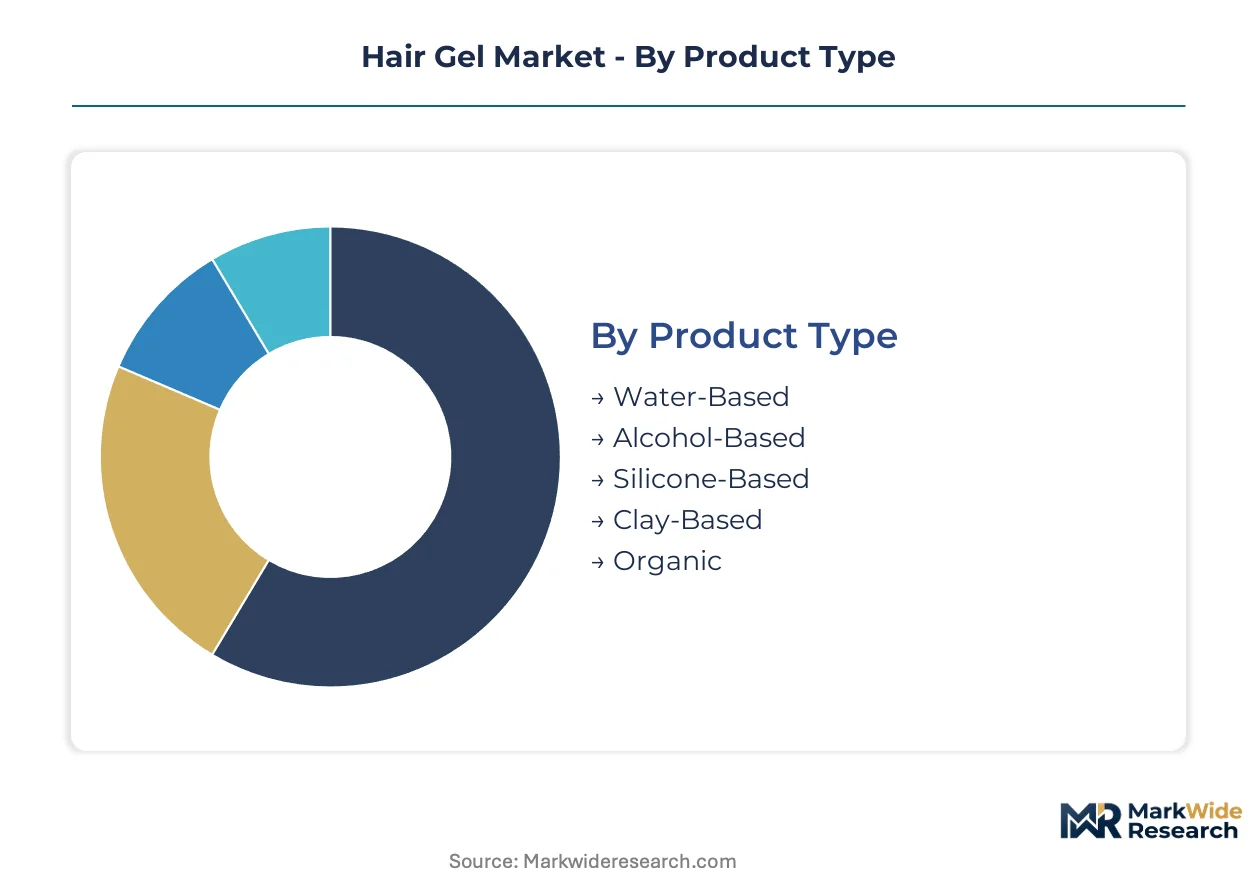
Hair gel manufacturers must navigate divergent capital requirements across formulation chemistries, packaging formats, and channel infrastructures. Segmentation reveals where equipment investments concentrate and which product lines justify dedicated production lines versus contract manufacturing arrangements.
Product Type:
Capital intensity peaks with organic certification infrastructure and REACH-compliant aqueous polymer systems, while alcohol-based lines face stranded asset risk from regulatory phase-outs.
- Water-Based:Carbomer and PVP resin suspensions in aqueous bases dominate volume manufacturing. Demand concentrates among United States retail consumers prioritizing non-flaking, easy-rinse properties, though carbomer supply concentration in Chinese coastal provinces creates input vulnerability.
- Clay-Based:Bentonite and kaolin suspensions deliver reworkable matte finishes without synthetic shine. Male grooming cohorts in German metropolitan markets are shifting volume toward this segment, making it the fastest-expanding category by application growth.
- Alcohol-Based:Ethanol-carried formulations face reformulation mandates under REACH VOC restrictions across European manufacturing sites.
- Silicone-Based:Dimethicone and cyclomethicone variants target humidity resistance in tropical climates.
- Organic:Plant-derived film formers and hydrolyzed wheat protein preparations require certified sourcing infrastructure per ISO 16128 guidelines.
Most installed capacity flows through water-based polymer lines. Expansion is steepest in clay-based matte formulations.
Application:
Performance specifications vary sharply across use cases, with heat-styling applications demanding the most rigorous polymer engineering and scalp treatments requiring dermatological testing protocols.
- Styling:General hold and texture definition applications consume the broadest raw material base across consumer and professional channels.
- Curl Defining:Specialized polymer blends enhance coil memory and frizz control for textured hair types.
- Hair Straightening:Heat-activated formulations require thermal protection additives for flat-iron and blow-dry compatibility.
- Volume Boosting:Lightweight polymers create root lift without weight accumulation.
- Scalp Treatment:Active ingredient delivery systems incorporate salicylic acid or tea tree oil for therapeutic positioning.
Styling commands the largest production footprint. Scalp treatment applications are climbing fastest as therapeutic claims penetrate mainstream retail.
End User:
Channel economics bifurcate between bulk procurement relationships with institutional buyers and fragmented replenishment patterns among individual consumers.
- Salons:Institutional procurement of professional-grade formulations operates on quarterly replenishment cycles with negotiated volume discounts.
- Professional Stylists:Independent technicians demand humidity-resistant, reworkable hold properties that command recurring bulk procurement and brand loyalty.
- Retail Consumers:Drugstore and e-commerce purchasers drive the highest SKU proliferation and packaging variety requirements.
- Beauty Clinics:Medical-aesthetic channels prioritize dermatologically tested formulations with minimal irritant profiles.
- Fashion Studios:Editorial and runway applications demand extreme-hold variants with rapid-dry properties for time-pressured styling environments.
Salon channels anchor the most stable demand base. Professional stylists are gaining share fastest as independent contractor models expand.
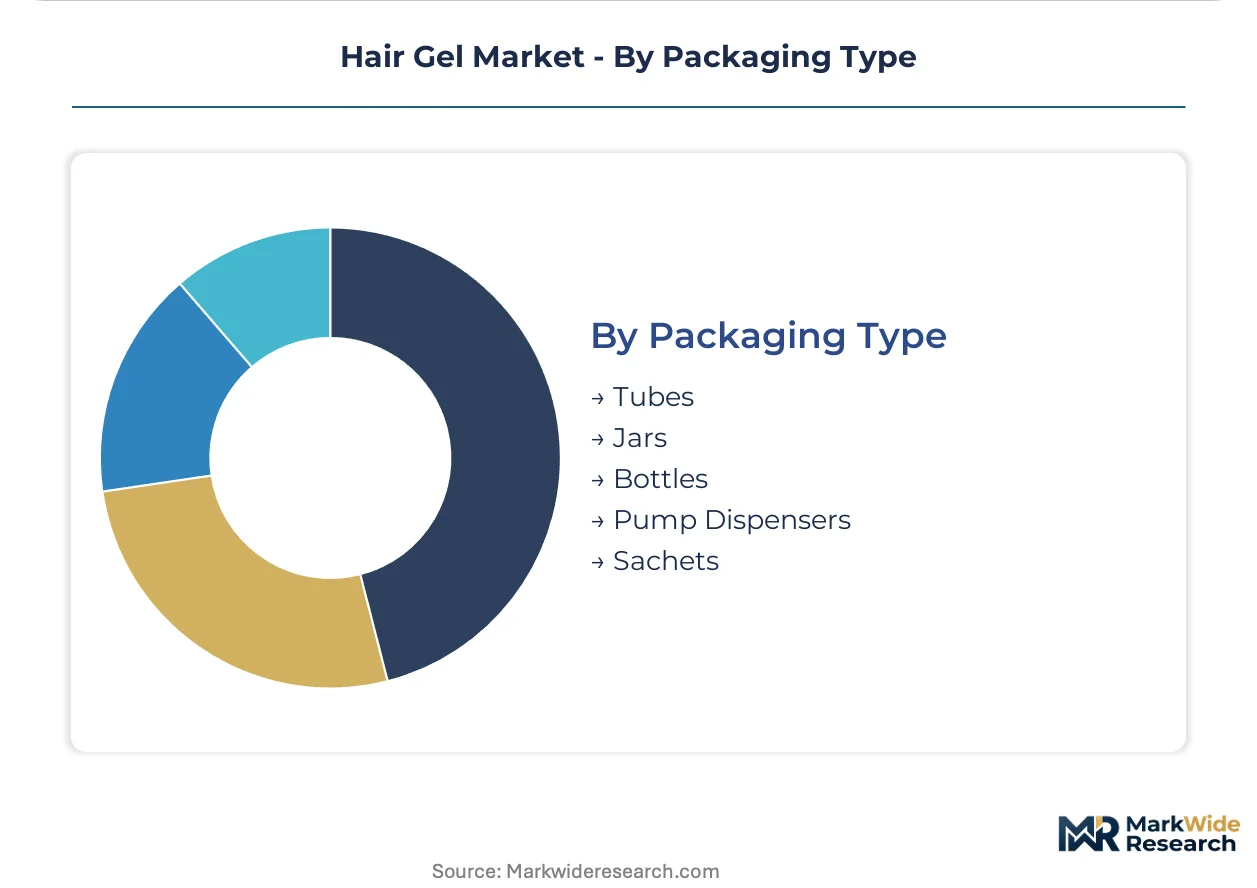
Packaging Type:
Format selection determines filling line configuration, with airless pump systems requiring the most specialized equipment investment.
- Tubes:Collapsible aluminum and laminate structures dominate mass-market travel and standard sizes.
- Jars:Wide-mouth containers suit clay-based and pomade-adjacent textures requiring finger-scoop application.
- Bottles:Standard cylindrical formats accommodate the broadest viscosity range across squeeze and flip-cap closures.
- Pump Dispensers:Airless systems prevent oxidation of organic formulations but require dedicated filling infrastructure.
- Sachets:Single-use foil pouches serve sampling programs and emerging market price-sensitive entry points.
Tubes and bottles together account for the majority of filling line capacity. Pump dispensers are expanding most quickly as premium positioning accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hair gel formulation science originated in mid-20th century United States salon culture, where polymer chemistry first met consumer styling demand. The industry later diffused through European professional channels and Japanese precision manufacturing before establishing concentrated production footprints across three continents.
United States
California and New York Metro drive premium styling demand through celebrity-influenced salon culture and direct-to-consumer platform adoption. FDA cosmetic labeling requirements mandate expanded ingredient disclosure, elevating compliance costs for imported formulations. The Pacific Northwest hosts emerging clean-label manufacturing clusters serving ISO 16128-certified organic lines.
Germany
Professional salon channels in Bavaria and North Rhine-Westphalia anchor European demand for humidity-resistant technical formulations. REACH VOC restrictions compel alcohol-based reformulation across manufacturing sites in Baden-Württemberg. The Hamburg beauty distribution corridor channels German-produced gels into Scandinavian and Eastern European markets.
Japan
Tokyo and Osaka metropolitan markets sustain loyalty to premium styling segments with exacting performance specifications. METI guidelines on chemical substance management shape raw material sourcing criteria for domestic formulators. The Kansai industrial belt concentrates precision polymer processing infrastructure serving Asian export markets.
China
Carbomer supply concentration in Zhejiang and Jiangsu coastal provinces creates input vulnerability for aqueous formulation lines serving domestic and export demand. SAMR cosmetic registration requirements extend approval timelines for novel bio-based thickeners. The Yangtze River Delta hosts contract manufacturing clusters supplying multinational brand portfolios.
Brazil
São Paulo and Rio de Janeiro metropolitan markets drive Latin American volume through mass-market retail penetration and professional salon expansion. ANVISA cosmetic regulation harmonizes ingredient standards with Mercosur trading partners. The Southeast industrial corridor hosts formulation facilities serving price-sensitive emerging market tiers.
Hair Gel Market Vendor Landscape
The competitive structure tilts toward multinational conglomerates with dual-channel presence across professional salon and mass retail infrastructures. Market concentration remains moderate, with tier-one players commanding shelf access through dense distribution networks while mid-tier specialists occupy niche formulation segments. Two strategic archetypes dominate: diversified beauty conglomerates leveraging portfolio cross-selling, and technical specialists anchoring professional-grade credibility. Primary competitive moves center on clean-label certification acquisition and salon-exclusive line extensions.
Within the diversified conglomerate tier, L'Oréal S.A. and Unilever PLC exemplify scale-driven positioning across multiple price tiers and channel configurations. Henkel AG & Co. KGaA occupies a specialist position through technical formulation credibility anchored in professional styling channels. These three entities collectively represent the spectrum from mass-market density to salon-grade precision, with each archetype defending distinct procurement relationships and formulation pipelines.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever PLC |
| The Procter & Gamble Company |
| Henkel AG & Co. KGaA |
| The Estée Lauder Companies Inc. |
| Coty Inc. |
| Revlon, Inc. |
| Kao Corporation |
| Shiseido Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ISO 16128-compliant organic formulations and conventional carbomer-based gels manifests in divergent pricing power and supply chain configurations. Premium organic tiers command sustained margin pools through certified sourcing infrastructure, while commodity aqueous lines face cost compression from carbomer supply concentration in Chinese coastal provinces.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates salon-exclusive professional lines from mass-market retail SKUs and private-label contract manufacturing. Price differentiation hinges on ISO 16128 certification grade and volume procurement scale, with institutional salon buyers negotiating quarterly rebates unavailable to fragmented retail consumers. Pricing pressure stems from REACH compliance costs elevating European manufacturing overhead, while independent professional stylists demonstrate lowest price sensitivity due to performance-driven procurement criteria.
Supply Chain Analysis
Reverse-logistics flows for pump dispenser components and aluminum tube returns remain underdeveloped in hair gel distribution, creating stranded packaging value and regulatory exposure under extended producer responsibility frameworks. Raw material sourcing draws from carbomer production clusters in China, bentonite clay deposits in the United States, and hydrolyzed wheat protein processors in Germany. Single-source vulnerability concentrates in Zhejiang province carbomer supply. Distribution runs through salon distribution networks in Germany, direct-to-consumer platforms in the United States, and department store beauty halls in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between REACH-constrained European manufacturing and lower-compliance Asian production bases offers cost differential capture for portfolio rebalancing. Regulatory divergence between ECHA enforcement intensity and SAMR registration timelines creates relocation incentives.
For Market Incumbents: Acquire certified organic formulation facilities to preempt clean-label shelf displacement. Defensive consolidation should prioritize ISO 16128-accredited production assets in Germany and Japan, while backward integration into carbomer supply hedges Chinese coastal concentration risk. Channel control through exclusive salon distribution agreements in Bavaria and North Rhine-Westphalia anchors professional-grade pricing power against mass-market erosion.
For New Entrants and Emerging Players: Independent professional stylists operating outside institutional salon procurement represent the most penetrable buyer archetype. White-space concentration appears in clay-based matte formulations for male grooming cohorts in German metropolitan markets and subscription-based replenishment platforms in United States coastal cities. Direct-to-consumer launch with automated delivery scheduling bypasses incumbent retail shelf dominance.
For Investors and Strategic Acquirers: Asymmetric upside sits with technical specialists possessing dual formulation pipelines for conventional and clean-label gels. Long-term viability over the projection horizon favors manufacturers with REACH pre-registration capabilities and established salon channel relationships. Watch California and New York state-level chemical disclosure law expansions as inflection indicators for compliance-cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 16128 Certification Acquisition | Opens premium shelf placement in German and Japanese department store beauty halls. |
| Backward Integration into Carbomer Supply | Reduces input vulnerability from Chinese coastal province concentration. |
| Salon Distribution Network Expansion | Secures institutional procurement relationships with quarterly replenishment cycles. |
| Direct-to-Consumer Platform Launch | Captures recurring male grooming replenishment through automated subscription scheduling. |
| REACH-Compliant Reformulation Investment | Maintains European market access as VOC restrictions phase out alcohol-based lines. |
Methodological Framework
Bottom-up salon and retail channel modeling reconciled against top-down polymer supply and formulation capacity tracking forms the analytical core. Primary interviews with professional stylists, salon procurement managers, cosmetic chemists, and beauty retail category buyers combined with secondary validation from ECHA REACH registration databases, FDA cosmetic labeling guidance documents, and ISO 16128 certification registries. Trade flow analysis from customs records and salon distributor sales data provided cross-reference points for volume reconciliation.
Historical trendline analysis of formulation chemistry shifts and channel migration patterns established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type chemistry, packaging format, end-user channel, and regional regulatory cluster. CAGRs were derived from volume-weighted average growth across compliant and non-compliant formulation pipelines, incorporating polymer innovation cycle timing and salon channel expansion rates as industry-specific forecast inputs.
Underlying measurement precision varies by segment; professional salon channels carry tighter precision than fragmented retail consumer estimates due to concentrated procurement visibility. Forecasts incorporate assumptions regarding REACH enforcement consistency and state-level chemical disclosure harmonization timelines. Practitioners should monitor ECHA substance restriction proposals and California Proposition 65 expansions for early signals of compliance-cost acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Personalized Beauty Devices Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Natural Deodorant Crystal Market
Beauty & Personal Care
North America Hair Conditioner Market