
 Beauty and Wellness Products Market | 2026-2036
Beauty and Wellness Products Market Size, Share, and Industry Trends Forecast 2026-2036
Beauty and Wellness Products Market Analytics
Korean contract manufacturing capacity is hardening as a supply-side constraint across color cosmetics and advanced skincare. L'Oréal S.A. leverages its Incheon-based R&D campus to anchor regional innovation pipelines. Shiseido Co., Ltd. competes through specialized biotech fermentation processes for active ingredients. Unilever Plc. extends its sustainability credentials via in-house natural extraction capabilities.
Beauty and wellness products encompass topical and ingestible formulations designed for skin health, hair maintenance, aesthetic enhancement, and physical wellbeing, typically incorporating active compounds at concentrations between 0.5% and 15% depending on regulatory thresholds and intended function. These products serve consumer self-care routines, professional salon services, and clinical dermatology applications through varied delivery mechanisms including emulsions, serums, powders, and solid formats. Skincare and haircare dominate current value pools due to higher purchase frequency and premiumization potential across age demographics. Organic and natural formulation segments are capturing disproportionate margin expansion as clean-label preferences intensify in North American and European distribution channels.
FDA cosmetic registration requirements under the Modernization of Cosmetics Regulation Act, EU REACH chemical compliance overseen by ECHA, and China's NMPA safety assessment protocols collectively elevate barrier costs for new market entrants. These frameworks mandate extensive toxicological documentation, restrict specific preservative classes, and enforce post-market surveillance obligations that favor established enterprises with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving ingredient ban schedules and pre-market approval timelines to anticipate reformulation cycles and geographic launch sequencing.
Market Dynamics
Korean contract manufacturing capacity constraints are forcing multinational beauty brands to redesign their supply footprints, with fermentation-based active ingredient production emerging as the critical bottleneck reshaping competitive access to premium skincare formulations.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH Annex XVII expansions are accelerating clean-label reformulation investments, creating first-mover advantages for brands with pre-positioned natural extraction capabilities.
- Biotech fermentation processes:Microbial-derived actives are displacing petrochemical synthetics in high-performance serums, with Seoul-Incheon clusters capturing disproportionate contract manufacturing demand.
- Millennial and Gen Z prestige skincare adoption:Younger cohorts in China's tier-one cities are driving purchase frequency increases through social commerce-enabled discovery and routine complexity expansion.
Market Restraints
- Concentrated Korean manufacturing:Over 60% of advanced fermentation capacity sits within 50 kilometers of Incheon, creating single-point-of-failure exposure for global brand supply security.
- FDA MoCRA compliance costs:Facility registration and serious adverse event reporting mandates are elevating barrier costs that disproportionately burden emerging brand entrants lacking dedicated regulatory infrastructure.
- Natural ingredient input volatility:Climate-sensitive botanical supply chains for shea, argan, and centella asiatica extracts are experiencing harvest variability that compresses margin predictability for clean-label portfolios.
Strategic Opportunities
- India's underpenetrated premium tier:FSSAI cosmetic safety guidelines are harmonizing with ASEAN standards, enabling streamlined market entry for brands with existing Southeast Asian regulatory dossiers.
- China NMPA simplified filing pathways:Cross-border e-commerce regulatory exemptions for pilot zones are opening direct-to-consumer channels previously blocked by animal testing requirements.
- Biotechnology-sensor convergence:At-home skin diagnostic devices paired with personalized serum dispensing systems are creating subscription revenue models that displace traditional retail replenishment cycles.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in natural preservative stabilization and encapsulation technology commands premium compensation that strains mid-cap brand R&D budgets.
- Multi-jurisdiction dossier synchronization:Divergent EU REACH, FDA MoCRA, and China NMPA safety assessment timelines force parallel track investments that delay geographic launch sequencing.
- Legacy ERP integration with traceability systems:Batch-level ingredient provenance tracking required by EU CSRD supply chain disclosure mandates conflicts with decades-old manufacturing execution software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beauty and Wellness Products Market |
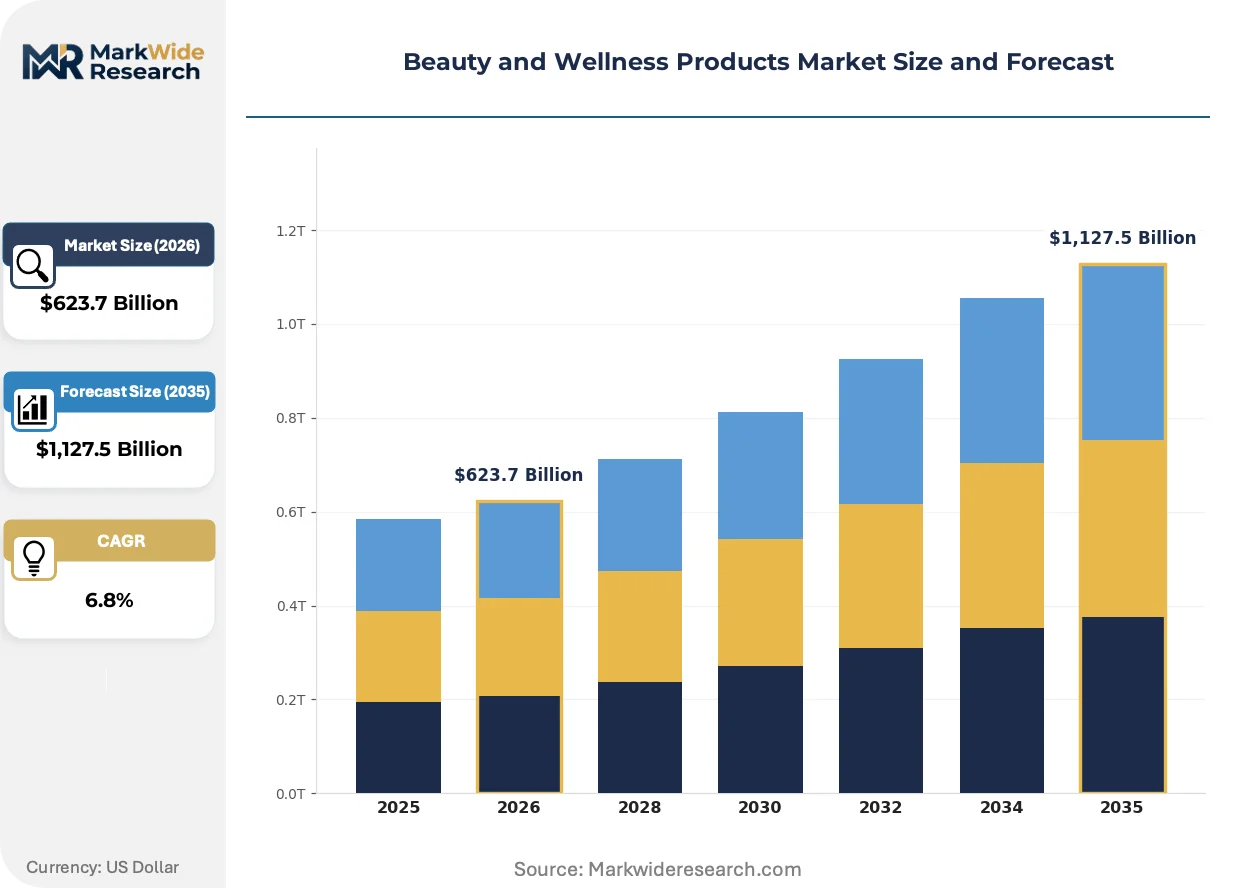
| Market Size in 2026 | $623.7 Billion |
| Market Size in 2035 | $1,127.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Age Group: Teens, Adults, Seniors, Children Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets Formulation: Organic, Natural, Chemical-based, Synthetic |
| Companies Covered | L'Oréal S.A., Unilever Plc., The Estée Lauder Companies Inc., The Procter & Gamble Company, LVMH, Beiersdorf AG, Shiseido Co., Ltd., Coty Inc., Amway Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beauty and Wellness Products Market Evolving Landscape
Active ingredient delivery mechanisms are undergoing fundamental redesign as consumer tolerance for irritation declines and efficacy thresholds rise, with biotechnology and artificial intelligence emerging as the twin engines of formulation precision.
Encapsulation technology is converging with machine learning-driven skin penetration modeling to enable time-release actives that previously required prescription-grade concentrations. Prestige brands in Seoul and Shanghai are piloting these systems for retinol and vitamin C stabilization. The structural consequence is compression of the efficacy gap between professional clinic treatments and at-home skincare routines.
ECHA's REACH microplastic restriction proposals are forcing immediate reformulation of rinse-off exfoliants and glitter-containing color cosmetics, with enforcement timelines accelerating ahead of industry preparedness. Manufacturers serving EU distribution channels are prioritizing biodegradable alternatives including cellulose beads and mineral-derived shimmer. Color cosmetics and body care categories face the steepest compliance cliffs, with several major retailers advancing their own ban deadlines ahead of regulatory mandates.
Social commerce livestreaming is displacing traditional department store counter relationships as the primary discovery and education channel for prestige skincare in China and Southeast Asia. Influencer-hosted sessions on Douyin and Xiaohongshu now drive trial conversion rates that exceed legacy retail environments by substantial margins. This behavioral shift concentrates marketing spend toward content production and KOL commission structures rather than fixed retail occupancy costs, with tier-one Chinese cities exhibiting the most pronounced channel migration velocity.
Beauty and Wellness Products Market Segmentation
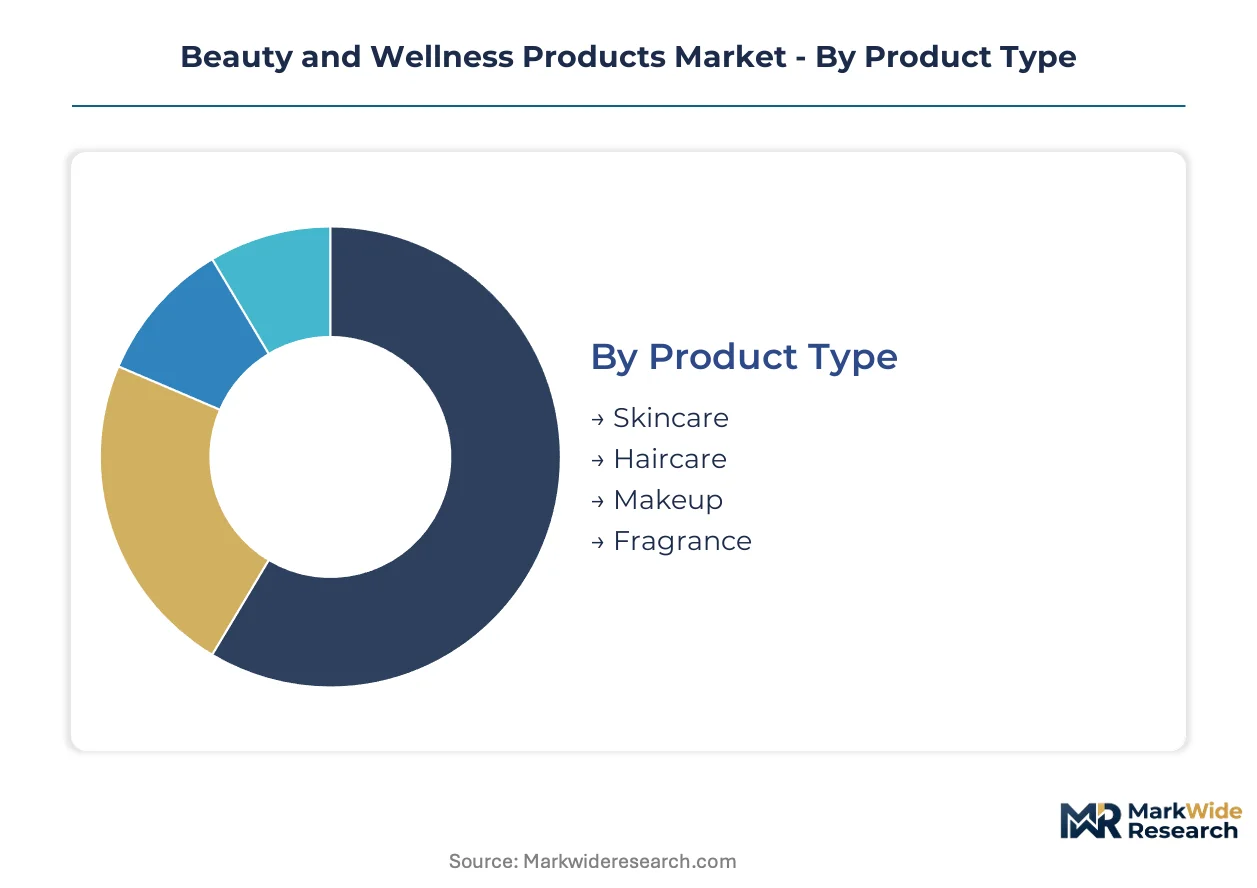
Segmentation in beauty and wellness products determines formulation investment priorities, regulatory compliance pathways, and channel-specific marketing resource allocation. Distinct consumer cohorts exhibit divergent tolerances for synthetic actives, price sensitivity, and purchase discovery mechanisms that reshape competitive positioning across the value chain.
Product Type:
Formulation complexity and active ingredient concentration thresholds differentiate manufacturing requirements and margin structures across topical and aesthetic product categories.
- Skincare:Serums and moisturizers incorporate actives at 0.5% to 15% concentrations depending on regulatory ceilings and intended dermatological function. Demand concentrates in Seoul-Incheon fermentation clusters and China's tier-one cities where prestige adoption among millennial and Gen Z consumers accelerates routine complexity expansion.
- Haircare:Shampoos, conditioners, and treatment masks balance cleansing efficacy with scalp microbiome preservation. Korean contract manufacturing capacity constraints are forcing multinational brands to redesign supply footprints for fermentation-based active ingredient production.
- Makeup:Color cosmetics require pigment dispersion stability and long-wear film-forming polymers. ECHA REACH microplastic restrictions are accelerating reformulation of glitter-containing and rinse-off exfoliant variants ahead of enforcement timelines.
- Fragrance:Fine and functional scents rely on alcohol-based delivery systems and natural extraction supply chains. Climate-sensitive botanical inputs for shea, argan, and centella asiatica extracts introduce harvest variability that compresses margin predictability.
Mature deployment sits with Skincare. Newer deployment is concentrated in Fragrance as natural extraction capabilities expand.
Age Group:
Purchase frequency, price elasticity, and channel preference diverge sharply across generational cohorts, dictating portfolio architecture and communication strategy.
- Teens:Entry-level consumers prioritize affordability and social commerce discovery. TikTok and Instagram drive trial conversion through influencer-led education, with routine simplicity favoring multi-functional formulations over complex layering systems.
- Adults:The core revenue cohort sustains premiumization through anti-aging and preventative skincare investments. China's tier-one cities exhibit the most pronounced channel migration velocity toward Douyin and Xiaohongshu livestreaming.
- Seniors:Mature skin concerns drive demand for barrier repair and gentle active delivery. Department store counter relationships retain residual importance for personalized consultation and tactile product evaluation.
- Children:Safety-first formulation requirements restrict preservative classes and fragrance loadings. FSSAI cosmetic safety guidelines in India are harmonizing with ASEAN standards to streamline market entry for clean-label portfolios.
Adults command the steepest expansion trajectory. Teens represent the emerging deployment frontier as social commerce infrastructure matures.
Distribution Channel:
Channel economics determine working capital intensity, customer acquisition cost structures, and post-purchase engagement mechanisms.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable personalized recommendation engines and subscription replenishment. China NMPA simplified filing pathways for cross-border e-commerce pilot zones are opening direct-to-consumer channels previously blocked by animal testing requirements.
- Specialty Stores:Sephora, Ulta, and regional equivalents provide curated discovery environments with trained beauty advisor support. These formats capture disproportionate prestige skincare volume through exclusive launches and loyalty program lock-in.
- Department Stores:Legacy retail environments face compression as social commerce livestreaming displaces traditional counter relationships. Fixed occupancy costs burden profitability relative to variable commission structures dominating digital channels.
- Supermarkets:Mass-market haircare and basic skincare rely on high-velocity replenishment and promotional pricing. Shelf space negotiations favor established enterprises with dedicated trade marketing infrastructure.
Department Stores anchor mature deployment. Online Retail concentrates newer deployment as regulatory exemptions expand geographic access.
Formulation:
Ingredient provenance and processing methodology determine regulatory compliance burden, consumer willingness-to-pay, and supply chain traceability requirements.
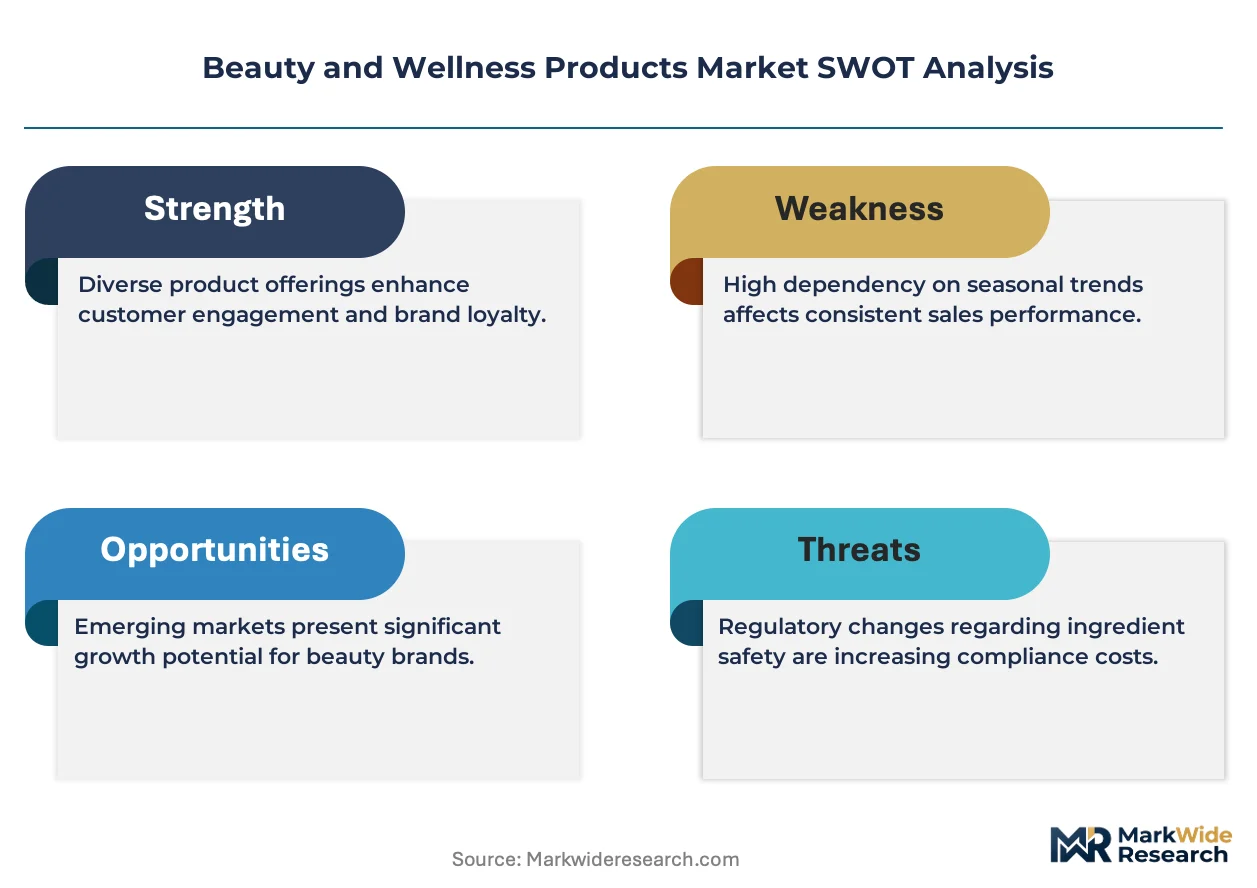
- Organic:Certified agricultural inputs meet strict cultivation and processing standards with full chain-of-custody documentation. EU Green Deal chemical restrictions are accelerating clean-label reformulation investments, creating first-mover advantages for brands with pre-positioned natural extraction capabilities.
- Natural:Botanically-derived actives without synthetic petrochemical inputs command premium positioning in North American and European distribution channels. FDA MoCRA facility registration and serious adverse event reporting mandates elevate barrier costs for emerging entrants lacking regulatory infrastructure.
- Chemical-based:Synthetic actives including retinoids, peptides, and stabilized vitamin derivatives deliver clinically-proven efficacy at accessible price points. These formulations retain dominance in professional dermatology and clinical spa applications.
- Synthetic:Petrochemically-derived base materials and preservatives offer cost efficiency and formulation stability. Biotechnology-sensor convergence in personalized dispensing systems is beginning to displace standardized synthetic SKUs in premium tiers.
Chemical-based formulations represent mature deployment. Organic and Natural segments concentrate newer deployment as clean-label preferences intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Centella asiatica harvests from Madagascar and Indonesia anchor botanical supply chains for premium skincare fermentation processes. Seoul-Incheon clusters process these inputs into active concentrates. Regulatory divergence across FDA, ECHA, and NMPA jurisdictions fragments geographic launch sequencing.
United States
Millennial prestige skincare adoption drives routine complexity expansion through social commerce discovery. FDA MoCRA facility registration mandates elevate barrier costs for emerging brand entrants lacking dedicated regulatory infrastructure. Greater New York and Los Angeles anchor premium distribution through specialty retail and direct-to-consumer platforms.
South Korea
Fermentation-based active ingredient production concentrates manufacturing gravity within 50 kilometers of Incheon. MFDS cosmetic safety assessments enforce post-market surveillance obligations favoring established enterprises with regulatory affairs infrastructure. Seoul-Incheon clusters capture disproportionate contract manufacturing demand for biotech-derived actives.
China
Tier-one city consumers exhibit the most pronounced channel migration velocity toward Douyin and Xiaohongshu livestreaming. NMPA simplified filing pathways for cross-border e-commerce pilot zones open direct-to-consumer channels previously blocked by animal testing requirements. Shanghai and Beijing concentrate prestige skincare demand through social commerce-enabled discovery.
France
Fine fragrance natural extraction capabilities command premium positioning in clean-label distribution channels. ECHA REACH Annex XVII expansions accelerate reformulation investments, creating first-mover advantages for brands with pre-positioned botanical supply chains. Paris anchors luxury beauty innovation through specialized fermentation and extraction infrastructure.
India
FSSAI cosmetic safety guidelines harmonizing with ASEAN standards enable streamlined market entry for brands with existing Southeast Asian regulatory dossiers. Climate-sensitive shea and argan harvest variability compresses margin predictability for natural formulation portfolios. Maharashtra and Karnataka concentrate emerging premium tier demand through urban middle-class expansion.
Beauty and Wellness Products Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance infrastructure and fermentation technology access. Market structure tilts toward consolidated leadership among conglomerates with dedicated regulatory affairs divisions and captive R&D campuses. Three archetypes dominate: integrated beauty conglomerates with multi-brand portfolios, specialized biotech fermenters with proprietary active platforms, and agile direct-to-consumer brands leveraging social commerce infrastructure. Competitive moves concentrate on M&A for clean-label capabilities and strategic partnerships for Korean manufacturing access.
Within the integrated conglomerate tier, L'Oréal S.A. exemplifies scale-driven regulatory navigation across FDA, ECHA, and NMPA jurisdictions. Shiseido Co., Ltd. occupies a position within the specialized biotech fermenter archetype, with Japanese corporate structure signaling fermentation process heritage. Unilever Plc. represents the diversified consumer goods anchor with sustainability credentialing capabilities.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever Plc. |
| The Estée Lauder Companies Inc. |
| The Procter & Gamble Company |
| LVMH |
| Beiersdorf AG |
| Shiseido Co., Ltd. |
| Coty Inc. |
| Amway Corp |
| Others |
Value Network & Pricing Analysis
Biotech fermentation processes for active ingredient production are simultaneously compressing unit economics for premium skincare formulations and concentrating manufacturing gravity within Seoul-Incheon clusters, creating asymmetric pricing power for brands with captive access to Korean contract capacity.
Pricing Analysis
Service bundling separates premium skincare tiers from mass-market alternatives, with prestige brands incorporating personalized consultation, diagnostic device pairing, and subscription replenishment into headline pricing while economy tiers strip these to minimum viable formulations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by active ingredient concentration, fermentation-derived bioavailability, and clean-label certification status. Cost compression in the mid-tier is intensifying because Korean manufacturing capacity constraints force brands to absorb premium slotting fees or sacrifice formulation complexity. Mass-market supermarket channels exhibit highest price sensitivity, while prestige consumers in China's tier-one cities demonstrate lowest elasticity due to social commerce-enabled discovery reducing perceived substitution risk.
Supply Chain Analysis
Freight cost volatility for temperature-sensitive active ingredient shipments from Seoul-Incheon to European and North American distribution hubs is amplifying landed cost unpredictability for brands without regional fermentation partnerships. Supply concentrates in South Korea, Madagascar, and Indonesia, with centella asiatica botanical harvests anchoring upstream input flows into Korean processing facilities. Raw material dependencies center on shea and argan extracts for natural formulation segments, alongside specialized fermentation media for microbial-derived actives. Single-source vulnerability characterizes the Seoul-Incheon manufacturing cluster, where over 60% of advanced fermentation capacity sits within 50 kilometers. Distribution runs through specialty retail and direct-to-consumer platforms for premium tiers, while mass-market volumes flow through supermarket and drugstore channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology-sensor convergence in personalized skincare dispensing is displacing legacy standardized SKU models, compressing the addressable market for traditional formulation portfolios while expanding subscription revenue opportunities for adaptive supply chains.
For Market Incumbents: Deepen backward integration into Korean fermentation capacity through strategic partnerships or captive facility investments, defending against supply security threats from concentrated Incheon manufacturing. Prioritize EU REACH pre-registration of natural preservative alternatives ahead of Annex XVII enforcement timelines, leveraging existing regulatory affairs infrastructure to accelerate clean-label portfolio transitions.
For New Entrants and Emerging Players: The premium-economy price-point gap in India's underpenetrated tier-one cities offers white-space entry through FSSAI-harmonized ASEAN regulatory dossiers. Target social commerce-enabled discovery channels for millennial and Gen Z consumers with simplified routine architectures that reduce formulation complexity barriers. Deploy direct-to-consumer pilot programs in China's NMPA cross-border e-commerce zones to bypass traditional animal testing requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized biotech fermenters with proprietary active ingredient platforms and established MFDS regulatory dossiers. Long-term viability favors targets with demonstrated natural extraction capabilities and pre-positioned EU Green Deal compliance infrastructure. Monitor ECHA microplastic restriction enforcement timelines as inflection indicators for reformulation investment cycles and stranded asset risk in color cosmetics portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Fermentation Partnership | Secures captive access to Seoul-Incheon manufacturing capacity for microbial-derived actives. |
| Clean-Label Reformulation Program | Accelerates EU REACH Annex XVII compliance ahead of microplastic and preservative restriction deadlines. |
| Social Commerce Platform Integration | Captures Douyin and Xiaohongshu livestreaming discovery channels displacing department store counters. |
| Natural Extraction Capability Buildout | Reduces climate-sensitive botanical supply risk for shea, argan, and centella asiatica inputs. |
| Personalized Dispensing System Launch | Enables subscription revenue models through biotechnology-sensor convergence in at-home diagnostics. |
Research Methodology
Document review covered SEC 10-K filings, EU REACH registration databases, NMPA cosmetic safety assessments, and Korean MFDS post-market surveillance reports, complemented by interviews with brand formulation directors, contract manufacturing executives at Seoul-Incheon facilities, regulatory affairs specialists navigating FDA MoCRA compliance, and specialty retail category buyers. Primary fieldwork with fermentation technology R&D leads and social commerce platform operators validated secondary findings. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical shipment data from Korean customs authorities with panel input from procurement heads at multinational beauty conglomerates anchored volume projections. Segmentation dimensions modeled include product type, age cohort, distribution channel, and formulation provenance alongside geographic regulatory cluster differentiation. CAGRs were derived through iterative reconciliation of demand elasticity estimates and supply capacity expansion schedules, with specific incorporation of EU Green Deal chemical restriction timelines and China NMPA simplified filing pathway adoption curves.
Underlying measurement precision varies by segment; skincare and haircare categories carry tighter precision than fragrance and color cosmetics due to more consolidated retail audit data availability. Forecasts reflect assumptions regarding regulatory enforcement continuity, fermentation capacity expansion rates, and social commerce channel migration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Australia Skin Care Products Market
Beauty & Personal Care
Makeup Brush and Tool Market
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
Hair Styling Equipment Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
Private Label Cosmetics Market