
 Sleeper Pads Market | 2026-2036
Sleeper Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Sleeper Pads Market Analytics
Modular bundling of sleeper pads with sleeping bags and tents is consolidating buyer choice across outdoor retail channels. Therm-a-Rest leverages its proprietary foam-inflation hybrid technology to sustain premium positioning in backcountry segments. Getzner Werkstoffe GmbH anchors European rail supply chains with elastomer-based pads engineered for vibration dampening in passenger cars. Decathlon competes through vertical control of its manufacturing network, extending cost advantages in mass-market camping categories.
Sleeper pads are portable cushioning systems, typically constructed from open-cell foam, closed-cell polyethylene, or inflatable TPU-coated fabrics with R-values measuring thermal resistance from one to seven. They function primarily to insulate users from ground heat loss and provide ergonomic support during sleep in outdoor, medical, or transportation environments. Foam-based products dominate volume in medical and institutional applications where puncture resistance and low maintenance outweigh packability concerns. Inflatable pads represent the fastest-expanding application segment, as ultralight designs penetrate thru-hiking and bikepacking communities willing to trade setup time for reduced carry weight. Eco-friendly feature claims are concentrating margin pools, with bluesign-certified and recycled-content pads commanding shelf space differentiation at REI and specialty retailers.
The US Consumer Product Safety Commission and California's Proposition 65 framework govern foam off-gassing and chemical content disclosures, compelling suppliers to reformulate polyurethane components or source certified clean materials. In Europe, the ECHA REACH regulation restricts isocyanate and flame-retardant chemistries in foam production, while the EU Green Deal pushes manufacturers toward bio-based polyols and circular end-of-life pathways. Railway applications face additional scrutiny under EN 45545 fire-safety standards administered by national notified bodies in Germany and France. Stakeholders must monitor evolving chemical restriction timelines and decide whether to front-load compliance investment or risk supply disruption when transitional periods expire.
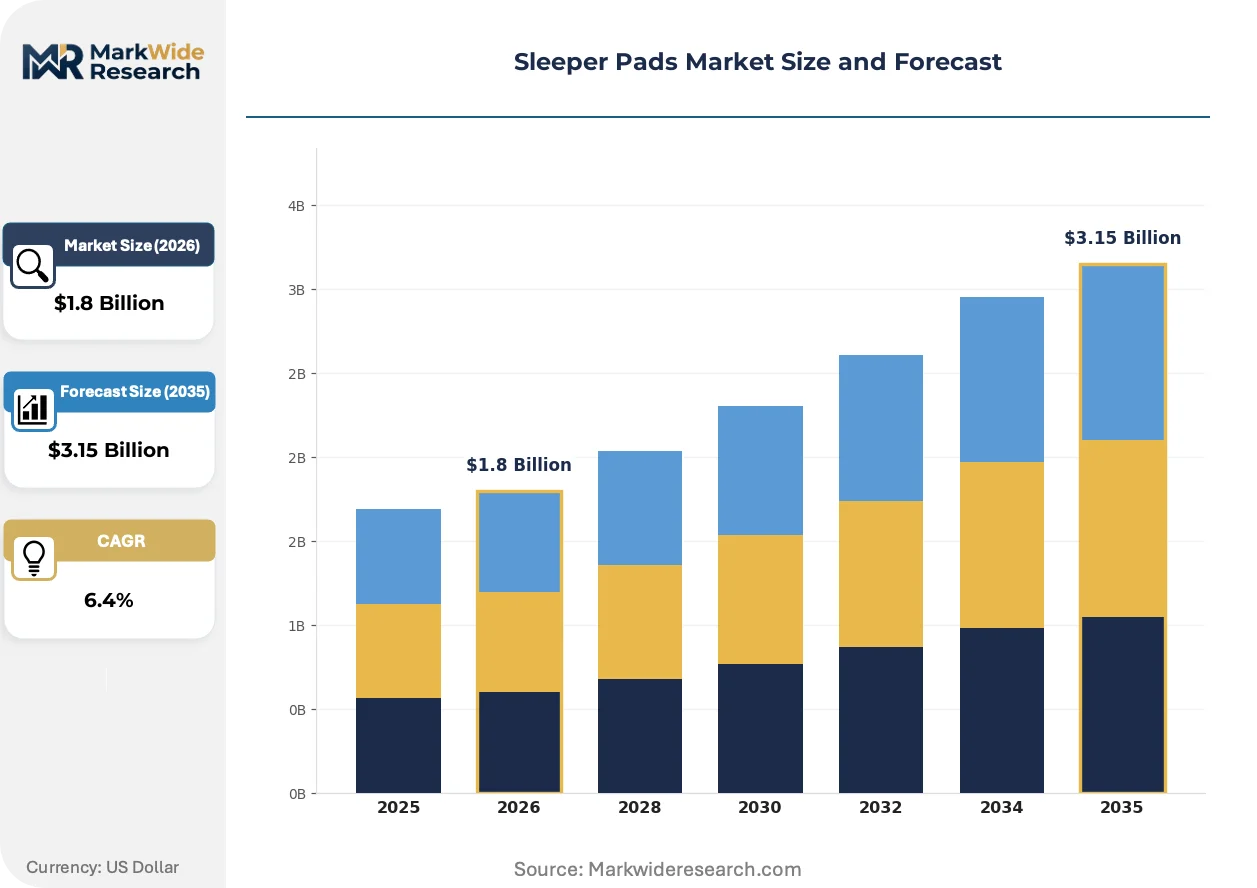
Market Dynamics
The EU's REACH chemicals regulation is forcing polyurethane foam reformulation across the supply base, while alpine tourism infrastructure investment in Germany concentrates institutional procurement and reshapes competitive positioning in rail and outdoor segments.
Growth Catalysts
- REACH chemical compliance deadlines:Manufacturers accelerating bio-based polyol adoption to meet ECHA transitional timelines, creating first-mover advantage for certified clean material suppliers.
- Alpine tourism infrastructure:German federal and state governments funding rail network sleeper car refurbishment and mountain hut modernization, driving institutional volume for vibration-dampening elastomer pads.
- Recycled polyester certification:bluesign and GRS-certified content requirements from REI and specialty retailers concentrating margin pools around eco-feature differentiation.
Market Restraints
- TPU-coated fabric cost volatility:Inflation-linked petrochemical feedstock pricing compressing margins on ultralight inflatable pad production.
- Isocyanate supply concentration:ECHA authorization restrictions limiting approved suppliers for polyurethane foam curing agents, creating single-source risk in European manufacturing.
- Closed-cell foam substitution:EVA and cross-linked polyethylene alternatives displacing traditional open-cell designs in medical institutional applications where sterilization cycles degrade foam integrity.
Strategic Opportunities
- EU Green Deal circular pathways:End-of-life take-back mandates creating closed-loop service models for foam recovery and chemical recycling.
- Bikepacking equipment convergence:Inflatable pad integration with frame bags and handlebar roll systems opening ultralight distribution through cycling-specialist channels.
- Railway fire-safety upgrades:EN 45545-2 compliance requirements across French and German rolling stock operators generating replacement demand for low-smoke, zero-halogen pad materials.
Industry Challenges
- Flame-retardant chemist talent scarcity:Formulation expertise for halogen-free, low-toxicity alternatives concentrated among retiring specialists in German and Austrian technical institutes.
- Multi-certification timeline compression:Simultaneous REACH, bluesign, and OEKO-TEX audit requirements extending product development cycles by 8-14 months for new pad launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleeper Pads Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyester, Foam, Cotton, Wool Application: Camping, Home Use, Medical, Outdoor Activities Size: Single, Double, Queen, King Feature: Water-Resistant, Portable, Eco-Friendly, Hypoallergenic |
| Companies Covered | Sea to Summit, Therm-a-Rest, REI, KLYMIT, Nemo Equipment, Exped, Decathlon, Getzner Werkstoffe GmbH, Vossloh AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleeper Pads Market Evolving Landscape
Material science convergence with circular economy mandates is reconfiguring how sleeper pads are designed, certified, and recovered across outdoor, medical, and transportation applications.
Foam-inflation hybrid architectures are integrating thermal mapping data from body pressure sensors to optimize R-value zoning in backcountry pads. Thru-hiking and alpine climbing buyers are adopting these designs despite 15-25% weight penalties versus pure air constructions. The technology is integrating computer-aided topology optimization to reduce material waste during die-cutting operations.
California's Proposition 65 enforcement expansion is mandating explicit chemical content labeling for polyurethane off-gassing in consumer-facing packaging. Foam suppliers serving the US market are reformulating to eliminate toluene diisocyanate residuals or absorbing litigation insurance premiums. Outdoor retailers with California exposure are demanding pre-certified clean foam stock from contract manufacturers to shield brand liability.
Modular bundling is consolidating buyer choice as REI and Decathlon package pads with sleeping bags and tents at fixed price points. Specialty outdoor channels are responding with unbundled, component-level SKUs targeting experienced users with existing kit. Germany's alpine club hut network and France's GR long-distance trail infrastructure are exhibiting the strongest concentration of this behavior, where rental and purchase decisions converge at trailhead retail.
Sleeper Pads Market Segmentation
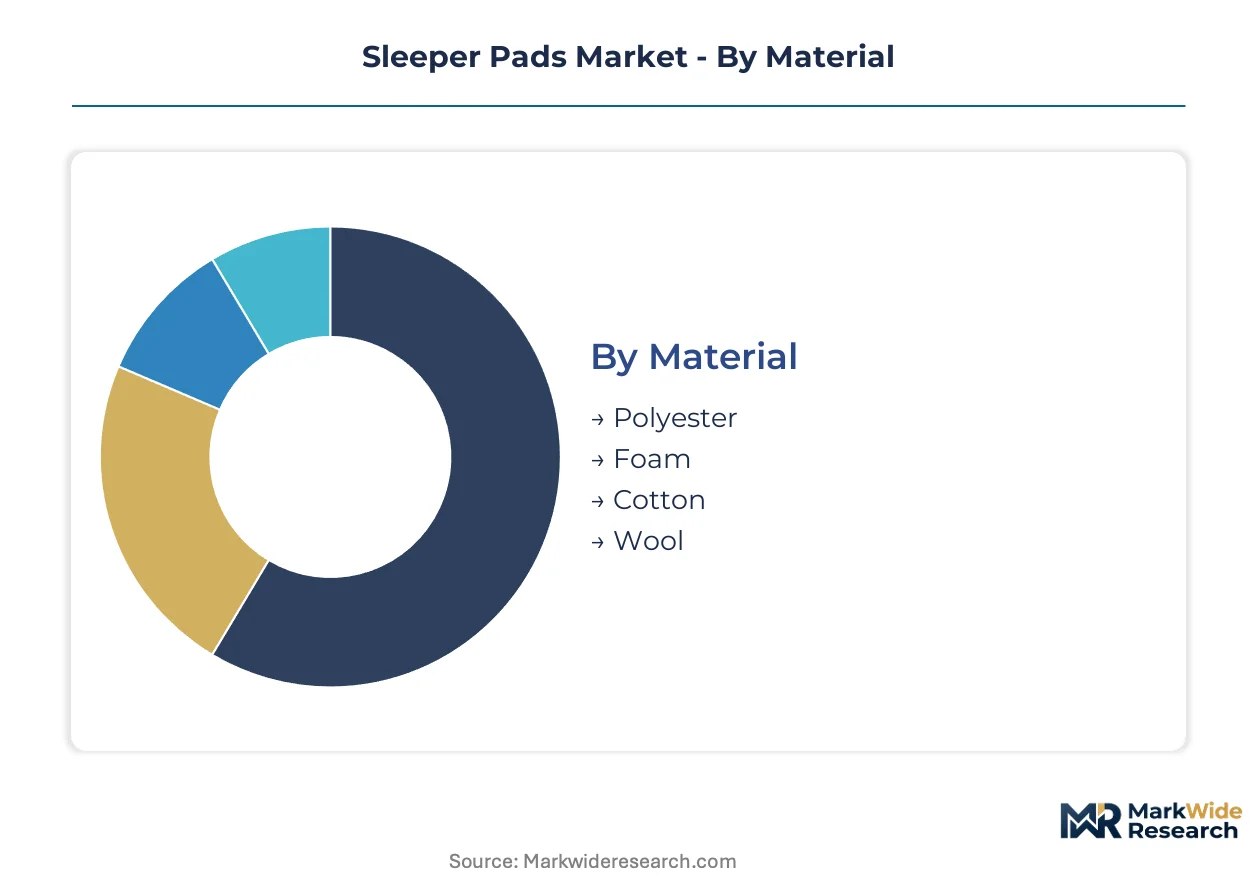
Material composition determines thermal performance, packability, and regulatory compliance pathways across sleeper pad categories. Application context shapes durability requirements and distribution channel selection. Understanding how these dimensions intersect reveals where margin pools concentrate and where substitution risk threatens incumbent technologies.
Material:
Foam dominates institutional volume while inflatable constructions command premium outdoor retail margins.
- Foam:Open-cell and closed-cell polyurethane formulations deliver puncture resistance and low maintenance for medical and rail applications. German alpine hut networks and hospital procurement in France favor foam for sterilization tolerance and vibration dampening in rolling stock. REACH chemical restrictions are forcing bio-based polyol transitions that extend product development timelines.
- Polyester:Recycled-content PET fabrics coated with TPU form the air chamber walls of ultralight inflatable pads. bluesign and GRS certification requirements from REI and specialty retailers in California concentrate sourcing decisions among certified clean material suppliers. Petrochemical feedstock volatility compresses margins on air pad production.
- Cotton:Natural fiber batting appears in budget camping pads and institutional bedding where breathability outweighs packability concerns. Indian and Turkish textile mills supply raw stock for European contract manufacturers.
- Wool:Merino and synthetic wool blends insulate luxury outdoor pads targeting cold-weather hunters and basecamp users. New Zealand and Australian fiber cooperatives anchor premium supply chains.
Today's leader: Foam. Tomorrow's challenger: Polyester.
Application:
End-use context determines whether packability or durability receives engineering priority.
- Camping:Backpacking and car camping segments split between ultralight air constructions and self-inflating foam hybrids. Thru-hiking communities in the Appalachian and Pacific Crest trail corridors drive R-value optimization and weight reduction specifications.
- Medical:Hospital and long-term care facilities demand pressure-relief surfaces with fire-retardant certification and sterilization compatibility. EN 45545-2 compliance requirements in German and French healthcare procurement constrain supplier pools.
- Outdoor Activities:Hunting, fishing, and festival use cases prioritize rapid deployment and weather resistance over thermal efficiency. Mass-market retailers in the US and Germany compete on bundled pricing with tents and sleeping bags.
- Home Use:Guest bedding and floor sleeping applications favor foldable foam designs with washable covers. Japanese tatami-adjacent products and European sofa-bed conversions represent distinct regional subsegments.
Medical procurement anchors volume stability. Camping applications are climbing the fastest.
Size:
Dimensional standardization enables modular bundling while custom sizing captures niche premium segments.
- Single:Standard 20-inch width dominates backpacking where every gram counts. Solo bikepackers and alpine climbers in the Alps and Rockies drive specification convergence.
- Double:Two-person pads reduce weight-per-sleeper for couples and integrate with four-season mountaineering tents. Couples camping in Germany's Black Forest and France's Vosges Mountains concentrate demand.
- Queen:Car camping and glamping applications favor width for comfort over trail weight constraints. US national park campgrounds and European campsite networks exhibit strongest uptake.
- King:Luxury basecamp and expedition support vehicles accommodate oversized pads for extended stays. Safari operators in Kenya and scientific field stations in Antarctica represent specialized procurement.
Single sizes capture unit volume. Double sizes gain share fastest in bundled tent-pad-sleeping bag configurations.
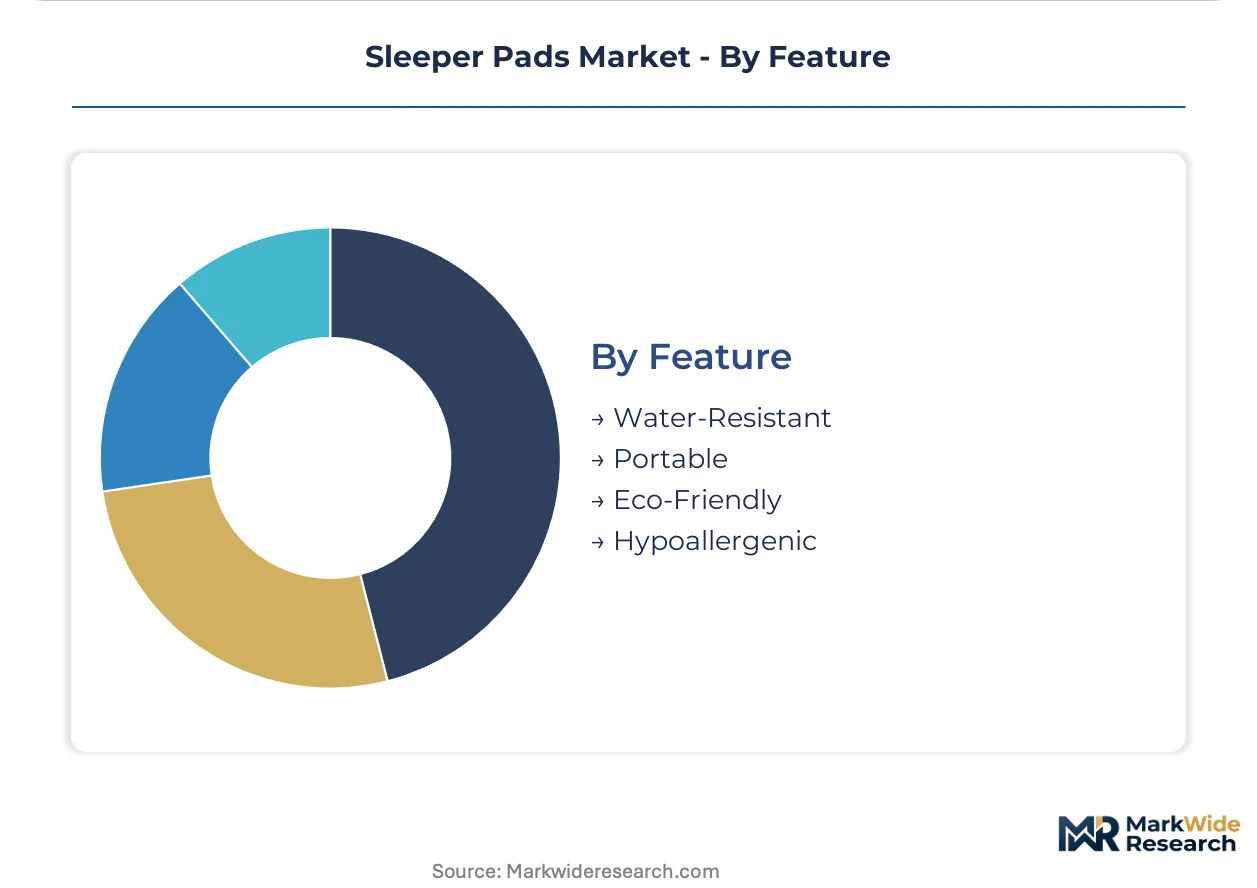
Feature:
Certification claims increasingly determine shelf placement and price positioning at specialty retailers.
- Eco-Friendly:Recycled polyester content, bio-based polyols, and end-of-life take-back programs satisfy EU Green Deal procurement criteria. REI and Decathlon demand bluesign or GRS certification for premium placement.
- Water-Resistant:TPU lamination and DWR treatments protect foam and air chambers from ground moisture. Pacific Northwest and Scottish Highland users prioritize this specification.
- Portable:Pack size and weight metrics dominate backpacking purchasing decisions. Compression straps and integrated pumps reduce setup friction for thru-hikers.
- Hypoallergenic:Latex-free foam and antimicrobial fabric treatments serve medical and sensitive-user segments. California Proposition 65 disclosure requirements pressure suppliers to eliminate residual isocyanates.
Eco-friendly certification commands current margin premiums. Hypoallergenic claims are expanding most quickly into mainstream outdoor retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sleeper pads industry traces its commercial origins to post-war European mountaineering culture, where alpine clubs in Switzerland and Austria pioneered lightweight foam insulation for high-altitude bivouacs before American manufacturers scaled production for recreational camping.
United States
California's Proposition 65 enforcement drives chemical disclosure reformulation across foam suppliers serving REI and specialty retailers. The EPA oversees volatile organic compound emissions from polyurethane manufacturing facilities in the Pacific Northwest. Seattle-area brands and Salt Lake City outdoor equipment clusters concentrate R&D investment for ultralight inflatable constructions.
Germany
Alpine tourism infrastructure programs fund rail network sleeper car refurbishment and mountain hut modernization, institutionalizing demand for vibration-dampening elastomer pads. The KBA administers EN 45545-2 fire-safety certification for rolling stock materials, constraining supplier pools. Bavarian chemical manufacturers and Baden-Württemberg foam fabricators anchor European supply chains with bio-based polyol transitions.
France
The GR long-distance trail network and alpine club hut infrastructure concentrate rental and purchase decisions at trailhead retail points. ANSM oversees medical device pressure-relief surface certifications for hospital procurement. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur regions exhibit strongest outdoor recreation participation rates driving consumer pad specifications.
Japan
METI's carbon neutrality roadmaps push manufacturers toward recycled polyester content and circular end-of-life pathways for camping equipment. The Osaka-Kobe industrial corridor hosts precision TPU coating operations for inflatable pad air chambers. Tokyo-based outdoor retailers demand bluesign-certified products, filtering supply chain access for domestic and imported brands.
China
MIIT's dual carbon goals accelerate bio-based polyol research partnerships between domestic foam producers and European technology licensors. The Yangtze River Delta concentrates TPU film extrusion and textile lamination capacity for export-oriented inflatable pad manufacturing. GB standards for furniture flammability create baseline compliance requirements distinct from REACH and California regulatory frameworks.
Sleeper Pads Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and material technology dimensions, with three structural tiers visible: integrated outdoor equipment conglomerates controlling retail channel access, specialized foam and elastomer compounders serving institutional rail and medical procurement, and contract manufacturers competing on certified clean material sourcing. Strategic moves concentrate on backward integration into TPU coating operations and geographic expansion through cycling-specialist distribution channels.
Within the integrated equipment tier, Therm-a-Rest and Sea to Summit exemplify premium positioning through proprietary construction technologies and direct consumer channel investment. Among European institutional suppliers, Getzner Werkstoffe GmbH occupies a position representing specialized elastomer engineering for railway vibration dampening applications. Decathlon anchors the mass-market vector with in-house manufacturing network control extending cost advantages across bundled camping equipment assortments.
| Leading Market Players |
|---|
| Sea to Summit |
| Therm-a-Rest |
| REI |
| KLYMIT |
| Nemo Equipment |
| Exped |
| Decathlon |
| Getzner Werkstoffe GmbH |
| Vossloh AG |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up foam compounders in Germany and Austria now control the majority of European polyurethane supply, concentrating pricing power among three holding-company portfolios while simultaneously locking in long-term offtake contracts with rail operators and medical distributors. This ownership consolidation has tightened working-capital discipline across the supply base, forcing mid-tier pad manufacturers to absorb petrochemical feedstock volatility or surrender shelf space to vertically integrated competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the sleeper pads landscape, with bluesign-certified and GRS-validated products commanding shelf-space premiums at REI and Decathlon while uncertified foam pads compete on landed cost in institutional procurement. Price differentiation rests on certification grade and volume scale, with bulk rail contracts in Germany compressing unit economics for elastomer suppliers. Cost compression in the inflatable pad tier is intensifying because TPU-coated fabric feedstock tracks volatile petrochemical indices. Mass-market camping buyers exhibit highest price sensitivity, while alpine hut networks and hospital procurement demonstrate inelastic demand for fire-certified foam constructions.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor European hub-and-spoke patterns for finished pad inventory, with secondary spokes radiating to trailhead retail clusters in the Alps and Pyrenees. Manufacturing concentrates in China, Germany, and Vietnam, with Chinese Yangtze River Delta facilities handling TPU film extrusion and German Baden-Württemberg plants managing bio-based polyol foam curing. Raw material flows draw from Saudi petrochemical feedstocks, New Zealand wool cooperatives, and Indian cotton textile mills. Single-source vulnerability in isocyanate curing agents creates disruption risk as ECHA authorization timelines expire. Distribution runs through outdoor specialty retailers, hospital GPOs, and rail operator direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sleeper pads market functions as a regulatory compounder where REACH chemical compliance deadlines and EN 45545-2 fire-safety upgrades generate replacement demand that outpaces underlying volume growth. ECHA transitional timelines for bio-based polyols represent the most consequential near-term milestone, rewarding first-mover suppliers with locked-in rail and medical contracts.
For Market Incumbents: Deepen backward integration into TPU coating operations to capture margin currently leaking to Yangtze River Delta contract manufacturers, while simultaneously accelerating bio-based polyol certification to defend against substitute elastomer technologies from Austrian compounders. Threats concentrate in EVA and cross-linked polyethylene displacement of open-cell foam in sterilization-intensive medical applications. Channel control through exclusive alpine hut supply agreements offers the strongest defensive lever.
For New Entrants and Emerging Players: Computer-aided topology optimization for foam-inflation hybrid architectures offers a technology-first wedge into the thru-hiking segment where established brands carry 15-25% weight penalties. White-space targets include bikepacking-specialist distribution channels and circular take-back service models mandated by EU Green Deal procurement criteria. The French GR trail network and German alpine club infrastructure represent the most penetrable geography, with unbundled component-level SKUs targeting experienced users as the optimal go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap foam fabricators with stranded isocyanate formulation expertise and aging plant assets in Bavaria and Baden-Württemberg. Long-term viability over the next decade hinges on successful bio-based polyol transition and circular pathway certification rather than volume scale. Acquisition targets should prioritize specialists with captive rail operator relationships and EN 45545-2 testing capabilities. The signal to watch is ECHA authorization list revisions for flame-retardant chemistries, which will determine stranded asset risk across European manufacturing footprints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TPU Coating | Captures margin from Yangtze River Delta contract manufacturers serving REI and Decathlon. |
| Bio-Based Polyol Certification Investment | Locks in German rail operator contracts ahead of ECHA REACH transitional deadlines. |
| Circular Take-Back Program Launch | Satisfies EU Green Deal procurement criteria for alpine hut networks and hospital GPOs. |
| Bikepacking Channel Partnership | Opens ultralight distribution through cycling-specialist retailers in the Alps and Rockies. |
| EN 45545-2 Fire-Safety Upgrade | Generates replacement demand from French and German rolling stock operators. |
Research Methodology
Direct dialogue with foam compounder plant managers, outdoor equipment procurement leads at REI and Decathlon, railway materials engineers at Deutsche Bahn and SNCF, and hospital GPO contracts managers grounded qualitative findings in operational reality. Secondary validation drew from ECHA REACH substance databases, EN 45545-2 test reports filed with German KBA and French notified bodies, customs trade data for TPU-coated fabric imports, and SEC 10-K disclosures from listed outdoor equipment conglomerates. Bottom-up and top-down triangulation cross-checked volume estimates against rail fleet refurbishment schedules and alpine tourism infrastructure investment flows.
Bottom-up modeling built from individual product SKU specifications across foam, inflatable, and hybrid constructions, while top-down analysis anchored on rail operator procurement budgets and outdoor retailer category growth rates across the analysis window. Segmentation dimensions included material composition, application context, dimensional sizing, and certification tier. CAGRs derived from curve-fitting historical replacement cycles in German rolling stock and projected camping participation trends in North American and Western European trail networks. Industry-specific inputs incorporated R-value thermal performance standards and packability metrics from thru-hiking community specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA authorization timeline extensions, petrochemical feedstock price volatility, and substitution rates from EVA alternatives in medical sterilization applications. Outputs reflect documented assumptions around regulatory compliance deadlines and infrastructure investment commitments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Portable Kayaks Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Global Artificial Grass Market
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Kayak Accessories Market