
 Above Ground Swimming Pools Market | 2026-2036
Above Ground Swimming Pools Market Size, Share, and Industry Trends Forecast 2026-2036
Above Ground Swimming Pools Market Analysis
Residential demand is shifting toward larger permanent-style installations as suburban households prioritize stay-at-home recreation over seasonal travel. Intex leverages its global manufacturing scale to dominate the inflatable and metal frame entry-level tiers. Bestway sustains competitive pressure through backward integration into PVC resin and pump production. Wilbar anchors the premium resin segment with proprietary composite wall systems and proprietary coping designs.
Above ground swimming pools are freestanding aquatic structures assembled from modular wall panels, support frames, and vinyl liners, typically installed on prepared earth or sand bases without excavation. Steel and aluminum wall systems range from 48 to 54 inches in height and accommodate volumes from 5,000 to 30,000 gallons for residential recreation and light commercial use. Metal frame pools occupy the volume leadership position due to their balance of affordability and structural longevity, while hybrid systems represent the fastest-expanding category as manufacturers combine steel uprights with resin top rails and composite wall materials. The accessories segment captures disproportionate margin pools as recurring filter, cover, and maintenance kit purchases generate annuity-like revenue streams.
The U.S. Consumer Product Safety Commission mandates anti-entrapment drain covers and climb-resistant barrier requirements that elevate engineering standards and compliance costs for manufacturers selling into the American market. ASTM International publishes structural integrity and liner durability specifications that shape warranty terms and retailer acceptance criteria across North American distribution channels. Pool builders and retailers must monitor evolving municipal setback ordinances and electrical bonding codes that increasingly treat permanent above ground installations with parity to in-ground pools.
Market Dynamics
Suburban homeowners are abandoning seasonal travel budgets in favor of permanent backyard recreation infrastructure, compressing replacement cycles and elevating durability expectations for above ground pool systems.
Growth Catalysts
- Sun Belt climate concentration:Extended swimming seasons across Texas, Florida, and Arizona sustain year-round demand that offsets northern seasonality. Municipal setback relaxations in these states accelerate permitting velocity.
- Resin composite wall systems:Hybrid material technology eliminates corrosion failure modes that plagued steel-only construction. Suburban buyers now specify 54-inch wall heights previously reserved for in-ground alternatives.
- ASTM F2208 barrier mandates:The CPSC-backed climb-resistant fencing standard creates replacement pull for compliant pool packages. Retailers bundle barrier systems to capture full-project spend.
Market Restraints
- Steel coil input volatility:Galvanized steel sheet pricing swings directly compress margin on metal-frame entry tiers. Manufacturers lack hedging instruments for this commodity exposure.
- China-based liner production:Vinyl membrane supply concentrates in Zhejiang and Guangdong provinces. Geopolitical friction threatens just-in-season inventory positioning for North American distributors.
- Permanent in-ground substitution:Fiberglass shell pools have achieved sub-$25,000 installed price points in competitive markets. This compresses the price gap that above ground systems historically exploited.
Strategic Opportunities
- Smart pool automation convergence:Integration of variable-speed pumps with Wi-Fi-enabled chemical monitoring creates premium positioning. Salt chlorine generators pair with app-based maintenance alerts.
- Commercial hospitality retrofit:Boutique hotels and campground operators seek rapid-deployment aquatic amenities without excavation disruption. Modular systems install within 48-hour windows.
- Canadian seasonal extension:Solar thermal blanket systems and heat pump compatibility address abbreviated swimming seasons. Ontario and Quebec municipalities increasingly permit permanent above ground structures.
Industry Challenges
- Skilled installer scarcity:Leveling and wall-panel assembly requires trained crews that pool service companies struggle to retain. Certification programs remain fragmented across state lines.
- Electrical bonding code variance:NEC Article 680 compliance differs materially across municipal inspectors. Re-inspection delays stall revenue recognition for pool builder networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Above Ground Swimming Pools Market |
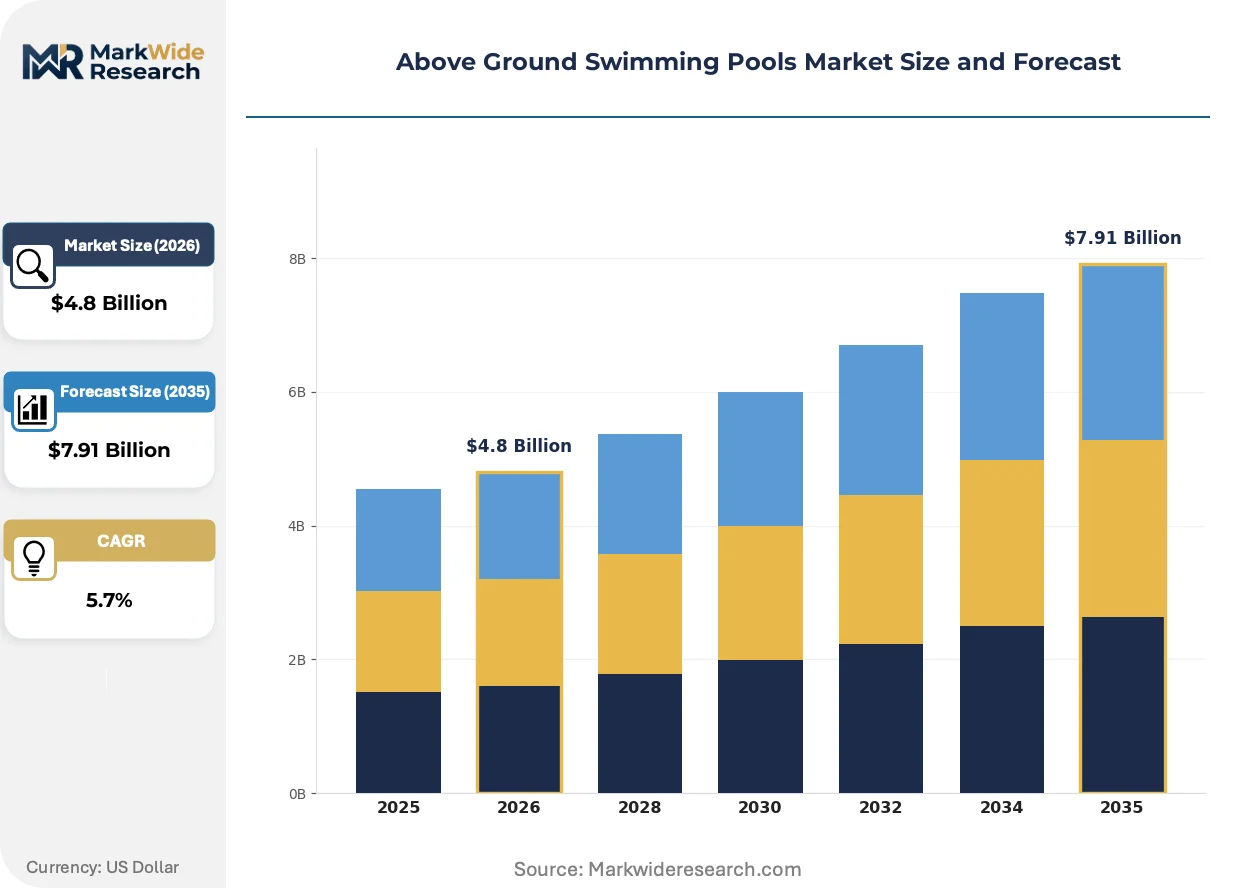
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Metal Frame, Hybrid, Resin Size: Small, Medium, Large, Extra Large Material: Steel, Aluminum, PVC, Composite Accessories: Covers, Ladders, Pumps, Maintenance Kits |
| Companies Covered | Intex, The Pool Factory, Wilbar, Pool Warehouse, Ecopool, Doughboy, Bestway, RTR Pools, Cornelius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Above Ground Swimming Pools Market Emerging Trajectories
Material science advances and connected-device integration are redefining durability expectations and maintenance economics across residential aquatic installations.
Composite resin wall panels are modularizing above ground pool construction by replacing corrosion-prone steel with UV-stabilized thermoplastic structures. Premium suburban buyers in California and Texas specify these systems for 20-year service life expectations. The shift is compressing warranty claim rates and enabling manufacturers to extend coverage terms without reserve escalation.
The U.S. Consumer Product Safety Commission's Virginia Graeme Baker Pool and Spa Safety Act mandates anti-entrapment drain covers and secondary suction-release systems. Compliance engineering adds $200-$400 to bill-of-materials costs for manufacturers serving the American market. Domestic distributors now require VGB certification documentation as a condition of retailer acceptance.
Homeowner maintenance behavior is fragmenting between full-service pool management subscriptions and self-directed chemical testing via digital test strip readers. The middle tier of quarterly professional servicing is eroding. This bifurcation is most pronounced in Arizona and Nevada, where extreme evaporation rates demand precise chemistry discipline.
Above Ground Swimming Pools Market Segmentation
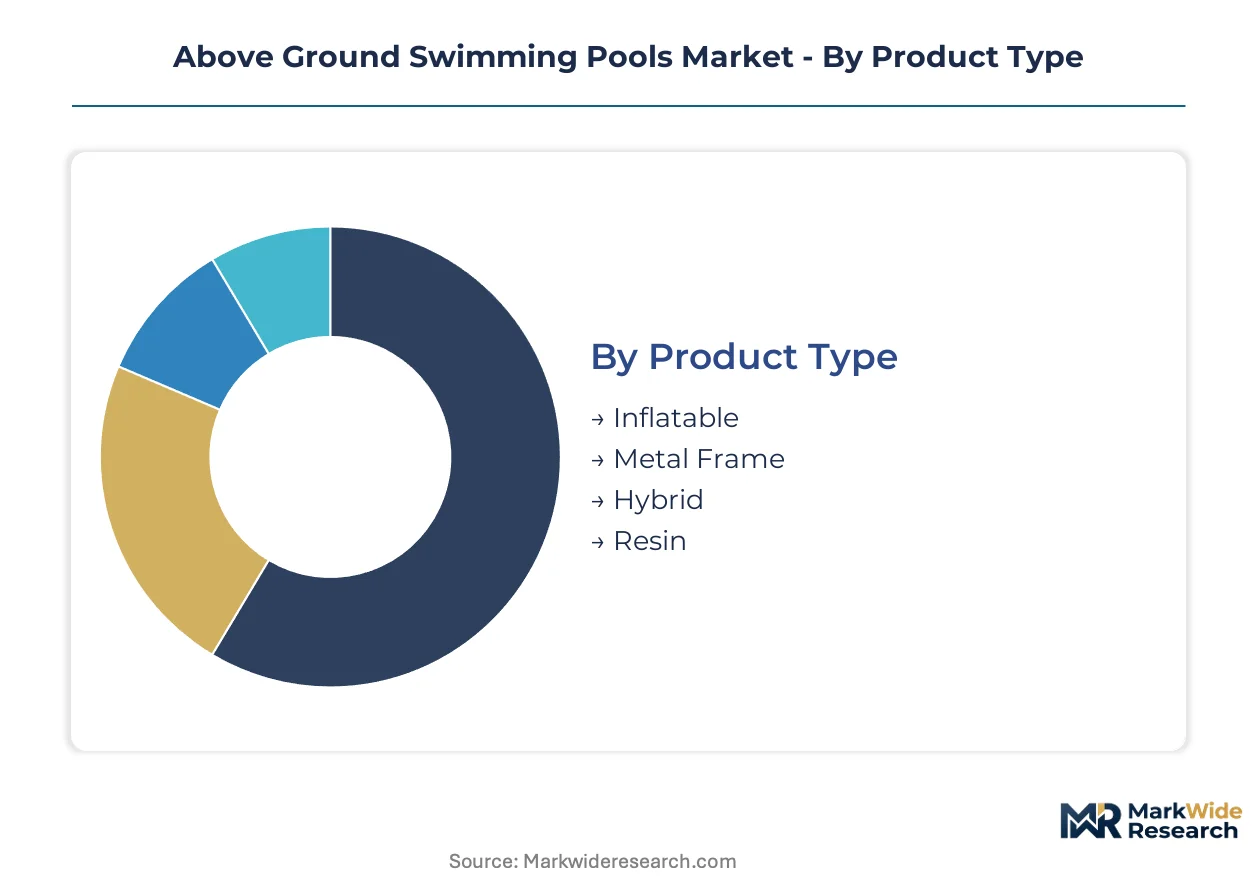
Above ground pool buyers navigate trade-offs between installation permanence, seasonal flexibility, and total cost of ownership that segment demand across distinct product architectures. Material selection and sizing decisions cascade into accessory ecosystems and maintenance regimes that lock in recurring revenue streams for manufacturers.
Product Type:
Installation permanence and durability expectations drive buyer sorting across the four structural tiers.
- Metal Frame:Galvanized steel uprights and horizontal supports provide structural rigidity for vinyl liners across 48-to-54-inch wall heights. Suburban households in Texas and Florida favor these systems for multi-season durability without in-ground excavation costs.
- Hybrid:Combines steel vertical supports with resin top rails and composite wall materials to eliminate corrosion failure points. Sun Belt buyers seeking 20-year service life specifications are migrating toward these systems as steel-only alternatives face warranty compression.
- Inflatable:PVC membrane structures with air-ring support collars enable same-day deployment and seasonal takedown. Renters and vacation property owners in Arizona and Nevada prioritize portability over longevity.
- Resin:UV-stabilized thermoplastic wall panels and structural components deliver maximum corrosion resistance. Premium California buyers specify these for permanent installations with in-ground aesthetic parity.
Volume sits with Metal Frame; growth tilts toward Hybrid.
Size:
Backyard dimensional constraints and household occupancy patterns determine capacity selection across the four-tier spectrum.
- Large:24-foot to 27-foot diameters accommodating 15,000-to-25,000-gallon volumes for multi-generational households. Suburban developments in Florida with minimum lot sizes of 0.25 acres drive concentration here.
- Medium:18-foot to 21-foot configurations balancing swimmable surface area against equipment and heating costs. First-time buyers in Texas Hill Country municipalities with restrictive setback ordinances select this tier.
- Small:12-foot to 15-foot diameter pools for limited yard footprints and single-family use. Urban fringe properties in Arizona with compact lot dimensions favor these systems.
- Extra Large:30-foot-plus diameters and oval configurations exceeding 30,000 gallons. Estate properties and light commercial hospitality installations in California coastal counties specify these for guest amenity differentiation.
Demand clusters at Medium for entry buyers; Large captures upgrade cycles and new construction pairings.
Material:
Corrosion resistance and thermal conductivity properties shape regional material preferences and warranty positioning.
- Steel:Galvanized and powder-coated sheet metal delivers cost-efficient structural strength for wall panels and support frames. Humid Gulf Coast climates accelerate coating degradation and drive replacement demand in Louisiana and Mississippi.
- Composite:Fiberglass-reinforced polymer and resin matrix materials eliminate electrolytic corrosion. Saltwater system compatibility in Florida and California is expanding specification rates for this tier.
- Aluminum:Lightweight extrusions with anodized finishes resist oxidation without galvanic coupling risks. Coastal California installations within salt air exposure zones specify these for frame components.
- PVC:Flexible vinyl membranes for liners and inflatable structures with UV stabilizer packages. Liner replacement cycles in Arizona and Nevada with extreme solar exposure compress to 3-5 years.
Steel dominates unit economics; Composite gains share fastest on saltwater compatibility.
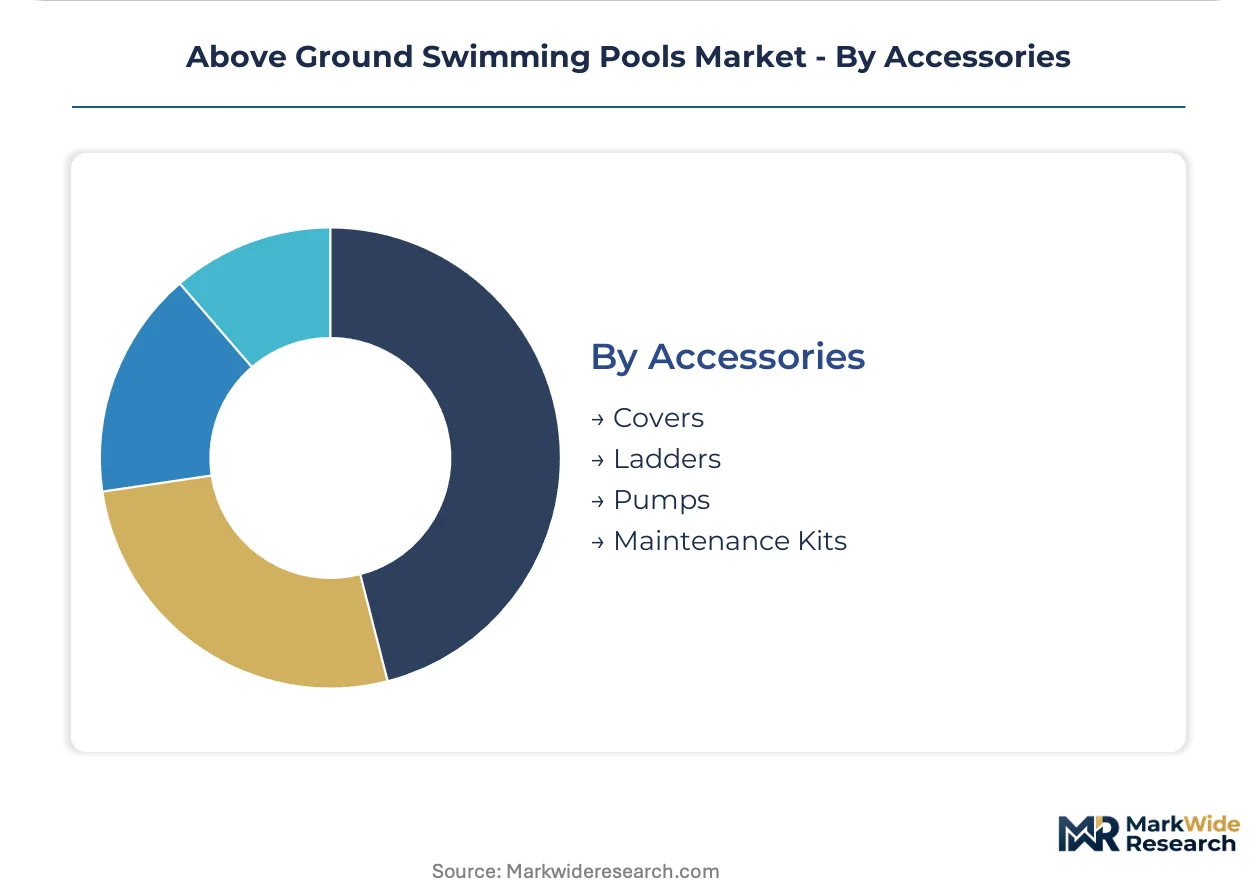
Accessories:
Post-installation spending concentrates on filtration, safety compliance, and seasonal protection equipment that generates recurring revenue.
- Pumps:Single-speed and variable-speed circulation systems with VGB-compliant drain covers. CPSC enforcement in Texas and Florida mandates anti-entrapment configurations for all new installations.
- Covers:Solar thermal blankets, mesh debris covers, and solid winterization systems. Heat retention priorities in abbreviated-season Canadian markets elevate solar cover attachment rates.
- Ladders:A-frame entry systems with lockable gates for ASTM F2208 barrier compliance. Retailer bundling in California and Arizona captures full-project spend through integrated safety packages.
- Maintenance Kits:Test strips, skimmer nets, vacuum heads, and chemical starter bundles. Self-directed maintenance behavior in Arizona and Nevada elevates direct-to-consumer kit sales.
Pumps anchor initial equipment attach rates; Maintenance Kits sustain highest repurchase frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sun Belt Opportunity Zones across southern United States jurisdictions concentrate above ground pool demand through accelerated depreciation allowances for permanent backyard infrastructure investments.
United States
Texas and Florida municipalities drive volume through extended swimming seasons and relaxed setback ordinances. The U.S. Consumer Product Safety Commission enforces Virginia Graeme Baker Pool and Spa Safety Act requirements for anti-entrapment drain covers. Houston-Galveston and Orlando-Kissimmee metropolitan clusters anchor installer networks and regional distribution hubs.
Canada
Ontario and Quebec buyers offset abbreviated seasons through solar thermal blanket attachments and heat pump compatibility. Health Canada coordinates with provincial regulators on recreational water quality standards. Toronto-Greater Golden Horseshoe and Montreal-Laval corridors concentrate permanent above ground installations as municipal permitting increasingly treats these structures with parity to in-ground pools.
Mexico
Vacation property owners in Baja California and Quintana Roo prioritize rapid-deployment aquatic amenities for rental income optimization. Mexican consumer protection agency PROFECO oversees product safety labeling for imported pool systems. Cancún-Riviera Maya and Los Cabos tourism corridors drive commercial hospitality retrofit demand for modular 48-hour installation windows.
Australia
New South Wales and Queensland homeowners specify corrosion-resistant resin systems for salt air exposure zones. Standards Australia publishes AS 2818 for private swimming pool safety barriers that shape product bundling requirements. Sydney-Illawarra and Brisbane-Gold Coast metropolitan clusters concentrate premium-tier demand for 54-inch wall height permanent installations.
United Kingdom
Southeast England and Midlands households seek stay-at-home recreation alternatives amid compressed seasonal travel budgets. The UK Health and Safety Executive enforces Building Regulations Part K and Part N for pool access and glazing safety. London commuter belt and Birmingham metropolitan area developments drive medium-size 18-to-21-foot diameter configurations for limited yard footprints.
Above Ground Swimming Pools Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding premium positioning while OEM assemblers compete on entry-tier price points. Market structure tilts toward consolidation at the top tier and fragmentation across regional installers and private-label distributors. Three archetypes dominate: vertically integrated resin system producers, metal-frame volume manufacturers with captive PVC supply, and specialty retailers bundling installation services. Capacity expansion through automated wall-panel fabrication and strategic partnerships with chemical monitoring technology providers represent the dominant competitive vectors reshaping positioning.
Among branded specialists, Intex and Bestway occupy positions exemplifying scale-driven metal-frame and inflatable tier dominance, while Wilbar anchors the premium resin composite segment through proprietary wall system engineering. These three entities represent distinct strategic postures: global manufacturing footprint with backward integration into raw materials, Asian production base with direct-to-consumer distribution, and North American fabrication with installer network partnerships.
| Leading Market Players |
|---|
| Intex |
| The Pool Factory |
| Wilbar |
| Pool Warehouse |
| Ecopool |
| Doughboy |
| Bestway |
| RTR Pools |
| Cornelius |
| Others |
Supply Flow & Price Mechanics
Steel-frame commodity tiers and resin-composite premium tiers diverge sharply in both margin structure and sourcing geography. The former competes on spot galvanized coil availability from domestic mills, while the latter commands price premiums through captive thermoplastic compounding and extended warranty positioning.
Pricing Analysis
Short-lead-time resin systems from North American fabricators command 15-25% premiums over spot-imported metal-frame equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by wall height, liner thickness, and bundled safety compliance. Pricing pressure stems from sub-$25,000 fiberglass in-ground alternatives compressing the value gap. First-time buyers in Texas and Arizona exhibit highest price sensitivity; California estate buyers least.
Supply Chain Analysis
Skilled thermoplastic welder availability constrains resin panel output in Ohio and Pennsylvania fabrication clusters. Raw material flows draw from Zhejiang vinyl membrane producers, Guangdong pump motor suppliers, and domestic galvanized steel coil mills. Tariff exposure on Chinese liner imports threatens just-in-season inventory positioning. Distribution runs through regional pool builder networks and big-box retail seasonal resets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over PVC resin compounding and pump assembly determines margin defense. Players capturing upstream chemical processing or downstream installer certification lock in pricing power.
For Market Incumbents: Anticipate fiberglass shell substitution by accelerating hybrid system R&D and extending warranty terms through captive liner production. Defend Texas and Florida installer network exclusivity against emerging direct-to-consumer entrants. Backward integration into thermoplastic resin compounding secures margin against commodity steel volatility. For New Entrants and Emerging Players: Begin with Canadian seasonal extension markets where heat pump compatibility and solar blanket bundling remain underdeveloped. Ontario and Quebec municipalities increasingly permit permanent above ground structures with parity to in-ground pools. White-space exists in smart chemical monitoring subscription services for self-directed maintenance households. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to building products conglomerates seeking outdoor living portfolio expansion. Five-to-ten year viability hinges on saltwater system compatibility and automation integration depth. Watch for inflection in municipal setback ordinance relaxations across Sun Belt states as permitting velocity signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin | Captive supply of liner-grade vinyl eliminates Zhejiang tariff exposure and compresses COGS. |
| Smart Pump and Chemical Monitoring Integration | Wi-Fi-enabled variable-speed systems with app alerts capture premium positioning in Arizona and Nevada. |
| Installer Certification Program Expansion | Standardized assembly training across state lines addresses skilled crew scarcity stalling revenue recognition. |
| Commercial Hospitality Retrofit Focus | Boutique hotel and campground 48-hour deployment windows bypass residential seasonality constraints. |
| Saltwater System Compatibility Engineering | Fiberglass-reinforced polymer wall panels meet Florida and California corrosion resistance specifications. |
Methodological Framework
Trade association filings, customs import records, and municipal permitting databases formed the secondary backbone for demand quantification. Primary interviews with pool builder network owners, big-box category buyers, thermoplastic fabrication plant managers, and CPSC compliance officers validated segment sizing. Bottom-up unit economics triangulated against top-down household penetration models across Sun Belt counties.
Bottom-up modeling tracked metal-frame, hybrid, inflatable, and resin unit shipments by wall height and regional climate zone. Segmentation dimensions included product architecture, material corrosion resistance grade, and bundled safety compliance tier. CAGRs derived from installer capacity expansion rates and replacement cycle compression observed across the analysis window. Forecast inputs incorporated steel coil price indices and municipal setback ordinance adoption curves.
Steel input volatility, Zhejiang supply disruption, and fiberglass substitution acceleration are the dominant revision risks to installed base projections. Forecasts reflect these assumptions without contingency buffers for tariff regime shifts. Material deviation in named triggers warrants pause and re-evaluation of volume trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Skateboard Ramp Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
Global Artificial Grass Market
Outdoor & Sports
Kids Scooter Market
Outdoor & Sports
Golf Stand Bag Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Europe Swimming Pools and Spas Market
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
Camping Utensils Market