
 Swimmer's Shoulder/Impingement Syndrome Market | 2026-2036
Swimmer's Shoulder/Impingement Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Swimmer's Shoulder/Impingement Syndrome Market Intelligence
North American surgical instrument manufacturing is reconfiguring around arthroscopic repair platforms for overuse shoulder injuries. Stryker anchors its position through integrated visualization systems that pair implant delivery with real-time imaging. Zimmer Biomet competes via specialized rotator cuff fixation devices optimized for repetitive-motion athletes. Smith & Nephew extends its reach through advanced biologic augmentation materials that accelerate tendon-to-bone healing timelines.
Swimmer's shoulder, or impingement syndrome, denotes subacromial compression of rotator cuff tendons and bursa caused by repetitive overhead strokes, clinically graded by pain provocation tests and imaging-confirmed tendon integrity. The condition demands interventions spanning pharmacologic suppression of inflammation, mechanical restoration of glenohumeral kinematics, and surgical decompression when conservative measures exhaust. Physical therapy modalities command structural prominence due to their role as first-line protocols before escalation to arthroscopic intervention. Ultrasound imaging and MRI technologies lead diagnostic segments by enabling dynamic assessment of supraspinatus pathology without radiation exposure. Surgical instruments capture concentrated margin pools through premium pricing on arthroscopic shavers and suture anchors designed for outpatient sports medicine settings.
FDA 510(k) clearance pathways govern orthopedic device commercialization in the United States, while CE marking under the EU Medical Device Regulation controls European market access for shoulder repair systems. The FDA's Breakthrough Devices Program accelerates review for novel diagnostic modalities that detect early tendinopathy before structural failure. ISO 13485 quality management standards bind contract manufacturers serving Arthrex and CONMED, embedding compliance costs that favor scaled producers. Stakeholders must monitor how CMS reimbursement adjustments for outpatient shoulder procedures reshape site-of-care economics between hospital operating rooms and ambulatory surgery centers.
Market Dynamics
Arthroscopic visualization platforms are compressing diagnostic-to-intervention timelines for repetitive-motion shoulder injuries, forcing manufacturers to bundle imaging hardware with biologic delivery systems rather than selling discrete instruments.
Growth Catalysts
- CMS Reimbursement Expansion:Outpatient shoulder procedure coverage under Medicare Advantage plans accelerates ambulatory surgery center adoption across Florida and Arizona retirement corridors.
- Biologic Augmentation Materials:Platelet-rich plasma and bone marrow concentrate protocols shorten tendon-to-bone healing windows, expanding addressable cases beyond surgical candidates.
- Masters Swimming Demographics:Aging competitive swimmers in Australia and the United States generate sustained demand for preventive diagnostics and early-intervention protocols.
Market Restraints
- Implant Cost Concentration:Suture anchor and interference screw pricing remains tethered to cobalt-chromium and PEEK polymer feedstock volatility.
- FDA 510(k) Pathway Friction:Substantial equivalence requirements for arthroscopic shaver modifications extend commercialization timelines by 12-18 months.
- Non-Operative Substitution:Ultrasound-guided corticosteroid injection and dry needling protocols capture margin from surgical candidates in initial treatment phases.
Strategic Opportunities
- AI-Assisted Tendinopathy Detection:Machine learning models applied to dynamic ultrasound sequences identify supraspinatus microtears before structural failure.
- Ambulatory Surgery Center Channel:Freestanding orthopedic facilities in Texas and California seek bundled implant-and-instrument contracts with single-source accountability.
- EU MDR Biologic Classification:Reclassified cellular augmentation products face elevated clinical evidence requirements, creating first-mover advantage for compliant manufacturers.
Industry Challenges
- Arthroscopic Technician Scarcity:Specialized instrument processing and sterilization expertise concentrates in major metropolitan hospital systems, constraining ASC expansion.
- ISO 13485 Audit Backlogs:Notified body capacity constraints delay quality management certification renewals for contract manufacturers serving tier-two orthopedic device firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swimmer's Shoulder/Impingement Syndrome Market |
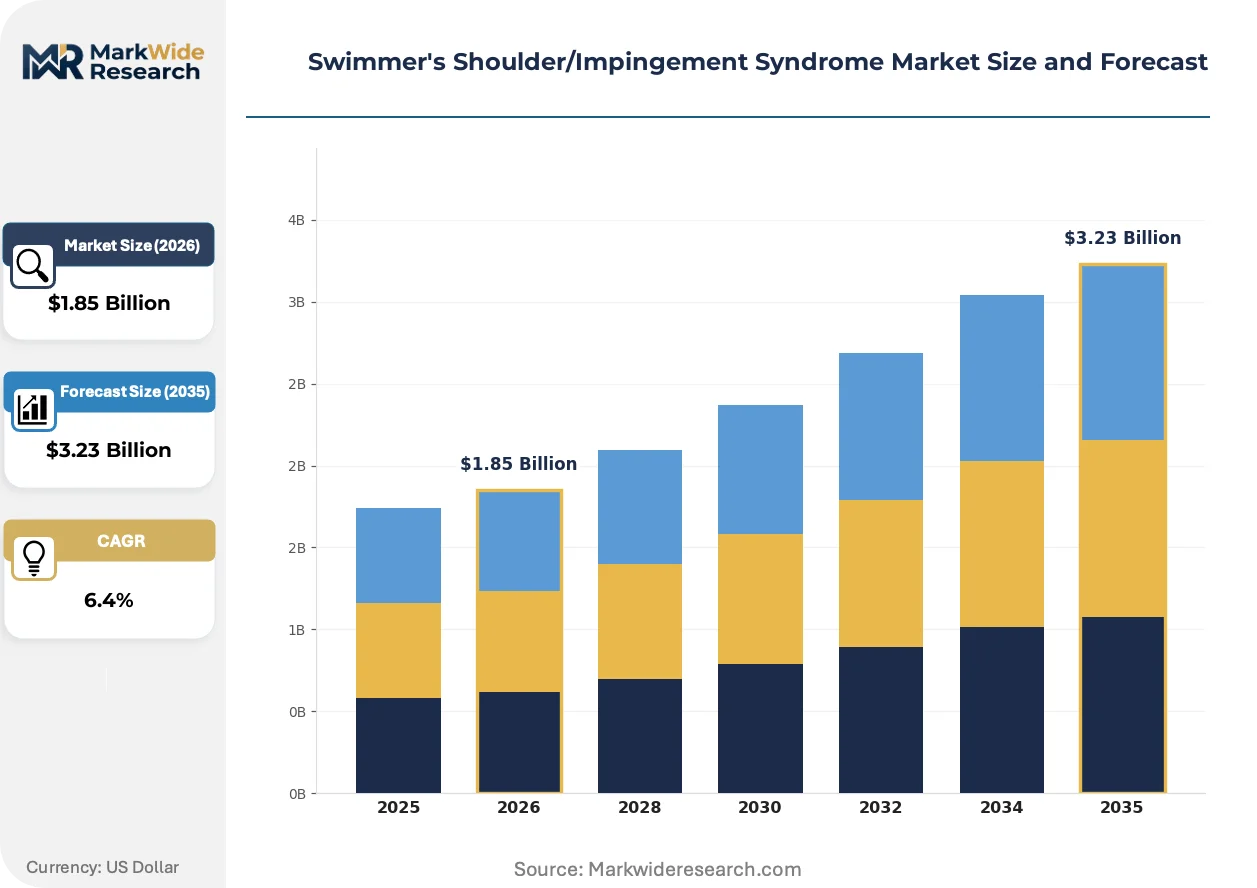
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Drugs, Physical Therapy, Surgical Instruments, Diagnostic Devices End User: Clinics, Hospitals, Home Care, Rehabilitation Centers Application: Pain Management, Surgery, Rehabilitation, Diagnosis Technology: Ultrasound Imaging, MRI, Arthroscopy, Injection Therapies |
| Companies Covered | Johnson & Johnson Services, DePuy Synthes, ATOS Klinik Heidelberg GmbH & Co. KG, Stryker, Zimmer Biomet, Smith & Nephew, Arthrex, CONMED, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swimmer's Shoulder/Impingement Syndrome Market Strategic Shifts & Innovations
Point-of-care diagnostic modalities and biologic-synthetic hybrid implants are restructuring how swimmer's shoulder progresses from first presentation to definitive repair, compressing traditional referral hierarchies.
Dynamic ultrasound with artificial intelligence annotation is digitizing supraspinatus tendon assessment in collegiate athletic departments and high-performance training centers. Sports medicine physicians at NCAA Division I programs deploy these systems during championship seasons to triage overhead athletes without MRI scheduling delays. The technology is digitizing diagnostic workflows previously fragmented between radiology suites and orthopedic clinics, collapsing decision timelines from weeks to single encounters.
FDA Breakthrough Devices Program designation for novel tendinopathy biomarker assays accelerates review timelines for diagnostic platforms detecting collagen degradation products in synovial fluid. Orthopedic device divisions now structure pre-submission meetings around real-world evidence protocols rather than traditional pivotal trials. Early-stage companies targeting outpatient sports medicine channels prioritize this pathway to secure coding and coverage precedents before commercial launch.
Direct-to-consumer physical therapy platforms are fragmenting traditional referral networks for overuse shoulder injuries. Subscription-based telehealth services connecting swimmers with specialized movement analysts bypass primary care gatekeepers in California and Colorado wellness markets. These digital channels capture patients seeking stroke mechanics optimization before pain escalates to surgical thresholds, shifting diagnostic capture upstream from orthopedic practices.
Swimmer's Shoulder/Impingement Syndrome Market Segmentation
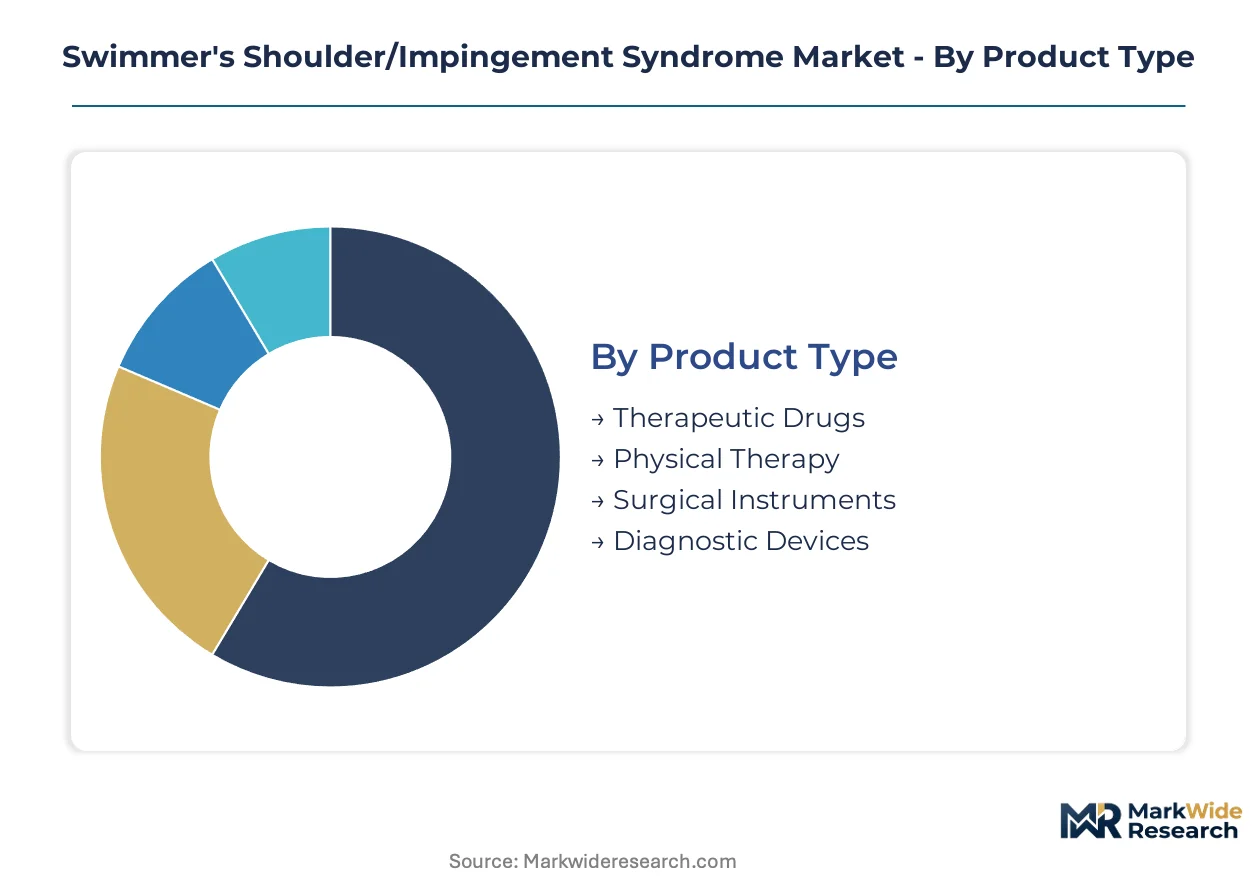
Segmentation in swimmer's shoulder care reveals distinct procurement cycles across intervention modalities. Diagnostic and therapeutic segments turn over rapidly due to consumable replenishment, while capital-intensive surgical platforms exhibit extended replacement timelines tied to ambulatory surgery center expansion.
Product Type:
Cycle times compress from months for biologic consumables to years for capital equipment, creating divergent inventory and financing pressures across manufacturer portfolios.
- Physical Therapy:First-line protocols deploy manual therapy, neuromuscular re-education, and scapular stabilization exercises to restore glenohumeral kinematics before surgical escalation. Demand concentrates in NCAA Division I athletic departments and Australian institute of sport networks where overhead athlete screening protocols mandate early intervention. Equipment refresh cycles accelerate as wearable motion capture systems replace traditional goniometry.
- Diagnostic Devices:Dynamic ultrasound systems and point-of-care MRI platforms enable tendon integrity assessment without radiology suite scheduling delays. Procurement clusters in Texas and Florida retirement corridors where Medicare Advantage plans cover outpatient shoulder evaluations. Portable systems turnover every 3-5 years versus 7-10 year cycles for hospital-based units.
- Therapeutic Drugs:NSAID formulations and corticosteroid suspensions for subacromial injection protocols.
- Surgical Instruments:Arthroscopic shavers, suture anchors, and visualization towers for outpatient decompression procedures.
Physical therapy anchors the volume base while diagnostic devices gain share at the steepest rate.
End User:
Site-of-care economics fragment procurement authority across facility types with divergent reimbursement structures and capital allocation priorities.
- Hospitals:Academic medical centers in Boston and Philadelphia anchor complex revision surgery volumes while maintaining fellowship training pipelines for arthroscopic technique advancement. Bundled payment models under CMS mandatory programs compress implant selection to standardized formularies.
- Clinics:Orthopedic specialty practices in California and Colorado wellness markets capture direct-to-consumer physical therapy referrals bypassing primary care gatekeepers. These facilities prioritize ultrasound-guided injection platforms and telehealth integration for stroke mechanics consultation.
- Rehabilitation Centers:Post-acute facilities specializing in rotator cuff repair recovery protocols.
- Home Care:Remote therapeutic monitoring and prescribed exercise program delivery.
Hospitals retain the highest absolute procedure value while clinics expand their diagnostic capture most aggressively.
Application:
Clinical utility maps directly to disease progression staging, with upstream applications expanding as preventive protocols penetrate masters swimming demographics.
- Diagnosis:Early tendinopathy detection through dynamic ultrasound and synovial fluid biomarker assays prevents progression to structural failure. Sports medicine physicians at high-performance training centers deploy these modalities during championship seasons to triage overhead athletes without MRI delays.
- Rehabilitation:Post-surgical and conservative management protocols restore range of motion and scapulohumeral rhythm through progressive loading. Australian and United States masters swimming leagues sustain demand for maintenance programs targeting aging competitive athletes.
- Pain Management:Ultrasound-guided corticosteroid injection and dry needling for inflammation suppression.
- Surgery:Arthroscopic subacromial decompression and rotator cuff repair procedures.
Diagnosis commands expanding share as detection shifts earlier in the care pathway, while surgery maintains the highest revenue per intervention.
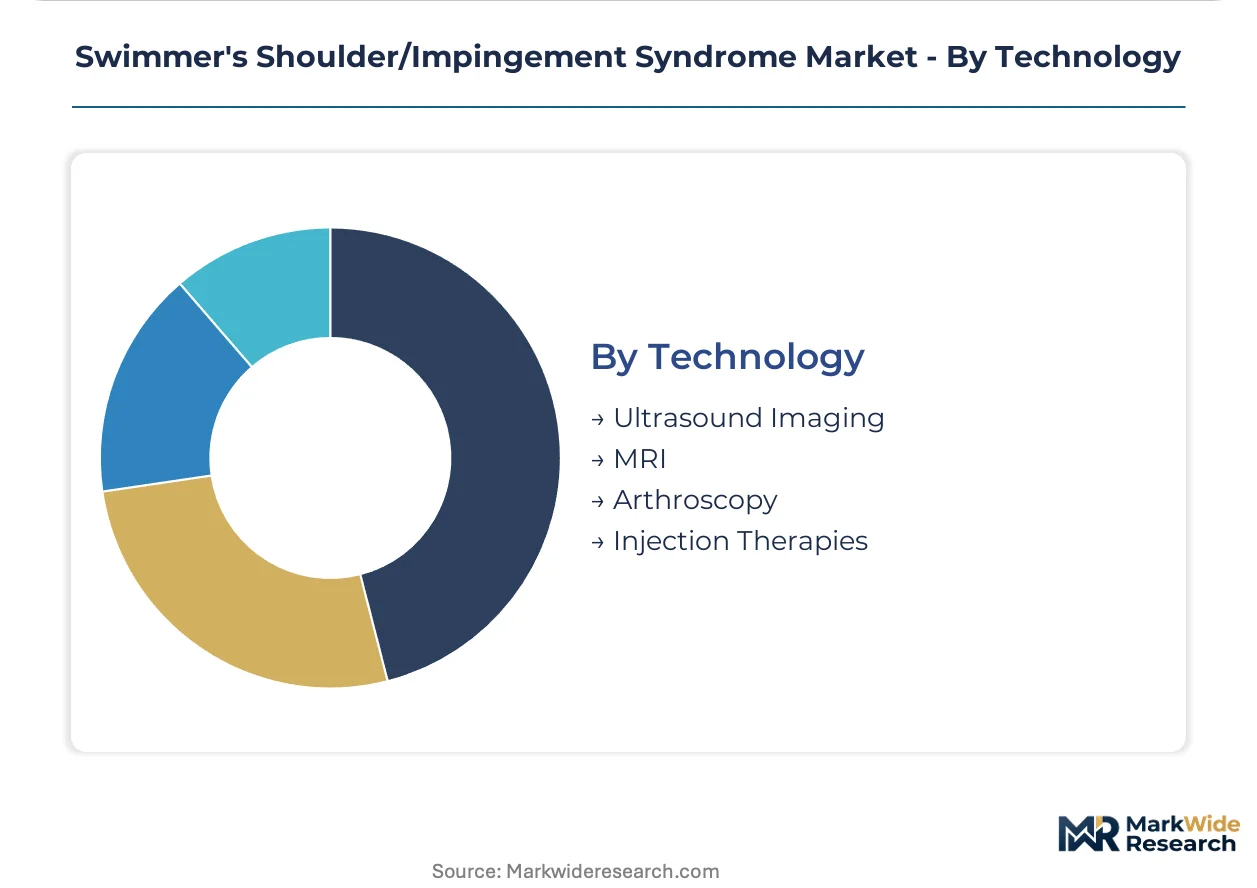
Technology:
Capital intensity and regulatory burden stratify competitive entry, with imaging platforms requiring FDA 510(k) or CE marking under EU MDR versus simpler injection modalities.
- Ultrasound Imaging:Portable systems with AI-assisted annotation digitize supraspinatus tendon assessment in collegiate athletic departments. FDA Breakthrough Devices Program designation accelerates review for novel platforms detecting collagen degradation products before structural failure.
- Arthroscopy:Integrated visualization and implant delivery systems compress diagnostic-to-intervention timelines in outpatient settings. Manufacturers bundle hardware with biologic delivery systems rather than selling discrete instruments to ambulatory surgery centers in Texas and California.
- MRI:High-field systems for tendon integrity confirmation in pre-surgical planning.
- Injection Therapies:Ultrasound-guided delivery of platelet-rich plasma and bone marrow concentrate.
Arthroscopy generates the highest equipment revenue per installation while ultrasound imaging expands its installed base most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic device manufacturing clusters in the United States and Germany supply arthroscopic platforms to high-volume sports medicine markets. FDA 510(k) clearance pathways and EU MDR certification requirements create divergent commercialization timelines across Atlantic markets. Australia and Japan sustain specialized demand through masters swimming demographics and high-performance athletic infrastructure.
United States
Collegiate swimming programs and ambulatory surgery center expansion drive instrument procurement across Florida and Arizona retirement corridors. CMS reimbursement adjustments for outpatient shoulder procedures reshape site-of-care economics between hospital operating rooms and freestanding facilities. Boston and Philadelphia academic medical centers anchor complex revision surgery volumes while maintaining fellowship training pipelines.
Germany
CE marking under EU MDR governs shoulder repair system commercialization, with notified body capacity constraints delaying quality management certification renewals. ATOS Klinik Heidelberg exemplifies specialized sports medicine infrastructure serving repetitive-motion athletes. Bavaria and Baden-Württemberg concentrate contract manufacturing serving tier-two orthopedic device firms.
Australia
Masters swimming leagues generate sustained demand for preventive diagnostics and early-intervention protocols among aging competitive athletes. TGA regulatory frameworks align with ISO 13485 quality management standards for imported implant systems. Sydney and Melbourne institute of sport networks mandate overhead athlete screening protocols that accelerate physical therapy equipment refresh cycles.
Japan
PMDA review timelines for novel diagnostic modalities extend market entry for AI-assisted tendinopathy detection platforms. METI industrial policy supports domestic arthroscopic visualization system development. Tokyo and Osaka high-performance training centers deploy dynamic ultrasound during championship seasons to triage overhead athletes without MRI scheduling delays.
Switzerland
Swissmedic certification requirements for biologic augmentation materials create first-mover advantage for compliant manufacturers of cellular products. Precision instrument manufacturing heritage supports specialized arthroscopic shaver and suture anchor production. Basel and Zurich clusters concentrate orthopedic research divisions of multinational device firms.
Swimmer's Shoulder/Impingement Syndrome Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the supply chain, supplying discrete instruments to bundled service contracts. The vendor base stratifies across three tiers: multinational conglomerates with full visualization-to-implant portfolios, mid-scale specialists in rotator cuff fixation or biologic augmentation, and regional contract manufacturers serving private-label channels. Consolidation pressures favor scaled producers with captive sterilization and processing capabilities. Geographic expansion into ambulatory surgery center corridors and strategic partnerships with collegiate athletic departments represent dominant competitive moves.
Among diversified orthopedic conglomerates, Johnson & Johnson Services and Stryker occupy positions spanning diagnostic imaging through surgical intervention. DePuy Synthes and Zimmer Biomet exemplify the integrated implant-and-instrument archetype, while Smith & Nephew represents biologic-augmentation-focused positioning. Arthrex and CONMED sit within the specialized sports medicine tier, with Medtronic anchoring the neuro-orthopedic crossover segment. ATOS Klinik Heidelberg GmbH & Co. KG represents the clinical-service-integrated model.
| Leading Market Players |
|---|
| Johnson & Johnson Services |
| DePuy Synthes |
| ATOS Klinik Heidelberg GmbH & Co. KG |
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| Arthrex |
| CONMED |
| Medtronic |
| Others |
Cost & Logistics Intelligence
The Port of Rotterdam to Basel pharmaceutical corridor carries cobalt-chromium and PEEK polymer feedstock for orthopedic implant manufacturing, with freight cost volatility amplifying margin pressure on mid-tier arthroscopic shaver producers while enabling premium pricing capture by integrated device firms with captive sterilization capabilities.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across premium, standard, and economy levels in arthroscopic repair platforms. Brand premium and ISO 13485 certification grade separate Stryker-integrated visualization systems from private-label contract manufacturer offerings. Cost compression in standard-tier suture anchors intensifies as cobalt-chromium feedstock volatility feeds through to contract manufacturers. Ambulatory surgery centers in Texas and Florida exhibit highest price sensitivity, while academic medical centers in Boston and Philadelphia prioritize performance metrics over unit cost.
Supply Chain Analysis
ISO 13485-certified contract manufacturers in Bavaria and Baden-Württemberg hold concentrated capacity for arthroscopic instrument sterilization and processing. Supply draws from German precision machining clusters, Swiss polymer extrusion facilities, and Taiwanese cobalt-chromium foundries. Single-source vulnerability in PEEK polymer feedstock creates exposure to medical-grade resin allocation constraints. Distribution runs through orthopedic GPO contracts and direct-to-hospital agreements with bundled implant-and-instrument accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of arthroscopic technician expertise for instrument processing and sterilization constrains ambulatory surgery center expansion, concentrating procurement leverage with manufacturers who embed training and certification into device contracts.
For Market Incumbents: Insulate market position by deepening backward integration into cobalt-chromium and PEEK polymer supply through long-term offtake agreements with German and Swiss raw material suppliers. Accelerate ISO 13485 certification renewal pipelines to outpace notified body capacity constraints that delay tier-two competitors. Counter dry needling and ultrasound-guided injection substitution by bundling AI-assisted diagnostic platforms with surgical instrument contracts. For New Entrants and Emerging Players: Pursue white-space positioning in AI-assisted dynamic ultrasound for early tendinopathy detection, where FDA Breakthrough Devices Program designation offers accelerated review timelines against entrenched MRI incumbents. Target Medicare Advantage-covered outpatient shoulder evaluation channels in Florida and Arizona retirement corridors. Deploy direct-to-consumer telehealth partnerships with masters swimming leagues as a bypass around orthopedic practice gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biologic-augmentation-focused device firms with EU MDR-compliant cellular product portfolios ahead of reclassification enforcement. Long-term viability hinges on ambulatory surgery center channel density and bundled payment model participation. Monitor CMS reimbursement adjustments for outpatient shoulder procedures as the primary inflection signal for site-of-care economics shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Devices Program Submission | Accelerated review timelines for AI-assisted tendinopathy detection platforms secure coding precedents before commercial launch. |
| Ambulatory Surgery Center Partnership | Texas and California freestanding orthopedic facilities seek bundled implant-and-instrument contracts with single-source accountability. |
| EU MDR Biologic Classification Compliance | Reclassified cellular augmentation products face elevated clinical evidence requirements, creating first-mover advantage for prepared manufacturers. |
| Collegiate Athletic Department Alliance | NCAA Division I programs deploy dynamic ultrasound during championship seasons, collapsing diagnostic-to-intervention timelines. |
| Backward Integration into Feedstock Supply | Cobalt-chromium and PEEK polymer offtake agreements with German and Swiss suppliers insulate against resin allocation volatility. |
Research Approach
A standing panel of arthroscopic surgeons, ambulatory surgery center administrators, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body certification logs. Bottom-up demand modeling across product type, end user, application, and technology segments triangulated with top-down market sizing from orthopedic device manufacturer revenue disclosures.
Scenario-bracketing around CMS reimbursement trajectory, EU MDR enforcement timing, and masters swimming demographic penetration anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include intervention modality, site-of-care economics, regulatory certification tier, and regional procurement authority. CAGRs derived from procedure volume elasticity to reimbursement adjustments and equipment replacement cycle compression in diagnostic platforms.
Macroeconomic conditions sit as an overlay; deviation in freight rates along the Rotterdam-Basel corridor or medical-grade polymer feedstock allocation would shift the trajectory. Quarterly review of CMS outpatient procedure reimbursement adjustments, FDA 510(k) clearance backlogs, and notified body ISO 13485 audit queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Gymnastic Hoops Market
Sports & Fitness
GCC Weight Management Market
Sports & Fitness
Skiing Equipment Market
Sports & Fitness
Shuttlecock Market
Sports & Fitness
UK Spectator Sports Market
Sports & Fitness
Military Fitness Training Equipment Market
Sports & Fitness
Middle East Sports Drinks Market
Sports & Fitness
South Korea Gym Accessories Market
Sports & Fitness
Speed Hurdle Market
Sports & Fitness
Saudi Arabia Health and Fitness Club Market
Sports & Fitness
L-Carnitine Supplements Market
Sports & Fitness
Badminton Equipment and Products Market
Sports & Fitness
Global Hydration Backpack Market
Sports & Fitness
Smart Fitness Market
Sports & Fitness
Mountain Bike Market
Sports & Fitness
Rubber Dumbbells Market