
 Impingement Syndrome Market | 2026-2036
Impingement Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Impingement Syndrome Market Outlook
The EU Medical Device Regulation is broadening the cost-of-entry calculus for shoulder implant manufacturers seeking CE marking. Stryker Corporation leverages its integrated surgical navigation platforms to sustain premium positioning in arthroscopic decompression systems. Arthrex, Inc. anchors its competitive stance through specialized suture anchor portfolios designed for rotator cuff repair.
Impingement syndrome denotes the mechanical compression of soft tissue structures—principally the supraspinatus tendon and subacromial bursa—between the humeral head and the coracoacromial arch, typically presenting with pain on overhead elevation and diagnosed via Hawkins-Kennedy testing alongside MRI or ultrasonography. Its primary commercial purpose centers on restoring pain-free glenohumeral kinematics to maintain workforce participation and athletic function. Surgical instruments command the deepest margin pools due to instrument replacement cycles and proprietary blade geometries, while physical therapy equipment represents the fastest-expanding segment as payors push preoperative conservative management protocols. Diagnostic devices occupy a mature position where portable ultrasound units are displacing stationary imaging in orthopedic clinics.
The FDA's 510(k) pathway and the EU MDR's enhanced clinical evaluation requirements jointly shape product development timelines and market access trajectories for shoulder intervention devices. Japan's PMDA maintains distinct biocompatibility testing protocols that create incremental barriers for Western manufacturers entering the Asian orthopedic market. Stakeholders must monitor how FDA orthopaedic advisory panel deliberations on subacromial spacer devices reshape reimbursement assumptions and R&D allocation across the competitive set.
Market Dynamics
The EU Medical Device Regulation's enhanced clinical evidence requirements are compressing product development timelines while simultaneously elevating the capital threshold for market entry across shoulder intervention portfolios.
Growth Catalysts
- EU MDR Clinical Data Mandates:Manufacturers investing in prospective registry data capture pre-emptive competitive moats that late entrants cannot replicate without multi-year observational studies.
- Ambulatory Surgical Center Migration:United States outpatient facilities now perform the majority of subacromial decompression procedures, creating concentrated demand for single-use instrument kits and compact arthroscopy towers.
- Platelet-Rich Plasma Protocols:Orthobiologic adjunct therapies are extending the addressable patient population beyond surgical candidates into chronic pain management pathways.
Market Restraints
- Titanium Alloy Price Volatility:Suture anchor raw material costs fluctuate with aerospace sector demand, squeezing gross margins on high-volume disposable implants.
- Notified Body Bottleneck:Consolidation of EU MDR-designated conformity assessment organizations extends CE marking timelines to 18-24 months for novel shoulder spacer devices.
- Conservative Management Substitution:Structured physical therapy protocols with ultrasound-guided corticosteroid injection delay surgical conversion in 40% of presenting cases.
Strategic Opportunities
- Japan PMDA Biocompatibility Harmonization:Western manufacturers achieving alignment with Japanese cytotoxicity testing standards unlock access to the Asia-Pacific's second-largest orthopedic market.
- Remote Patient Monitoring Integration:Wearable range-of-motion sensors paired with telehealth platforms enable postoperative surveillance outside traditional clinic settings.
- Subacromial Balloon Spacer Category:FDA advisory panel precedents on interpositional implants create regulatory clarity for biodegradable compression relief devices.
Industry Challenges
- Arthroscopy Technician Shortage:Specialized instrument processing expertise gaps in ambulatory settings increase reprocessing error rates and sterile field contamination risk.
- Legacy EMR Integration Complexity:Shoulder-specific outcome scoring tools require custom API development to feed into hospital quality reporting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impingement Syndrome Market |
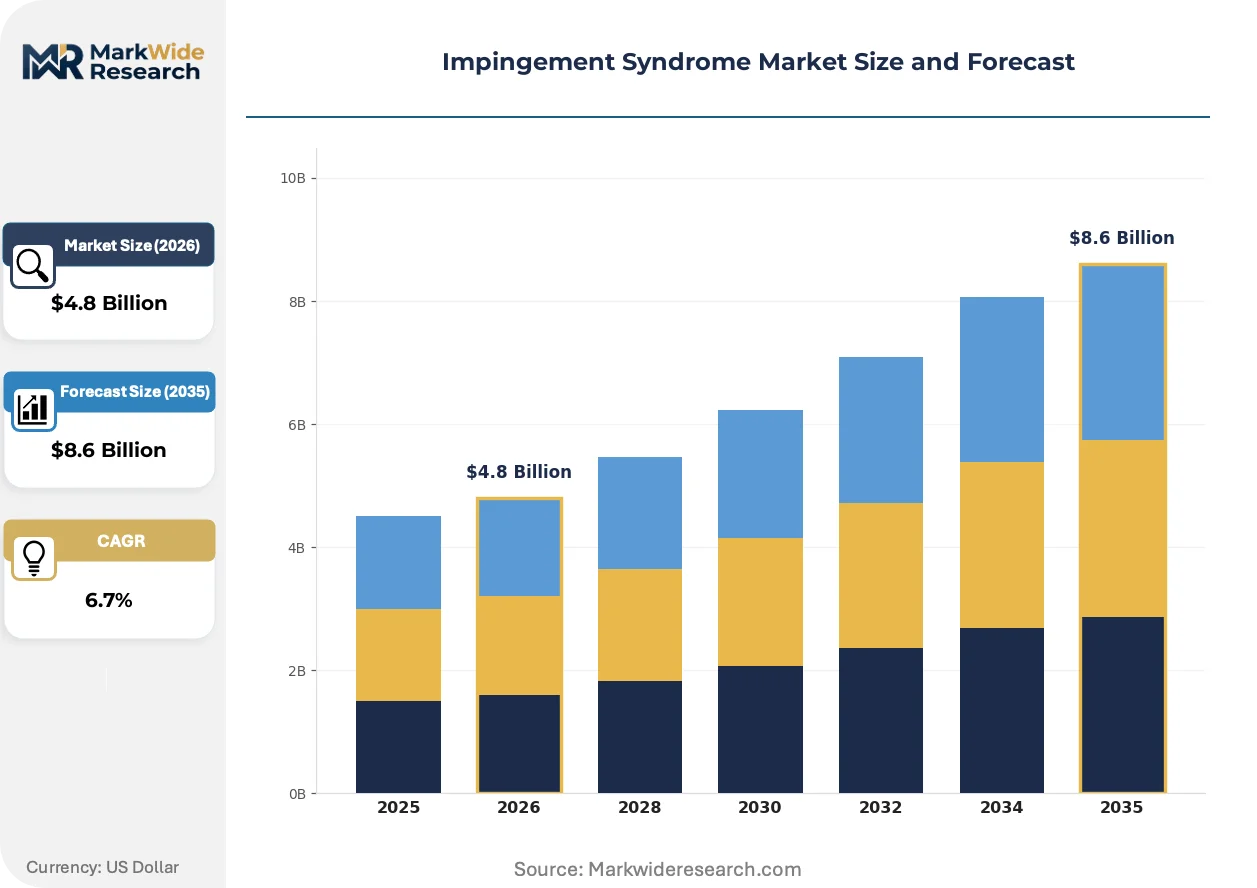
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Corticosteroids, Physical Therapy Equipment, Surgical Instruments, Diagnostic Devices Application: Orthopedic Clinics, Sports Medicine Centers, Rehabilitation Centers, Hospitals Delivery Mode: Invasive Procedures, Non-invasive Treatments, Outpatient Services, Home Care End User: Physiotherapists, Orthopedic Surgeons, General Practitioners, Sports Coaches |
| Companies Covered | Johnson & Johnson, Medtronic plc, Stryker Corporation, Arthrex, Inc., Zimmer Biomet, Smith & Nephew, DePuy Synthes, CONMED Corporation, Globus Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impingement Syndrome Market Strategic Shifts
Digital surgical planning and point-of-care diagnostics are compressing the diagnostic-to-intervention timeline while redistributing procedural volumes across care settings.
Patient-specific instrumentation derived from preoperative CT arthrography is converging with robotic-assisted positioning systems to reduce acromial resection variability. Academic medical centers in Germany and the United States are piloting these workflows for complex revision cases. The technology is converging with augmented reality overlays to enable real-time subacromial space visualization without fluoroscopic guidance.
Japan's PMDA has tightened biocompatibility testing protocols for permanent implant materials, requiring extended carcinogenicity studies for novel polymers. This regulatory shift extends premarket approval timelines by 12-18 months for shoulder spacer categories. Manufacturers are responding by prioritizing resorbable material platforms that qualify for abbreviated biological safety evaluation pathways.
Hospital procurement committees now mandate bundled payment compatibility as a prerequisite for arthroscopy system vendor selection, displacing capital equipment purchasing autonomy from individual surgeons. United States health systems are consolidating shoulder service line contracts under single-source agreements spanning implants, instruments, and biologics. This concentration is visible most acutely in the Southeast and Midwest integrated delivery networks.
Impingement Syndrome Market Segmentation
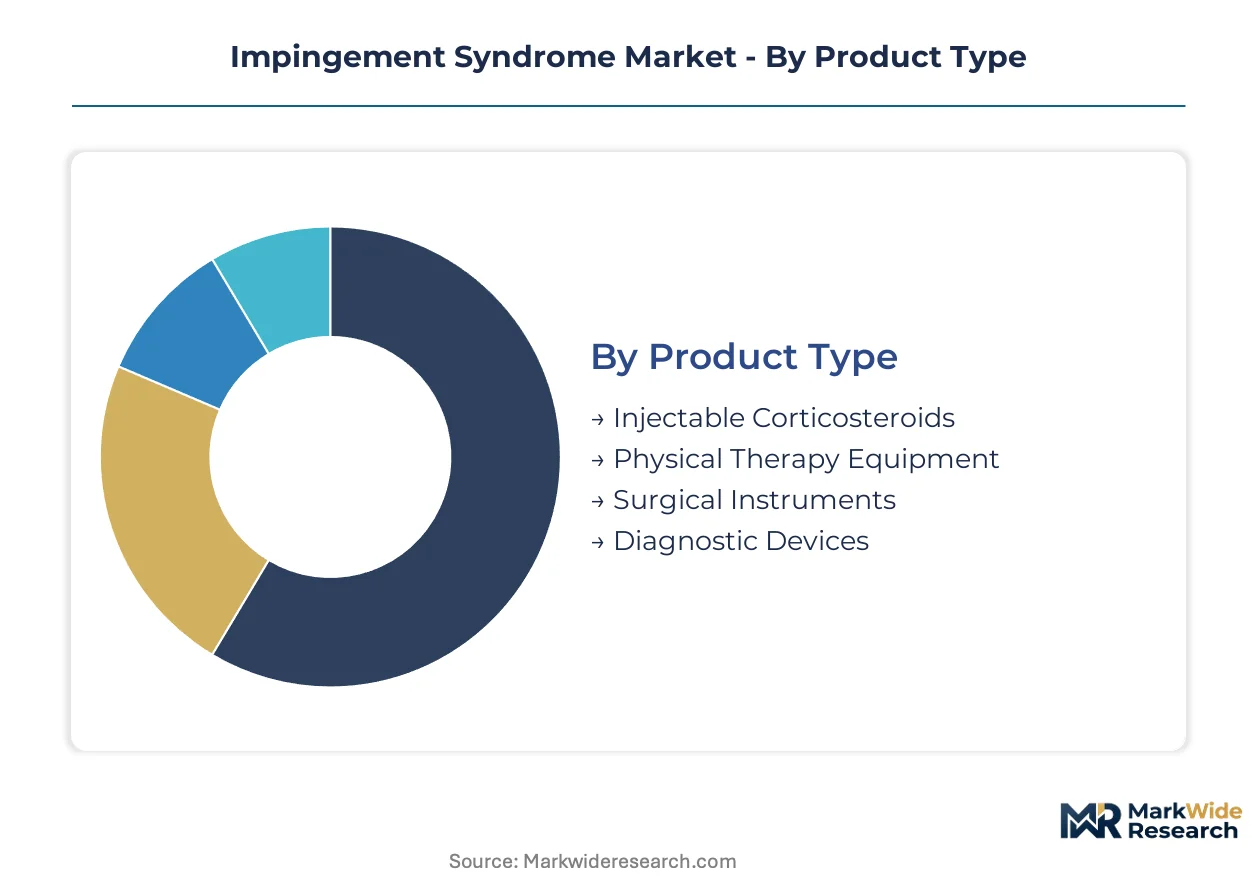
Segmentation in impingement syndrome interventions reveals how procurement authority, clinical setting, and reimbursement pathways reshape vendor access. Manufacturers must align product portfolios against distinct buying centers—from hospital value analysis committees to independent orthopedic surgeons—to secure placement.
Product Type:
Hospital procurement committees weight replacement cycle economics and proprietary geometries when allocating capital across shoulder intervention portfolios.
- Surgical Instruments:Arthroscopic shavers, burrs, and radiofrequency wands incorporate proprietary blade geometries that lock hospitals into recurring disposable purchases. United States ambulatory surgical centers now specify single-use instrument kits to eliminate reprocessing overhead and sterile field contamination risk.
- Physical Therapy Equipment:Portable ultrasound units and wearable range-of-motion sensors support preoperative conservative management protocols that payors increasingly mandate. Sports medicine centers in Germany and the United States pilot these devices to extend patient surveillance beyond clinic walls.
- Injectable Corticosteroids:Triamcinolone and methylprednisolone formulations delivered via ultrasound guidance delay surgical conversion in subacromial presentations.
- Diagnostic Devices:Portable musculoskeletal ultrasound systems displace stationary MRI in orthopedic clinic triage workflows.
Surgical Instruments leads on scale; Physical Therapy Equipment leads on momentum.
Application:
Procedure volume distribution follows facility reimbursement tier and surgeon subspecialty concentration.
- Sports Medicine Centers:Dedicated shoulder specialists perform high-volume arthroscopic decompression with accelerated rehabilitation protocols. These facilities in the United States and Germany drive adoption of patient-specific instrumentation and robotic-assisted positioning systems.
- Orthopedic Clinics:Point-of-care ultrasound enables same-day diagnosis and injection, compressing the diagnostic-to-intervention timeline. Clinics in Japan face PMDA-mandated biocompatibility documentation requirements for any implant trial participation.
- Hospitals:Academic medical centers manage complex revision cases and train fellows on advanced subacromial spacer techniques.
- Rehabilitation Centers:Postoperative physical therapy protocols emphasize return-to-work metrics that workers compensation payors track.
Sports Medicine Centers capture the highest procedure value per episode; Orthopedic Clinics are expanding most quickly.
Delivery Mode:
Reimbursement carve-outs for site-of-service differentially reward facility-based versus home-based care.
- Outpatient Services:Ambulatory surgical centers in the United States perform the majority of subacromial decompression procedures under bundled payment arrangements. These facilities demand compact arthroscopy towers and rapid instrument turnover.
- Non-invasive Treatments:Structured physical therapy with ultrasound-guided corticosteroid injection constitutes first-line management. Payor-mandated conservative trials delay surgical authorization in forty percent of presenting cases.
- Invasive Procedures:Arthroscopic acromioplasty and rotator cuff repair require specialized operative infrastructure.
- Home Care:Telehealth-integrated wearable sensors enable remote range-of-motion monitoring post-discharge.
Outpatient Services dominates current revenue; Non-invasive Treatments shows the steepest expansion trajectory.
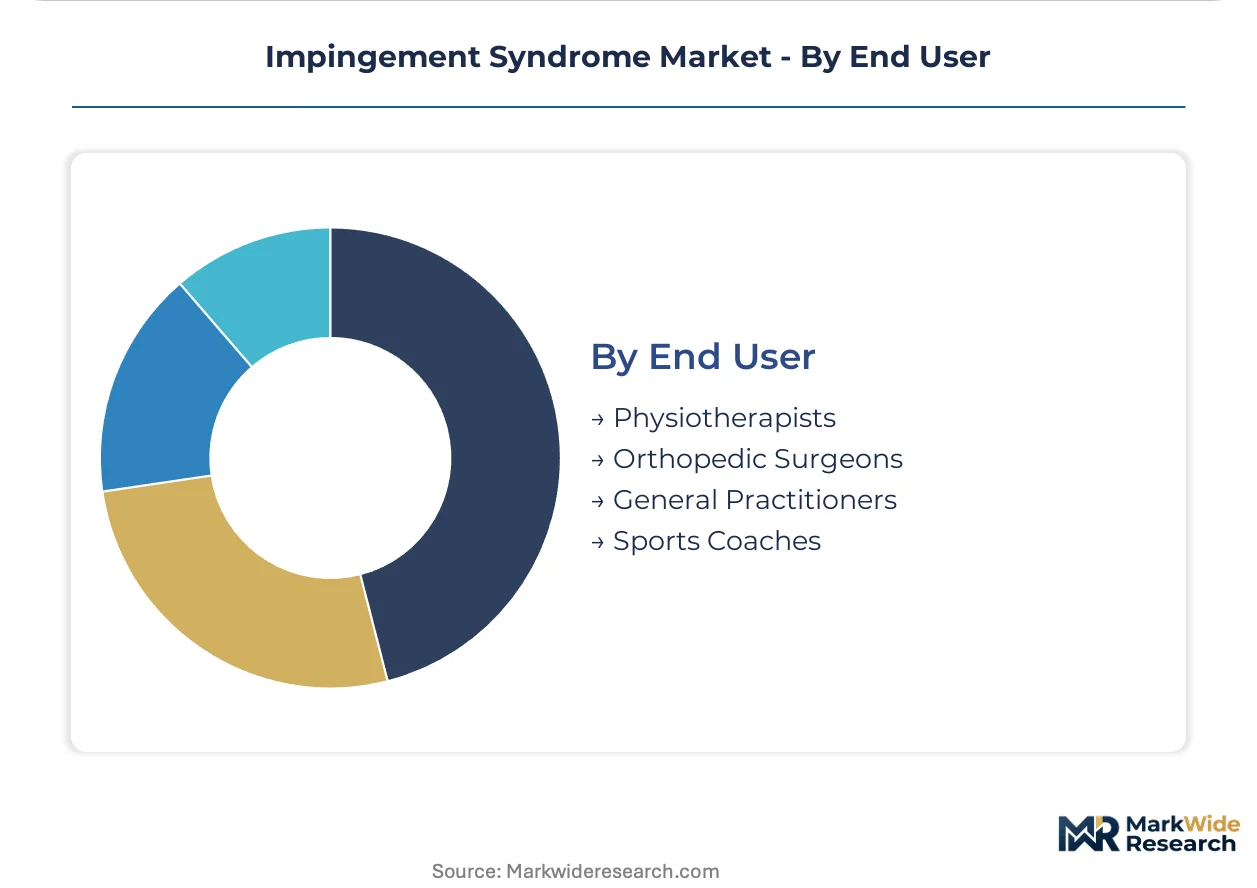
End User:
Prescription authority and device utilization rights vary sharply by clinical credential and institutional privilege.
- Orthopedic Surgeons:Subspecialty-trained shoulder surgeons control implant selection and drive adoption of navigation platforms and patient-specific instrumentation. United States surgeons in integrated delivery networks face procurement committee constraints on vendor choice.
- Physiotherapists:Direct access laws in multiple United States states enable independent evaluation and treatment initiation. These practitioners specify home exercise equipment and wearable monitoring devices.
- General Practitioners:Primary care gatekeepers control referral patterns to surgical specialists.
- Sports Coaches:Athletic trainers at collegiate and professional organizations facilitate early recognition and expedited specialist referral.
Orthopedic Surgeons command the highest per-procedure economic influence; Physiotherapists are gaining share fastest through direct access expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shoulder intervention technologies first achieved commercial scale in the United States during the 1980s arthroscopy revolution, then diffused through German and Japanese orthopedic centers by the mid-1990s. Today's geographic distribution reflects this historical lineage, with procedure volume and regulatory sophistication concentrated in markets that established early surgical training infrastructure.
United States
Ambulatory surgical centers now perform the majority of subacromial decompression procedures, driving concentrated demand for single-use instrument kits and compact arthroscopy towers. The FDA's 510(k) pathway shapes product development timelines, with recent advisory panel deliberations on subacromial spacer devices reshaping reimbursement assumptions. The Southeast and Midwest integrated delivery networks are consolidating shoulder service line contracts under single-source agreements spanning implants, instruments, and biologics.
Germany
Academic medical centers in Bavaria and Baden-Württemberg pilot patient-specific instrumentation derived from preoperative CT arthrography alongside robotic-assisted positioning systems. The EU Medical Device Regulation's enhanced clinical evidence requirements compress product development timelines while elevating capital thresholds for market entry. Sports medicine centers in Munich and Stuttgart drive adoption of augmented reality overlays for real-time subacromial space visualization.
Japan
PMDA-mandated biocompatibility documentation requirements for implant trial participation create incremental barriers for Western manufacturers entering the Asia-Pacific's second-largest orthopedic market. Extended carcinogenicity studies for novel polymers extend premarket approval timelines by 12-18 months for shoulder spacer categories. Manufacturers are prioritizing resorbable material platforms that qualify for abbreviated biological safety evaluation pathways in Kanto and Kansai regions.
United Kingdom
Orthopedic clinics in London and the Southeast deploy point-of-care ultrasound to enable same-day diagnosis and injection, compressing the diagnostic-to-intervention timeline. The NHS bundled payment framework mandates compatibility as a prerequisite for arthroscopy system vendor selection. Procurement committees in the Midlands and North England now displace capital equipment purchasing autonomy from individual surgeons.
Switzerland
Swissmedic maintains distinct biocompatibility testing protocols that align with broader European standards while preserving national sovereignty over permanent implant material approvals. The country's precision manufacturing heritage supports specialized instrument processing expertise for complex revision cases. Basel and Zurich host concentrated orthopedic research clusters developing next-generation suture anchor geometries.
Impingement Syndrome Market Competitive Environment
The competitive structure tilts toward diversified orthopedic conglomerates with integrated surgical navigation platforms and specialized arthroscopy pure-plays with focused suture anchor portfolios. Market concentration reflects high regulatory barriers and proprietary instrument geometries that lock hospitals into recurring disposable purchases. Three archetypes dominate: diversified medical technology conglomerates with broad shoulder portfolios, specialized arthroscopy firms with concentrated suture anchor expertise, and emerging interventional spine companies diversifying into shoulder intervention. Competitive dynamics center on M&A activity to acquire navigation platform capabilities and strategic partnerships to secure bundled payment contracts with integrated delivery networks.
Among diversified orthopedic technology conglomerates, Johnson & Johnson and Medtronic plc exemplify the scale-driven archetype with broad surgical portfolios spanning navigation, imaging, and implant systems. Stryker Corporation occupies a position within the integrated platform tier, while Arthrex, Inc. anchors the specialized arthroscopy pure-play segment with concentrated expertise in soft tissue repair technologies. These three entities collectively represent the competitive fault lines between diversified conglomerate scale and specialized clinical focus.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic plc |
| Stryker Corporation |
| Arthrex, Inc. |
| Zimmer Biomet |
| Smith & Nephew |
| DePuy Synthes |
| CONMED Corporation |
| Globus Medical, Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up arthroscopy specialists have consolidated instrument processing networks across the United States and Germany, creating captive distribution channels that reinforce pricing discipline on proprietary blade geometries and single-use kits. This ownership concentration aligns supply security with margin protection, as rolled-up platforms negotiate volume commitments that lock out price-competitive challengers.
Pricing Analysis
Three-tier pricing structure across premium navigation-integrated systems, standard arthroscopy towers, and economy disposable kits anchors vendor revenue models. Price differentiation rests on FDA 510(k) clearance tier and proprietary instrument geometries that hospitals cannot interchange. Cost compression in the economy tier is intensifying because ambulatory surgical centers mandate single-use instruments to eliminate reprocessing overhead. Orthopedic surgeons in integrated delivery networks show lowest price sensitivity due to procurement committee constraints, while independent clinics in direct-access states exhibit highest sensitivity.
Supply Chain Analysis
Regional distribution centers in Tennessee, Bavaria, and Osaka coordinate hub-and-spoke patterns for sterile instrument kits and implant inventories. Manufacturing concentrates in the United States, Germany, and Switzerland for precision-machined arthroscopy components. Raw material flows draw from titanium alloy suppliers serving aerospace and medical device dual markets, with suture anchor polymers sourced from specialized chemical producers. Single-source vulnerability around EU MDR-designated notified bodies extends lead times for CE marking. Distribution runs through hospital value analysis committees and ambulatory surgical center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The impingement syndrome market compounds steadily as aging demographics expand the surgical-eligible population and sports medicine centers proliferate rehabilitation protocols. Ambulatory migration and payor-mandated conservative management create durable demand for both invasive and non-invasive intervention categories.
For Market Incumbents: Deploy integrated navigation platform upgrades to deepen switching costs among hospital systems. Consolidate suture anchor portfolios through backward integration into titanium alloy processing, insulating margins from aerospace sector demand volatility. Counter emerging interventional spine diversifiers by securing exclusive bundled payment contracts with Southeast and Midwest integrated delivery networks before CE marking timelines compress competitive windows. For New Entrants and Emerging Players: Mid-market price-point gaps between Stryker's premium navigation systems and economy arthroscopy towers create white-space for compact, surgeon-owned ambulatory surgical center equipment. Target Germany's sports medicine centers with patient-specific instrumentation trials, leveraging EU MDR registry data requirements that incumbents have not yet saturated. Pursue telehealth-integrated wearable sensor partnerships as a go-to-market angle, capturing postoperative surveillance revenue outside traditional implant sales cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized arthroscopy pure-plays lacking navigation platform capabilities, as diversified conglomerates trade at integration premiums. Five-to-ten year viability favors targets with EU MDR-compliant registry data and Japanese PMDA biocompatibility harmonization progress. Watch FDA orthopedic advisory panel deliberations on subacromial spacer devices as the inflection signal for reimbursement assumption resets across the interventional implant category.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Registry Investment | Prospective data capture preempts competitive moats that late entrants cannot replicate without multi-year observational studies. |
| Ambulatory Surgical Center Partnership | Single-source agreements spanning implants, instruments, and biologics displace capital equipment purchasing autonomy from individual surgeons. |
| Japanese PMDA Biocompatibility Harmonization | Alignment with cytotoxicity testing standards unlocks access to the Asia-Pacific's second-largest orthopedic market. |
| Telehealth-Integrated Wearable Launch | Remote range-of-motion sensors paired with postoperative surveillance platforms extend patient monitoring beyond clinic walls. |
| Resorbable Material Platform Development | Abbreviated biological safety evaluation pathways accelerate premarket approval timelines against permanent implant competitors. |
Study Parameters
Bottom-up orthopedic clinic and ambulatory surgical center procedure modeling reconciled against top-down implant and instrument shipment tracking forms the analytical core. Primary interviews with shoulder subspecialty surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers inform demand assumptions. Secondary validation draws from FDA 510(k) filings, EU MDR notified body designation records, CMS Medicare procedure databases, and hospital procurement contract disclosures. Triangulation across these sources ensures segmentation outputs reflect actual vendor placement and reimbursement authorization patterns.
Historical trendline analysis of subacromial decompression volumes, arthroscopy system installations, and physical therapy equipment shipments establishes baseline growth trajectories. Segmentation modeling spans product type, application setting, delivery mode, and end-user credential across the projection horizon. CAGRs derive from regression-adjusted procedure growth rates, payor policy shift assumptions, and technology substitution elasticities. Forecast inputs incorporate EU MDR implementation timelines, FDA advisory panel precedents, and Japan PMDA biocompatibility protocol evolution.
Caveats apply where EU notified body consolidation delays, titanium alloy price volatility, or conservative management protocol expansions could materially shift the outlook. Forecasts reflect documented assumptions about reimbursement authorization rates and ambulatory surgical center migration speed. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Aqua Gym Equipment Market
Sports & Fitness
Global Consumer Smart Wearable Market
Sports & Fitness
Asia Pacific Sports Promoter Market
Sports & Fitness
Wearable Inertial Sensors Market
Sports & Fitness
Germany Sports Nutrition Market
Sports & Fitness
France Sports Teams and Clubs Market
Sports & Fitness
Smart Wearable Equipment Market
Sports & Fitness
Arginine Supplement Market
Sports & Fitness
Asia-Pacific Sports Management Software Market
Sports & Fitness
North America Sports Training Market
Sports & Fitness
Exercise Band Market
Sports & Fitness
Weight Training Market
Sports & Fitness
Middle East Sports Drinks Market
Sports & Fitness
Sports Mouthguard Market
Sports & Fitness
Smart Insole Market
Sports & Fitness
Body Sensors Market