
 Sustainable Fabrics Market | 2026-2036
Sustainable Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Fabrics Market Outlook
Textile chemistry expertise is bifurcating the competitive landscape between legacy dye houses and bio-based innovators. Lenzing AG dominates wood-derived cellulosic fiber production through its proprietary closed-loop manufacturing. Unifi Inc. leverages bottle-to-fiber recycling infrastructure across the southeastern United States. Toray Industries anchors technical performance segments with petroleum-alternative polymers for sportswear applications.
Sustainable fabrics are textile materials engineered from renewable, recycled, or low-environmental-impact feedstocks, typically certified to standards such as OEKO-TEX or GOTS, and manufactured with reduced water consumption, energy use, or chemical inputs. Organic cotton and Tencel command premium positioning in fashion apparel due to consumer-facing traceability and softness performance. Recycled polyester sustains cost-competitive supply for activewear as rPET flake availability tightens. Hemp occupies niche upholstery channels where durability and natural antimicrobial properties offset processing roughness.
The EU Green Deal and REACH chemical restrictions are forcing reformulation across European supply chains, while EPA industrial discharge rules shape North American wet-processing economics. OEKO-TEX and GRS certification now function as de facto market access requirements for brands selling into regulated jurisdictions. Stakeholders must monitor feedstock cost volatility between agricultural commodities and petroleum derivatives when committing to capacity expansion or long-term supplier contracts.
Market Dynamics
The EU Green Deal textile regulations are compressing chemical disclosure timelines and mandating recycled content minimums, forcing dyehouses and fiber producers to reconfigure wet-processing infrastructure and feedstock sourcing strategies ahead of enforcement deadlines.
Growth Catalysts
- REACH chemical restrictions:ECHA's expanded SVHC candidate list is accelerating substitution of azo dyes and formaldehyde-based finishes across European supply chains, creating certified-fiber demand pull.
- Organic cotton cultivation:Agricultural extension programs in India and Turkey are expanding GOTS-certified acreage, reducing premium pricing gaps versus conventional cotton for apparel brands.
- Closed-loop manufacturing:Solvent recovery systems in lyocell production are cutting per-unit water intensity below 5% of conventional viscose, attracting ESG-mandated institutional capital.
Market Restraints
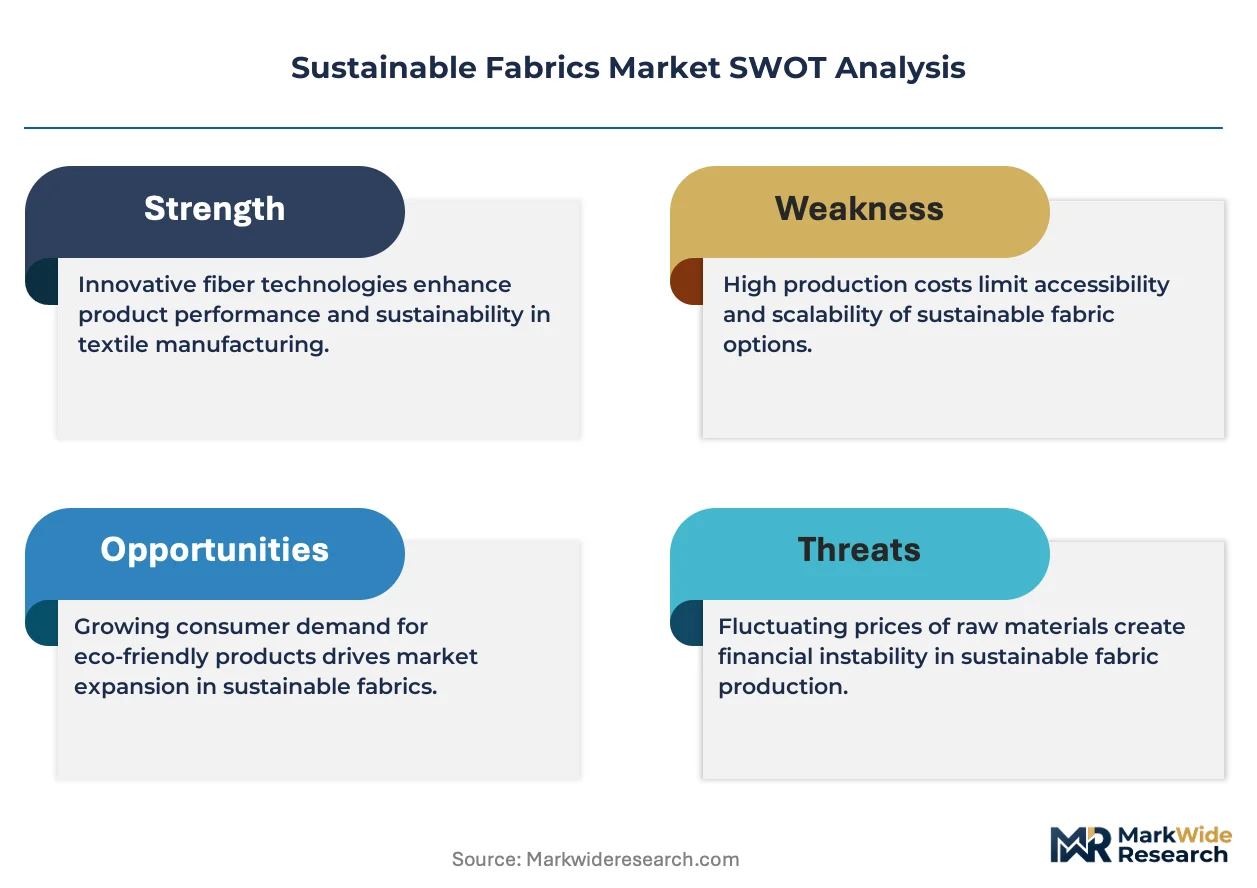
- Agricultural commodity volatility:Organic cotton premiums swing 40-80% above conventional futures depending on monsoon patterns in Maharashtra and Gujarat, compressing spinner margins.
- rPET flake concentration:Bottle collection infrastructure clusters in the southeastern United States and Taiwan, creating transoceanic shipping dependencies for European recycled polyester producers.
- Technical performance ceiling:Bio-based polyesters from succinic acid feedstocks currently max at 85% of petroleum-based PET tensile strength, limiting adoption in high-abrasion sportswear.
Strategic Opportunities
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive requires Scope 3 textile emissions disclosure from 2026, creating first-mover advantage for suppliers with verified LCA data.
- Indonesia industrial zones:Batang and Kendal special economic zones offer 10-year tax holidays for renewable fiber manufacturing, attracting backward integration from finished apparel exporters.
- Mycelium leather hybrids:Bolt Threads and MycoWorks materials are penetrating luxury accessories as chrome-tanned leather faces ECHA restriction proposals, opening premium pricing tiers.
Industry Challenges
- Certification audit backlogs:GOTS and OEKO-TEX inspection body capacity constraints are extending certification timelines to 14-18 months, delaying product launches for seasonal collections.
- Textile chemistry skill scarcity:Formulation expertise in bio-based dye affinity and enzymatic finishing concentrates among retiring specialists in Basel and Ludwigshafen clusters, constraining R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Fabrics Market |
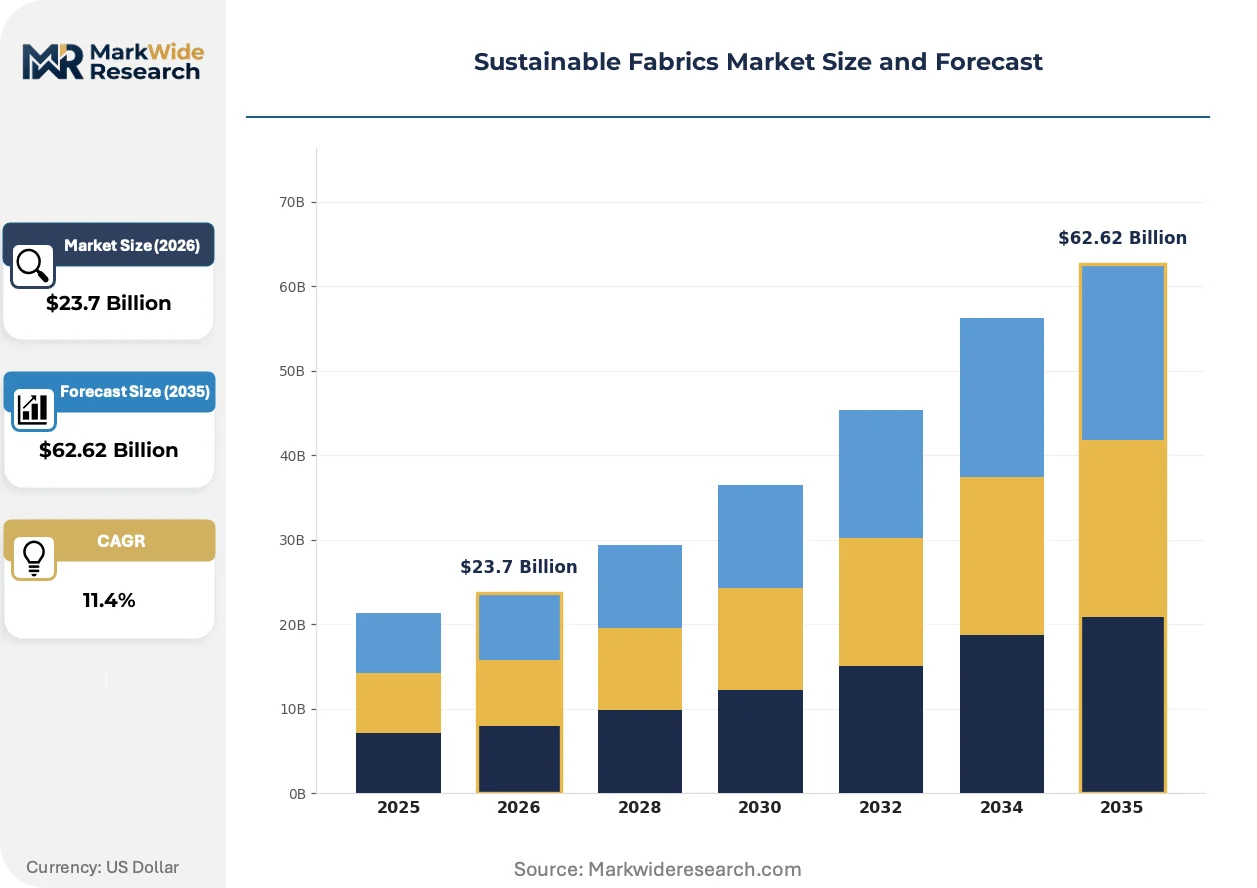
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Organic Cotton, Hemp, Recycled Polyester, Tencel Fabric Usage: Activewear, Home Textiles, Fashion Apparel, Upholstery Production Method: Low-Impact Dyeing, Weaving, Knitting, Biodegradable Treatments Target Market: Eco-Conscious Consumers, Fashion Brands, Interior Designers, Manufacturers |
| Companies Covered | Glen Raven, Eagle Fabrics, Lenzing AG, DuPont, Toray Industries, Milliken & Company, Sino Silk, Hyosung, Unifi Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Fabrics Market Strategic Shifts
Digital traceability infrastructure and enzymatic processing breakthroughs are compressing the gap between laboratory-scale bio-innovation and commercial textile volumes, reshaping how brands verify and communicate sustainability claims.
Enzymatic textile finishing is supplanting conventional caustic soda and chlorine-based pre-treatments in cotton preparation. Denim laundries in Mexico and Bangladesh are adopting cellulase and laccase systems to achieve vintage abrasion effects without potassium permanganate spraying. This shift is compressing wastewater treatment capital requirements while eliminating hazardous chemical handling permits.
EU Green Deal textile regulations now mandate separate collection of discarded garments from 2025, with EPR schemes requiring producer financing of sorting infrastructure. France's Refashion eco-organization is already operationalizing reverse logistics networks, while Germany's Zentek certification is emerging as the compliance benchmark. Premium apparel brands are pre-positioning take-back programs to capture secondary fiber feedstocks ahead of quota obligations.
Direct-to-brand fiber sourcing is disrupting traditional yarn trader intermediation in organic cotton procurement. Mara Hoffman and Reformation are contracting directly with Ivorian and Ugandan grower cooperatives, bypassing Alexandria and Hamburg commodity houses. This channel compression is most advanced in California and New York headquarters clusters, where sustainability teams negotiate bale-specific provenance documentation.
Sustainable Fabrics Market Segmentation
Segmentation in sustainable fabrics reveals how certification requirements, performance specifications, and end-use durability demands fragment procurement strategies across apparel and interior applications. Material origin and processing chemistry now function as gatekeepers to premium pricing tiers and regulatory compliance.
Material Type:
REACH chemical restrictions and EU Green Deal textile mandates are bifurcating feedstock sourcing between agricultural cellulosics and recycled synthetics, with certification intensity determining market access.
- Organic Cotton:Cultivated without synthetic pesticides or fertilizers under GOTS certification, this fiber delivers traceable provenance for EU market entry. Demand concentrates in German and French fashion houses where EPR schemes and consumer willingness to pay premiums outpace other European markets.
- Tencel:Lenzing AG's proprietary lyocell fiber utilizes closed-loop solvent recovery systems that cut water intensity below 5% of conventional viscose. Procurement from Austrian and Indonesian production facilities is accelerating as CSRD disclosure mandates drive Scope 3 emissions accounting.
- Hemp:Bast fiber with natural antimicrobial properties and superior tensile durability for upholstery applications.
- Recycled Polyester:rPET flake-based fiber facing feedstock concentration risks from southeastern United States and Taiwan collection infrastructure.
Organic cotton handles the majority of throughput; Tencel is climbing the fastest on share as closed-loop manufacturing attracts ESG-mandated institutional capital.
Fabric Usage:
End-use durability requirements and wash-cycle intensity create divergent material specifications across consumer and contract applications.
- Fashion Apparel:Premium positioning depends on OEKO-TEX and GOTS certification for direct-to-consumer traceability, with softness and drape performance driving organic cotton and Tencel adoption in German and California headquarters clusters.
- Activewear:High-abrasion sportswear demands petroleum-alternative polymers with technical performance approaching conventional PET, though bio-based polyesters from succinic acid feedstocks currently max at 85% tensile strength.
- Home Textiles:Bedding and bath applications prioritizing GOTS-certified organic cotton for skin-contact safety.
- Upholstery:Contract and residential furniture requiring hemp's durability and natural antimicrobial resistance.
Fashion apparel commands the dominant revenue share; activewear represents the steepest expansion trajectory as rPET supply constraints ease.
Production Method:
Water intensity and chemical discharge regulations are reshaping wet-processing economics across dyeing, finishing, and mechanical formation stages.
- Low-Impact Dyeing:Waterless and supercritical CO2 systems eliminate effluent treatment capital while meeting EPA industrial discharge rules and REACH SVHC substitution mandates for azo dye phase-out.
- Biodegradable Treatments:Enzymatic finishing with cellulase and laccase systems replaces caustic soda and chlorine pre-treatments, compressing hazardous chemical handling permits in Mexican and Bangladeshi denim laundries.
- Weaving:Mechanical interlacing of warp and weft yarns for structural stability in upholstery and technical applications.
- Knitting:Loop formation for stretch and recovery in activewear and intimate apparel.
Low-impact dyeing processes the largest volume; biodegradable treatments are gaining share fastest as enzymatic systems achieve vintage abrasion effects without potassium permanganate.
Target Market:
Procurement authority and sustainability mandate intensity vary sharply between institutional buyers and dispersed consumer segments.
- Fashion Brands:Mara Hoffman and Reformation are contracting directly with Ivorian and Ugandan grower cooperatives, bypassing Alexandria and Hamburg commodity houses to secure bale-specific provenance documentation for CSRD compliance.
- Eco-Conscious Consumers:Premium willingness-to-pay clusters in Germany and California drive certified organic cotton and Tencel demand, with Zentek certification emerging as the German compliance benchmark.
- Interior Designers:Contract specification for hemp upholstery and GOTS-certified textiles in commercial hospitality projects.
- Manufacturers:Tier-1 and tier-2 suppliers integrating backward into renewable fiber production in Batang and Kendal Indonesian special economic zones.
Fashion brands direct the largest procurement volumes; eco-conscious consumers are expanding most quickly as take-back programs pre-position for EU separate collection mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German procurement concentrates on certified organic cotton and Tencel for premium apparel traceability, while Indonesian manufacturers exploit SEZ tax holidays for backward integration into renewable fiber production. United States demand clusters around rPET-based activewear as EPA discharge rules reshape wet-processing economics.
Germany
Zentek certification operates as the compliance benchmark for circular economy legislation, with consumer willingness-to-pay premiums outpacing other European markets. The EU Green Deal textile regulations mandate separate garment collection from 2025, forcing brands to pre-position take-back programs. Hamburg and Berlin headquarters clusters direct direct-to-grower contracting with Ivorian and Ugandan cooperatives.
United States
EPA industrial discharge rules compress wet-processing capital requirements in southeastern dye houses, while rPET flake infrastructure concentrates bottle-to-fiber recycling in North Carolina and South Carolina. California and New York sustainability teams negotiate bale-specific provenance documentation for CSRD-aligned disclosure. Unifi Inc. anchors this regional recycling corridor with established collection networks.
Indonesia
Batang and Kendal special economic zones offer 10-year tax holidays attracting renewable fiber manufacturing investments from finished apparel exporters. The country's central bank monitors feedstock cost volatility between agricultural commodities and petroleum derivatives for capacity planning. Jakarta-based procurement teams coordinate lyocell sourcing from domestic Lenzing AG facilities for regional brand supply.
India
Agricultural extension programs in Maharashtra and Gujarat expand GOTS-certified organic cotton acreage, though monsoon patterns swing premiums 40-80% above conventional futures. The Bureau of Indian Standards tracks chemical disclosure alignment with REACH SVHC substitution timelines. Tiruppur and Surat textile clusters adopt enzymatic finishing systems to eliminate hazardous chemical handling permits.
France
Refashion eco-organization operationalizes reverse logistics networks ahead of EU EPR scheme deadlines, with Paris-based luxury houses pioneering mycelium leather hybrids for accessories. ANSM monitors chrome-tanned leather restriction proposals affecting upholstery procurement. Lyon and Marseille industrial zones concentrate low-impact dyeing infrastructure for waterless supercritical CO2 systems.
Sustainable Fabrics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in sustainable fabrics, with closed-loop manufacturers and recycling infrastructure operators commanding premium positioning. The upper tier consolidates around wood-derived cellulosic fiber production and bottle-to-fiber recycling systems, while mid-tier players compete on certification velocity and regional feedstock access. Three archetypes dominate: Austrian-Indonesian integrated cellulosic producers, American rPET recycling specialists, and Japanese technical performance polymer developers. Competitive moves concentrate on backward integration into renewable feedstocks and enzymatic processing technology licensing.
Among integrated cellulosic specialists, Lenzing AG exemplifies the closed-loop manufacturing archetype with Austrian and Indonesian production footprints. Unifi Inc. represents the American rPET recycling infrastructure model, while Toray Industries anchors technical performance segments with petroleum-alternative polymer development. These three occupy distinct competitive vectors—feedstock integration, recycling scale, and performance engineering—without direct overlap in core capabilities.
| Leading Market Players |
|---|
| Glen Raven |
| Eagle Fabrics |
| Lenzing AG |
| DuPont |
| Toray Industries |
| Milliken & Company |
| Sino Silk |
| Hyosung |
| Unifi Inc. |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month GOTS certification timelines compress inventory turns and amplify pricing power for pre-certified suppliers serving EU-bound apparel brands. This lead-time band concentrates procurement leverage among Austrian and Indonesian lyocell producers with established OEKO-TEX documentation, while spinner margins erode when organic cotton premiums spike during monsoon disruptions.
Pricing Analysis
Long-term offtake contracts dominate premium fiber procurement as brands lock in GOTS-certified organic cotton and Tencel volumes ahead of CSRD disclosure mandates. Price differentiation rests on certification tier—OEKO-TEX Standard 100 versus MADE IN GREEN—and geographic delivery cost from Austrian versus Indonesian production bases. Cost compression in mid-tier recycled polyester intensifies as rPET flake availability tightens in southeastern United States collection corridors. Fast-fashion private labels exhibit highest price sensitivity; luxury houses anchored in Paris and Milan demonstrate lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Indian and Turkish organic cotton shipments to German spinning clusters. Feedstock sourcing draws from Maharashtra and Gujarat agricultural belts, Austrian wood pulp facilities, and southeastern United States bottle collection infrastructure. Single-source vulnerability concentrates in Lenzing AG's proprietary lyocell solvent recovery systems. Distribution runs through Alexandria and Hamburg commodity houses for conventional channels, with direct-to-grower contracting bypassing intermediaries for certified provenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sustainable fabrics market tracks a cyclical recovery pattern as EU Green Deal enforcement deadlines synchronize procurement cycles and inventory restocking across European apparel supply chains.
For Market Incumbents: Consolidate certification audit capacity through exclusive partnerships with GOTS and OEKO-TEX inspection bodies to compress 14-18 month timelines and defend against emerging bio-based fiber entrants. Lock in backward integration into Indonesian Batang and Kendal special economic zones to capture 10-year tax holidays before quota exhaustion. Prioritize enzymatic finishing technology licensing to Mexican and Bangladeshi denim laundries seeking potassium permanganate substitution.
For New Entrants and Emerging Players: White-space gaps in verified LCA data services for CSRD-aligned Scope 3 disclosure offer immediate service-layer entry points. Target midsize German fashion houses lacking in-house sustainability teams for direct-to-grower contracting facilitation. Penetrate through mycelium leather hybrid sourcing for luxury accessories as ECHA chrome-tanning restrictions advance.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Green Deal textile mandates and REACH SVHC expansions create durable competitive moats for pre-certified suppliers. Acquisition focus centers on Indonesian renewable fiber manufacturing assets with established Lenzing AG technology licensing. Monitor ECHA restriction proposal timelines for chrome-tanned leather as inflection signal for mycelium leather valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | Captures Indonesian SEZ tax holidays and secures lyocell pulp supply for EU brands. |
| Enzymatic Processing Technology Licensing | Enables Bangladeshi denim laundries to eliminate potassium permanganate permits and REACH non-compliance. |
| Direct-to-Grower Contracting Programs | Bypasses Alexandria and Hamburg commodity houses for bale-specific CSRD documentation. |
| Certification Audit Capacity Expansion | Compresses 14-18 month GOTS timelines to capture seasonal collection windows. |
| Mycelium Leather Hybrid Development | Positions luxury accessories suppliers ahead of ECHA chrome-tanning restriction enforcement. |
Study Parameters
Cross-validation between primary interviews with fiber procurement directors, sustainability officers at German and California headquarters clusters, and GOTS certification body representatives anchors the qualitative findings. Secondary validation draws from EU Green Deal regulatory filings, ECHA SVHC candidate list updates, Bureau of Indian Standards chemical disclosure alignments, and SEC filings from listed textile chemistry firms. Bottom-up volume modeling from individual production facility capacities triangulates against top-down apparel brand procurement disclosures.
Sensitivity analysis around organic cotton premium volatility and rPET flake availability shapes the analytical framework across the projection horizon. Segmentation dimensions include material origin, certification tier, end-use durability requirements, and production method water intensity. CAGRs derive from weighted average of historical capacity expansion patterns and regulatory mandate phase-in schedules. Feedstock cost volatility between agricultural commodities and petroleum derivatives, plus enzymatic processing adoption curves, constitute industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU REACH and Green Deal textile regimes; material policy shifts would require re-modeling. Agricultural commodity volatility from monsoon pattern disruption and ECHA restriction proposal acceleration for chrome-tanned leather represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles
Smart Textiles for Military Market
Textiles
Textile Auxiliaries Market
Textiles
Direct to Garment Printing Market
Textiles
North America Technical Textiles Market
Textiles
Silicone Fabrics Market
Textiles
Spandex Fiber Market
Textiles
Nonwoven Decking Market
Textiles
Textile Floorings Market
Textiles
Arm Pouches Market
Textiles
Wool Worsted Yarn Market
Textiles
US Digital Printed Textile Market
Textiles
Foot Mask Market
Textiles
Italy Textile Manufacturing Market
Textiles
Uniform Market
Textiles
Knitting Cam Market
Textiles
Active Smart Textiles Market