
 Global Nuclear Magnetic Resonance (NMR) Spectrometer Market | 2026-2036
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market Foresight
A shift from single-source magnet procurement to multi-source component sourcing is restructuring supply economics for NMR system builders. Bruker Corporation leverages its captive superconducting wire production to control critical input costs. JEOL Ltd. anchors its position through integrated gradient coil manufacturing in Japan. Thermo Fisher Scientific Inc. competes by extending its service network density across North American and European research clusters.
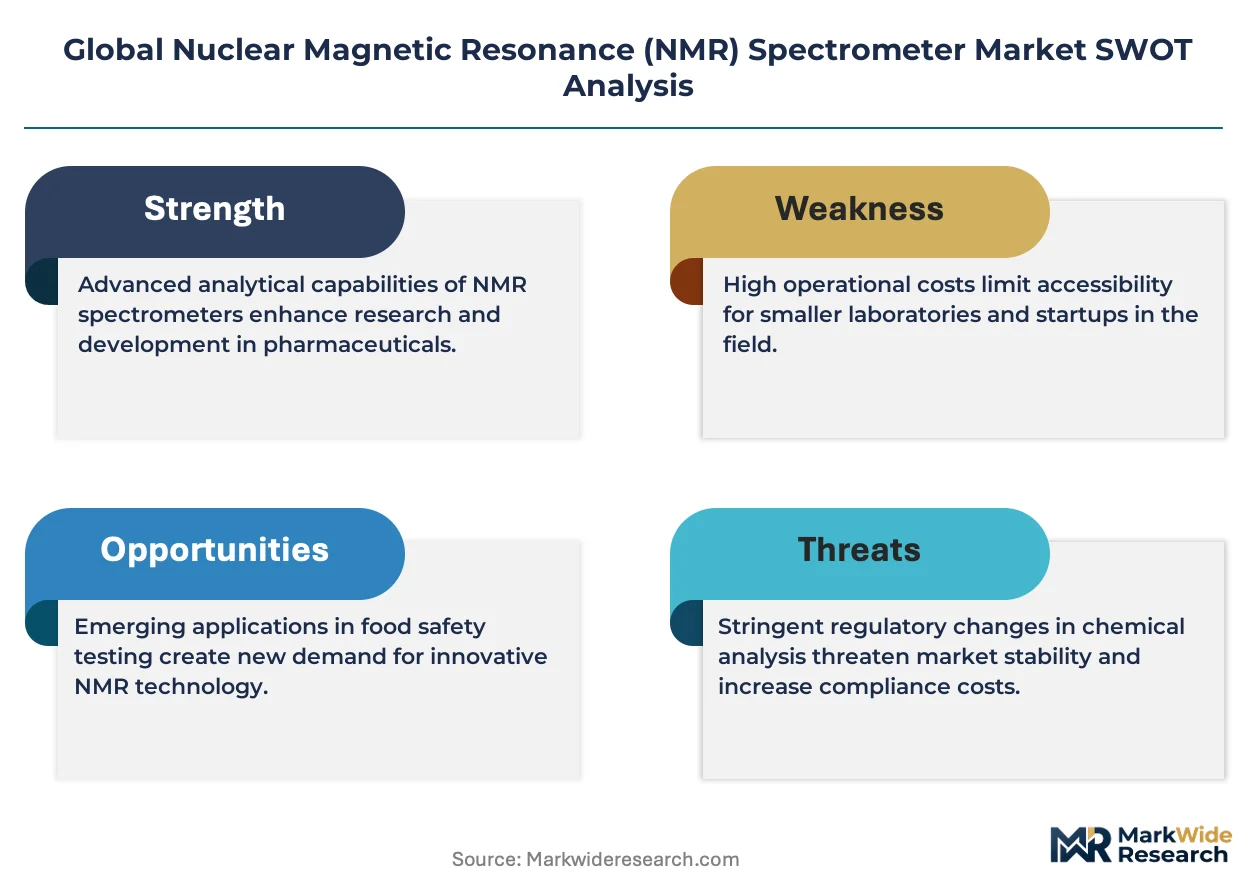
A nuclear magnetic resonance spectrometer applies strong homogeneous magnetic fields, typically 300 to 1000 MHz proton frequency, to induce and detect nuclear spin transitions for molecular structure determination. Pharmaceutical quality control laboratories employ these systems to verify compound identity, purity, and stereochemistry with non-destructive sampling. High-field NMR systems command the largest installed base among product categories due to their irreplaceable resolution for complex natural product elucidation. Solid-state NMR technology shows the fastest expansion trajectory as battery and catalyst researchers adopt it for amorphous material characterization. Drug development applications concentrate the highest margin pool because regulatory submission requirements mandate comprehensive spectroscopic documentation.
FDA validation guidelines for analytical methods in pharmaceutical manufacturing directly shape NMR instrument specifications and software compliance requirements in the United States. EMA's ICH Q6A guidelines and REACH chemical registration mandates in Europe drive parallel demand for traceable spectroscopic data packages. ISO/IEC 17025 accreditation standards govern calibration protocols that laboratories must maintain for cross-border result acceptance. Stakeholders should monitor how tightening export controls on superconducting materials affect magnet lead times and regional pricing asymmetries.
Market Dynamics
Cryogen-free magnet technology is compressing total cost of ownership and expanding addressable laboratory segments beyond traditional high-budget research institutions.
Growth Catalysts
- REACH chemical registration mandates:European manufacturers must submit traceable spectroscopic data packages for substance approval, creating mandatory procurement of compliant NMR systems.
- Battery material research:Solid-state NMR adoption is accelerating among lithium-ion and solid-state electrolyte developers for amorphous structure characterization.
- Contract research organization expansion:CROs in the United States, Germany, and China are maintaining active instrument replacement cycles to service pharmaceutical outsourcing demand.
Market Restraints
- Superconducting wire supply concentration:Niobium-titanium and niobium-tin conductor production concentrates among limited specialty metal suppliers, exposing magnet lead times to raw material volatility.
- High-field system capex thresholds:800-1000 MHz installations require dedicated facility infrastructure including cryogen storage and magnetic shielding, restricting placement to capital-flush institutions.
- Skilled operator scarcity:PhD-level spectroscopist availability lags instrument deployment, particularly in mid-sized analytical service laboratories.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO regulatory alignment with ICH guidelines is creating demand for qualification-ready NMR systems in API and formulation facilities.
- Artificial intelligence spectral interpretation:Machine learning deconvolution tools are converging with automation workflows to reduce analysis time and operator dependency.
- Service contract unbundling:Third-party maintenance providers are capturing aftermarket service revenue from legacy installed bases through ISO/IEC 17025-accredited calibration protocols.
Industry Challenges
- Legacy software integration:Pharmaceutical quality control laboratories face friction connecting modern spectrometers to validated LIMS environments without triggering requalification timelines.
- Export control compliance:Tightening restrictions on superconducting material shipments are forcing manufacturers to reconfigure regional assembly and magnet sourcing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nuclear Magnetic Resonance (NMR) Spectrometer Market |
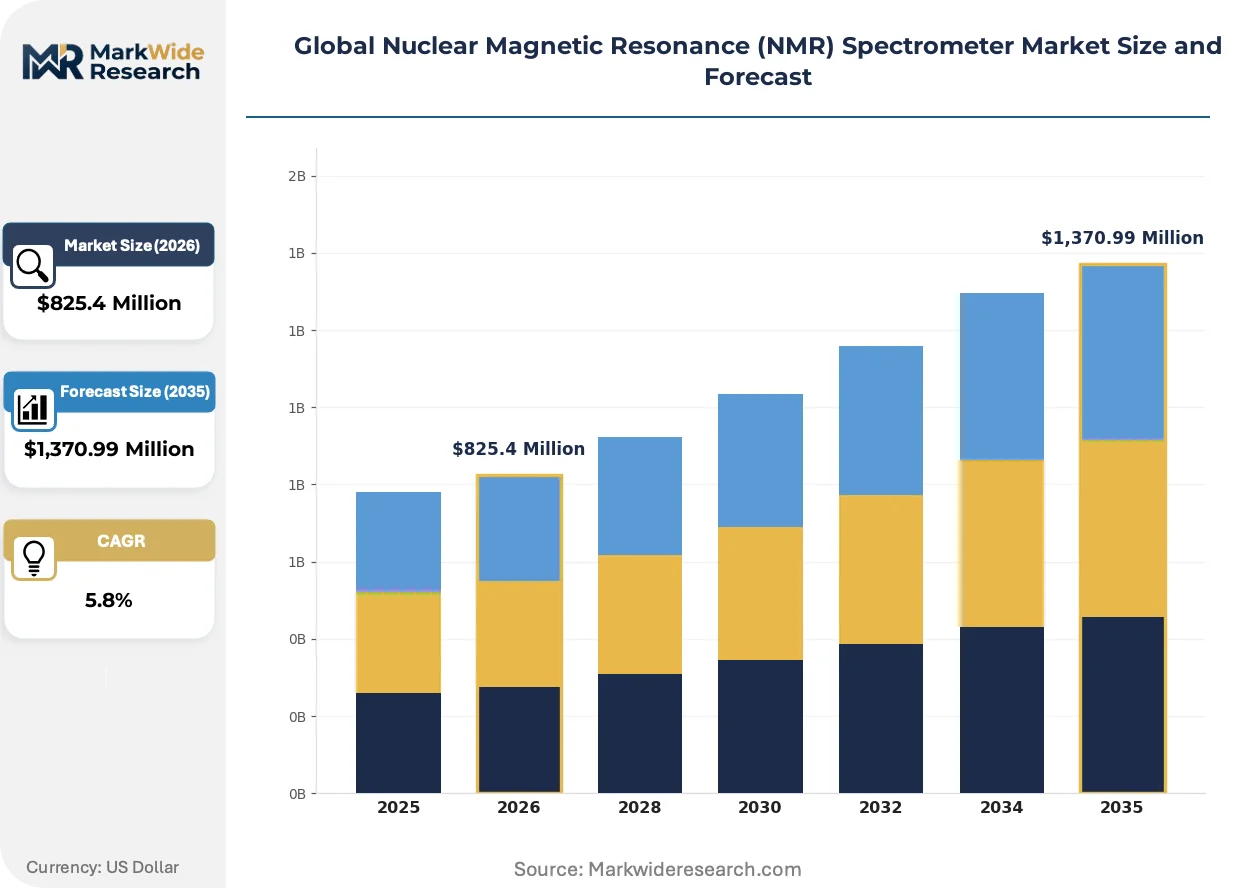
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,370.99 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Field NMR, Bench-Top NMR, Nuclear Overhauser Effect NMR, Fourier Transform NMR End User: Pharmaceutical Industry, Academic Research, Chemical Industry, Biotechnology Technology: Proton NMR, Carbon-13 NMR, Solid-State NMR, Relaxation NMR Application: Drug Development, Quality Control, Chemical Analysis, Material Science |
| Companies Covered | Bruker Corporation, JEOL Ltd., Thermo Fisher Scientific Inc., Oxford Instruments plc, Nanalysis Scientific Corp., Magritek, Anasazi Instruments, Inc., QoneTec, Advanced Magnetic Resonance Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market Shifts & Advancements
Automation and computational integration are compressing analytical timelines while regulatory digitization is reshaping data integrity requirements across pharmaceutical and chemical manufacturing.
Cryogen-free permanent magnet systems are converging with benchtop form factors to enable deployment in process chemistry and teaching laboratories previously excluded by infrastructure demands. Specialty chemical manufacturers in Japan and South Korea are adopting these systems for rapid reaction monitoring. The technology is converging with cloud-based spectral libraries to reduce local computational requirements and accelerate structure confirmation workflows.
EMA's ICH Q14 analytical procedure development guidelines are mandating enhanced method understanding documentation that elevates NMR's role in quality control dossiers. Pharmaceutical sponsors must now demonstrate spectroscopic method robustness across deliberate parameter variations. European generic drug manufacturers are responding by upgrading to 400-600 MHz systems with enhanced software validation packages.
Academic consortia are consolidating core facility access through shared instrumentation models rather than individual departmental ownership. Major research universities in the United States are centralizing high-field NMR operations under staffed core facilities with fee-for-service structures. This concentration is visible most prominently in Boston and San Diego research clusters where multi-investigator access agreements replace siloed instrument purchases.
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market Segmentation
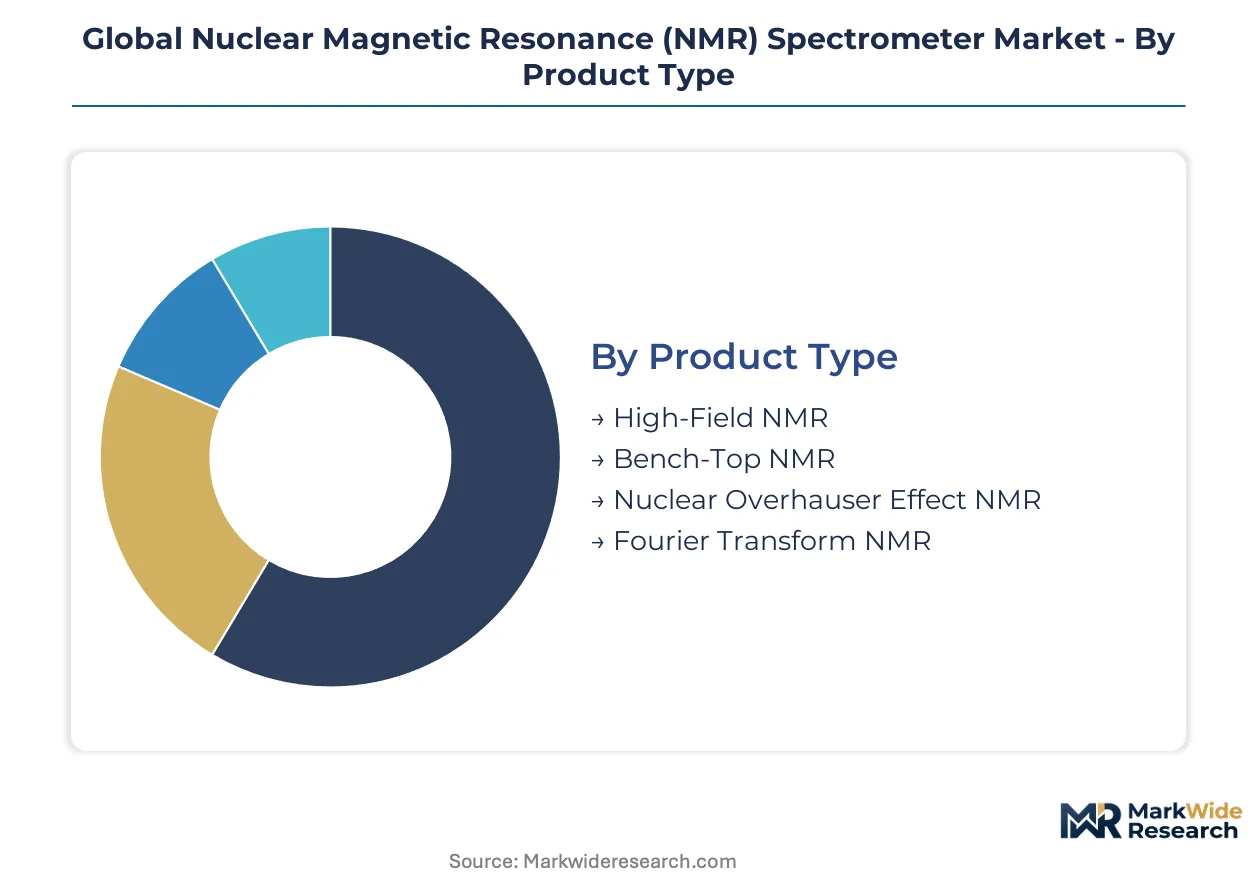
NMR spectrometer segmentation reflects divergent capital deployment strategies across research-intensive sectors. Procurement patterns split sharply between facilities requiring maximum resolution and those prioritizing throughput or accessibility.
Product Type:
Capital intensity and infrastructure requirements separate buyers into distinct budget tiers with different replacement cycles.
- High-Field NMR:Systems operating at 600 MHz and above deliver sub-part-per-billion resolution for complex natural product elucidation. Pharmaceutical quality control laboratories in the United States and Germany maintain the densest installed bases, driven by FDA and EMA regulatory submission requirements for comprehensive spectroscopic documentation.
- Bench-Top NMR:Cryogen-free permanent magnet designs eliminate facility infrastructure demands, enabling deployment in process chemistry and teaching laboratories. Specialty chemical manufacturers in Japan and South Korea are adopting these systems for rapid reaction monitoring where space constraints previously excluded conventional platforms.
- Nuclear Overhauser Effect NMR:Specialized configurations exploit through-space dipolar coupling for three-dimensional structure determination in biological macromolecules.
- Fourier Transform NMR:Signal processing architecture enables rapid pulse-sequence acquisition for high-throughput screening environments.
High-Field NMR leads volumes today; Bench-Top NMR is gaining share fastest.
End User:
Research orientation versus commercial production creates divergent specifications around automation and validation documentation.
- Pharmaceutical Industry:Quality control and drug development applications mandate 21 CFR Part 11-compliant software with full audit trails. CDSCO regulatory alignment with ICH guidelines in India is expanding qualification-ready system demand across API manufacturing facilities.
- Academic Research:Core facility consolidation at major United States universities is shifting procurement toward multi-investigator service models with fee-for-service structures. Boston and San Diego research clusters exemplify this concentration trend.
- Chemical Industry:REACH registration mandates in Europe require traceable spectroscopic data packages, creating mandatory procurement of compliant systems for substance approval.
- Biotechnology:Protein characterization workflows drive demand for high-sensitivity cryogenic probe configurations in recombinant therapeutic development.
Pharmaceutical Industry leads volumes today; Academic Research is gaining share fastest.
Technology:
Nucleus-specific detection capabilities determine application suitability across molecular structure problems.
- Proton NMR:Highest sensitivity natural abundance detection dominates routine structure confirmation. Battery material researchers in China are deploying proton-based systems for electrolyte characterization alongside solid-state platforms.
- Solid-State NMR:Magic-angle spinning techniques enable amorphous and crystalline material characterization inaccessible to solution methods. Lithium-ion and solid-state electrolyte developers are accelerating adoption for non-crystalline structure determination.
- Carbon-13 NMR:Low natural abundance necessitates isotopic enrichment or extended acquisition times for detailed connectivity mapping.
- Relaxation NMR:Time-domain measurements probe molecular dynamics and diffusion coefficients for formulation science applications.
Proton NMR leads volumes today; Solid-State NMR is expanding most quickly.
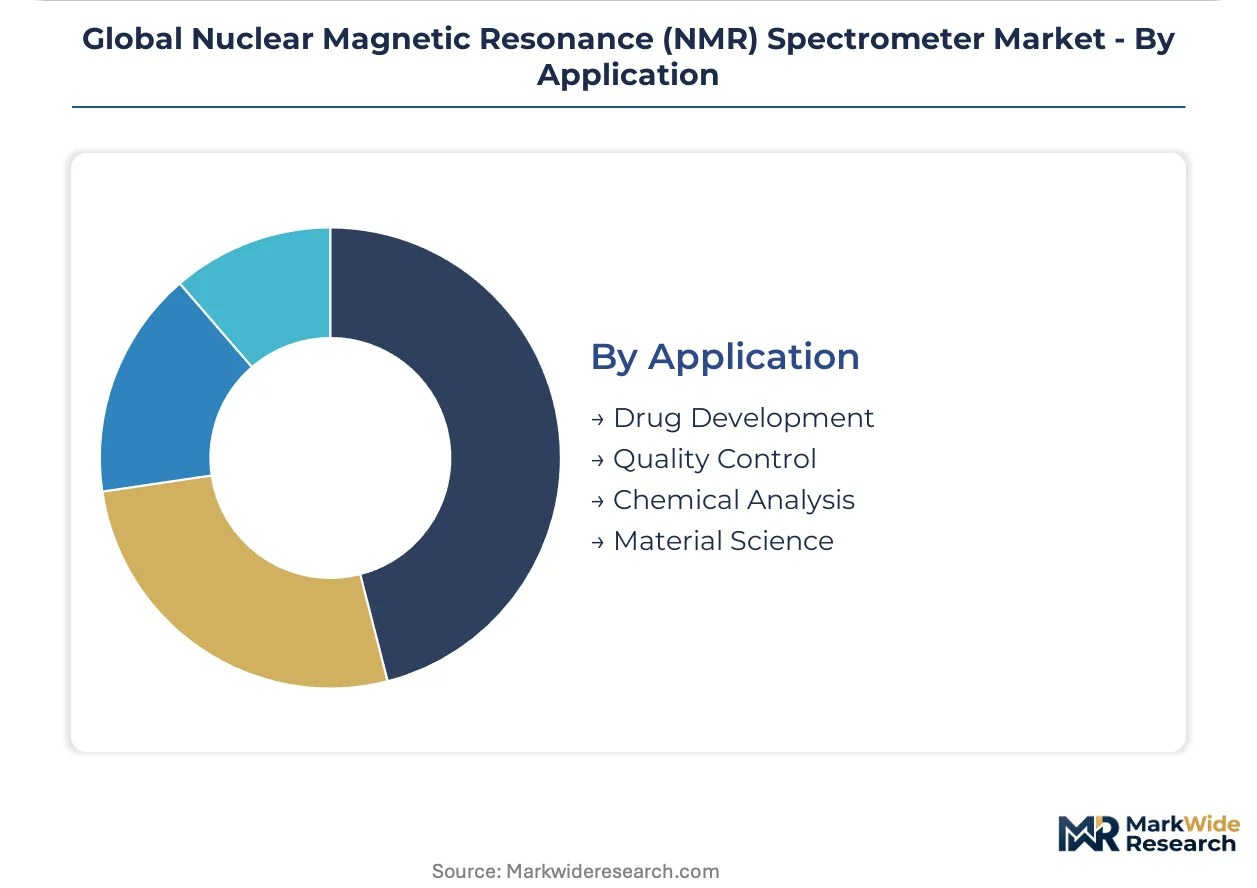
Application:
Regulatory documentation burden and analytical throughput requirements shape instrument configuration priorities.
- Drug Development:Comprehensive spectroscopic documentation for IND and NDA submissions commands premium pricing. EMA ICH Q14 guidelines now mandate enhanced method understanding documentation that elevates NMR's role in quality control dossiers.
- Quality Control:Validated LIMS integration and automated sample changers dominate procurement specifications for release testing laboratories.
- Chemical Analysis:Reaction monitoring and impurity profiling applications favor mid-field systems with rapid turnaround capabilities.
- Material Science:Battery, catalyst, and polymer researchers drive solid-state NMR adoption for amorphous structure characterization where diffraction methods fail.
Drug Development leads volumes today; Material Science is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Diego research clusters anchor pharmaceutical NMR procurement in the United States, while German chemical manufacturing and Chinese battery research drive parallel demand concentrations across three continents.
United States
FDA validation guidelines for analytical methods shape instrument specifications for pharmaceutical quality control laboratories. 21 CFR Part 11 compliance mandates drive software procurement decisions among drug manufacturers. Boston and San Diego research clusters concentrate core facility consolidation under multi-investigator access agreements.
Germany
REACH chemical registration mandates create mandatory procurement of compliant NMR systems for substance approval. EMA ICH Q6A guidelines and ICH Q14 analytical procedure development standards govern quality control documentation requirements. The Rhine-Ruhr industrial corridor maintains dense installed bases serving chemical manufacturing and contract research organizations.
China
Battery material researchers accelerate solid-state NMR adoption for lithium-ion and solid-state electrolyte characterization. NMPA regulatory alignment with international standards expands qualification-ready system demand across API facilities. Yangtze River Delta research institutes concentrate high-field system procurement for natural product elucidation.
Japan
Specialty chemical manufacturers adopt cryogen-free benchtop systems for rapid reaction monitoring in space-constrained process laboratories. METI industrial technology programs support advanced materials characterization infrastructure. Osaka and Nagoya industrial clusters drive compact system deployment for manufacturing quality control.
India
CDSCO regulatory alignment with ICH guidelines creates demand for qualification-ready NMR systems in API and formulation facilities. Pharmaceutical manufacturing expansion drives instrument replacement cycles among contract research organizations. Maharashtra and Gujarat pharmaceutical corridors concentrate procurement activity for export-oriented production.
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cryogen-free and benchtop configurations. The vendor base splits between integrated magnet manufacturers and component assemblers sourcing superconducting wire externally. Three archetypes dominate: captive superconducting wire producers controlling input costs, integrated gradient coil fabricators, and service-network extenders competing on aftermarket density. Consolidation pressures favor backward integration into critical magnet components and geographic assembly reconfiguration under tightening export controls.
Among diversified analytical instrument conglomerates, Bruker Corporation and Thermo Fisher Scientific Inc. exemplify scale-driven archetypes with extensive service infrastructures. JEOL Ltd. represents the integrated manufacturing specialist archetype with captive production capabilities. Oxford Instruments plc anchors the cryogen-free technology segment. These three companies collectively illustrate how competitive positioning diverges between superconducting system heritage and emerging permanent-magnet disruptors.
| Leading Market Players |
|---|
| Bruker Corporation |
| JEOL Ltd. |
| Thermo Fisher Scientific Inc. |
| Oxford Instruments plc |
| Nanalysis Scientific Corp. |
| Magritek |
| Anasazi Instruments, Inc. |
| QoneTec |
| Advanced Magnetic Resonance Limited |
| Others |
Supply & Pricing Matrix
Niobium-titanium superconducting wire pricing propagates from specialty metal refiners in the United States and Japan through magnet manufacturers to downstream system assemblers, compressing margins at each tier as export licensing delays extend procurement cycles.
Pricing Analysis
Input-cost pass-through from niobium-titanium and niobium-tin conductor suppliers drives pricing stratification across premium, standard, and economy tiers. FDA 21 CFR Part 11 certification and ISO/IEC 17025 accreditation create price differentiation between pharmaceutical-grade and teaching-laboratory configurations. Pricing pressure stems from cryogen-free permanent magnet alternatives displacing mid-field superconducting systems in process chemistry applications. Academic core facilities exhibit highest price sensitivity due to shared-instrument funding models, while contract research organizations demonstrate lowest sensitivity given regulatory submission timelines.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical and academic procurement, with authorized distributors serving mid-sized analytical service laboratories in India and Southeast Asia. Superconducting wire production concentrates in the United States, Japan, and Germany, with gradient coil fabrication anchored in Japanese manufacturing clusters. Magnet assembly depends on helium logistics infrastructure and specialized cryogenic engineering talent concentrated in European and North American facilities. Single-source vulnerability in niobium-titanium conductor supply exposes lead times to mining output fluctuations and export control restrictions. Distribution runs through Bruker and JEOL captive service networks for high-field installations, with third-party maintenance providers penetrating legacy installed bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogen-free magnet technology is compressing manufacturing costs while solid-state NMR applications command premium pricing, creating margin expansion headroom for vendors with permanent-magnet intellectual property.
For Market Incumbents: Anticipate displacement pressure from benchtop NMR entrants in teaching and process chemistry segments by accelerating cryogen-free product line development. Secure backward integration into superconducting wire supply through long-term offtake agreements with niobium refiners to insulate against export control disruptions. Prioritize ISO/IEC 17025-accredited service network density in India and China to defend aftermarket revenue from third-party calibration providers. For New Entrants and Emerging Players: CDSCO regulatory alignment with ICH guidelines in India opens a window for qualification-ready benchtop system penetration in API manufacturing facilities previously priced out of superconducting platforms. Target battery material research laboratories in China and Germany with solid-state NMR configurations optimized for amorphous electrolyte characterization. Pursue cloud-based spectral library partnerships to reduce local computational requirements and accelerate structure confirmation workflows. For Investors and Strategic Acquirers: Roll-up economics work for cryogen-free technology specialists because permanent-magnet manufacturing scales with consumer electronics component sourcing rather than superconducting material constraints. Five-to-ten year viability favors vendors with integrated gradient coil production and software validation packages. Watch for inflection when export control restrictions force regional magnet assembly reconfiguration, creating acquisition opportunities among component-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Magnet Platform Expansion | Permanent-magnet designs eliminate helium infrastructure demands, opening mid-sized laboratory segments previously excluded. |
| Cloud-Integrated Spectral Library Partnership | Remote computational processing reduces local hardware requirements for structure confirmation workflows. |
| ISO/IEC 17025 Service Network Accreditation | Third-party calibration providers capture aftermarket revenue from legacy superconducting installed bases. |
| Backward Integration into Superconducting Wire | Captive niobium-titanium supply insulates magnet lead times from raw material volatility and export controls. |
| AI-Assisted Spectral Interpretation Development | Machine learning deconvolution reduces PhD-level spectroscopist dependency in high-throughput screening environments. |
Research Methodology
Direct dialogue with pharmaceutical quality control directors, academic core facility managers, superconducting wire procurement leads, and battery materials researchers grounded qualitative findings in operational realities. Secondary validation drew from FDA 510(k) filings, EMA ICH guideline documentation, SEC 10-K instrument revenue disclosures, and customs trade data for NMR system imports. Bottom-up triangulation against top-down macroeconomic indicators ensured segment-level consistency.
Bottom-up modeling anchored volume projections in installed base replacement cycles, academic funding disbursement patterns, and pharmaceutical R&D capital expenditure trends across the analysis window. Segmentation dimensions included field strength tier, magnet technology type, end-use industry, and regional regulatory cluster. CAGRs derived from historical instrument shipment correlations with downstream research funding and manufacturing investment indices.
Revisions become necessary when superconducting material export controls tighten, cryogen-free technology performance specifications shift competitive thresholds, or pharmaceutical regulatory submission requirements alter software validation burdens. Forecasts reflect documented assumptions regarding helium supply stability and academic research funding continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Microplate Instrumentation and Systems Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Battery Analyzer Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Energy Dispersive X-Ray Spectrometer Market
Analytical Instruments
Array Instruments Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Metallurgical Microscope Market