
 Asia-Pacific Digital Education Market | 2026-2036
Asia-Pacific Digital Education Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Education Market Analytics
The Asia-Pacific digital education sector is restructuring around a sharp split between premium AI-driven tutoring platforms and commodity video conferencing tools. BYJU'S leverages its offline-to-online hybrid model to dominate premium test-prep segments across India. Coursera Inc. sustains credential-granting partnerships with universities in Australia and Singapore. Tencent Education anchors its position through WeChat-integrated K-12 delivery across China's provincial school systems.
Asia-Pacific digital education encompasses software platforms, curated content libraries, and connected hardware that facilitate remote instruction, skills assessment, and credential verification across formal and corporate learning environments. Cloud-based solutions with sub-100-millisecond latency thresholds and AI-driven adaptive engines that adjust difficulty in real time now constitute the technical baseline for scale. Learning Management Systems occupy the most mature margin pool, while AI-Driven Platforms represent the fastest-growing segment as institutions in South Korea and Japan deploy personalized tutoring algorithms. Mobile Learning Tools compete primarily on offline functionality and low-bandwidth optimization for rural Indonesia and the Philippines.
TRAI's broadband quality directives in India, MIIT's ed-tech data localization requirements in China, and Australia's TGA-adjacent privacy frameworks for student health data collectively raise compliance costs for cross-border platform operators. Japan's METI standards for AI transparency in educational software add a fourth layer of technical verification. Stakeholders must monitor which regulatory jurisdiction achieves de facto extraterritorial reach over regional data flows and content licensing.
Market Dynamics
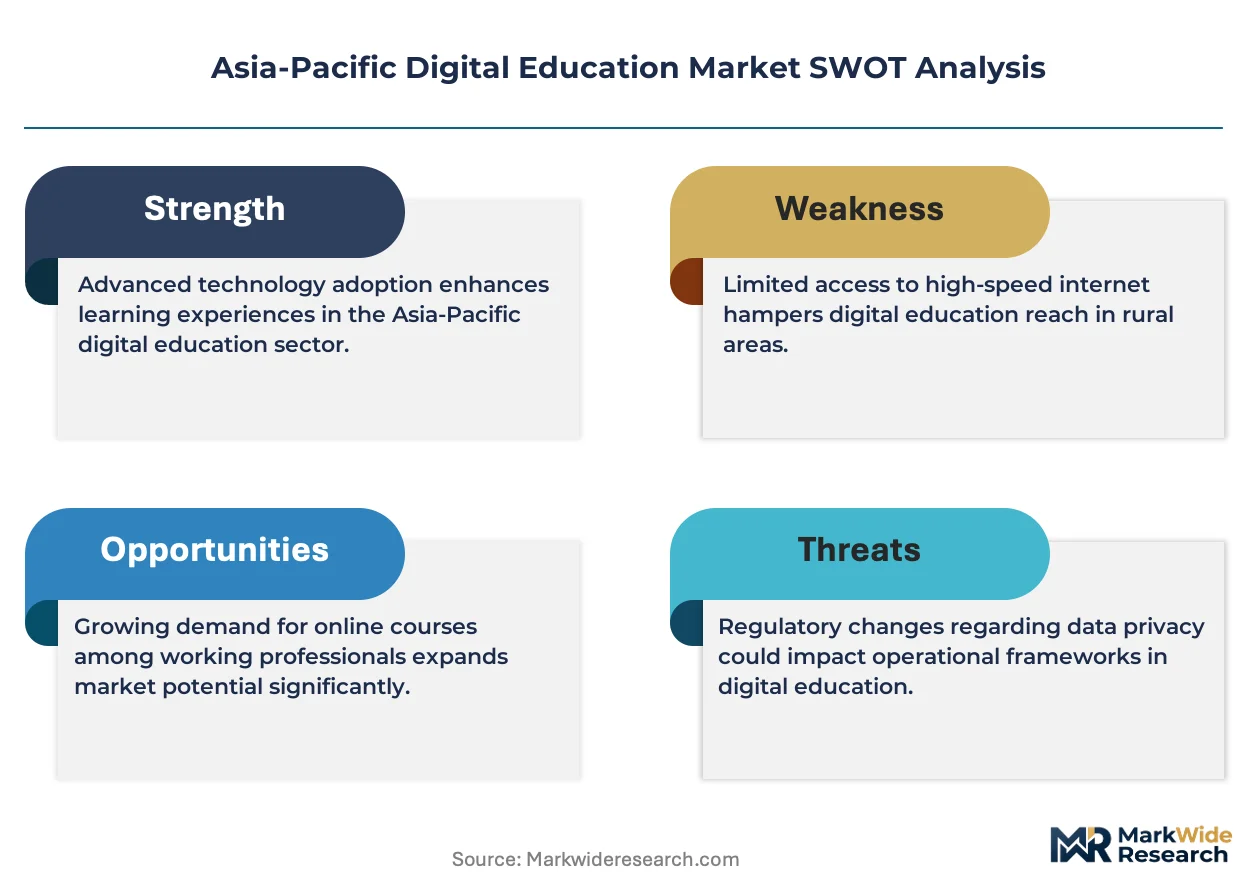
The Asia-Pacific digital education sector is bifurcating around latency-sensitive AI tutoring infrastructure and low-bandwidth mobile delivery, with TRAI's broadband mandates and MIIT's data localization rules forcing platform operators to rebuild their technical stacks for compliance-first deployment.
Growth Catalysts
- TRAI Broadband Quality Directives:India's mandated minimum speeds for educational content delivery are accelerating fiber-to-the-home investments in tier-2 and tier-3 cities, expanding addressable markets for synchronous learning platforms.
- AI-Driven Adaptive Engines:Real-time difficulty adjustment algorithms are penetrating South Korean and Japanese institutional procurement, displacing static Learning Management Systems in premium segments.
- Smartphone Penetration Clusters:Rural Indonesia and the Philippines are experiencing hardware saturation that enables offline-first mobile learning tools to reach previously unserved student populations.
Market Restraints
- MIIT Data Localization:China's ed-tech data residency requirements impose redundant infrastructure costs on cross-border platform operators, compressing margins for foreign entrants serving provincial school systems.
- Bandwidth Asymmetry:Persistent last-mile connectivity gaps between urban and rural India create technical fragmentation that prevents standardized platform deployment across the national K-12 system.
- Regional Language Content Scarcity:The shortage of curriculum-aligned materials in Tamil, Bahasa Indonesia, and Tagalog limits platform penetration outside English-medium urban centers.
Strategic Opportunities
- Vietnam and Bangladesh:These underpenetrated markets exhibit rising smartphone adoption without incumbent platform saturation, creating first-mover windows for localized content aggregators.
- WeChat-Integrated Delivery:China's super-app ecosystem enables embedded K-12 services that bypass traditional software procurement cycles, offering channel innovation for curriculum publishers.
- Japan METI AI Transparency Standards:Compliance with algorithmic explainability requirements positions certified platforms for premium pricing in institutional segments where auditability commands budget allocation.
Industry Challenges
- Multilingual Instructional Design Talent:The scarcity of professionals capable of structuring pedagogical content across five or more regional languages constrains platform localization velocity.
- Legacy System Integration:Australia's TGA-adjacent privacy frameworks for student health data require complex API bridges between new platforms and existing school information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Education Market |
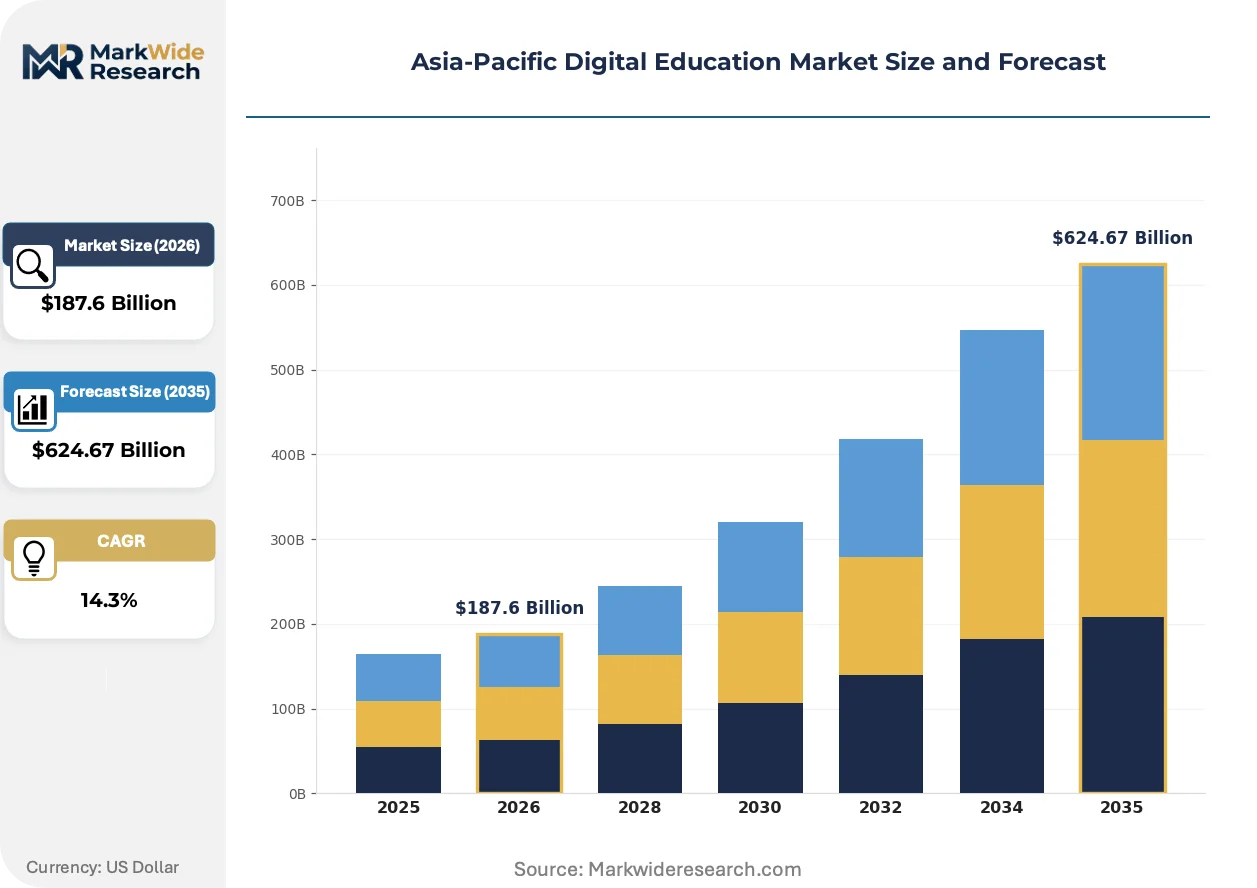
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $624.67 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Digital Content, Virtual Classrooms, Mobile Learning Tools End User: K-12 Schools, Higher Education Institutions, Corporates, Training Centers Technology: AI-Driven Platforms, Cloud-Based Solutions, Augmented Reality, Video Conferencing Delivery Mode: Synchronous Learning, Asynchronous Learning, Blended Learning, Online Courses |
| Companies Covered | Chegg Inc., Blackboard Inc., Coursera Inc., upGrad Education Private Limited, edX Inc., BYJU'S, Alphabet Inc. (Google), Instructure Inc., Tencent Education, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Education Market Evolving Landscape
Generative AI is compressing content production cycles while regulatory fragmentation around student data is forcing architectural isolation between national deployments. Platform operators are rebuilding for jurisdiction-specific compliance rather than regional scale.
Edge-computing nodes for AI inference are expanding into Australia's remote learning networks and Japan's rural prefectures. These localized processing units reduce round-trip latency for adaptive tutoring systems below the 100-millisecond threshold that preserves student engagement. The technology is expanding into institutional procurement specifications as a mandatory performance baseline rather than a premium upgrade.
Japan's METI standards for AI transparency in educational software are creating template requirements that other Asia-Pacific regulators are adopting through bilateral harmonization agreements. The industrial consequence is a compliance cost escalation for opaque algorithmic systems that cannot produce auditable decision trails. South Korean ed-tech procurement now embeds METI-equivalent certification as a technical prequalification, forcing platform rebuilds for vendors targeting both markets.
Enterprise learning buyers in Singapore and Australia are unbundling content libraries from delivery platforms, contracting directly with subject-matter experts for proprietary curriculum while licensing lightweight distribution infrastructure. This procurement pattern compresses vendor margins by separating high-value intellectual property from commodity hosting services. The shift is most visible in financial services and healthcare verticals where regulatory continuing-education requirements create captive demand for customized certification pathways.
Asia-Pacific Digital Education Market Segmentation
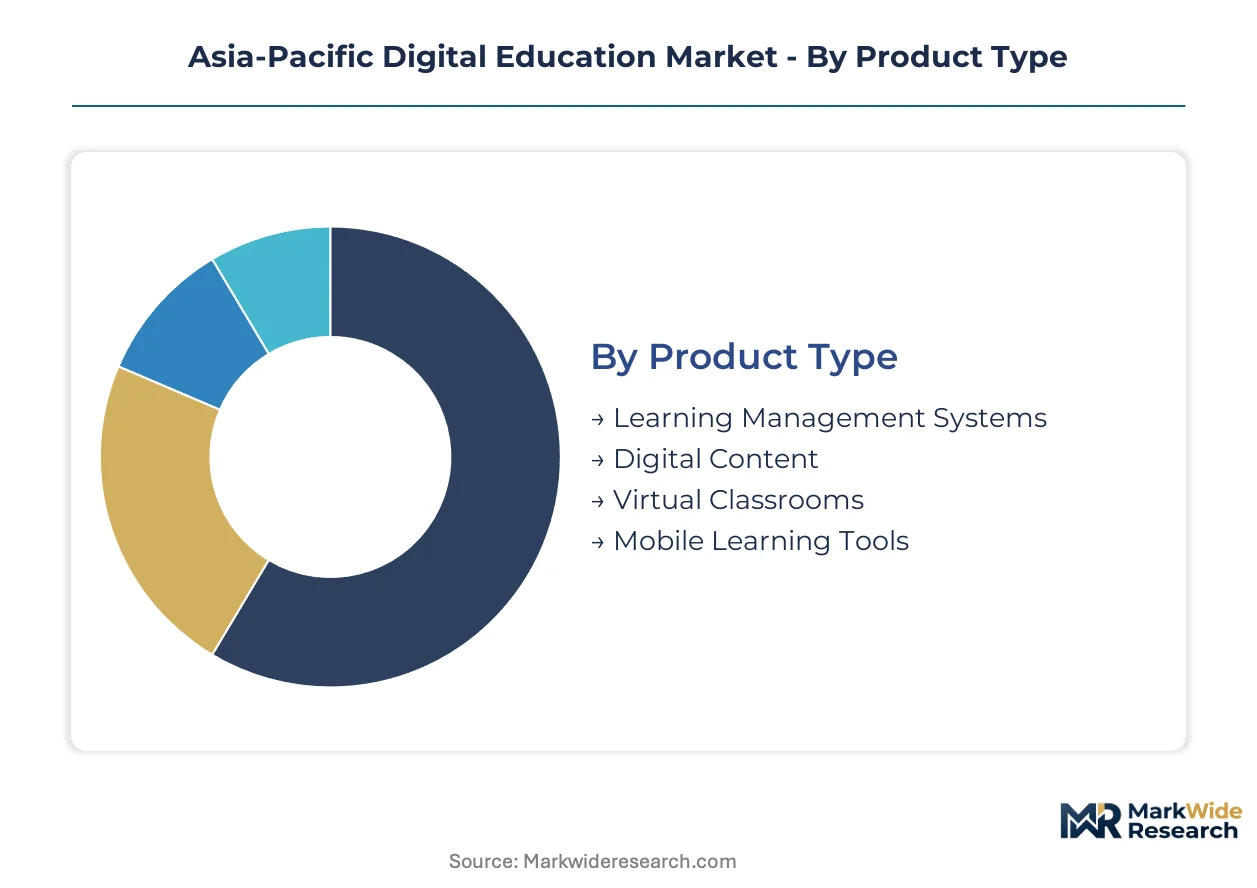
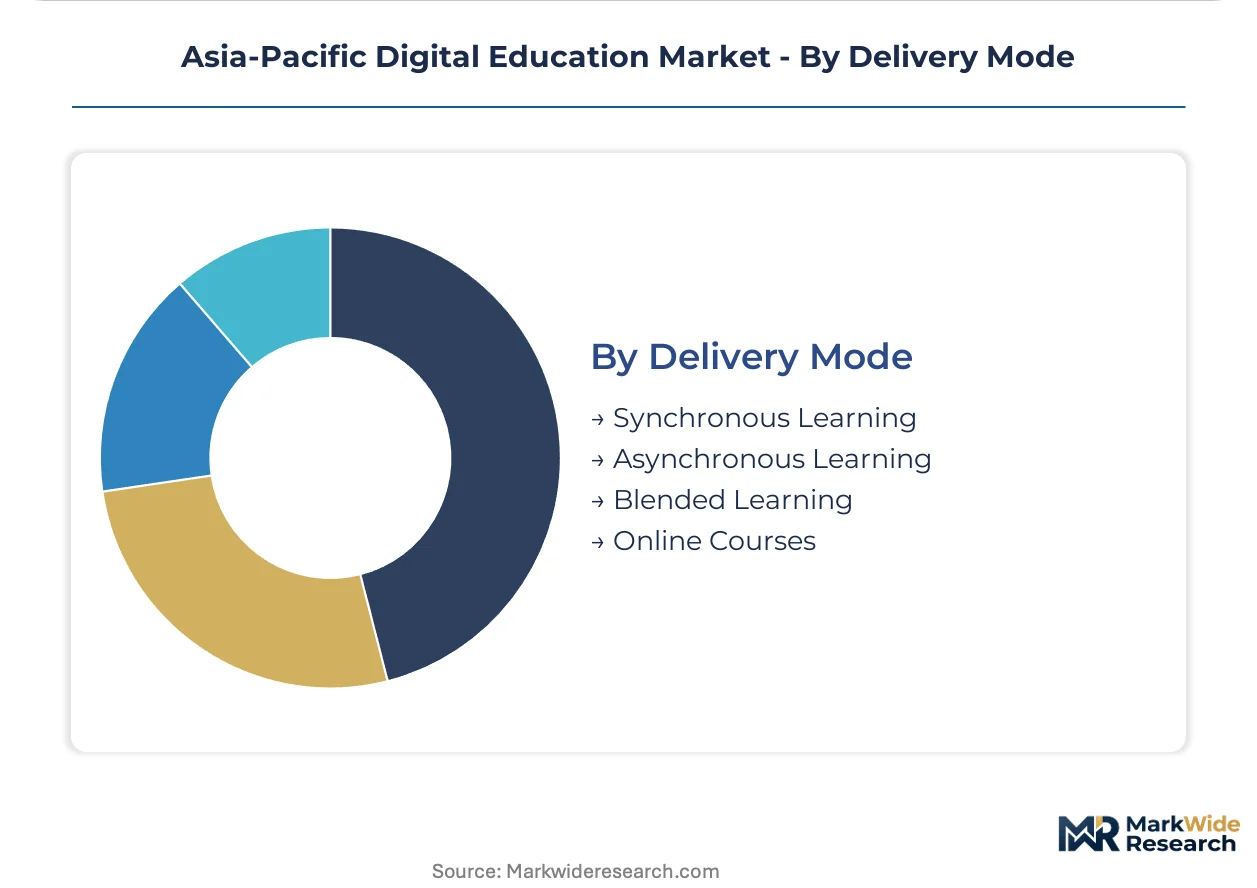
Asia-Pacific digital education procurement splits sharply between latency-sensitive synchronous platforms and offline-capable mobile tools. Platform operators must architect for these divergent technical specifications to capture institutional budgets across India's tier-2 cities and China's provincial school systems.
Product Type:
Technical specifications around latency thresholds and offline functionality define competitive positioning in this category.
- Learning Management Systems:Cloud-hosted administrative frameworks manage enrollment, assessment, and credentialing with sub-100-millisecond response requirements. Procurement concentrates in Australian universities and Singaporean polytechnics where integration with existing student information systems drives vendor selection.
- Digital Content:Curriculum-aligned multimedia libraries span video, interactive simulations, and assessment banks. Demand clusters in India's tier-2 and tier-3 cities where regional-language availability determines platform penetration outside English-medium institutions.
- Virtual Classrooms:Real-time video delivery with breakout rooms and collaborative whiteboards.
- Mobile Learning Tools:Offline-first applications optimized for low-bandwidth environments in rural Indonesia and the Philippines.
Mature deployment sits with Learning Management Systems. Newer deployment is concentrated in Mobile Learning Tools.
End User:
Budget cycles and procurement authority structures vary substantially across institutional buyer types.
- K-12 Schools:Government-funded primary and secondary institutions with centralized purchasing at state or provincial levels. India's state education boards and China's county-level education bureaus are accelerating cloud platform adoption under TRAI broadband mandates and MIIT infrastructure policies.
- Higher Education Institutions:Universities and technical colleges with autonomous IT procurement. Credential-granting partnerships dominate in Australia and Singapore where international student recruitment depends on digital delivery reputation.
- Corporates:Enterprise learning and development departments.
- Training Centers:Vocational and test-preparation institutes.
Volume concentration rests with K-12 Schools. Margin expansion is steepest in Corporates.
Technology:
Processing architecture choices determine compliance obligations and performance benchmarks across jurisdictions.
- AI-Driven Platforms:Adaptive engines adjusting content difficulty in real time based on learner performance data. South Korean and Japanese institutional procurement now embeds METI-equivalent algorithmic transparency certification as a technical prequalification.
- Cloud-Based Solutions:Scalable hosting infrastructure with automatic failover and multi-region redundancy. TRAI's quality directives and MIIT's data localization rules force redundant infrastructure builds for cross-border operators serving Indian and Chinese markets simultaneously.
- Augmented Reality:Spatial computing overlays for immersive STEM instruction.
- Video Conferencing:Commodity real-time communication infrastructure.
Compliance complexity peaks with AI-Driven Platforms. Deployment velocity is fastest in Cloud-Based Solutions.
Delivery Mode:
Temporal structure of instruction determines bandwidth requirements and platform architecture decisions.
- Synchronous Learning:Real-time scheduled sessions requiring continuous connectivity. Fiber-to-the-home investments in India's tier-2 cities under TRAI mandates are expanding addressable markets for live instruction platforms.
- Asynchronous Learning:Self-paced content access with flexible scheduling. Rural Indonesia and Philippines adoption depends on offline download capabilities that bypass intermittent connectivity.
- Blended Learning:Hybrid models combining scheduled live sessions with self-directed modules.
- Online Courses:Structured certificate or degree programs delivered entirely through digital channels.
Technical standardization is most advanced in Online Courses. Innovation investment is heaviest in Blended Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru anchors Asia-Pacific digital education activity through its concentration of adaptive learning startups and AI engineering talent pools serving domestic and export markets.
India
Tier-2 and tier-3 cities drive procurement volume as smartphone penetration crosses critical thresholds in Indore, Lucknow, and Coimbatore. TRAI broadband quality directives mandate minimum speeds for educational content delivery, accelerating fiber-to-the-home investments. Hyderabad's EdTech Valley cluster houses curriculum localization teams producing Tamil, Telugu, and Marathi instructional modules.
China
Provincial school systems in Sichuan, Hunan, and Shandong deploy WeChat-integrated K-12 platforms at county-level scale. MIIT data localization requirements force redundant infrastructure builds for operators serving multiple provinces. Shenzhen's hardware ecosystem supplies edge-computing nodes for latency-sensitive AI tutoring deployment across the Yangtze River Delta.
Japan
Institutional procurement in Tokyo, Osaka, and Nagoya prioritizes METI-certified algorithmic transparency for AI-driven adaptive engines. Rural prefectures deploy localized edge-computing infrastructure to maintain sub-100-millisecond response thresholds. Fukuoka's education technology corridor specializes in audit-ready tutoring systems for premium pricing segments.
Australia
Universities in Sydney and Melbourne sustain credential-granting partnerships with international platforms targeting Southeast Asian student recruitment. TGA-adjacent privacy frameworks for student health data require complex API integration with legacy school information systems. Brisbane's vocational training hubs pilot blended learning models combining synchronous delivery with self-paced modules.
South Korea
Seoul's metropolitan school districts embed METI-equivalent AI certification as technical prequalification for institutional procurement. Daegu-Gyeongbuk's education technology cluster develops real-time difficulty adjustment algorithms displacing static Learning Management Systems. Busan-Ulsan manufacturers supply low-latency hardware for synchronous platform deployment.
Asia-Pacific Digital Education Market Competitive Landscape
Premium-margin players sit above commodity-margin players across algorithmic sophistication and compliance certification tiers. The market structures around three concentration poles: domestic champions with government procurement relationships, global platforms with university credential partnerships, and super-app integrators with embedded distribution channels. Strategic moves concentrate on geographic licensing arrangements and jurisdiction-specific compliance architecture rather than product differentiation.
Within the domestic champion tier, BYJU'S and upGrad Education Private Limited exemplify hybrid offline-to-online models built for test-prep and upskilling segments respectively. Coursera Inc. anchors the global credential partnership vector through university relationships in Australia and Singapore. Tencent Education occupies the super-app integration position, leveraging WeChat distribution across China's provincial school procurement systems.
| Leading Market Players |
|---|
| Chegg Inc. |
| Blackboard Inc. |
| Coursera Inc. |
| upGrad Education Private Limited |
| edX Inc. |
| BYJU'S |
| Alphabet Inc. (Google) |
| Instructure Inc. |
| Tencent Education |
| Others |
Value Network & Pricing Analysis
Japan's METI algorithmic transparency standards gate qualified supply for premium AI-driven tutoring platforms, restricting premium-tier pricing access to vendors with certified audit-ready systems while compressing margins for uncertified operators across South Korean and Japanese institutional procurement.
Pricing Analysis
Value-based pricing anchored to measurable learning outcome improvements dominates institutional procurement in South Korea and Japan. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels separates METI-certified platforms from METI-equivalent and uncertified alternatives. Pricing pressure stems from MIIT data localization requirements forcing redundant infrastructure builds for cross-border operators serving Chinese provincial school systems. K-12 schools in India's tier-2 cities exhibit highest price sensitivity, while Japanese metropolitan school districts show lowest sensitivity due to auditability requirements commanding dedicated budget allocation.
Supply Chain Analysis
Single-source vulnerability sits with Shenzhen's edge-computing hardware ecosystem for sub-100-millisecond latency components. Geographic supply concentration centers on China for WeChat-integrated delivery infrastructure, India for regional-language content localization talent, and South Korea for adaptive engine algorithm development. Raw material dependencies include cloud compute capacity from hyperscaler data centers, specialized AI inference chips, and multilingual instructional design expertise. Supply chain risk manifests as regulatory restriction from TRAI broadband quality directives and MIIT data residency rules fragmenting technical architecture. Distribution runs through government procurement cycles at state education boards and county-level education bureaus.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained qualified vendor capacity for METI-certified AI transparency compliance props premium-tier pricing, creating durable margin pools for certified operators while excluding uncertified competitors from Japanese and South Korean institutional segments.
For Market Incumbents: Cement procurement relationships with India's state education boards before fiber-to-the-home investments mature in tier-2 cities, locking in multi-year cloud platform contracts. Acquire regional-language content localization studios in Hyderabad and Bengaluru to accelerate Tamil, Telugu, and Marathi module production ahead of competitor entry. Vertical integration into edge-computing hardware manufacturing mitigates Shenzhen supply concentration risk. For New Entrants and Emerging Players: Begin with Vietnam and Bangladesh where smartphone adoption rises without incumbent platform saturation, creating first-mover windows for localized content aggregators. Target vocational training centers in Indonesia's rural districts with offline-first mobile tools bypassing bandwidth constraints. Partner with WeChat curriculum publishers for embedded K-12 distribution channel access. For Investors and Strategic Acquirers: Japanese prefecture-level edge-computing infrastructure deployment acceleration is the leading indicator that rural latency-sensitive AI tutoring markets are reaching investable scale. Target acquisition archetypes are adaptive learning startups with existing METI certification or clear certification pathway within 24-36 months. Watch for South Korean ed-tech procurement embedding METI-equivalent standards as technical prequalification signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | WeChat-embedded K-12 services bypass traditional software procurement cycles in China's county-level education bureaus. |
| Geographic Expansion | Fiber-to-the-home investments under TRAI mandates expand addressable markets for synchronous platforms in India's tier-2 cities. |
| Acquisition of Specialist Firm | Regional-language content studios accelerate Tamil, Bahasa Indonesia, and Tagalog curriculum penetration outside urban centers. |
| Strategic Partnership | Credential-granting university relationships in Australia and Singapore anchor international student recruitment channels. |
| Product Launch | METI-certified algorithmic transparency modules unlock premium pricing in Japanese institutional segments requiring auditability. |
Research Methodology
Independent corroboration across ed-tech procurement officers at India's state education boards, platform engineering leads at adaptive learning startups, and channel partners distributing WeChat-integrated services underwrites the qualitative findings. Primary interviews with curriculum localization directors, AI transparency compliance consultants, and hyperscaler education vertical sales teams combined with secondary validation from SEC filings, TRAI broadband quality reports, and METI certification registries. Bottom-up and top-down triangulation reconciles platform deployment data with institutional budget allocation surveys.
Rate-of-change decomposition across product type, end user, technology, and delivery mode dimensions structures the analytical framework over the projection horizon. CAGRs derive from modeled adoption curves for AI-driven platforms displacing static Learning Management Systems, smartphone penetration thresholds enabling offline-first mobile tools, and fiber-to-the-home expansion timelines under TRAI mandates. Forecast inputs include provincial school system procurement cycle timing and edge-computing node deployment specifications.
Regulatory harmonization delays, broadband infrastructure investment shortfalls, and multilingual instructional design talent scarcity are the dominant revision risks to modeled adoption trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Higher Education Learning Systems Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Artificial Intelligence in the Education Sector Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
SETM Education Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
Education Technology Market