
 M-Education Market | 2026-2036
M-Education Market Size, Share, and Industry Trends Forecast 2026-2036
M-Education Market Foresight
Subscription-based content licensing is decoupling curriculum delivery from institutional ownership, transforming how schools and enterprises procure educational software. Instructure leverages its cloud-native architecture to sustain dominance in higher education learning management. Google anchors K-12 distribution through Chromebook ecosystem integration and Workspace for Education bundling. BYJU'S competes aggressively in India's after-school tutoring segment with video-first content libraries.
M-education encompasses digitally delivered instructional content, assessment tools, and collaborative environments accessed through mobile devices, tablets, and lightweight laptops, typically requiring persistent internet connectivity or offline sync capabilities for asynchronous learning. Its primary commercial purpose centers on democratizing access to structured knowledge while reducing per-learner infrastructure costs versus traditional classroom models. E-learning platforms and virtual classrooms command the deepest margin pools where institutional contracts lock in multi-year recurring revenue. Mobile learning apps represent the fastest-expanding delivery vector among individual consumers and informal learners. Educational games remain structurally niche, constrained by curriculum alignment requirements and lengthy district procurement cycles.
The EU AI Act, GDPR, and US FERPA collectively impose divergent data governance obligations that fragment platform development roadmaps and elevate compliance costs for cross-border operators. India's TRAI and BIS standards further complicate device certification and content localization for entrants targeting its price-sensitive mass market. Stakeholders must monitor evolving AI disclosure mandates and biometric data restrictions that threaten to disqualify existing personalization engines from regulated deployments.
Market Dynamics
Enterprise reskilling mandates and workforce automation pressures are restructuring procurement priorities across corporate learning departments, diverting budget share from traditional higher education contracts toward modular, mobile-first credentialing platforms.
Growth Catalysts
- EU AI Act compliance frameworks:Mandatory algorithmic transparency requirements are accelerating platform redevelopment cycles, creating replacement demand for legacy personalization engines across European deployments.
- India's tier-2 urbanization:Low-cost smartphone penetration in secondary cities is unlocking first-time digital learner cohorts previously unreachable through desktop-dependent delivery models.
- Corporate training departments:Enterprise workforce reskilling programs now represent the fastest-expanding buyer segment as automation threats intensify internal capability-building investments.
Market Restraints
- GDPR biometric restrictions:Facial recognition and attention-tracking features face outright prohibition in European K-12 deployments, forcing removal of engagement analytics tools from core product roadmaps.
- Device certification fragmentation:India's BIS standards and TRAI connectivity mandates impose divergent hardware compliance requirements that extend localization timelines for foreign platform entrants.
- Curriculum alignment cycles:District-level procurement processes for educational games stretch 18-24 months, compressing addressable margins for content developers targeting formal institutional channels.
Strategic Opportunities
- Offline-first architecture:Asynchronous sync capabilities for intermittent connectivity environments unlock penetration in rural India and sub-Saharan African markets where infrastructure remains unreliable.
- Subscription licensing decoupling:Cloud-native curriculum delivery models separate content access from institutional ownership, enabling month-to-month enterprise contracts previously impossible under perpetual license structures.
- AI disclosure standardization:Emerging ISO guidelines for educational algorithm transparency are creating certification-driven preference advantages for early-adopter platforms demonstrating compliance leadership.
Industry Challenges
- Cross-border data architecture:FERPA, GDPR, and India's data localization rules impose conflicting storage and processing requirements that fragment engineering resources across regional product variants.
- Legacy LMS integration:Higher education institutions running on-premises Blackboard and Moodle deployments resist API connectivity with newer mobile-native platforms, extending sales cycles and implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | M-Education Market |
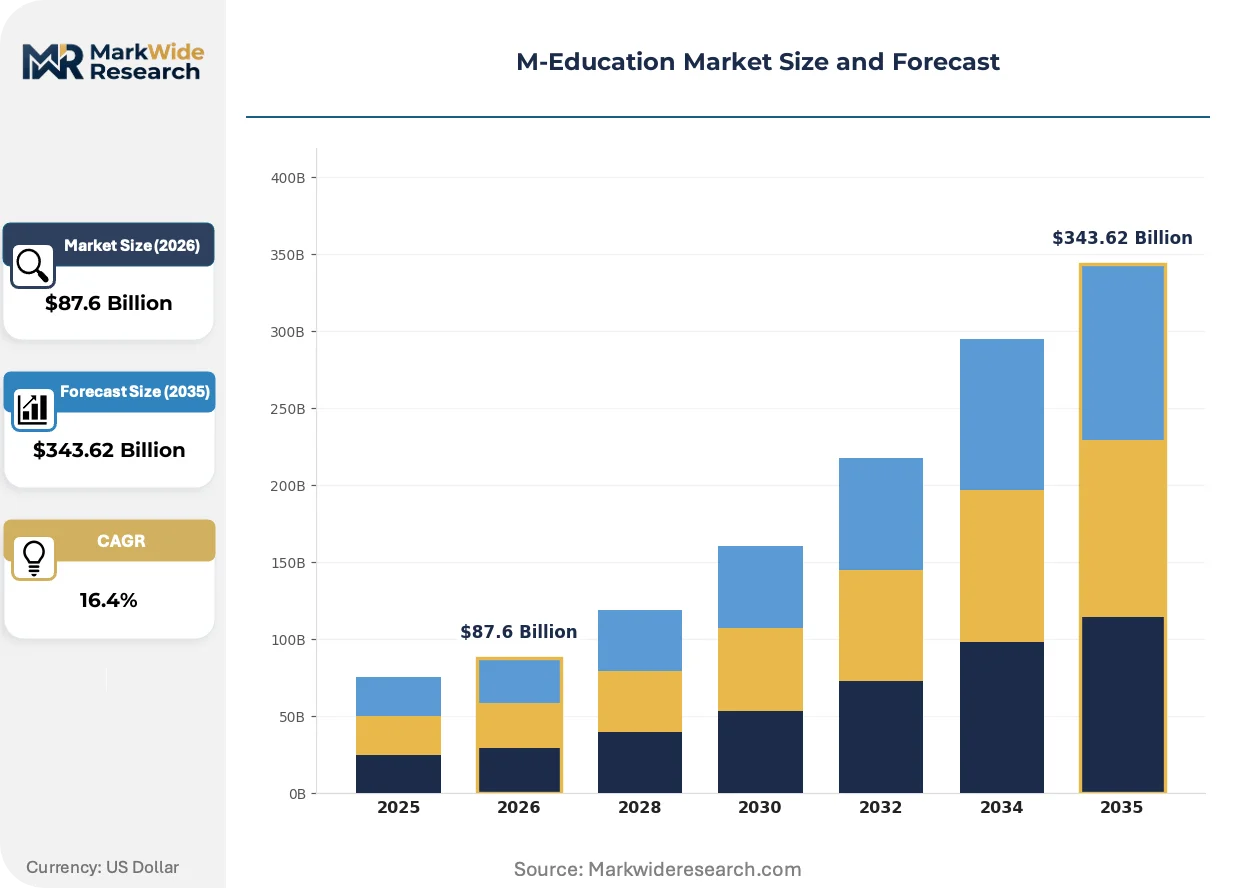
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $343.62 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: E-Learning Platforms, Mobile Learning Apps, Virtual Classrooms, Educational Games End User: Students, Teachers, Educational Institutions, Corporate Training Delivery Mode: Online, Offline, Hybrid, Blended Learning Application: K-12 Education, Higher Education, Skill Development, Professional Training |
| Companies Covered | Instructure, Anthology, D2L, Moodle, Coursera, Google, Microsoft, Pearson, BYJU'S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
M-Education Market Shifts & Advancements
Adaptive assessment engines and generative content pipelines are compressing production timelines for personalized learning pathways, while regulatory pressure on algorithmic transparency forces architectural disclosure that was previously proprietary.
Generative AI tutoring systems are automating the synthesis of practice problems, explanatory feedback, and mastery verification previously requiring human instructional design. Corporate training departments are piloting these tools at accelerating pace for technical certification preparation. This capability compression threatens incumbent content library economics built on fixed production investments.
The EU AI Act's risk classification system for educational algorithms is forcing platform operators to restructure data processing workflows and document decision logic for audit trails. Higher education deployments face the strictest scrutiny under "high-risk" categorization for credential-bearing assessments. Vendors are responding by segregating European infrastructure and accelerating ISO 27001 certification to demonstrate governance maturity.
Enterprise buyers are consolidating vendor relationships around bundled platform ecosystems that combine content delivery, skills assessment, and credential verification in single contracts. This preference compression disadvantages point-solution providers lacking adjacent capability depth. The shift is most visible in North American Fortune 500 learning and development budgets, where procurement teams prioritize integration simplicity over best-of-breed feature differentiation.
M-Education Market Segmentation
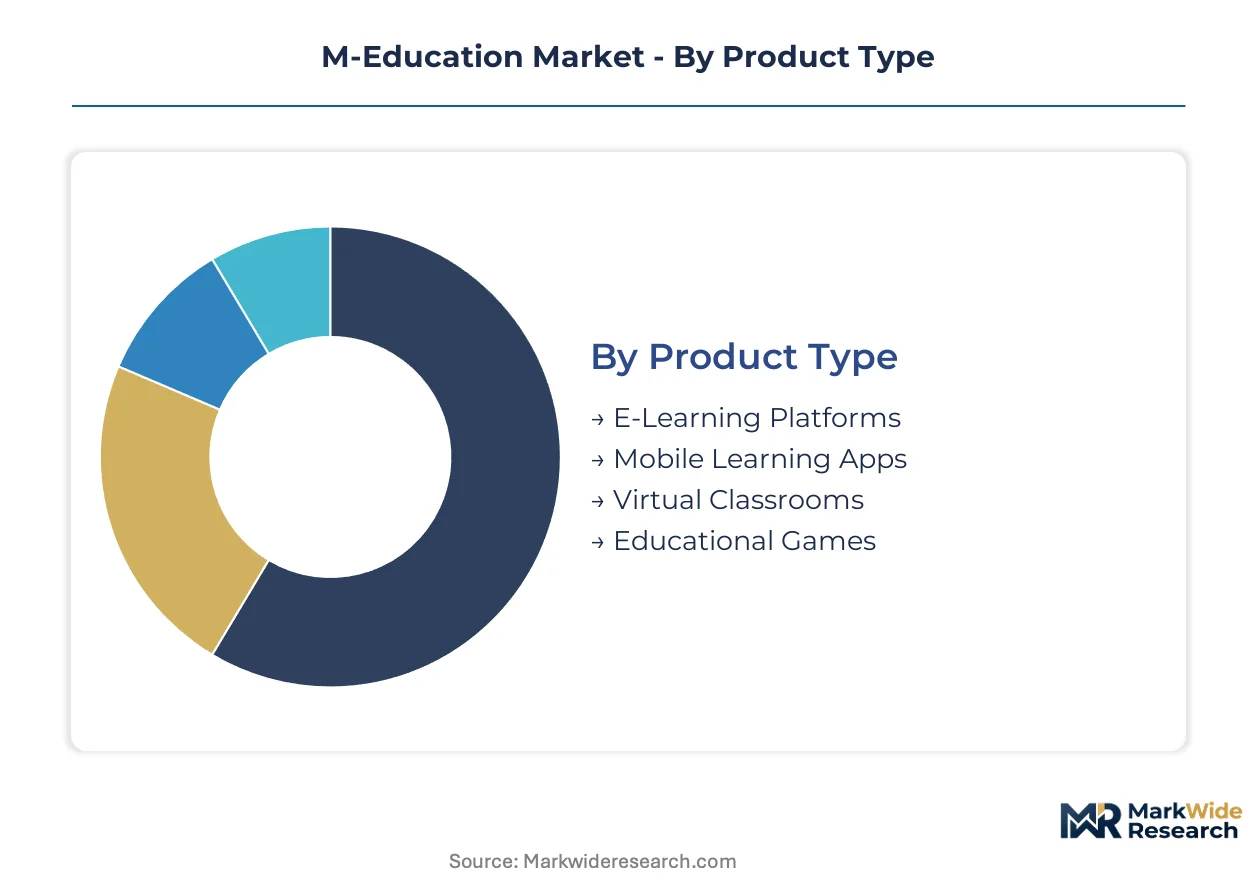
Segmentation in M-Education reveals divergent margin structures and procurement rhythms across delivery formats and buyer types. Product architecture decisions, end-user workflows, and connectivity constraints each create distinct competitive arenas requiring specialized positioning.
Product Type:
The customization-vs-standardization spectrum runs from configurable enterprise stacks to mass-market consumer applications, with institutional contracts demanding API flexibility while individual learners prioritize immediate accessibility.
- E-Learning Platforms:Cloud-native learning management systems with modular assessment engines and third-party content integration. Demand concentrates in North American higher education and Fortune 500 corporate training departments, where multi-year institutional contracts lock in recurring revenue streams and require FERPA-compliant data architectures.
- Mobile Learning Apps:Lightweight, smartphone-optimized delivery vehicles with offline sync capabilities and microlearning content formats. India's tier-2 and tier-3 cities represent the steepest expansion trajectory, as low-cost Android penetration enables first-time digital learners previously unreachable through desktop-dependent models.
- Virtual Classrooms:Real-time video conferencing tools with breakout rooms, collaborative whiteboards, and attendance analytics.
- Educational Games:Gamified assessment modules aligned to curriculum standards with progress tracking dashboards.
Most installed capacity flows through E-Learning Platforms. Expansion is steepest in Mobile Learning Apps.
End User:
Cost tier stratification separates enterprise procurement budgets from individual discretionary spending, with institutional buyers negotiating volume discounts while teachers and students access freemium tiers.
- Students:Individual learners accessing content through personal devices, often via subscription or ad-supported models. K-12 and higher education segments in India and Southeast Asia are gaining share fastest, where smartphone-first consumption patterns dominate and price sensitivity drives demand for low-cost annual subscriptions.
- Corporate Training:Enterprise learning and development departments procuring workforce reskilling solutions. North American and European deployments lead contract value, as automation pressures intensify internal capability-building investments and modular credentialing platforms displace traditional higher education partnerships.
- Teachers:Individual instructors seeking supplemental content and classroom management tools.
- Educational Institutions:Schools, districts, and universities with centralized procurement and compliance requirements.
Volume concentrates in Student-facing deployments. Value expansion is strongest in Corporate Training.
Delivery Mode:
Application context determines connectivity architecture, with synchronous collaboration demanding persistent bandwidth while asynchronous models accommodate infrastructure constraints.
- Online:Real-time, internet-dependent delivery requiring continuous connectivity for streaming video and live interaction. Urban centers in developed economies maintain deepest penetration, where broadband reliability supports synchronous virtual classrooms and immediate assessment feedback loops.
- Offline:Downloadable content with periodic sync capabilities for intermittent connectivity environments. Rural India and sub-Saharan African markets are expanding most quickly, where infrastructure unreliability makes asynchronous access essential for educational reach.
- Hybrid:Blended schedules alternating between physical and digital instruction.
- Blended Learning:Integrated classroom-digital workflows with teacher-facilitated technology use.
Current installations favor Online delivery. Infrastructure gaps are accelerating Offline adoption.
Application:
Customer maturity varies across education lifecycle stages, with K-12 requiring district-level procurement cycles while professional training demands rapid skill-to-job alignment.
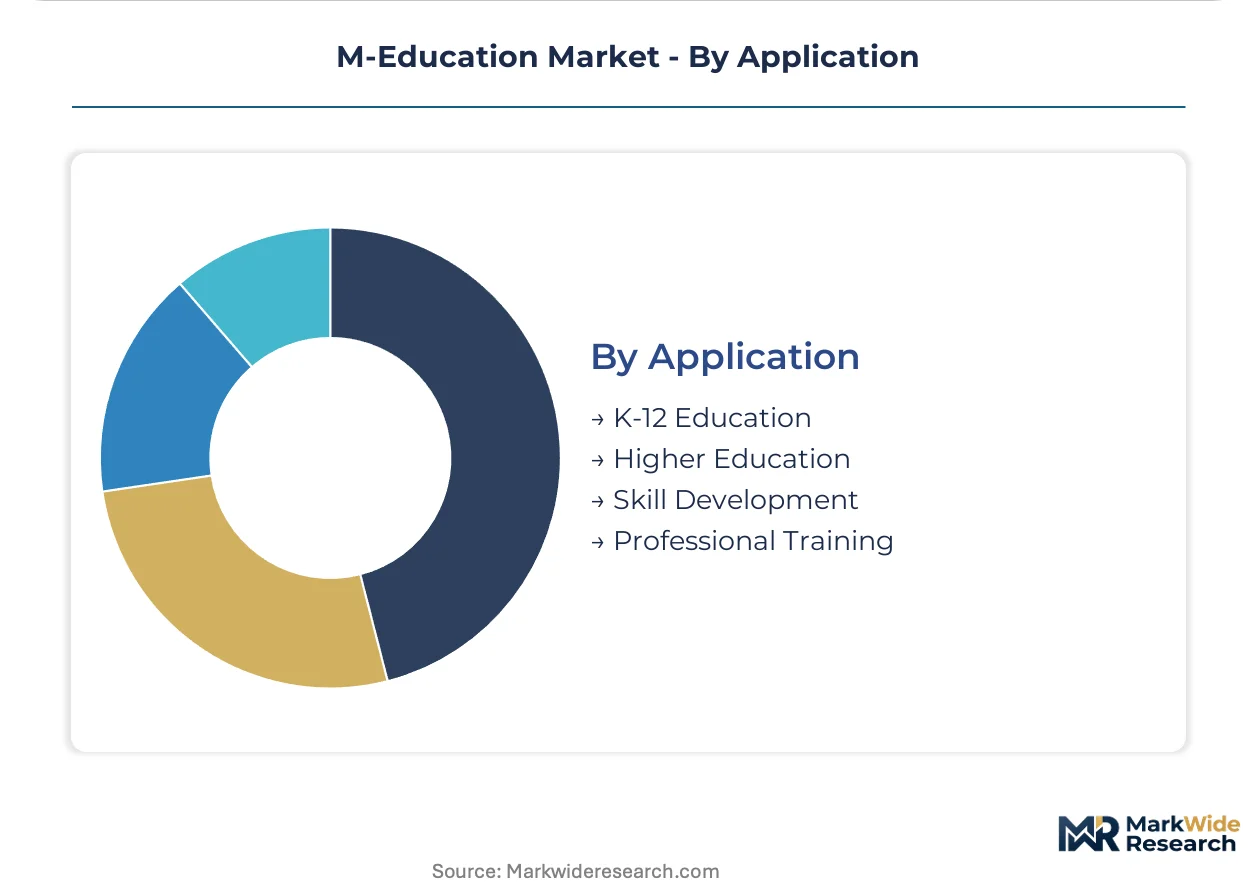
- K-12 Education:Curriculum-aligned content serving primary and secondary school systems with parental oversight features. Procurement concentrates in US school districts and Indian state education boards, where GDPR and national data localization rules impose divergent compliance architectures.
- Skill Development:Vocational and technical training programs targeting employment readiness. India's National Skill Development Corporation and German federal employment initiatives are gaining share fastest, where public-private partnerships fund platform access for workforce transition programs.
- Higher Education:Degree-granting institutions with credential-bearing assessment requirements.
- Professional Training:Industry certification preparation and continuing education for licensed occupations.
Deployment scale currently centers on K-12 Education. Investment intensity is climbing fastest in Skill Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's tier-2 urbanization outpaces Brazil's ed-tech adoption curve by a factor of three, while Germany's regulatory complexity exceeds that of any single Asian market. Corporate training budgets in the United States and United Kingdom now exceed combined K-12 procurement across Southeast Asia.
United States
Fortune 500 reskilling programs and university LMS replacement cycles drive enterprise demand. FERPA compliance requirements shape data architecture decisions for platforms serving degree-granting institutions. Austin and Boston clusters concentrate venture-backed adaptive learning startups targeting corporate technical certification markets.
India
Low-cost smartphone penetration in secondary cities unlocks first-time digital learner cohorts previously unreachable through desktop models. TRAI connectivity mandates and BIS device certification standards complicate foreign platform localization timelines. Bangalore and Hyderabad anchor domestic platform development for after-school tutoring and vernacular content libraries.
Germany
Federal employment agency funding for workforce transition programs accelerates vocational platform procurement. GDPR biometric restrictions and EU AI Act algorithmic transparency requirements force architectural redevelopment of personalization engines. Berlin and Munich clusters concentrate corporate learning technology vendors serving DAX-listed industrial employers.
United Kingdom
University consortium purchasing and Open University partnership models sustain platform demand in higher education. UK-specific GDPR interpretations and Ofqual accreditation requirements create compliance complexity distinct from continental deployments. London and Manchester concentrate ed-tech venture activity and corporate training headquarters for financial services sectors.
Brazil
Public-private partnership models for vocational training and federal professional certification programs expand platform access. ANVISA and national data protection authority guidelines impose emerging compliance obligations for biometric-enabled engagement analytics. São Paulo and Rio de Janeiro clusters concentrate domestic platform development for Portuguese-language corporate training content.
M-Education Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platforms commanding premium pricing in institutional contracts while mobile-first consumer apps compete on acquisition efficiency. The vendor base concentrates around three strategic tiers: established LMS incumbents with multi-year university relationships, hyperscaler ecosystems leveraging device and productivity suite bundling, and regional specialists with vernacular content depth. Dominant competitive moves include strategic API partnerships with legacy system integrators and accelerated ISO certification investments to satisfy emerging AI disclosure mandates.
Within the cloud-native platform tier, Instructure and Coursera exemplify divergent positioning strategies—one anchored in degree-granting institutional infrastructure, the other in modular credentialing and enterprise workforce partnerships. Google occupies a distinctive position through Chromebook ecosystem integration and Workspace for Education bundling that compresses procurement friction for K-12 districts. BYJU'S represents the regional specialist archetype, with video-first content libraries and vernacular delivery formats capturing India's price-sensitive after-school tutoring expansion.
| Leading Market Players |
|---|
| Instructure |
| Anthology |
| D2L |
| Moodle |
| Coursera |
| Microsoft |
| Pearson |
| BYJU'S |
| Others |
Supply & Pricing Matrix
Cloud-native platform tiers diverge sharply from mobile-first consumer applications in both pricing architecture and supply chain configuration. Enterprise LMS contracts command annual recurring revenue premiums through FERPA-compliant data infrastructure and API flexibility, while mass-market apps in India compete on acquisition efficiency and offline sync capabilities. This bifurcation concentrates margin pools in North American institutional procurement while compressing unit economics in emerging market consumer segments.
Pricing Analysis
Capacity additions in India's domestic platform development ecosystem are reshaping price floors for vernacular content delivery. Subscription-based SaaS tiers dominate enterprise procurement, with price differentiation driven by ISO 27001 certification status and customization depth for legacy LMS integration. Cost compression in the mobile learning app segment is intensifying because low-cost Android device proliferation enables freemium models with ad-supported tiers. Corporate training departments show least price sensitivity, while individual learners in tier-2 Indian cities demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud infrastructure providers for enterprise platform hosting. Content delivery networks draw from the United States, Ireland, and Singapore for latency optimization, while AI tutoring engines rest on proprietary training data and third-party foundation model APIs. Tariff exposure runs through semiconductor components for student device procurement in price-sensitive markets. Distribution runs through direct institutional sales teams for enterprise contracts and app store marketplaces for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The M-Education market functions as a regulatory compounder where EU AI Act algorithmic transparency mandates are accelerating platform replacement cycles and reshaping procurement priorities across European deployments.
For Market Incumbents: To counter generative AI tutoring systems threatening fixed content library economics, incumbents should accelerate backward integration into proprietary assessment engines and deepen ISO 27001 certification investments to satisfy emerging disclosure mandates. API partnerships with legacy Blackboard and Moodle system integrators extend sales cycles but lock in multi-year institutional retention. For New Entrants and Emerging Players: Enter via offline-first architecture targeting rural India and sub-Saharan African markets where intermittent connectivity creates white-space unavailable to synchronous platform incumbents. The most penetrable segment combines vernacular microlearning content with BIS-compliant device certification for government procurement channels. A channel partnership strategy with domestic telecom operators accelerates distribution reach. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented point-solution providers lack adjacent capability depth in skills assessment and credential verification. Long-term viability over the next decade hinges on bundled platform ecosystem positioning rather than best-of-breed feature differentiation. Watch for ISO algorithm transparency certification adoption rates as the inflection signal separating compliant platforms from regulatory-exposed legacy engines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity with legacy LMS infrastructure reduces procurement friction for higher education contracts. |
| Geographic Expansion | Offline sync capabilities unlock penetration in Indian tier-2 cities and sub-Saharan African markets. |
| Strategic Partnership | Telecom operator bundling compresses customer acquisition costs in price-sensitive emerging markets. |
| Acquisition of Specialist Firm | Vernacular content libraries accelerate localization timelines for India's state education board procurement. |
| Regulatory Certification Program | EU AI Act compliance leadership creates preference advantages in European institutional RFP processes. |
Research Methodology
Direct dialogue with chief learning officers, platform engineering leads, district procurement managers, and regulatory affairs specialists grounded qualitative assessment of procurement priorities and compliance architecture decisions. Secondary validation drew from SEC filings of publicly traded platform providers, EU AI Act implementation guidance documents, TRAI connectivity mandate circulars, and hyperscaler education vertical capex disclosures. Bottom-up segment sizing triangulated with top-down market construction across product type, end user, delivery mode, and application dimensions.
Segment-level revenue trajectories across the analysis window reflect modeled assumptions for smartphone penetration curves, enterprise reskilling budget allocations, and regulatory compliance cost pass-through rates. Deployment model, organization size, vertical integration complexity, and regional adoption patterns structured the segmentation framework. CAGRs were derived from logistic diffusion modeling of digital learner cohort expansion and replacement demand cycles for legacy personalization engines.
Inputs from EU regulatory guidance releases and Indian BIS certification databases were available through the study window; gaps in real-time corporate training budget allocation data introduce uncertainty bands around enterprise segment projections. Forecasts reflect documented assumptions regarding connectivity infrastructure buildout timelines and algorithmic transparency implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Child Care Software Market