
 Flipped Classroom Market | 2026-2036
Flipped Classroom Market Size, Share, and Industry Trends Forecast 2026-2036
Flipped Classroom Market Foresight
The direct-to-institution software channel is narrowing as platform providers consolidate campus procurement decisions. Cisco Systems leverages its networking infrastructure to anchor large university deployments. Dell Technologies sustains hardware refresh cycles through bundled device-and-management offerings. Khan Academy competes on zero-cost content access, forcing paid platforms to differentiate on analytics depth.
A flipped classroom inverts traditional instruction by delivering lecture content through pre-recorded video or digital modules before scheduled class time, then using synchronous sessions for application, discussion, and remediation; this architecture demands asynchronous video hosting, embedded formative assessment tools, and learning management system integration. Blended Learning dominates current implementation patterns across K-12 and higher education, while Self-Paced modules capture the fastest expansion in corporate training environments where schedule flexibility governs engagement. Interactive Whiteboard hardware anchors premium classroom retrofit budgets, though Tablet and Laptop volumes sustain the largest installed base across price-sensitive districts.
FCC E-Rate funding shapes K-12 connectivity investment thresholds, while FERPA compliance requirements constrain how Canvas by Instructure and Google for Education handle student data analytics. State-level procurement standards in California and Texas increasingly mandate interoperability certifications that filter vendor eligibility. Stakeholders must weigh platform switching costs against emerging AI-powered personalization capabilities when evaluating long-term contracts.
Market Dynamics
Cloud migration is compressing procurement timelines for higher education IT administrators, forcing synchronous session platforms and asynchronous hosting providers to integrate learning analytics or face displacement from bundled campus management suites.
Growth Catalysts
- FCC E-Rate funding thresholds:US K-12 districts access subsidized connectivity infrastructure, expanding device-per-student ratios and video streaming capacity requirements.
- FERPA compliance frameworks:Student data privacy mandates compel institutions to upgrade from consumer-grade video tools to enterprise learning management systems with audit trails.
- Asynchronous video hosting:Pre-recorded lecture modules enable schedule flexibility that attracts non-traditional and working learners into degree completion programs.
Market Restraints
- Interoperability certification costs:California and Texas state procurement standards mandate Learning Information Services certification, filtering smaller platform vendors from eligibility pools.
- Hardware refresh cycles:Interactive whiteboard and tablet deployment requires capital allocation that competes with cybersecurity and physical infrastructure budgets.
- Faculty development timelines:Pedagogical retraining for active learning facilitation extends implementation phases beyond single budget cycles.
Strategic Opportunities
- Corporate training environments:Self-paced module architectures capture schedule-constrained professional learners seeking micro-credentialing outside traditional semester structures.
- Learning analytics convergence:Embedded formative assessment tools integrated with student information systems enable predictive intervention workflows.
- Hybrid infrastructure mandates:District-level technology budgets prioritize flexible classroom designs supporting both in-person and remote synchronous delivery.
Industry Challenges
- Legacy LMS integration complexity:Canvas by Instructure and Google for Education environments require custom API development to synchronize video analytics with gradebook systems.
- Instructional design capacity gaps:Institutions lack sufficient staff to convert lecture content into chunked digital modules with embedded knowledge checks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flipped Classroom Market |
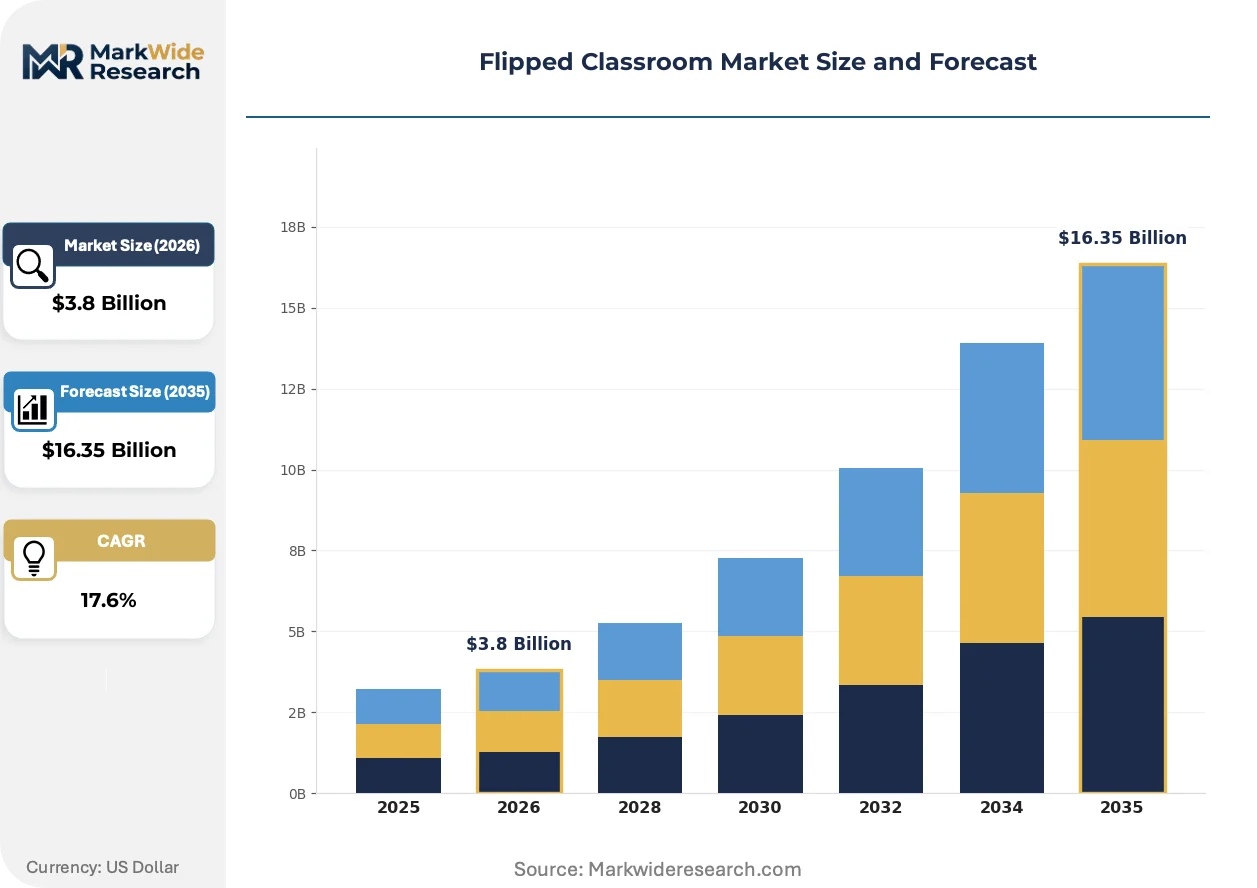
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Learning Mode: Blended Learning, Synchronous, Asynchronous, Hybrid, Self-Paced Device Type: Tablet, Laptop, Smartphone, Desktop Computer, Interactive Whiteboard End User: K-12 Schools, Higher Education, Corporate Training, Vocational Institutes, Language Centers Content Delivery: Video Lectures, Interactive Quizzes, Discussion Forums, Digital Textbooks, Gamified Modules |
| Companies Covered | Cisco Systems, Dell Technologies, Crestron Electronics, Echo360, Panopto, Coursera, Khan Academy, Canvas by Instructure, Google for Education, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flipped Classroom Market Shifts & Advancements
Artificial intelligence capabilities are embedding directly into video platforms, automating transcription, content indexing, and personalized study pathway generation that reshapes how institutions evaluate vendor proposals.
Immersive simulation environments are virtualizing laboratory and clinical instruction for health sciences and engineering programs. Medical schools and nursing programs deploy virtual patient scenarios ahead of physical skills labs. This technology is virtualizing expensive physical infrastructure requirements while maintaining accreditation standards for hands-on training hours.
FCC E-Rate modernization is expanding eligible services to include cybersecurity and advanced firewall protections for K-12 networks. District administrators now bundle connectivity procurement with content filtering and threat monitoring. Rural and urban districts with limited IT staffing rely most heavily on these consolidated service offerings.
Subscription-based content licensing is displacing perpetual software purchases across community college systems. Procurement officers negotiate multi-year platform access with embedded professional development credits. California community college districts demonstrate this shift most visibly, with system-wide master agreements reducing per-campus negotiation overhead.
Flipped Classroom Market Segmentation
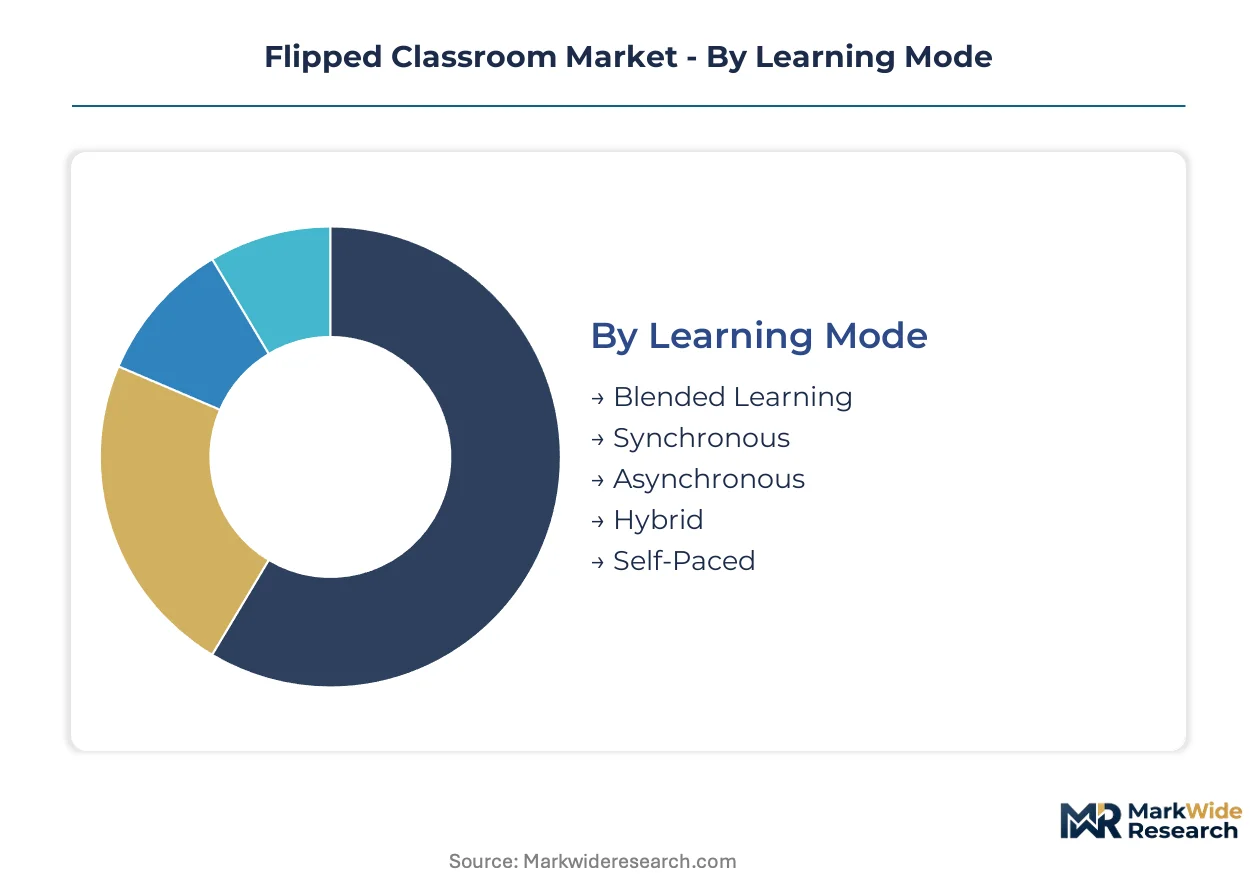
Segmentation in the flipped classroom market reveals distinct procurement patterns across learning architectures, hardware refresh cycles, and institutional buyer profiles. Each dimension carries different after-sales service intensity, from minimal-touch self-paced modules to high-touch enterprise LMS deployments requiring ongoing faculty support and analytics integration.
Learning Mode:
After-sales service intensity varies sharply across learning modes, with synchronous and hybrid deployments demanding 24/7 technical support for live session reliability while self-paced architectures minimize ongoing vendor touchpoints.
- Blended Learning:Combines scheduled face-to-face sessions with pre-recorded digital content delivery, requiring tight LMS-gradebook synchronization. K-12 districts in Texas and California concentrate procurement here, constrained by state interoperability mandates that filter vendor pools.
- Self-Paced:Modular architectures grant learners schedule autonomy through chunked content with embedded knowledge checks. Corporate training environments in professional services and technology sectors drive fastest expansion, prioritizing micro-credentialing outside semester structures.
- Synchronous:Real-time video conferencing for scheduled virtual sessions demands low-latency infrastructure and immediate technical escalation pathways.
- Asynchronous:Pre-recorded lecture hosting enables time-shifted consumption but requires automated transcription and content indexing services.
- Hybrid:Flexible classroom designs supporting simultaneous in-person and remote participation impose dual infrastructure maintenance obligations on IT departments.
Blended Learning holds the largest share; momentum sits with Self-Paced architectures.
Device Type:
Cost tier segmentation separates premium interactive whiteboard retrofits from volume tablet and laptop deployments, with hardware refresh cycles competing against cybersecurity and physical infrastructure budgets.
- Tablet:Touch-enabled portable devices dominate price-sensitive K-12 one-to-one initiatives. Volume procurement concentrates in US districts leveraging FCC E-Rate subsidies, though shorter replacement cycles strain capital planning.
- Interactive Whiteboard:Large-format touch displays anchor premium classroom retrofit budgets with bundled stylus and annotation software. Higher education institutions in research-intensive clusters prioritize these for collaborative STEM instruction, accepting higher per-unit costs for durability and warranty coverage.
- Laptop:Full-keyboard portable computers sustain the broadest installed base across secondary and postsecondary environments.
- Smartphone:Personal mobile devices supplement formal instruction through microlearning apps but face FERPA compliance barriers for primary content delivery.
- Desktop Computer:Fixed workstation deployments persist in computer labs and library settings with lower mobility requirements.
Tablet captures the greatest unit volume; Interactive Whiteboard commands the steepest expansion trajectory in premium segments.
End User:
Customer type segmentation distinguishes institutional procurement authority structures, from centralized district technology offices in K-12 to decentralized academic department budgets in higher education.
- Higher Education:Universities and colleges with distributed academic departments demand enterprise-grade analytics integration with student information systems. North American institutions lead procurement volume, compressing evaluation timelines as cloud migration accelerates.
- K-12 Schools:District-level technology offices manage standardized device-per-student ratios and video streaming capacity. FCC E-Rate funding thresholds shape connectivity investment, while state procurement standards in California and Texas mandate Learning Information Services certification.
- Corporate Training:Enterprise learning and development departments prioritize schedule flexibility and skills-based credentialing over semester structures.
- Vocational Institutes:Career-focused programs blend hands-on lab instruction with digital theory modules, requiring specialized simulation content.
- Language Centers:Intensive oral proficiency training demands high-fidelity audio capture and pronunciation analysis tools.
Higher Education holds the largest share; Corporate Training is gaining share fastest among non-traditional learners.
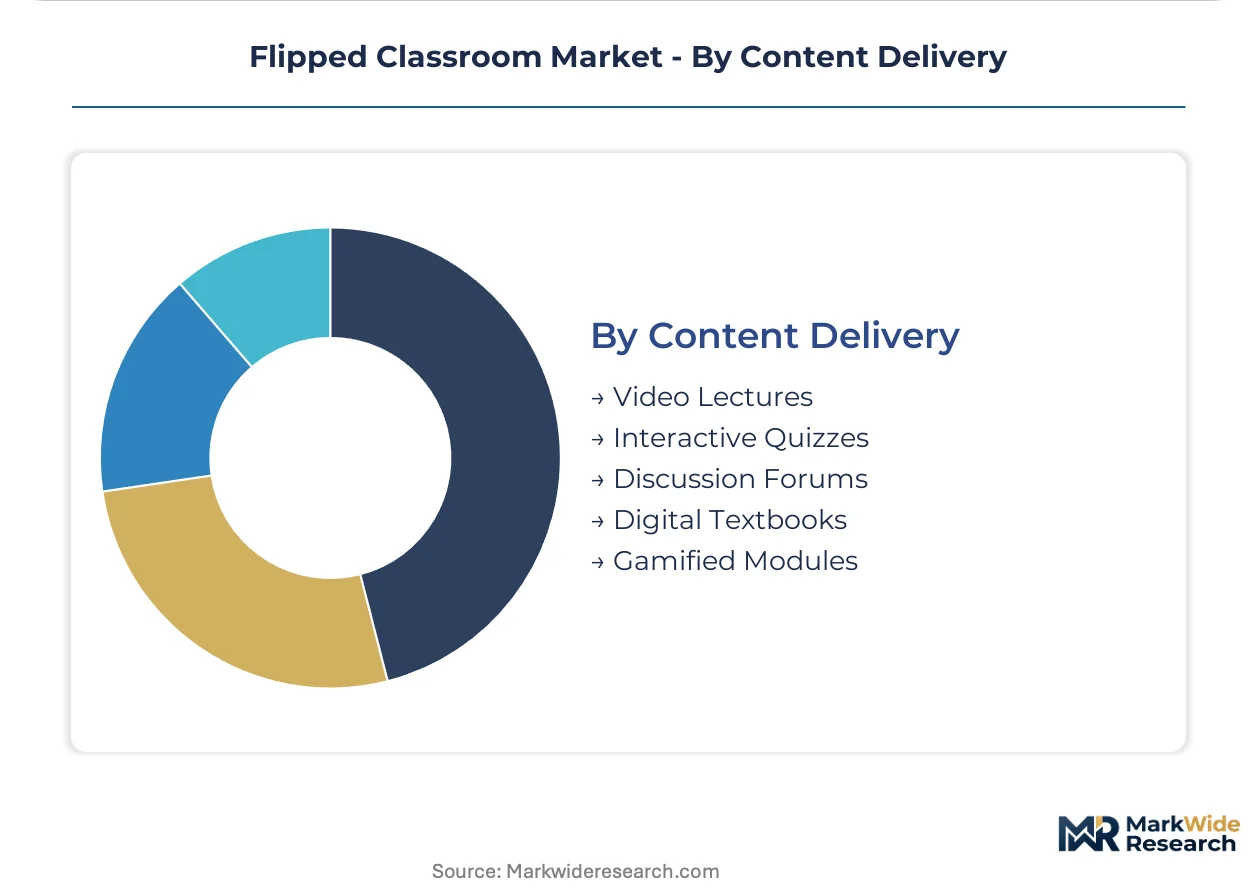
Content Delivery:
Maturity segmentation separates established video lecture formats from emerging gamified and immersive modalities, with implementation complexity rising alongside interactivity depth.
- Video Lectures:Pre-recorded instructor presentations with automated transcription and chapter indexing form the foundational content layer. Higher education institutions across the United States standardize on this format, though instructional design capacity gaps delay conversion of legacy lecture materials.
- Interactive Quizzes:Embedded formative assessments with immediate feedback loops enable predictive intervention workflows. Health sciences programs in medical schools and nursing colleges concentrate adoption here, linking performance data to accreditation compliance documentation.
- Discussion Forums:Asynchronous text-based collaboration tools support peer interaction outside scheduled sessions.
- Digital Textbooks:DRM-protected electronic course materials with annotation and search capabilities replace physical print procurement.
- Gamified Modules:Points, badges, and progression mechanics overlay learning content to sustain engagement in self-paced environments.
Video Lectures holds the largest share; momentum sits with Interactive Quizzes as analytics convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States higher education procurement offices, where bundled platform contracts command premium analytics integration fees, while Indian state universities negotiate per-seat SaaS rates that compress vendor margins.
United States
District-level technology offices in Texas and California drive K-12 hardware refresh cycles through FCC E-Rate subsidies, with state procurement standards mandating Learning Information Services certification. FERPA compliance frameworks compel institutions to migrate from consumer-grade video tools toward enterprise learning management systems with audit trails. The Research Triangle in North Carolina anchors large university deployments, where Cisco Systems leverages networking infrastructure to capture multi-year campus management contracts.
Canada
Provincial education ministries in Ontario and British Columbia standardize asynchronous video hosting across community college systems, prioritizing interoperability with existing student information systems. Privacy commissioners at federal and provincial levels enforce PIPEDA compliance for student data analytics, filtering vendor eligibility toward domestic cloud providers. Toronto and Vancouver metropolitan clusters concentrate procurement authority, with subscription-based content licensing displacing perpetual software purchases across college districts.
United Kingdom
Higher education institutions in England and Scotland compress evaluation timelines as cloud migration accelerates, demanding enterprise-grade analytics integration with decentralized academic department budgets. The Information Commissioner's Office enforces GDPR compliance for student data processing, constraining how international platforms handle cross-border analytics. The Golden Triangle of Oxford, Cambridge, and London anchors research-intensive university deployments, where premium interactive whiteboard retrofits compete for STEM instruction budgets.
Germany
Federal state education ministries in Bavaria and North Rhine-Westphalia mandate interoperability certifications for learning management system procurement, filtering smaller platform vendors from eligibility pools. The Kultusministerkonferenz coordinates standards that constrain vendor switching costs for long-term contracts. Munich and Berlin metropolitan regions concentrate corporate training demand, where self-paced module architectures capture schedule-constrained professional learners in automotive and industrial engineering sectors.
India
Central and state universities expand device-per-student ratios through National Education Policy digital infrastructure allocations, prioritizing tablet deployments in price-sensitive districts. The Ministry of Education's DIKSHA platform shapes content standards, while the University Grants Commission mandates accreditation compliance for online degree programs. Bangalore and Hyderabad technology corridors anchor corporate training demand, where micro-credentialing platforms compete for IT services sector workforce upskilling contracts.
Flipped Classroom Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in hardware and content layers. The vendor base fragments across three functional strata: networking infrastructure providers bundling campus-wide deployments, learning management system operators competing on analytics depth, and zero-cost content platforms forcing paid alternatives toward differentiation. Strategic moves concentrate on cloud migration partnerships and AI-powered personalization capability integration.
Among networking-centric platform providers, Cisco Systems and Dell Technologies exemplify the infrastructure-anchored archetype, leveraging hardware refresh cycles to capture bundled device-and-management contracts. Khan Academy occupies a distinct position in the zero-cost content tier, compelling paid platforms toward analytics-driven differentiation. Canvas by Instructure and Google for Education sit within the enterprise learning management tier, where legacy system integration complexity shapes procurement evaluation criteria for IT administrators.
| Leading Market Players |
|---|
| Cisco Systems |
| Dell Technologies |
| Crestron Electronics |
| Echo360 |
| Panopto |
| Coursera |
| Khan Academy |
| Canvas by Instructure |
| Google for Education |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States anchors margin capture for enterprise learning management suites, while hardware assembly in Taiwan and South Korea shapes device procurement economics for K-12 districts balancing FCC E-Rate subsidies against refresh cycle pressures.
Pricing Analysis
Configured-to-order analytics bundles command 40-60% premiums over standard SaaS tiers in higher education procurement. Three-tier pricing structure across premium, standard, and economy levels segments by interoperability certification depth and embedded AI personalization capabilities. Cost compression in the tablet tier intensifies because Chinese OEMs flood volume segments, while interactive whiteboard premiums hold firm in research-intensive university clusters. Corporate training buyers exhibit highest price sensitivity, accepting stripped-down self-paced modules; K-12 districts show lowest sensitivity where bundled E-Rate eligibility filters alternatives.
Supply Chain Analysis
Export-control restrictions on advanced GPU and AI accelerator chips limit flows from NVIDIA and AMD to Chinese EdTech platforms, redirecting supply toward North American and European institutional buyers. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; display panel production centers on China and South Korea. Cloud data center hardware draws from Taiwanese ODMs, while learning content production rests on Indian instructional design labor pools. Single-source vulnerability runs through TSMC's advanced node capacity for AI-enabled video analytics chips. Distribution runs through direct-to-institution enterprise sales teams and regional VAR networks serving district technology offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
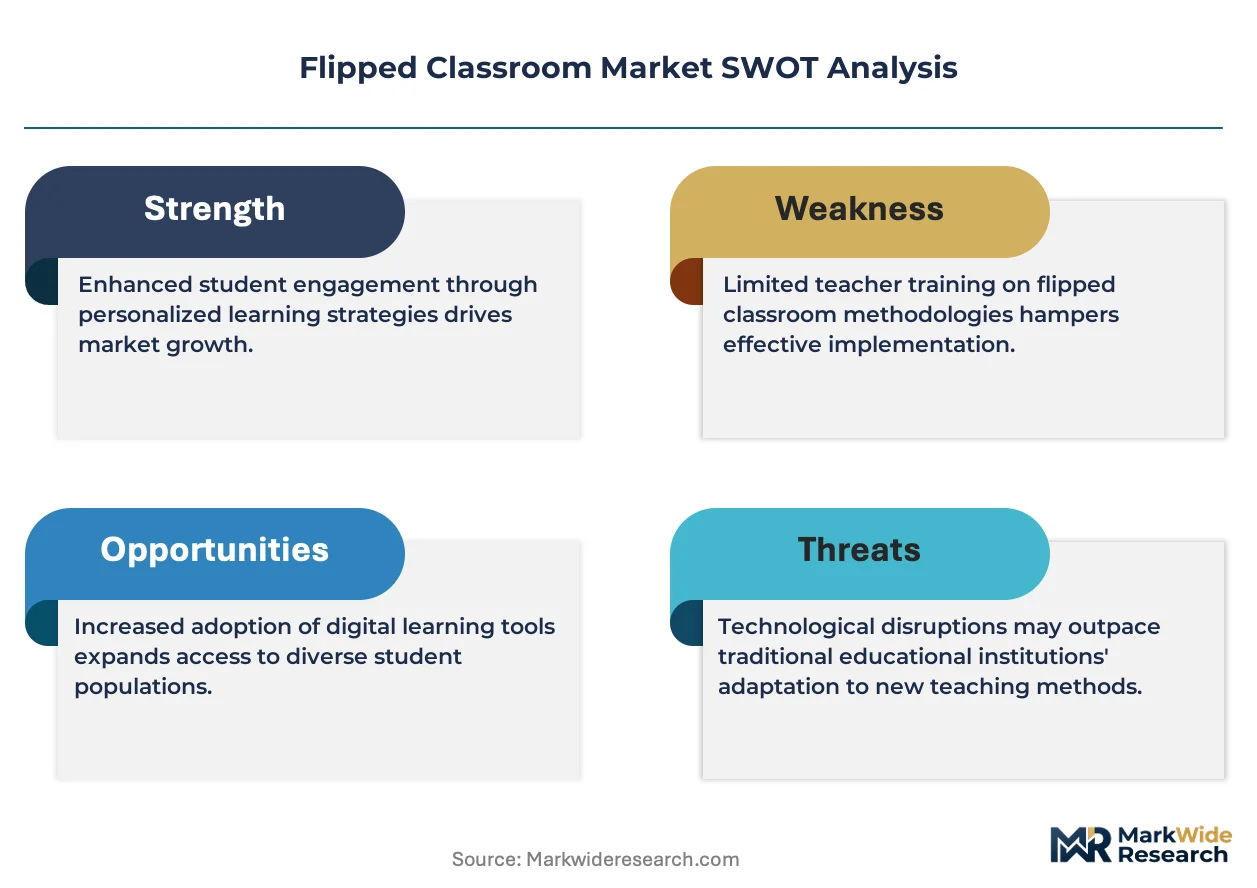
This market functions as a defensive-moat arena where FERPA compliance entrenchment and LMS switching costs protect incumbent positions against platform fragmentation.
For Market Incumbents: Harden data residency architectures to preempt state-level procurement mandates in California and Texas. Deepen backward integration into cloud infrastructure to capture margin pools escaping to hyperscalers. Khan Academy's zero-cost model and emerging AI-native entrants threaten pricing power; certification investments in Learning Information Services interoperability anchor long-term contract renewals. For New Entrants and Emerging Players: Mid-tier community college systems in Canada and Germany represent the most penetrable entry point, where subscription fatigue with legacy LMS operators creates evaluation windows. Corporate training environments in Indian IT services corridors offer parallel white-space, with micro-credentialing demand outpacing incumbent platform flexibility. A vertical-specific go-to-market targeting nursing and allied health simulation content bypasses generalized video hosting competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed learning analytics specialists carrying 2018-2021 vintage platform investments. Long-term viability hinges on AI-powered personalization capability integration and SIS interoperability depth. Watch for inflection where state procurement offices mandate real-time learning data portability as a contract precondition, forcing consolidation among point-solution vendors.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Personalization Integration | Canvas by Instructure and Google for Education embed predictive analytics to differentiate against Khan Academy's free tier. |
| Backward Integration into Cloud Infrastructure | Cisco Systems captures margin pools by bundling networking hardware with campus-wide LMS deployment management. |
| Interoperability Certification Investment | Texas and California state mandates filter vendor eligibility toward platforms with Learning Information Services compliance. |
| Vertical-Specific Content Development | Medical schools and nursing programs demand virtual patient scenarios that generalist platforms cannot replicate. |
| Subscription-Based Licensing Conversion | California community college master agreements demonstrate multi-year platform access with embedded professional development credits. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, FCC E-Rate disbursement databases, state procurement registries, and learning management system interoperability certification records. Interviews with higher education CIOs, K-12 district technology directors, instructional design leads, and corporate L&D officers informed demand-side assumptions. Vendor-side validation drew from EdTech platform executives, cloud infrastructure specialists, and hardware OEM account managers. Bottom-up segmentation modeling triangulated against top-down market sizing from trade associations and regulatory filings.
Forecast inputs span learning mode adoption curves, device refresh cycle timing, and interoperability mandate implementation schedules across the projection horizon. Segmentation dimensions include learning architecture, hardware tier, institutional buyer type, and content delivery modality. CAGRs derive from logistic diffusion curves fitted to historical LMS deployment patterns and cloud migration timelines. AI capability integration pace and E-Rate funding authorization levels serve as scenario-dependent inputs.
Stress conditions across FCC funding volatility, state procurement standard acceleration, and faculty development capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding interoperability adoption timelines and cloud infrastructure cost trajectories. Material shifts in federal education technology appropriations or GDPR-equivalent federal privacy legislation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Education Technology Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market