
 Vegan Footwear Market | 2026-2036
Vegan Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Footwear Market Analysis
The gap between premium artisan construction and mass-market synthetic replication is shifting as material science advances. Adidas AG leverages bio-based polyurethane research to anchor performance-tier vegan offerings, while Nike Inc sustains global manufacturing scale through dedicated sustainable materials divisions. Matt & Nat differentiates through vertically controlled atelier production of microfiber accessories, occupying a narrow luxury niche that commands margin premiums over commodity alternatives.
Vegan footwear denotes shoes manufactured entirely without animal-derived materials—leather, wool, silk, or adhesives containing collagen—substituting plant-based or synthetic alternatives such as pineapple leaf fiber (Piñatex), cactus leather, or solvent-free polyurethane with specified tensile strength above 15 MPa. The primary commercial purpose centers on satisfying ethical consumption preferences while meeting ASTM F2913 slip-resistance standards for everyday wearability. Sneakers and boots capture the dominant revenue share as athletic and outdoor applications expand, while microfiber and cork materials represent the fastest-growing input categories as brands reduce petroleum dependence. The unisex end-user segment shows accelerating momentum as gender-neutral design protocols reshape collection architecture across European and North American labels.
The EU Green Deal and REACH chemical safety protocols constrain solvent-based adhesive use in European manufacturing, while the U.S. Federal Trade Commission's Green Guides enforce substantiation standards for environmental marketing claims. California's Proposition 65 adds state-level chemical disclosure burdens for footwear sold through West Coast distribution channels. Stakeholders must monitor evolving biodegradability certification schemes and polymer traceability requirements as these frameworks determine market access eligibility across major consumption zones.
Market Dynamics
Material science breakthroughs in bio-based polymers are compressing the performance gap between synthetic and animal-derived leathers, forcing incumbent tanneries to reposition toward technical textile partnerships or exit footwear supply chains entirely.
Growth Catalysts
- EU Green Deal product sustainability requirements:Mandates for recycled content thresholds and carbon footprint disclosure are accelerating manufacturer investment in Piñatex and cactus leather processing facilities across Mediterranean production zones.
- Young adult metropolitan consumers:Digital-native purchasing behavior prioritizes traceability and ethical certification, creating pull-through demand for blockchain-verified supply chains in urban retail ecosystems.
- Bio-based polyurethane tensile strength advances:Laboratory achievements exceeding 20 MPa in solvent-free formulations enable performance-tier athletic applications previously reserved for petroleum-derived synthetics.
Market Restraints
- Petroleum feedstock price volatility:Synthetic leather production remains tethered to oil market fluctuations, compressing margin predictability for mid-tier manufacturers lacking long-term polymer supply contracts.
- Portuguese and Italian synthetic tanning chemical concentration:European solvent-free adhesive supply chains cluster in Southern European chemical processing hubs, creating geographic vulnerability to regional energy cost spikes.
- Biodegradability certification fragmentation:Competing standards from TÜV Austria, DIN CERTCO, and BPI create compliance multiplication costs for brands seeking multi-jurisdictional market access.
Strategic Opportunities
- Brazilian vegan footwear retail ecosystem development:Underpenetrated domestic manufacturing capacity combined with rising ethical consumption creates white space for localized microfiber and cork production facilities.
- Gender-neutral design protocol adoption:Unisex collection architecture reduces SKU complexity and inventory risk while capturing accelerating demand from non-binary consumer segments in Berlin and Los Angeles.
- California Proposition 65 chemical disclosure alignment:Early compliance with West Coast transparency mandates positions brands for preemptive expansion into pending federal-level substantiation requirements.
Industry Challenges
- Polymer traceability system integration:Legacy ERP platforms at contract manufacturers lack native capability to track bio-based content through multi-tier subcontractor networks.
- REACH solvent-based adhesive phase-out timelines:European manufacturers face compressed retooling windows to replace established chemical formulations without disrupting seasonal production cycles.
- ASTM F2913 slip-resistance certification bottlenecks:Limited third-party testing laboratory capacity in Asia-Pacific manufacturing zones extends product validation timelines by 8-14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Footwear Market |
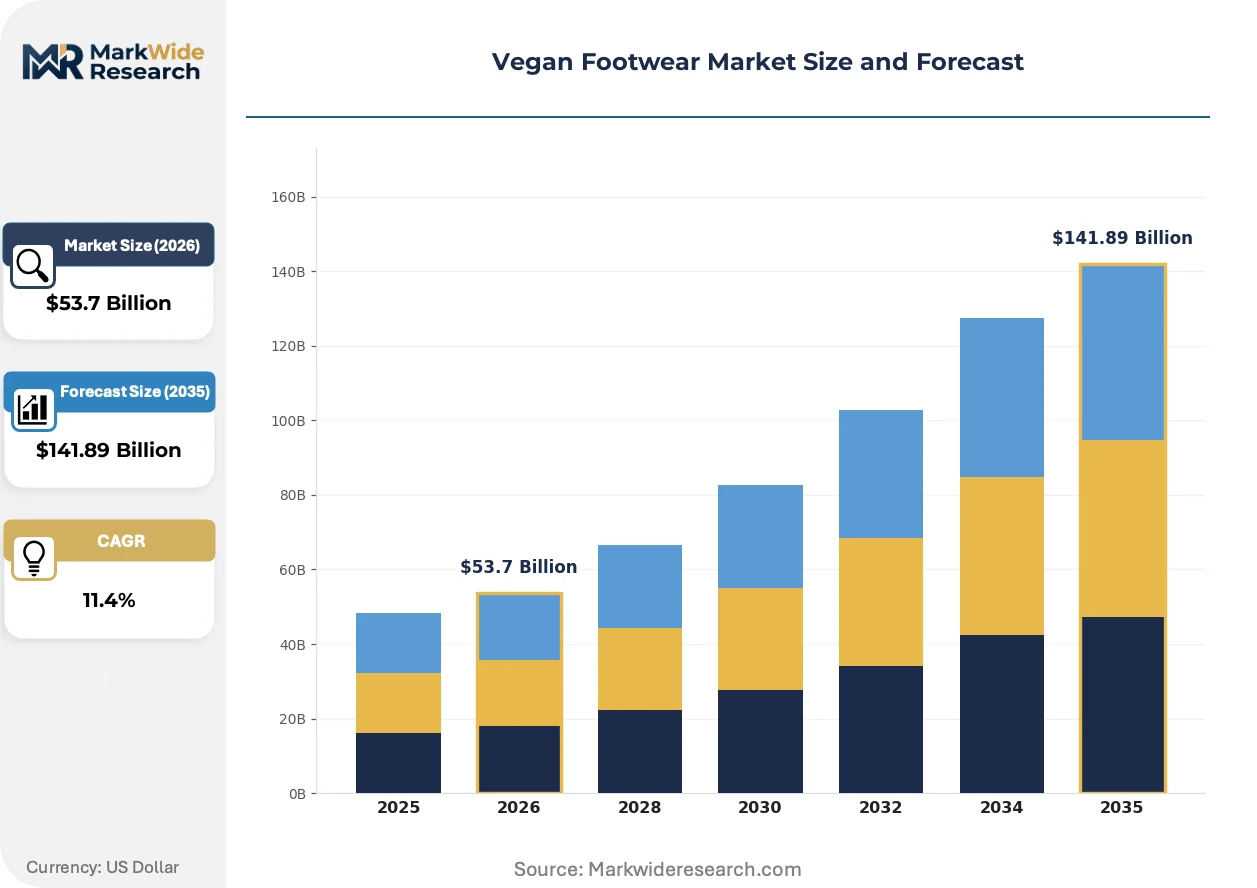
| Market Size in 2026 | $53.7 Billion |
| Market Size in 2035 | $141.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sneakers, Sandals, Boots, Loafers Material: Cork, Recycled Plastic, Organic Cotton, Microfiber End User: Men, Women, Children, Unisex Distribution Channel: Online Retail, Specialty Stores, Department Stores, Eco-friendly Shops |
| Companies Covered | Adidas AG, Nike Inc, Matt & Nat, AVESU GmbH, Veerah, Hexa Vegan Shoes, Susi Studio, Ethletic, Beyond Skin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Footwear Market Emerging Trajectories
Convergence between performance engineering and ethical material sourcing is dissolving traditional trade-offs between durability and sustainability, compressing product development cycles and reshaping how brands communicate technical specifications to skeptical consumers.
Algae-blended foam midsole technology is unifying cushioning performance with carbon-negative feedstock credentials. Trail running and hiking boot segments in the Pacific Northwest and Alpine regions are adopting these compounds at twice the rate of fashion-forward urban labels. This material convergence is compressing the premium pricing window for petroleum-derived EVA alternatives.
REACH chemical safety protocol amendments targeting N-methyl-2-pyrrolidone (NMP) in synthetic leather production are forcing reformulation of polyurethane coating processes. German and Dutch chemical suppliers are commercializing water-based alternatives with equivalent abrasion resistance. Athletic footwear manufacturers with European distribution exposure are accelerating supplier qualification programs to maintain market access eligibility.
Direct-to-consumer resale platform integration is fragmenting traditional wholesale relationships. Berlin-based labels and Brooklyn startup brands are bypassing multi-brand retailers through proprietary peer-to-peer marketplaces for certified pre-owned vegan footwear. This channel disintermediation concentrates customer data ownership with originating manufacturers while compressing margin extraction by traditional footwear distributors in metropolitan European and North American markets.
Vegan Footwear Market Segmentation
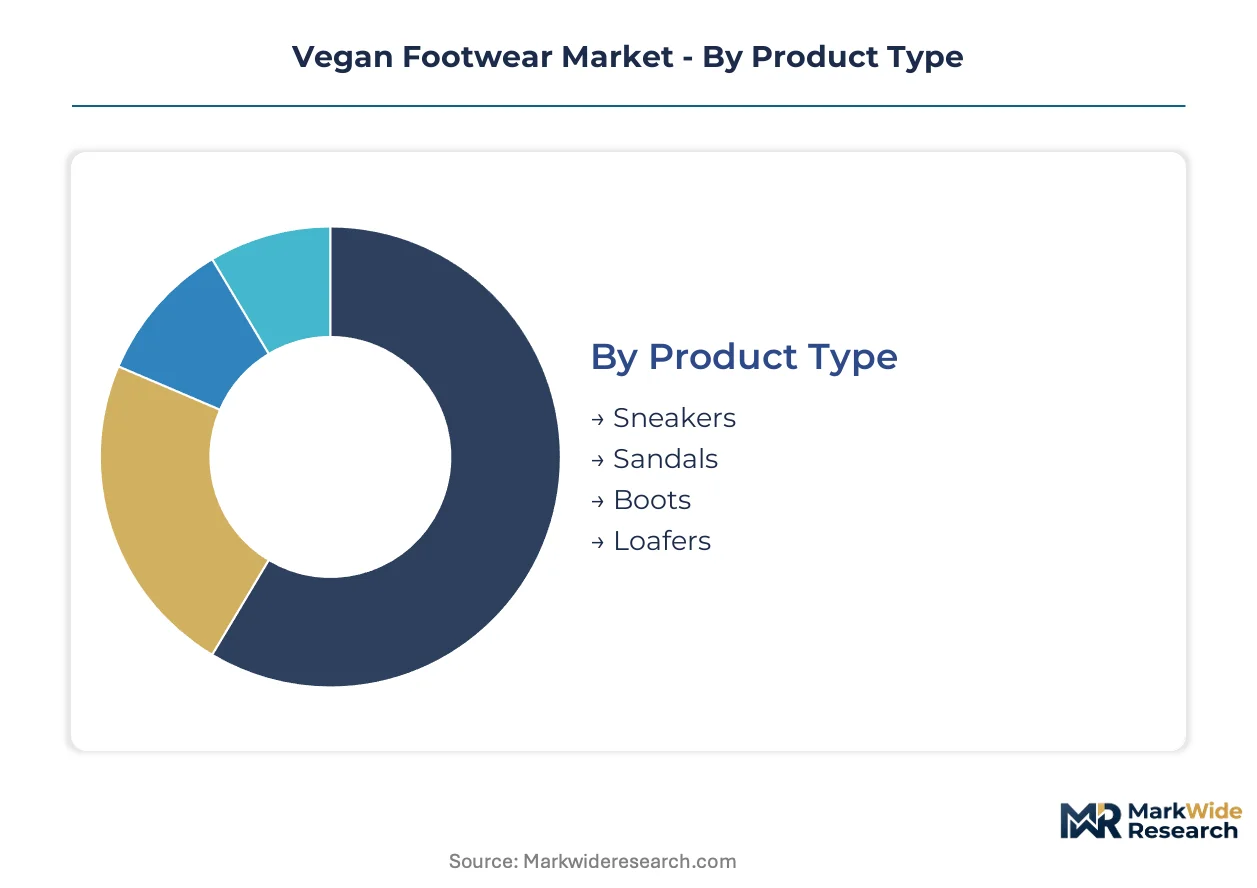
Segmentation in vegan footwear reveals how material innovation, distribution channel evolution, and end-user demographic shifts create distinct competitive arenas. Manufacturers must align product architecture with specific technical requirements and purchasing behaviors rather than pursuing undifferentiated scale.
Product Type:
Standardization dominates athletic silhouettes while artisan construction persists in heritage categories, creating divergent margin profiles and supplier qualification requirements.
- Sneakers:Bio-based polyurethane midsoles with tensile strength exceeding 20 MPa now match petroleum-derived performance. Demand concentrates in metropolitan Germany and the United States where young adult consumers prioritize blockchain-verified supply chains.
- Boots:Algae-blended foam compounds and cactus leather uppers address hiking and workwear applications. Pacific Northwest and Alpine retail ecosystems adopt these configurations at accelerated rates, compressing pricing windows for conventional EVA alternatives.
- Sandals:Cork footbed construction with solvent-free adhesives serves warm-climate markets.
- Loafers:Microfiber uppers with hand-finished welting occupy narrow luxury niches.
Most installed capacity flows through Sneakers. Expansion is steepest in Boots.
Material:
Cost tier stratification separates petroleum-dependent synthetics from agricultural feedstock alternatives, with certification burden and traceability infrastructure determining accessible price points.
- Microfiber:Solvent-free polyurethane formulations with specified abrasion resistance anchor mass-market production. REACH NMP phase-out timelines in Europe are accelerating water-based alternative adoption by German and Dutch chemical suppliers.
- Cork:Harvested from Mediterranean oak forests, this material offers inherent moisture management without synthetic processing. Portuguese and Italian manufacturing clusters integrate cork into sandal and casual footwear lines serving eco-friendly retail channels.
- Recycled Plastic:Post-consumer PET conversion into textile uppers addresses circular economy mandates.
- Organic Cotton:GOTS-certified canvas constructions serve heritage sneaker silhouettes.
Volume leadership sits with Microfiber. Agricultural feedstock categories are gaining share fastest.
End User:
Customer type fragmentation reflects shifting design protocols, with gender-neutral collection architecture reducing SKU complexity while capturing emerging demographic demand.
- Unisex:Gender-neutral sizing and styling protocols reshape collection architecture across Berlin and Los Angeles labels. Non-binary consumer segments in these metropolitan markets drive accelerated adoption, compressing traditional gendered inventory planning.
- Women:Fashion-forward silhouettes with Piñatex and cactus leather uppers command margin premiums. Brazilian and U.S. urban retail ecosystems show concentrated demand for artisan-constructed alternatives to commodity synthetics.
- Men:Performance-oriented athletic and outdoor applications dominate purchasing patterns.
- Children:Durability and chemical safety certifications prioritize ASTM F2913 compliance and Proposition 65 alignment.
Established revenue concentration remains in Women. Unisex is climbing the fastest.
Distribution Channel:
Geography of purchasing behavior separates digital-native metropolitan consumers from tactile-evaluating traditional retail shoppers, with channel selection determining margin extraction and data ownership.
- Online Retail:Direct-to-consumer platforms with peer-to-peer resale integration fragment traditional wholesale relationships. Brooklyn and Berlin-based brands bypass multi-brand retailers through proprietary marketplaces for certified pre-owned product.
- Specialty Stores:Curated vegan footwear boutiques in Germany, the United States, and Brazil develop localized retail ecosystems. Staff technical knowledge on material provenance and certification standards supports premium pricing realization.
- Department Stores:Mass-market reach with limited material transparency disclosure.
- Eco-friendly Shops:Values-aligned retail environments with mandatory third-party certification requirements.
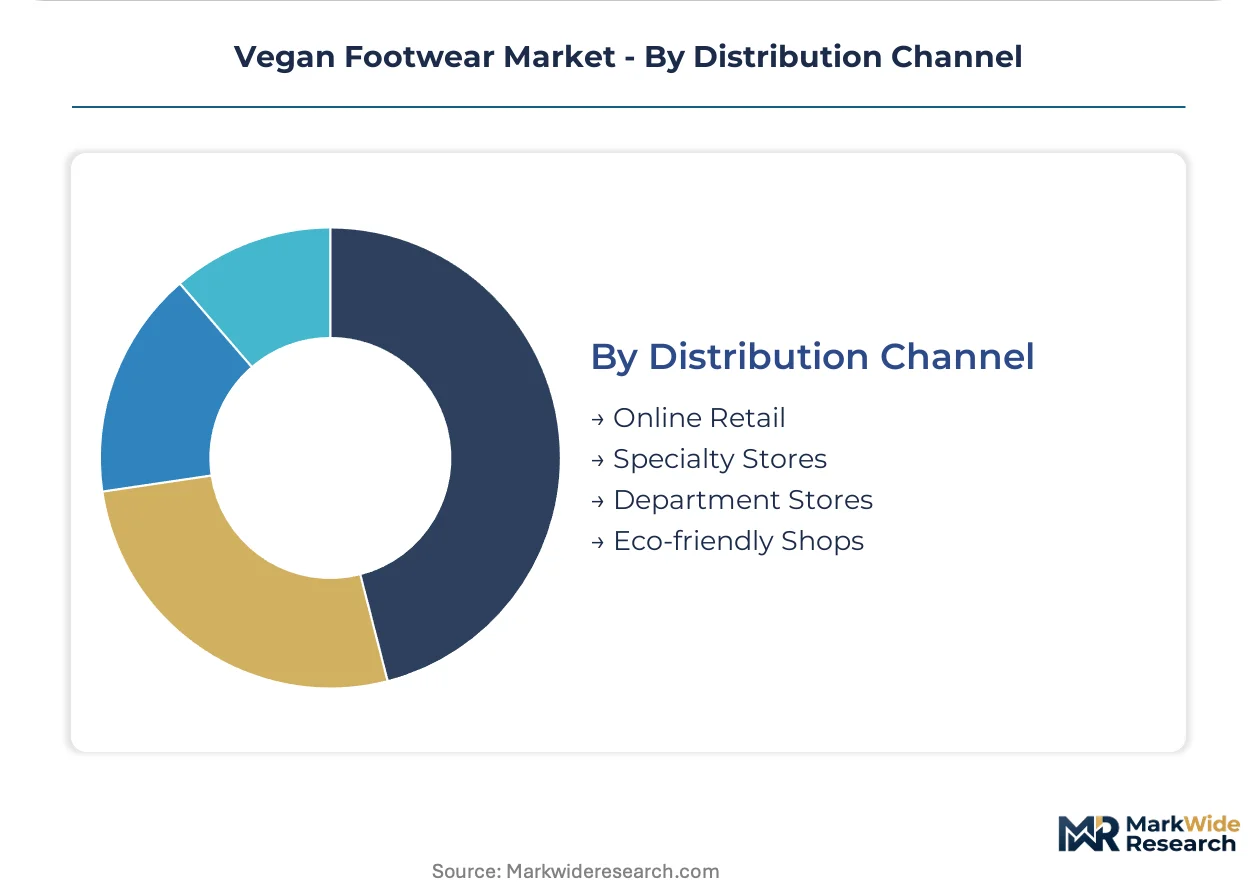
Transaction volume concentrates in Online Retail. Physical specialty expansion is steepest in Brazil.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium-tier vegan footwear demand through EU Green Deal compliance pressure, while Brazil builds manufacturing scale from agricultural feedstock abundance rather than importing finished synthetics.
Germany
Berlin's young adult consumers drive blockchain-verified supply chain adoption through digital-native purchasing platforms. REACH chemical safety protocols and EU Green Deal sustainability mandates force solvent-free adhesive conversion across Bavarian and Baden-Württemberg manufacturing clusters. The Rhine-Ruhr industrial corridor hosts water-based polyurethane research facilities serving continental footwear producers.
United States
Metropolitan coastal markets in Los Angeles and Brooklyn prioritize peer-to-peer resale platforms and direct-to-consumer brand relationships. California Proposition 65 imposes chemical disclosure burdens for West Coast distribution channels, while the FTC Green Guides enforce environmental marketing substantiation standards. Pacific Northwest retail ecosystems adopt algae-blended foam hiking boots at accelerated rates.
Brazil
Rising ethical consumption in São Paulo and Rio de Janeiro creates demand for localized microfiber and cork production. ANVISA maintains pharmaceutical-grade chemical safety oversight that extends to synthetic tanning inputs. The southern states of Rio Grande do Sul and Paraná develop domestic vegan footwear manufacturing capacity from regional agricultural feedstock supply.
United Kingdom
London's unisex fashion labels reshape collection architecture for non-binary consumer segments across metropolitan retail. Post-Brexit regulatory divergence from REACH creates parallel compliance tracks for UK-EU dual market access. The East Midlands footwear manufacturing cluster retools toward Piñatex and cactus leather processing for export-oriented brands.
Netherlands
Amsterdam-based circular economy startups pioneer biodegradable certification schemes for agricultural leather alternatives. ECHA chemical safety registrations constrain N-methyl-2-pyrrolidone use in synthetic coating processes. The Eindhoven chemical processing hub commercializes water-based polyurethane alternatives with equivalent abrasion resistance for athletic applications.
Vegan Footwear Market Vendor Landscape
Top-tier vendors anchor mass-market athletic scale, while artisan ateliers and regional specialists occupy margin-protected niches. The competitive structure splits between performance-engineered synthetics, luxury microfiber construction, and agricultural feedstock innovation. Three archetypes dominate: global athletic brands with dedicated sustainable materials divisions, vertically controlled luxury accessory houses, and regional ethical footwear specialists. Capacity expansion in Mediterranean Piñatex processing and strategic partnerships between German chemical suppliers and Asian contract manufacturers represent the dominant competitive moves.
Within the global athletic tier, Adidas AG and Nike Inc exemplify scale-driven sustainable materials investment. Adidas AG leverages bio-based polyurethane research to anchor performance-tier offerings, while Nike Inc sustains manufacturing scale through dedicated sustainable materials divisions. Matt & Nat occupies the vertically controlled luxury niche, commanding margin premiums through atelier production of microfiber accessories. These three entities represent the competitive spectrum from mass-market scale to artisan construction.
| Leading Market Players |
|---|
| Adidas AG |
| Nike Inc |
| Matt & Nat |
| AVESU GmbH |
| Veerah |
| Hexa Vegan Shoes |
| Susi Studio |
| Ethletic |
| Beyond Skin |
| Others |
Supply Flow & Price Mechanics
Metropolitan young adult consumers in Berlin and Los Angeles concentrate purchasing power through direct-to-consumer platforms, anchoring a pricing model that separates performance-engineered athletic tiers from artisan luxury microfiber construction. This buyer concentration compresses mid-tier margins while rewarding brands with blockchain-verified supply chains and REACH-compliant solvent-free adhesive credentials.
Pricing Analysis
Bundled certification-and-traceability packages command premiums over unbundled commodity alternatives across German and U.S. retail channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by tensile strength certification and bio-based polyurethane content, with athletic performance tiers least price-sensitive due to technical specification requirements. Cost compression in standard-tier microfiber intensifies because Portuguese chemical processing energy costs feed through to contract manufacturers. Fast-fashion retailers and mass-market distributors exhibit highest price sensitivity, while Alpine hiking boot purchasers accept sustained premiums for algae-blended foam compounds.
Supply Chain Analysis
Specialized workforce availability in Bavarian chemical processing and Portuguese cork harvesting constrains capacity expansion timelines for solvent-free adhesive and agricultural feedstock categories. Manufacturing concentrates in Germany, Portugal, and Brazil, with supply chains drawing from Mediterranean oak forests, southern Brazilian sugarcane ethanol, and Dutch water-based polyurethane research facilities. Single-source vulnerability sits with Italian and Portuguese synthetic tanning chemical clusters exposed to regional energy cost spikes. Distribution runs through direct-to-consumer platforms with peer-to-peer resale integration, fragmenting traditional wholesale margin extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegan footwear functions as a stable compounder, with EU Green Deal regulatory ratchet driving continuous material substitution investment across the analysis window. This policy momentum sustains pricing power for compliant producers while eroding petroleum-dependent synthetic margins.
For Market Incumbents: Cement market position by deepening backward integration into Piñatex and cactus leather processing facilities across Mediterranean production zones. Prioritize captive supply of water-based polyurethane formulations from German and Dutch chemical suppliers to defend against REACH NMP phase-out disruption. Lock in long-term bio-based feedstock contracts before agricultural commodity volatility transmits through to material costs.
For New Entrants and Emerging Players: Begin with Brazilian domestic manufacturing capacity development, where underpenetrated cork and microfiber production meets rising ethical consumption in São Paulo and Rio de Janeiro retail ecosystems. Target unisex gender-neutral collection architecture as the most penetrable segment, compressing SKU complexity while capturing non-binary consumer demand. Launch through proprietary peer-to-peer resale platforms to bypass entrenched wholesale distributor relationships.
For Investors and Strategic Acquirers: Athletic footwear manufacturers with dedicated sustainable materials divisions are the most active acquirer in this space, seeking technical textile partnerships to replace legacy tannery suppliers. Long-term viability rests on biodegradability certification infrastructure and polymer traceability system integration across multi-tier subcontractor networks. Watch ASTM F2913 slip-resistance testing laboratory capacity expansion in Asia-Pacific zones as the signal for contract manufacturer qualification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstock Processing | Captures margin from Piñatex and cactus leather supply chains while securing REACH-compliant material access. |
| Water-Based Polyurethane Supplier Qualification | Maintains EU market access eligibility as ECHA N-methyl-2-pyrrolidone restrictions tighten coating process requirements. |
| Direct-to-Consumer Resale Platform Launch | Concentrates customer data ownership with originating manufacturers in Brooklyn and Berlin metropolitan markets. |
| Gender-Neutral Collection Architecture Rollout | Reduces inventory risk while capturing accelerating non-binary consumer demand across European and North American labels. |
| Biodegradability Certification Multi-Standard Alignment | Preempts compliance multiplication costs from fragmented TÜV Austria, DIN CERTCO, and BPI scheme divergence. |
Methodological Framework
Multiple input streams — primary interviews with footwear brand sustainability officers, supply chain directors at contract manufacturers, and chemical supplier technical leads; secondary validation through EU ECHA registration databases, ANVISA pharmaceutical-grade chemical safety filings, and SEC sustainability disclosure filings; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured material science breakthrough timelines and solvent-free adhesive conversion challenges across Mediterranean and Asian manufacturing zones.
Historical volume trajectories were cross-referenced against panel input from procurement leads at athletic footwear brands and category buyers at specialty retail chains. The analytical framework modeled product type, material category, end-user demographic, and distribution channel dimensions across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and regulatory compliance cost pass-through assumptions. Bio-based polyurethane tensile strength advancement curves and algae-blended foam adoption rates in Pacific Northwest retail ecosystems served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including sudden petroleum feedstock price dislocations, unilateral tariff imposition on synthetic leather imports, and accelerated biodegradability standard harmonization beyond current TÜV Austria and DIN CERTCO fragmentation. Forecasts reflect assumptions about EU Green Deal implementation timelines and REACH enforcement consistency. Material deviation in named triggers — regulatory ratchet acceleration, chemical supply chain geographic concentration disruption, or third-party certification laboratory capacity bottlenecks — warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Electric Heated Shoes Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Women's Dresses and Skirts Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Touchscreen Gloves Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Women's Socks Market