
 Mister Cap Market | 2026-2036
Mister Cap Market Size, Share, and Industry Trends Forecast 2026-2036
Mister Cap Market Foresight
Sports fan merchandise adoption is expanding across licensed headwear categories, reshaping procurement priorities for stadium retail and e-commerce channels. Flutter Entertainment leverages its digital wagering platform to cross-promote branded caps through fan engagement ecosystems. Las Vegas Sands anchors its hospitality merchandising strategy with exclusive headwear lines tied to entertainment properties. DraftKings competes through limited-edition sports league collaborations that drive direct-to-consumer cap sales.
A mister cap denotes a structured or unstructured headwear garment engineered with specified crown height, visor curvature, and closure mechanisms for adjustable or fitted wear. Manufacturing employs pattern grading, fused buckram interfacing, and embroidered or heat-transferred appliqué to achieve dimensional stability and brand visibility. Snapback caps lead volume through retro styling cycles and hip-hop fashion crossover appeal, while polyester blends capture share in performance-oriented sports fan segments where moisture-wicking properties command priority. Online retail channels concentrate margin pools through direct brand relationships and reduced wholesale intermediation, though specialty stores sustain premium positioning for limited releases.
REACH compliance in Europe and evolving textile safety standards tighten material specifications for imported caps, elevating testing costs for cotton and acrylic suppliers. The US Consumer Product Safety Commission governs small-part regulations for children's headwear, constraining design options in that target audience segment. Stakeholders must monitor how sports league licensing agreements restructure exclusive manufacturing partnerships and redirect volume toward vertically integrated suppliers.
Market Dynamics
Licensing concentration among professional sports leagues is restructuring manufacturing partnerships, redirecting volume toward vertically integrated suppliers capable of meeting exclusivity and speed-to-market requirements.
Growth Catalysts
- REACH compliance:European textile safety mandates are elevating material traceability standards, compelling suppliers to upgrade testing protocols and capturing premium positioning for certified producers.
- Performance polyester blends:Moisture-wicking fabric technologies are expanding adoption in sports fan segments where functional properties command priority over cotton alternatives.
- Retro styling cycles:Hip-hop fashion crossover appeal is sustaining snapback cap volumes through cyclical aesthetic revivals that refresh demand across age demographics.
Market Restraints
- Acrylic and cotton input volatility:Petroleum-derived synthetic fiber costs fluctuate with crude oil benchmarks, compressing margin predictability for mid-tier manufacturers.
- Small-part regulations:The US Consumer Product Safety Commission constrains design options in children's headwear, limiting closure mechanism choices and decorative element applications.
- Licensed production concentration:Exclusive league agreements concentrate manufacturing among a narrow supplier base, raising barriers for new entrants seeking official merchandise authorization.
Strategic Opportunities
- Direct-to-consumer channels:Online retail platforms are capturing margin pools through reduced wholesale intermediation, enabling brands to own customer data and release cadence.
- Limited-edition collaborations:Sports wagering platforms and entertainment properties are creating co-branded headwear lines that monetize fan engagement beyond traditional stadium retail.
- EU Green Deal alignment:Circular textile initiatives and extended producer responsibility frameworks are creating first-mover advantage for suppliers with recycled material capabilities.
Industry Challenges
- Embroidery digitization talent:Technical proficiency in pattern grading and heat-transfer appliqué is scarce among domestic workforce pools, constraining design-to-sample velocity.
- Multi-jurisdiction certification timelines:Simultaneous compliance with REACH, CPSIA, and ISO 9001 quality standards extends product launch cycles and elevates administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mister Cap Market |
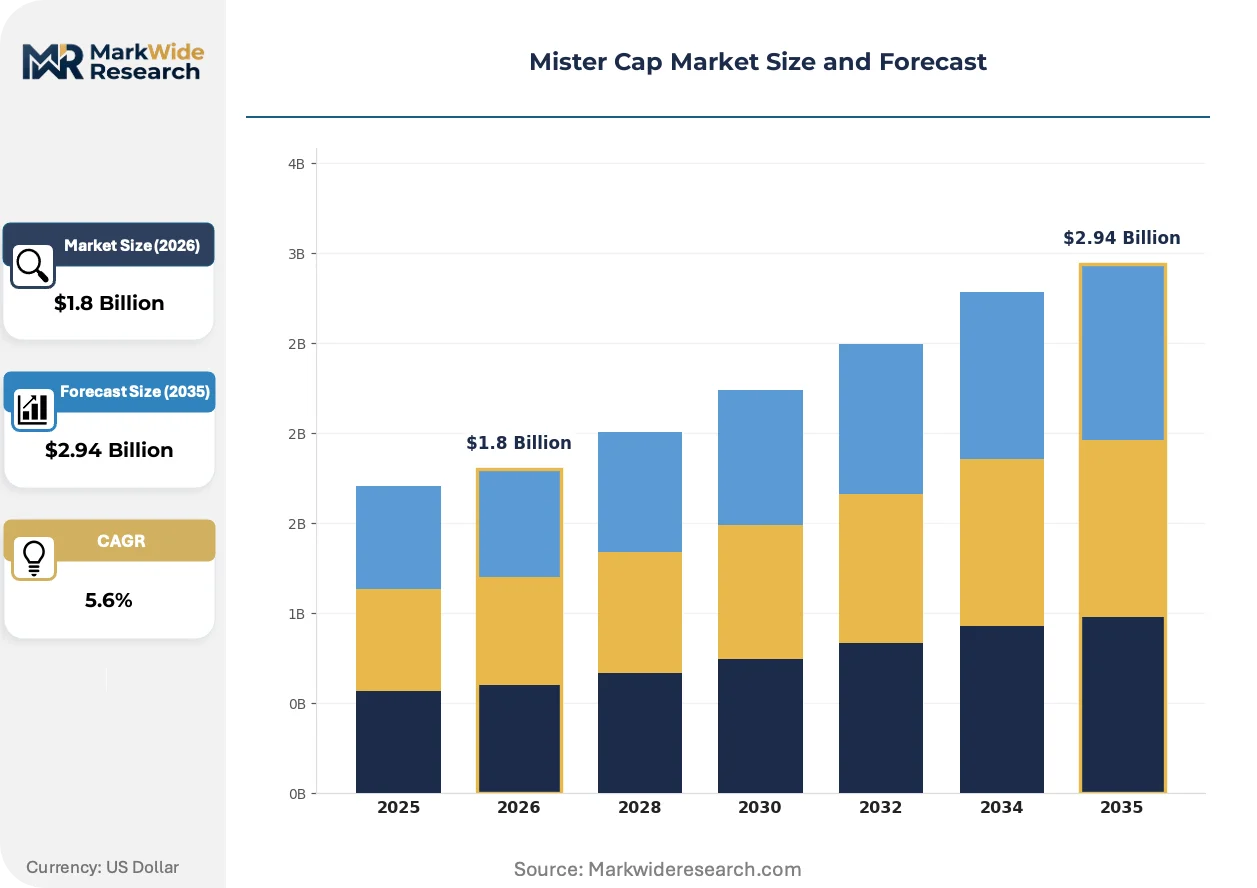
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snapback Caps, Beanies, Bucket Hats, Trucker Caps Material: Cotton, Polyester, Wool, Acrylic Target Audience: Sports Fans, Fashion Enthusiasts, Children, Professionals Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Pop-Up Shops |
| Companies Covered | Flutter Entertainment, Las Vegas Sands, Aristocrat Leisure, DraftKings, Evolution Gaming, Wynn Resorts, Light & Wonder, Caesars Entertainment, Mr Cooper Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mister Cap Market Shifts & Advancements
Digital design workflows and sustainable material substitutions are compressing development cycles while reshaping procurement criteria across licensed headwear categories.
3D embroidery digitization software is converging with automated stitching machinery to enable complex appliqué execution at reduced sampling cost. Stadium retail buyers and direct-to-consumer brands are adopting these tools to compress design-to-shelf timelines from weeks to days. This capability convergence is compressing competitive differentiation formerly held by established suppliers with legacy artisan networks.
REACH substance restrictions and evolving EU textile safety standards are tightening material specifications for imported caps, elevating testing costs for cotton and acrylic suppliers. Manufacturers serving European distribution channels must now document chemical compliance across full supply chains or risk customs detention. Children's headwear categories face the most stringent scrutiny, with small-part regulations forcing redesign of decorative elements and closure mechanisms.
Collector behavior around limited releases is shifting procurement priorities toward scarcity-driven release models and authenticated resale platforms. Specialty stores and brand-owned e-commerce channels are displacing traditional wholesale relationships for premium positioning. This pattern concentrates in the United States, where professional sports league licensing drives demand for authenticated, numbered editions with verified provenance.
Mister Cap Market Segmentation
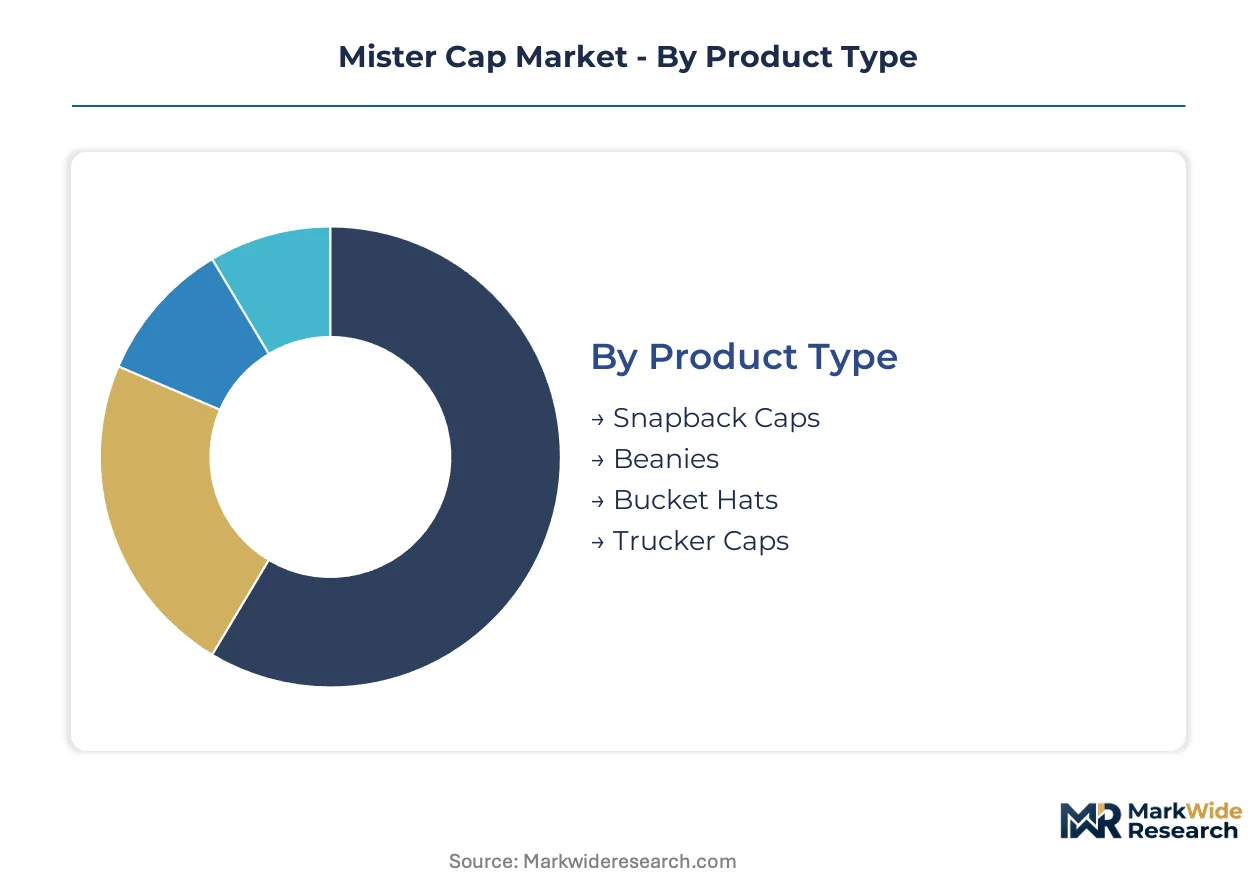
Segmentation in the mister cap market reveals how supply-side capabilities align with divergent demand profiles across styling preferences, material specifications, and channel economics. Understanding these fault lines enables manufacturers to prioritize capacity investments and licensing negotiations.
Product Type:
Manufacturing partnerships concentrate around closure mechanisms and crown structures that dictate equipment requirements and minimum order quantities.
- Snapback Caps:Structured six-panel construction with flat visor and adjustable plastic strap defines the silhouette. Demand clusters in the United States where professional sports league licensing drives premium volumes through retro styling cycles and hip-hop fashion crossover appeal.
- Beanies:Knitted skull-hugging design without visor or structure relies on gauge variation and fiber blend for differentiation. Cold-weather markets in northern Europe and Canada sustain baseline demand, though fashion-forward colorways are expanding adoption into transitional seasons.
- Bucket Hats:Soft cotton or nylon construction with downward-sloping brim offers sun protection and streetwear credibility. Festival culture and coastal tourism markets in Australia and Brazil favor this silhouette for its packability and UV coverage.
- Trucker Caps:Foam front panel with mesh rear construction originated in agricultural and logistics workwear. Rural United States and Australian outdoor retail channels maintain steady demand for high-visibility and custom-embroidery applications.
Today's leader: Snapback Caps. Tomorrow's challenger: Bucket Hats.
Material:
Raw material sourcing strategies diverge based on performance requirements, regulatory compliance burdens, and petroleum price exposure.
- Cotton:Natural fiber with breathability and print compatibility dominates casual and fashion-oriented segments. REACH compliance in Europe and evolving textile safety standards are elevating testing costs, compelling suppliers to document chemical compliance across full supply chains or risk customs detention.
- Polyester:Petroleum-derived synthetic with moisture-wicking and dimensional stability properties commands priority in sports fan segments. Performance-oriented buyers in the United States favor recycled PET variants that align with corporate sustainability commitments and stadium procurement criteria.
- Wool:Natural insulator with moisture-management and odor-resistance properties serves premium cold-weather and heritage positioning. Limited domestic scouring capacity in the United States constrains supply elasticity for fine-gauge applications.
- Acrylic:Synthetic alternative to wool offering colorfastness and lower cost in knitted constructions. Input volatility tied to crude oil benchmarks compresses margin predictability for mid-tier manufacturers serving price-sensitive wholesale channels.
Cotton and polyester split volume leadership; wool and acrylic occupy specialized niches where fiber properties justify premium positioning or cost discipline.
Target Audience:
End-use concentration shapes design constraints, regulatory exposure, and margin architecture across the customer base.
- Sports Fans:Licensed merchandise buyers seeking team affiliation through official headwear. The US Consumer Product Safety Commission small-part regulations constrain closure mechanism choices for youth sizing, while adult segments drive authenticated, numbered editions with verified provenance.
- Fashion Enthusiasts:Trend-responsive consumers prioritizing aesthetic novelty and limited-release scarcity. Direct-to-consumer channels and specialty stores capture margin pools through reduced wholesale intermediation and data-owned release cadence.
- Children:Age-restricted segment with stringent safety requirements governing decorative elements and closure mechanisms. Design options narrow as regulators enforce choke-hazard standards and chemical substance restrictions across multiple jurisdictions.
- Professionals:Corporate and uniform applications requiring consistent quality and bulk procurement terms. Embroidery digitization talent scarcity constrains design-to-sample velocity for logo-heavy orders with tight delivery windows.
Sports Fans anchor current volume; Fashion Enthusiasts are climbing the fastest as scarcity-driven release models reshape procurement priorities.
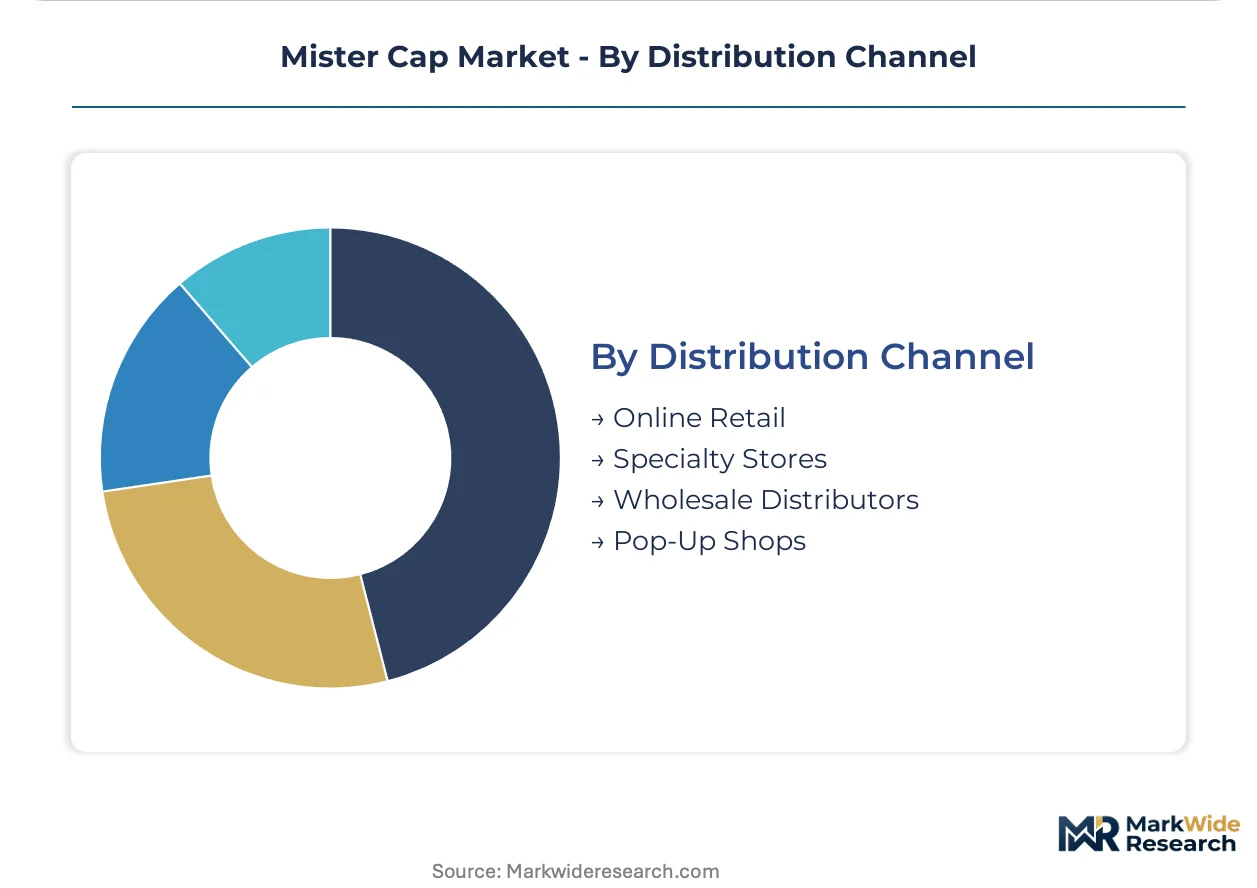
Distribution Channel:
Channel selection determines margin retention, customer data ownership, and speed-to-market capability for new releases.
- Online Retail:Direct brand relationships and reduced wholesale intermediation enable customer data ownership and release cadence control. E-commerce platforms concentrate margin pools while compressing geographic constraints on inventory placement.
- Specialty Stores:Curated physical environments sustain premium positioning for limited releases and authenticated resale platforms. Collector behavior concentrates in urban United States clusters with established streetwear retail infrastructure.
- Wholesale Distributors:Traditional intermediation model serving mass retail and regional sporting goods chains. Volume commitments and extended payment terms strain working capital for smaller manufacturers.
- Pop-Up Shops:Temporary retail activation tied to event schedules, album releases, or sports calendar moments. High fixed costs per square foot demand precise inventory forecasting and rapid sell-through execution.
Online Retail leads margin capture; Pop-Up Shops represent the most volatile expansion trajectory dependent on event density and location scouting expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan anchors global headwear manufacturing capacity, with licensed sports merchandise demand concentrating across three distinct consumption clusters. Professional sports league licensing and direct-to-consumer channel expansion are redirecting procurement priorities toward vertically integrated suppliers.
United States
Professional sports league licensing drives premium snapback and fitted cap volumes through retro styling cycles and hip-hop fashion crossover appeal. The US Consumer Product Safety Commission governs small-part regulations for children's headwear, constraining closure mechanism choices. Los Angeles and New York City sustain specialty retail infrastructure for authenticated, numbered editions with verified provenance.
Germany
Performance polyester blends command priority in Bundesliga fan segments where moisture-wicking properties justify premium positioning over cotton alternatives. REACH compliance mandates elevate material traceability standards, compelling suppliers to document chemical compliance across full supply chains. Bavaria's textile engineering clusters are upgrading testing protocols to capture first-mover advantage in certified production.
China
Dongguan and Shenzhen manufacturing zones supply global volume through pattern grading and embroidery digitization capabilities. GB standards and evolving textile safety requirements govern export-oriented production. Yangtze River Delta suppliers are integrating automated stitching machinery to compress design-to-sample timelines from weeks to days.
Japan
Fashion-forward colorways in knitted constructions are expanding beanie adoption into transitional seasons beyond cold-weather baseline demand. METI oversight of industrial standards intersects with JIS textile specifications for imported headwear. Osaka-based specialty retailers sustain premium positioning for limited releases and authenticated resale platforms.
United Kingdom
Premier League licensing and music festival culture sustain demand for bucket hats and trucker caps across urban consumer segments. The UK's departure from EU regulatory alignment creates parallel compliance obligations for REACH-equivalent substance restrictions. London's streetwear retail infrastructure concentrates collector behavior around scarcity-driven release models.
Mister Cap Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers retrofit facilities for REACH compliance and automated embroidery digitization. The vendor base concentrates around three tiers: vertically integrated manufacturers owning full supply chains, specialist licensors holding exclusive league agreements, and digital-native brands leveraging direct-to-consumer channel economics. Two strategic archetypes anchor competitive positioning: sports wagering platforms cross-promoting branded caps through fan engagement ecosystems, and hospitality operators anchoring merchandising strategy with exclusive entertainment property lines. M&A activity and strategic partnerships are redirecting volume toward suppliers capable of meeting exclusivity and speed-to-market requirements.
Among wagering and entertainment platform operators, Flutter Entertainment plc, DraftKings Inc., and Caesars Entertainment, Inc. occupy positions that exemplify divergent channel strategies. Flutter Entertainment represents the archetype of digital ecosystem integration, where fan engagement platforms create cross-promotional velocity for licensed merchandise. DraftKings Inc. sits within the limited-edition collaboration tier, where sports league partnerships drive direct-to-consumer velocity through scarcity-driven release cadence. Caesars Entertainment, Inc. anchors the hospitality-anchored merchandising vector, where exclusive headwear lines tied to entertainment properties capture tourist expenditure. Each structure illustrates how licensing concentration restructures manufacturing partnerships and redirects volume toward suppliers meeting exclusivity requirements.
| Leading Market Players |
|---|
| Flutter Entertainment |
| Las Vegas Sands |
| Aristocrat Leisure |
| DraftKings |
| Evolution Gaming |
| Wynn Resorts |
| Light & Wonder |
| Caesars Entertainment |
| Mr Cooper Group |
| Others |
Supply & Pricing Matrix
Embroidery digitization talent scarcity in Dongguan and Shenzhen manufacturing zones widens pricing-tier spreads, as labor-cost differentials between automated stitching facilities and artisan-dependent suppliers stratify premium from economy positioning. REACH compliance testing and CPSIA certification burdens compound input-cost pass-through, forcing mid-tier manufacturers to absorb margin compression or cede volume to vertically integrated competitors.
Pricing Analysis
Input-cost pass-through from petroleum-derived acrylic fiber volatility and cotton supply-chain documentation requirements shapes a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade (REACH/CPSIA compliance) and volume scale, with licensed sports merchandise commanding brand premiums. Cost compression in standard tiers is intensifying because mid-tier manufacturers face dual pressure from crude oil benchmarks and elevated testing overhead. Children's headwear buyers exhibit highest price sensitivity due to regulatory-constrained design options, while authenticated limited-edition collectors show least sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Dongguan-centered embroidery digitization capacity and concentrated licensed sports league manufacturing partnerships. Supply draws from China, Vietnam, and Bangladesh for cut-and-sew assembly, with raw material dependencies spanning cotton from India, petroleum-based synthetics from South Korea, and wool from Australia. Tariff exposure on Chinese-origin finished goods threatens margin stability for US-bound volumes. Distribution runs through direct-to-consumer platforms and specialty retail channels that displace traditional wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on automation-driven cost-down trajectories in embroidery digitization and heat-transfer appliqué, alongside premium-tier shifts toward authenticated limited releases with verified provenance.
For Market Incumbents: To counter new entrant encroachment via digital-native direct-to-consumer channels, incumbents should deepen backward integration into automated stitching machinery ownership and secure exclusive league licensing renewals that block competitor access. Certification investment in REACH and CPSIA compliance creates switching costs for stadium retail buyers. For New Entrants and Emerging Players: Enter via underserved bucket hat demand in Australian and Brazilian festival tourism markets, where coastal UV protection needs and packability requirements outstrip current specialty store coverage. White-space exists in recycled PET performance polyester for Bundesliga fan segments. A sustainability-first go-to-market angle captures EU Green Deal-aligned procurement criteria. For Investors and Strategic Acquirers: Sports wagering platforms are the most active acquirer in this space, seeking fan engagement ecosystem extensions through licensed headwear monetization. Long-term viability over the coming decade rests on circular textile capabilities and extended producer responsibility compliance. Acquisition target archetype: vertically integrated suppliers with automated digitization and certified European distribution channels. Watch for REACH substance restriction expansions as inflection indicator for testing-cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Investment in Embroidery Digitization | Dongguan suppliers compress design-to-sample timelines from weeks to days, eroding artisan-network differentiation. |
| REACH Compliance Certification Program | European customs detention risk elevates certified producers to premium positioning in stadium retail procurement. |
| Direct-to-Consumer Channel Launch | Brand-owned e-commerce captures customer data and release cadence control from wholesale distributors. |
| Licensed Sports League Partnership | Exclusive manufacturing agreements with NFL, NBA, or MLB redirect volume toward vertically integrated suppliers. |
| Recycled Material Capability Buildout | rPET performance blends align with Bundesliga fan segment sustainability commitments and stadium procurement criteria. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with headwear manufacturing executives, sports league licensing directors, stadium retail procurement managers, and embroidery digitization specialists with secondary validation. Sources included customs and trade data, SEC filings from wagering and hospitality operators, professional sports league merchandise reports, and textile safety regulatory databases. Bottom-up demand modeling and top-down supply triangulation cross-checked volume estimates.
Segment-weighting across product type, material specification, target audience, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from historical volume trajectories, licensing agreement renewal patterns, and channel-shift elasticity parameters. Forecast inputs incorporated polyester blend adoption curves in sports fan segments and REACH compliance cost pass-through assumptions.
Inputs from manufacturing executives and licensing directors were available through the study window; gaps in real-time inventory positioning data from direct-to-consumer platforms introduce uncertainty bands around channel-share projections. Forecasts reflect documented assumptions regarding automation adoption rates and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Fitness Apparel Market
Apparel & Footwear
Apparel Dry Wash Spray Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Platform Shoes Market
Apparel & Footwear
Outdoor Apparel and Accessories Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
North America Denim Jeans Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Bra Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Loungewear Market
Apparel & Footwear
Outdoor Apparel Market
Apparel & Footwear
Asia-Pacific Denim Jeans Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Headwear Market