
 Fitness Apparel Market | 2026-2036
Fitness Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Fitness Apparel Market Analysis
Asset-light licensing and third-party manufacturing partnerships is tilting competitive dynamics toward brands with superior design control rather than capital-intensive vertical infrastructure. Nike leverages its global supplier network to sustain rapid SKU turnover across seasonal collections. Under Armour anchors its position through R&D intensity in compression fabrics and body-mapping technologies. Lululemon Athletica differentiates via community-driven retail and premium positioning in the women's performance segment.
Fitness apparel encompasses engineered garments designed for physical exertion, typically constructed from moisture-wicking synthetic blends such as polyester-spandex interlocks with four-way stretch and breathability ratings exceeding standard casual wear, serving to regulate thermoregulation and reduce friction during repetitive movement. The product type dimension shows leggings and sports bras commanding the largest volume pools as athleisure permeates daily wardrobes, while jackets capture higher per-unit margins through technical weatherproofing layers. Customer type segmentation reveals gym enthusiasts and casual wearers merging into a single mass-market bloc, whereas professional athletes and trainers sustain niche premium tiers through performance certification requirements.
The EU's ECHA enforces REACH compliance on chemical inputs in textile dyes and finishing agents, while the US FTC monitors green marketing claims under its Guides for the Use of Environmental Marketing Claims, collectively elevating compliance costs for cross-border sellers. China's SAMR implements GB standards for textile labeling and fiber content disclosure, shaping export readiness for manufacturers supplying international distributors. Stakeholders must monitor how evolving extended producer responsibility frameworks in Europe and North America will reshape cost allocation across material recovery and recycling infrastructure investments.
Market Dynamics
EU Green Deal textile sustainability mandates are forcing brands to re-engineer supply chains around recycled synthetic fibers and closed-loop manufacturing systems, compressing margins for laggards while rewarding early adopters with regulatory preferential access.
Growth Catalysts
- REACH chemical compliance:ECHA enforcement on textile dyes and finishing agents is accelerating substitution toward bio-based alternatives, creating first-mover advantage for compliant suppliers in EU export channels.
- Boutique fitness studio expansion:Specialized training facilities in North America and Western Europe are expanding dedicated apparel procurement budgets beyond generic athletic wear toward performance-certified garments.
- Recycled polyester scaling:Mechanical and chemical recycling infrastructure investments in Southeast Asia are lowering input costs for rPET fiber, enabling mass-market price parity with virgin synthetics.
Market Restraints
- Petroleum-based input volatility:Crude oil price swings directly compress margins on virgin polyester-spandex blends, forcing hedging costs onto mid-tier manufacturers without captive chemical supply.
- Chinese production concentration:Anta Sports and Li Ning's domestic scaling has concentrated technical knitwear capacity in Fujian and Guangdong provinces, creating geographic supply risk for non-Chinese brands.
- Technical breathability ceilings:Current moisture-wicking synthetic interlocks face thermoregulation limits in extreme humidity conditions, constraining expansion into tropical outdoor performance segments.
Strategic Opportunities
- Extended producer responsibility frameworks:EU and North American material recovery mandates are creating closed-loop service revenue streams for brands investing in take-back infrastructure and fiber-to-fiber recycling partnerships.
- India domestic market penetration:Underpenetrated organized retail channels in tier-2 and tier-3 Indian cities offer volume expansion for brands adapting sizing and pricing to local body-type demographics and purchasing power.
- Biometric sensor integration:Convergence of conductive yarn technology with compression fabric body-mapping is enabling real-time muscle-activation monitoring for professional training segments.
Industry Challenges
- GB standards compliance timeline:China's SAMR textile labeling and fiber content disclosure requirements impose documentation burdens on export-ready manufacturers, extending product launch cycles by 8-12 weeks for cross-border sellers.
- Technical talent scarcity:Specialized knitwear engineers with expertise in four-way stretch construction and seam-free welding are concentrated in Dongguan and Taipei, creating recruitment bottlenecks for brands establishing captive R&D.
- Multi-jurisdiction greenwashing exposure:US FTC Guides for environmental marketing claims and EU consumer protection authorities are escalating enforcement against unsubstantiated sustainability claims, requiring legal review of all packaging and digital assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fitness Apparel Market |
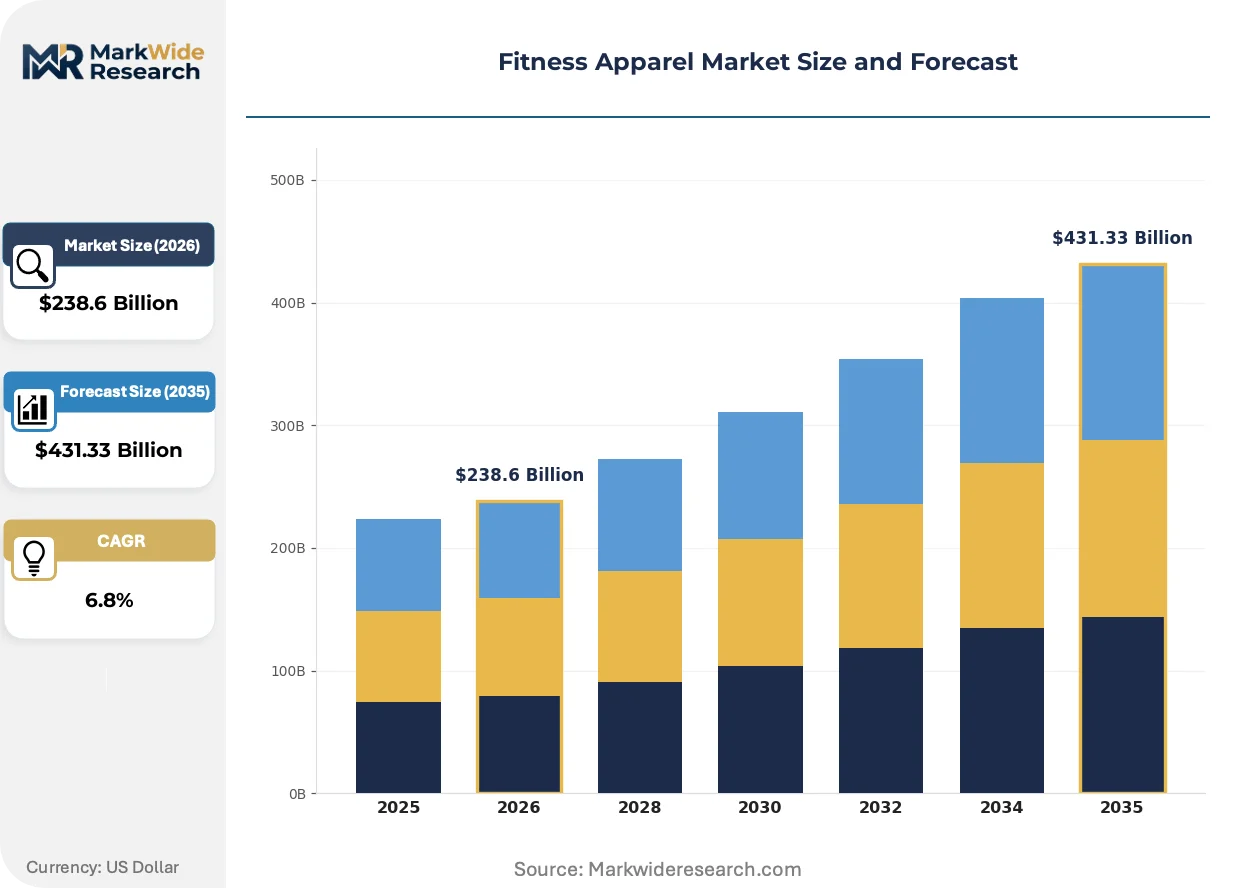
| Market Size in 2026 | $238.6 Billion |
| Market Size in 2035 | $431.33 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leggings, Sports Bras, T-Shirts, Jackets Customer Type: Gym Enthusiasts, Casual Wearers, Professional Athletes, Trainers Material: Nylon, Polyester, Spandex, Cotton Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Under Armour, Columbia Sportswear Company, Nike, Li Ning, Anta Sports, Adidas, PUMA, Asics, Lululemon Athletica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fitness Apparel Market Emerging Trajectories
Active material science breakthroughs and regulatory pressure on chemical inputs are compressing product development cycles while fragmenting competitive advantage across specialized technical competencies rather than scale economies alone.
Seamless knitting technology is migrating from high-end compression wear into mid-market leggings and sports bras, enabling single-piece construction that eliminates chafe points and reduces labor assembly costs. Marathon runners and CrossFit practitioners are adopting seamless base layers at accelerating rates, with specialty retailers reporting category share gains against traditional cut-and-sew alternatives. The technology is migrating from premium positioning toward mass-market accessibility, compressing differentiation windows for incumbent brands dependent on conventional manufacturing.
EU Green Deal textile sustainability requirements are mandating recycled content minimums and carbon footprint disclosure across the apparel value chain, with ECHA enforcement mechanisms tightening through 2025-2030 implementation windows. Brands sourcing from non-compliant suppliers face exclusion from EU distribution channels, with penalties cascading through wholesale and direct-to-consumer operations. Technical outerwear and weatherproofed jackets face the steepest compliance burdens due to multi-layer synthetic construction and PFC-based water-repellent finishes.
Gym enthusiasts and casual wearers are collapsing into a single mass-market bloc, eroding historical segmentation between performance-certified and lifestyle-oriented product lines. Specialty sporting goods retailers are responding with unified floor sets that merchandise technical and athleisure inventory together, while pure-play digital natives are launching subscription replenishment models for core basics. This behavioral convergence is most visible in China and South Korea, where social fitness culture has normalized gym-to-street wardrobe continuity.
Fitness Apparel Market Segmentation
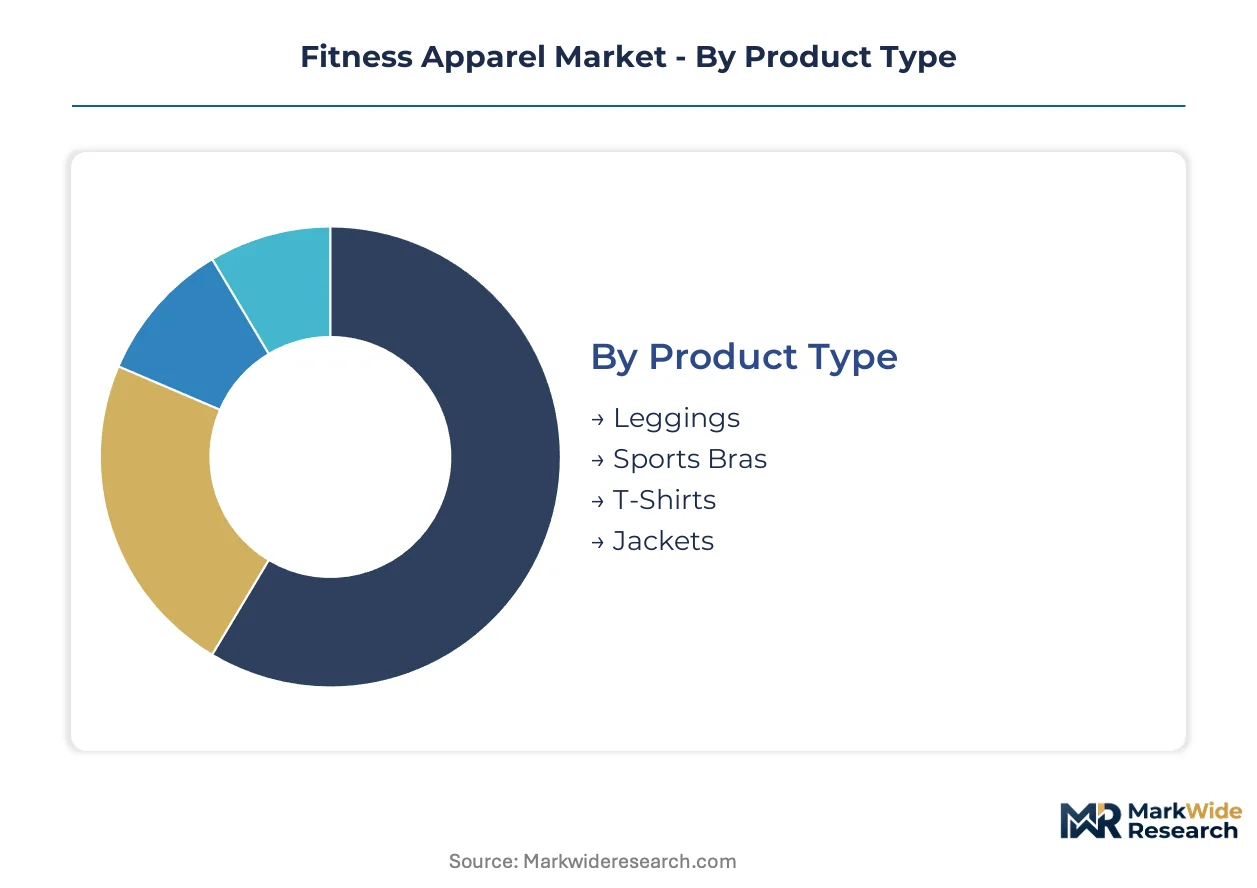
Fitness apparel segmentation reveals how technical specifications, price positioning, and end-use intensity create distinct procurement patterns across channels. Manufacturers calibrate fiber blends and construction methods differently for boutique studio buyers versus mass-market distributors.
Product Type:
After-sales service intensity varies sharply by garment complexity, with technical outerwear requiring repair networks and warranty fulfillment that basic leggings rarely need.
- Leggings:Four-way stretch polyester-spandex interlocks with moisture-wicking ratings above standard casual wear dominate construction. Demand concentrates in China and South Korea where gym-to-street wardrobe continuity has normalized daily athleisure use.
- Sports Bras:Compression-molded cups with seamless knitting and adjustable support zones address high-impact movement requirements. Boutique fitness studios in North America and Western Europe are expanding dedicated procurement budgets toward performance-certified garments with moisture management certification.
- T-Shirts:Lightweight polyester blends with anti-odor treatments serve as entry-level volume drivers for mass-market replenishment cycles.
- Jackets:Multi-layer synthetic construction with PFC-based water-repellent finishes commands technical weatherproofing margins.
Leggings hold the largest share; momentum sits with sports bras as boutique studio procurement accelerates.
Customer Type:
Cost tier differentiation separates brands pursuing professional certification requirements from those serving undifferentiated casual demand.
- Gym Enthusiasts:Performance-certified garments with body-mapping compression and thermoregulation specifications dominate purchasing criteria. This segment merges functionally with casual wearers in China and South Korea where social fitness culture has normalized technical apparel for daily use.
- Casual Wearers:Aesthetic-focused athleisure with minimal performance certification drives volume through unified floor sets at specialty sporting goods retailers. The behavioral convergence with gym enthusiasts has eroded historical product line separation.
- Professional Athletes:Custom-fitted compression systems with biometric sensor integration potential command premium positioning through R&D-intensive suppliers.
- Trainers:Durability-focused basics with rapid replenishment cycles sustain niche premium tiers through institutional procurement channels.
Gym enthusiasts and casual wearers collectively dominate volume; professional athletes command the steepest expansion trajectory in per-unit value terms.
Material:
Application requirements dictate fiber selection, with thermoregulation and stretch recovery specifications varying by end-use intensity.
- Polyester:Virgin and recycled PET fibers with mechanical and chemical recycling infrastructure investments in Southeast Asia enabling mass-market price parity. EU Green Deal mandates are accelerating substitution toward rPET inputs for EU export channel access.
- Spandex:Elastane content percentages determine compression gradation and shape retention over wash cycles, critical for high-repeat-use garments.
- Nylon:Abrasion-resistant filament yarns serve technical outerwear and high-durability training applications.
- Cotton:Natural fiber blends retain presence in low-sweat lifestyle positioning despite moisture-wicking performance limitations.
Polyester holds the largest share; recycled polyester variants are gaining share fastest as regulatory compliance tightens.
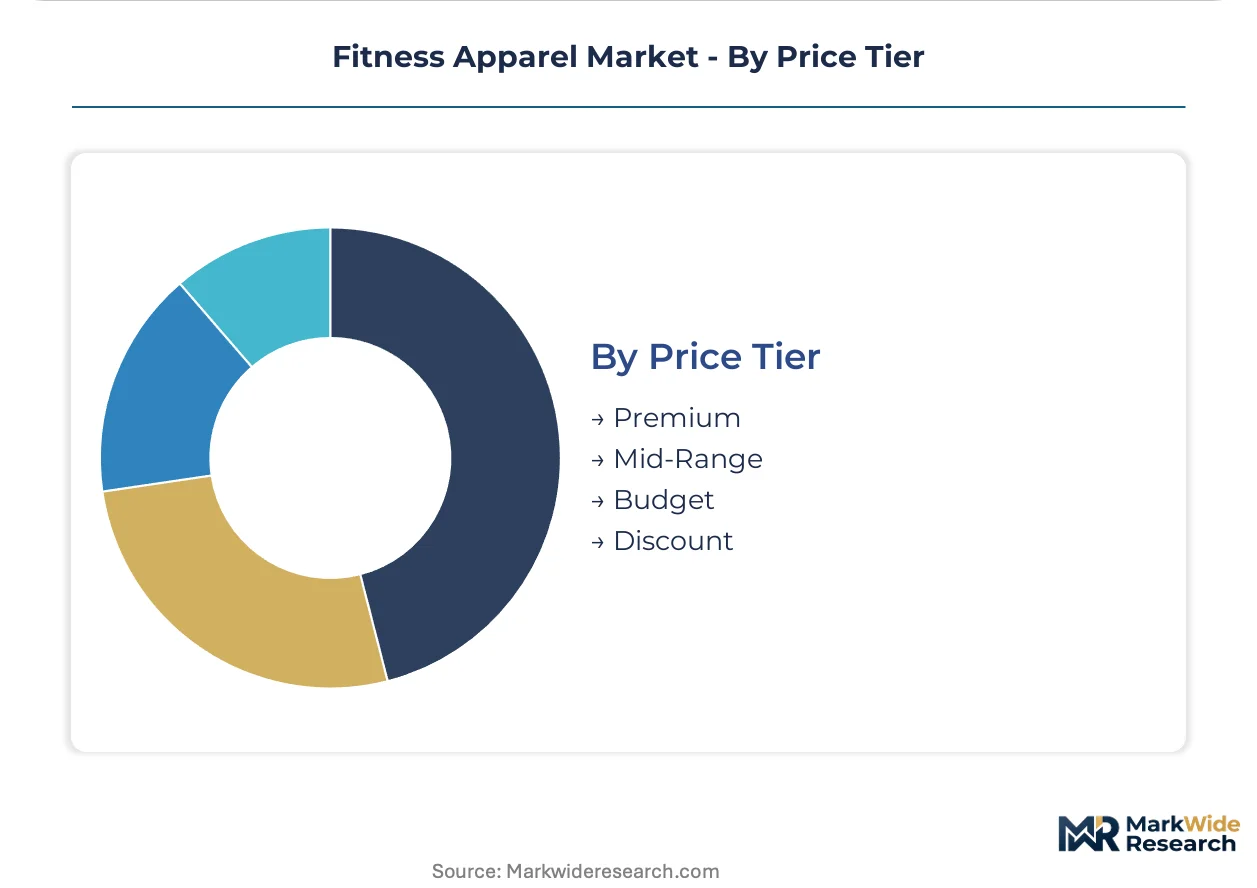
Price Tier:
Margin structure stratifies across certification depth, fiber origin, and manufacturing geography rather than brand premium alone.
- Premium:Seamless knitting construction with closed-loop manufacturing verification and extended producer responsibility compliance. Brands investing in take-back infrastructure capture regulatory preferential access in EU distribution channels.
- Mid-Range:Conventional cut-and-sew assembly with partial recycled content meeting baseline ECHA REACH requirements without full carbon footprint disclosure.
- Budget:Virgin polyester-spandex blends from concentrated Fujian and Guangdong production clusters serve price-sensitive mass-market distributors.
- Discount:Unbranded basic construction with minimal compliance documentation faces exclusion risk from regulated export channels.
Premium and budget tiers anchor opposite ends of the value chain; mid-range positioning faces the fastest margin compression as compliance costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal textile sustainability mandates are redirecting procurement flows toward compliant supply zones, while boutique fitness studio expansion in North America and Western Europe accelerates demand for performance-certified garments. China's SAMR labeling requirements and domestic brand scaling are reshaping export readiness criteria across Asian manufacturing clusters.
United States
Boutique fitness studios in New York and Los Angeles are expanding dedicated apparel procurement budgets beyond generic athletic wear. US FTC enforcement under Guides for the Use of Environmental Marketing Claims is escalating scrutiny of greenwashing claims, requiring legal review of packaging assets. Technical knitwear engineering talent concentrates in Portland and Boston, supporting R&D-intensive compression fabric development.
Germany
ECHA REACH compliance on textile dyes and finishing agents is accelerating substitution toward bio-based alternatives for EU export channel access. The EU Green Deal's extended producer responsibility frameworks are creating closed-loop service revenue opportunities for brands investing in take-back infrastructure. Munich and Hamburg host specialized distributors serving boutique studio procurement channels across German-speaking Europe.
China
Anta Sports and Li Ning are scaling domestic production while capturing share in Southeast Asian export markets, concentrating technical knitwear capacity in Fujian and Guangdong provinces. SAMR GB standards for textile labeling and fiber content disclosure shape export readiness timelines for cross-border sellers. Dongguan maintains critical mass in four-way stretch construction and seam-free welding expertise.
India
Underpenetrated organized retail channels in tier-2 and tier-3 cities offer volume expansion for brands adapting sizing to local body-type demographics. BIS textile standards and DGFT export documentation requirements impose compliance burdens on manufacturers supplying international distributors. Tiruppur and Surat industrial clusters are scaling recycled polyester processing capacity for EU-bound shipments.
South Korea
Social fitness culture has normalized gym-to-street wardrobe continuity, collapsing historical segmentation between performance-certified and lifestyle-oriented product lines. MFDS textile safety standards and consumer protection enforcement shape quality benchmarks for domestic distribution. Seoul-based digital natives are launching subscription replenishment models for core athleisure basics.
Fitness Apparel Market Vendor Landscape
On the supply side, the industry is consolidating around asset-light licensing models that tilt competitive dynamics toward brands with superior design control rather than capital-intensive vertical infrastructure. Three strategic archetypes dominate: global sportswear houses with rapid SKU turnover capabilities, premium specialists anchored in community-driven retail, and domestic champions scaling regional export share. Dominant competitive moves include strategic partnerships with third-party manufacturers and portfolio diversification into closed-loop service revenue streams.
Within the premium specialist tier, Lululemon Athletica occupies a position exemplifying community-driven retail and women's performance segment focus. Among China-based domestic champions, Anta Sports and Li Ning represent the scaling archetype capturing Southeast Asian export share while concentrating technical production in Fujian and Guangdong. These three companies illustrate how design control, regional manufacturing concentration, and regulatory compliance investments are separating competitive outcomes across the value chain.
| Leading Market Players |
|---|
| Under Armour |
| Columbia Sportswear Company |
| Nike |
| Li Ning |
| Anta Sports |
| Adidas |
| PUMA |
| Asics |
| Lululemon Athletica |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor's freight volatility compresses margins on virgin polyester-spandex blends while amplifying price spreads between EU-compliant recycled fiber garments and conventional alternatives. This logistics chokepoint feeds directly into how brands calibrate procurement across Fujian production clusters and Southeast Asian recycling infrastructure.
Pricing Analysis
Certification level creates the primary spread across the fitness apparel landscape, with ECHA REACH-compliant garments commanding substantial premiums over baseline alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by fiber origin and carbon disclosure depth, with mid-range positioning experiencing the fastest margin compression as compliance costs escalate. Price erosion runs through budget tiers where virgin petroleum-based inputs face crude oil volatility without hedging capacity. Boutique fitness studios in North America and Western Europe demonstrate the lowest price sensitivity, while mass-market distributors in emerging channels exhibit acute responsiveness to unit cost fluctuations.
Supply Chain Analysis
Petroleum derivative feedstocks from integrated chemical complexes in China, South Korea, and Saudi Arabia supply the virgin polyester and elastane inputs that dominate mass-market construction. rPET fiber draws from mechanical and chemical recycling infrastructure scaling across Vietnam, Indonesia, and Thailand, with capacity expansion lowering input costs toward virgin parity. Single-source vulnerability concentrates in Dongguan and Taipei, where specialized knitwear engineers with four-way stretch expertise create recruitment bottlenecks for brands establishing captive R&D. Distribution runs through hybrid direct-to-consumer platforms and unified floor sets at specialty sporting goods retailers, with subscription replenishment models gaining share in digitally native channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fitness apparel is approaching a platform-economics inflection where biometric sensor integration and closed-loop service infrastructure create interoperability lock-in between garment ecosystems and training software platforms.
For Market Incumbents: Build regulatory compliance moats through preemptive investment in ECHA REACH-certified dye substitution and EU extended producer responsibility infrastructure. Secure captive supply of rPET fiber through backward integration into Southeast Asian recycling partnerships before mass-market price parity erodes differentiation. Defend against digital-native subscription entrants by anchoring community-driven retail with seamless knitting technology migration into mid-market lines.
For New Entrants and Emerging Players: Pursue white-space expansion in tier-2 and tier-3 Indian cities where organized retail penetration remains underdeveloped and local body-type demographics favor adapted sizing strategies. Target professional athlete segments with biometric sensor-integrated compression systems, leveraging conductive yarn partnerships to bypass incumbent R&D scale advantages. Launch through studio-direct procurement channels rather than conventional wholesale to capture boutique fitness budget expansion.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate apparel portfolios seeking to divest non-core athletic wear divisions amid sustainability compliance cost escalation. Long-term viability hinges on fiber-to-fiber recycling infrastructure ownership and take-back program scale rather than brand equity alone. Monitor ECHA enforcement intensity as the critical inflection signal distinguishing regulatory preferential access from channel exclusion risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Manufacturing Transition | ECHA REACH compliance secures EU distribution channel access against exclusion risk. |
| Biometric Sensor Integration | Conductive yarn convergence enables real-time muscle-activation monitoring for professional training segments. |
| Southeast Asian Recycling Partnership | rPET infrastructure investments lower input costs toward mass-market virgin polyester parity. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models capture behavioral convergence between gym enthusiasts and casual wearers. |
| India Market Footprint Expansion | Tier-2 and tier-3 city penetration adapts sizing to local demographics and purchasing power. |
Methodological Framework
Operator-level perspectives from brand supply chain directors, boutique studio procurement managers, technical knitwear engineers, and recycled fiber facility operators anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against customs trade records, ECHA substance restriction databases, and SEC apparel sector filings. Bottom-up demand modeling across product type, customer segment, material composition, and price tier dimensions triangulated against top-down market sizing from production capacity assessments and distributor channel audits.
Scenario-bracketing around regulatory implementation timelines and petroleum price volatility bands shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type intensity, customer use-case certification requirements, fiber origin and recycled content thresholds, and regional regulatory cluster compliance depth. CAGRs derived from elasticity-adjusted volume projections incorporating substitution effects between virgin and recycled synthetic inputs, with boutique fitness studio expansion rates and ECHA enforcement intensity as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, EU carbon border adjustment implementation pace, or Chinese domestic consumption recovery would shift the trajectory materially. Cross-checking against IEA energy price benchmarks and EU trade flow statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Shapewear Market
Apparel & Footwear
Plus Size Clothing Market
Apparel & Footwear
Asia Pacific Swimwear Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
North America Jeans Market
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Europe Headwear Market
Apparel & Footwear
Thimbles Market
Apparel & Footwear
Outdoor Apparel Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
Polo Shirt Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Smart Heating Scarf Market