
 Stream Hosting Market | 2026-2036
Stream Hosting Market Size, Share, and Industry Trends Forecast 2026-2036
Stream Hosting Market Analytics
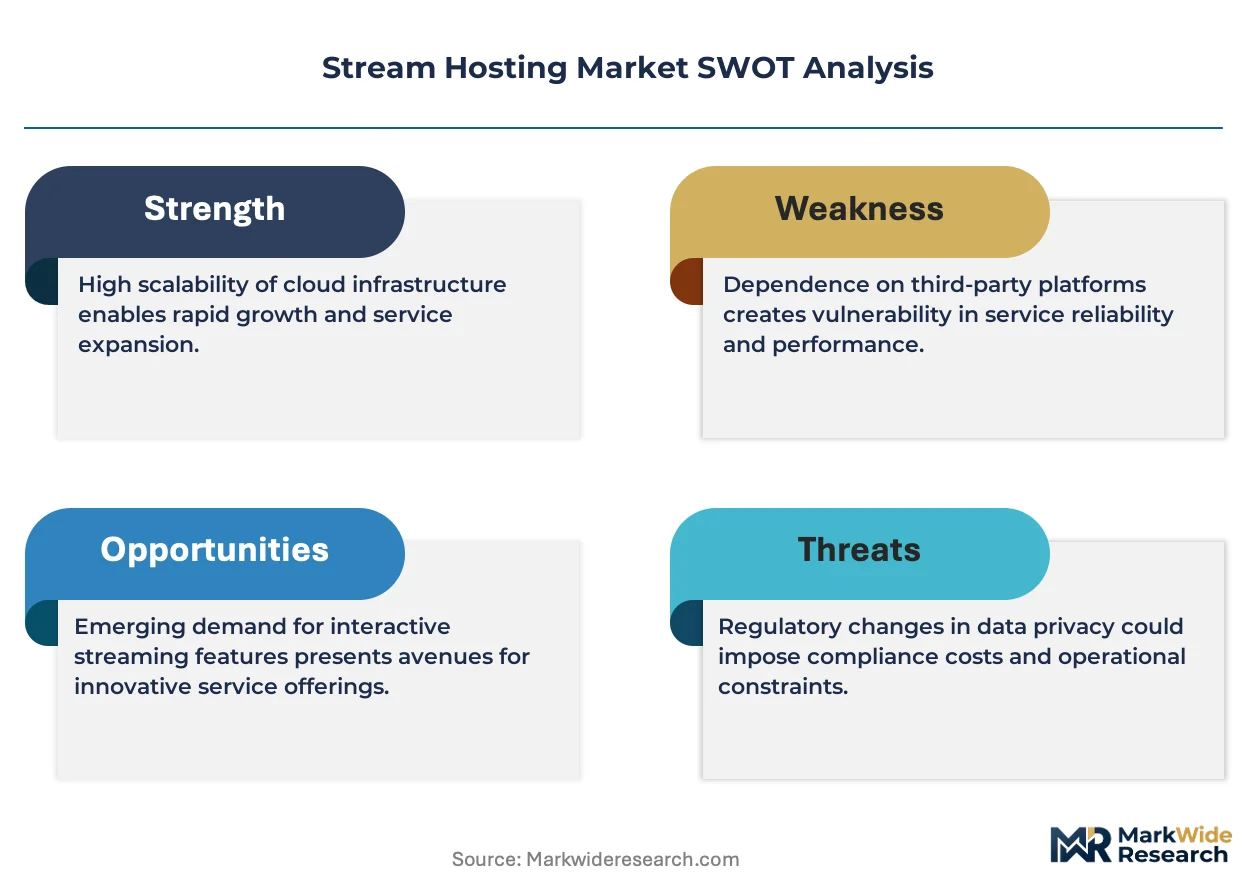
The EU AI Act is repositioning how stream hosting providers architect content moderation pipelines across European deployments. Amazon Web Services leverages its global edge network to sustain low-latency delivery for live events at scale. Brightcove anchors its competitive stance through specialized monetization tooling for media publishers. Wowza Media Systems differentiates via deep protocol flexibility spanning RTMP through WebRTC.
Stream hosting encompasses cloud-based infrastructure for ingest, transcoding, storage, and distribution of live and on-demand video streams, typically operating across redundant data centers with sub-100ms edge caching. The technology serves broadcasters, enterprises, and platform operators requiring elastic capacity during audience spikes without capital-intensive hardware ownership. Live Streaming commands the largest revenue share among service types due to sports and event broadcasting migration off satellite distribution. Video on Demand exhibits the fastest expansion as subscription platforms invest in personalized recommendation engines and multi-CDN failover. Ad-Supported pricing models attract the highest volume of new content creators entering the market with minimal upfront commitment.
FCC net neutrality rulings in the United States, GDPR data localization mandates from European regulators, and Japan's METI cloud security guidelines collectively shape where providers must locate transcoding nodes and store viewer analytics. ISO 27001 and SOC 2 Type II certifications have become baseline requirements for enterprise procurement committees evaluating vendor shortlists. Stakeholders must monitor how emerging sovereign cloud requirements in Germany, France, and India fragment previously centralized infrastructure strategies.
Market Dynamics
Cloud-native transcoding clusters are displacing satellite distribution for live sports broadcasting, forcing infrastructure providers to rearchitect edge node placement around sub-100ms latency requirements rather than centralized data center economics.
Growth Catalysts
- EU AI Act compliance mandates:Content moderation pipeline investments across European deployments are accelerating procurement cycles for AI-enabled stream hosting infrastructure.
- Enterprise video communications:North American and European corporations are migrating internal broadcast workflows off legacy hardware to elastic cloud platforms.
- WebRTC protocol adoption:Browser-native streaming is reducing plugin dependencies and expanding addressable device pools for interactive live applications.
Market Restraints
- Energy cost volatility:Transcoding node electricity consumption in Germany and France is compressing gross margins during peak demand periods.
- Supply concentration in hyperscaler silicon:GPU accelerator availability depends on Taiwan and South Korea foundry capacity, creating allocation risk.
- GDPR data localization:Viewer analytics storage requirements fragment previously centralized infrastructure strategies across multiple sovereign jurisdictions.
Strategic Opportunities
- India's sovereign cloud requirements:Localized transcoding node mandates are opening dedicated infrastructure deployment opportunities for compliant providers.
- Ad-supported tier expansion:Minimal upfront commitment models are attracting independent content creators previously excluded from subscription platforms.
- AI-driven personalization convergence:Recommendation engine integration with delivery infrastructure is creating new monetization layers for video on demand services.
Industry Challenges
- Real-time encoding specialist scarcity:FFmpeg and hardware-accelerated codec engineering talent commands premium compensation, constraining R&D velocity.
- SOC 2 Type II certification timelines:Enterprise procurement committees require 12-18 month audit completion before vendor shortlist inclusion.
- Multi-CDN failover integration:Legacy broadcast workflow migration demands complex orchestration layer development across incompatible vendor APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stream Hosting Market |
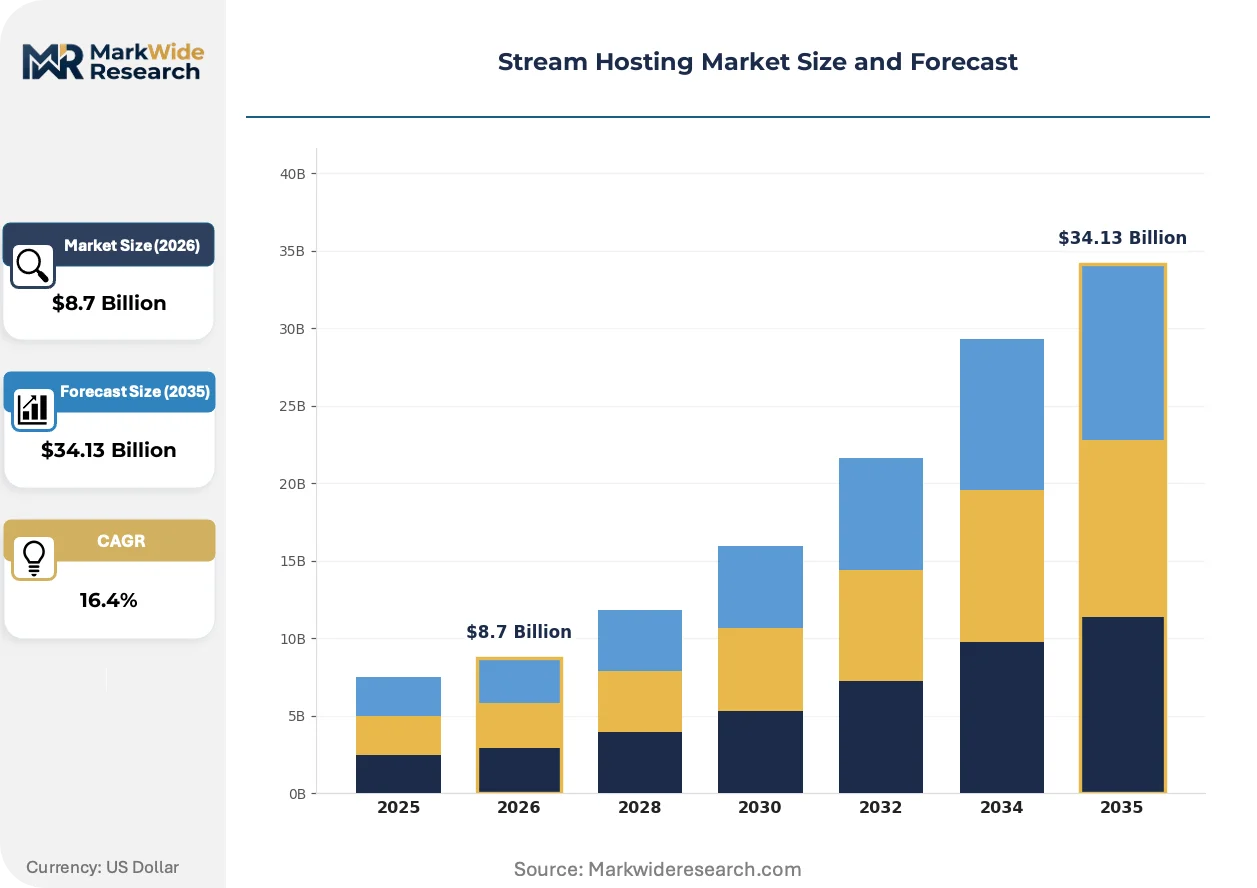
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Live Streaming, Video on Demand, Cloud Storage, CDN Technology: RTMP, HTML5, HLS, WebRTC End User: Content Creators, Enterprises, Media Companies, Educators Pricing Model: Subscription-Based, Pay-Per-View, Freemium, Ad-Supported |
| Companies Covered | Amazon Web Services, Brightcove, Vimeo, IBM Video Streaming, Kaltura, Wowza Media Systems, Dacast, AKAMAI Technologies, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stream Hosting Market Evolving Landscape
Protocol flexibility and edge computing density are redefining competitive differentiation in stream hosting, with providers racing to collapse latency while expanding monetization tooling.
AV1 codec deployment is overtaking H.264 for premium tier distribution, slashing bitrate requirements by thirty percent without perceptual quality degradation. Sports broadcasters in the United States and Japan are piloting AV1 for 4K live events to reduce egress costs. This compression efficiency is overtaking bandwidth-provisioned pricing models that previously dominated enterprise procurement negotiations.
The EU AI Act's content moderation requirements are mandating automated classification pipelines for live streams above defined audience thresholds. Providers must deploy region-specific inference clusters to comply with data sovereignty provisions. German and French deployments face the strictest implementation timelines, with technical specifications still evolving through delegated acts.
Consumption patterns among enterprise buyers are fragmenting across use-case-specific procurement channels. Media publishers now separate live event infrastructure from video on demand platforms, creating vendor specialization opportunities. This bifurcation is most pronounced in the United States, where sports rights holders maintain distinct technology stacks from corporate communications teams.
Stream Hosting Market Segmentation
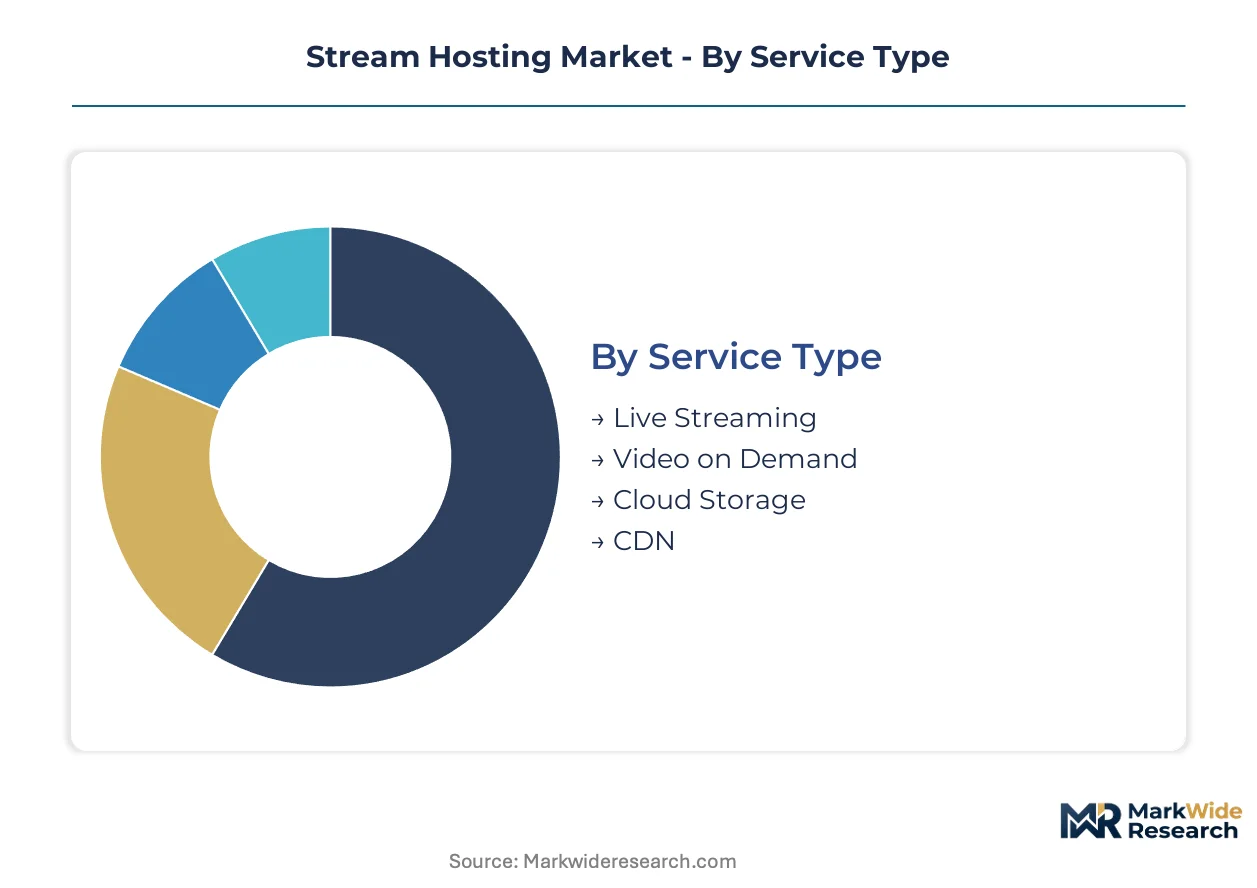
Stream hosting infrastructure serves divergent workload profiles that demand specialized architectural configurations. Segmentation reveals how live event broadcasting, enterprise communications, and creator monetization each impose distinct technical and commercial requirements on platform selection.
Service Type:
Migration cycles from legacy satellite distribution to cloud-native architectures are reshaping procurement priorities across service categories.
- Live Streaming:Real-time ingest, transcoding, and edge distribution infrastructure designed for sub-5 second latency requirements. Sports broadcasters in the United States and Japan are driving capacity expansion as they abandon satellite uplinks for elastic cloud clusters during audience spikes.
- Video on Demand:Storage-optimized architectures with multi-CDN failover and personalized recommendation engine integration. Subscription platforms in Germany are investing most heavily here as they compete on content discovery algorithms.
- Cloud Storage:Cold and warm archival tiers for compliance retention and content library monetization.
- CDN:Distributed edge caching networks optimized for last-mile delivery efficiency across varying network conditions.
Volume placements concentrate in Live Streaming; the faster expansion belongs to Video on Demand.
Technology:
Protocol selection directly determines device reach, latency floors, and development complexity for deployment teams.
- RTMP:Legacy ingest protocol maintaining dominance in professional broadcast workflows despite browser deprecation. Production houses in Japan continue standardizing on RTMP for camera-to-cloud pipelines due to established hardware ecosystem compatibility.
- HLS:Adaptive bitrate streaming protocol with native iOS support and mature DRM integration. Media companies across the United States deploy HLS as their primary distribution layer for premium content protection requirements.
- HTML5:Browser-native playback eliminating plugin dependencies for basic video consumption.
- WebRTC:Peer-to-peer protocol enabling sub-500ms latency for interactive applications without proprietary plugins.
Deployment density clusters around HLS; WebRTC is climbing the fastest as interactive use cases proliferate.
End User:
Buyer sophistication and procurement cycle length vary dramatically across organizational types and content strategies.
- Media Companies:Enterprise-grade infrastructure buyers requiring 99.99% SLA guarantees and dedicated support tiers. Broadcasters in Germany are migrating entire channel operations to cloud-native stacks, triggering multi-year vendor consolidation contracts.
- Enterprises:Internal communications and training video platforms with strict security and compliance mandates. North American corporations are displacing legacy hardware encoders with elastic SaaS solutions for town hall broadcasts.
- Content Creators:Individual and small-team producers prioritizing low barrier-to-entry and monetization tooling integration.
- Educators:Institutions requiring accessibility compliance, learning management system integration, and usage analytics.
Contract value concentrates with Media Companies; Educators represent the steepest expansion trajectory as institutional digital learning investments accelerate.
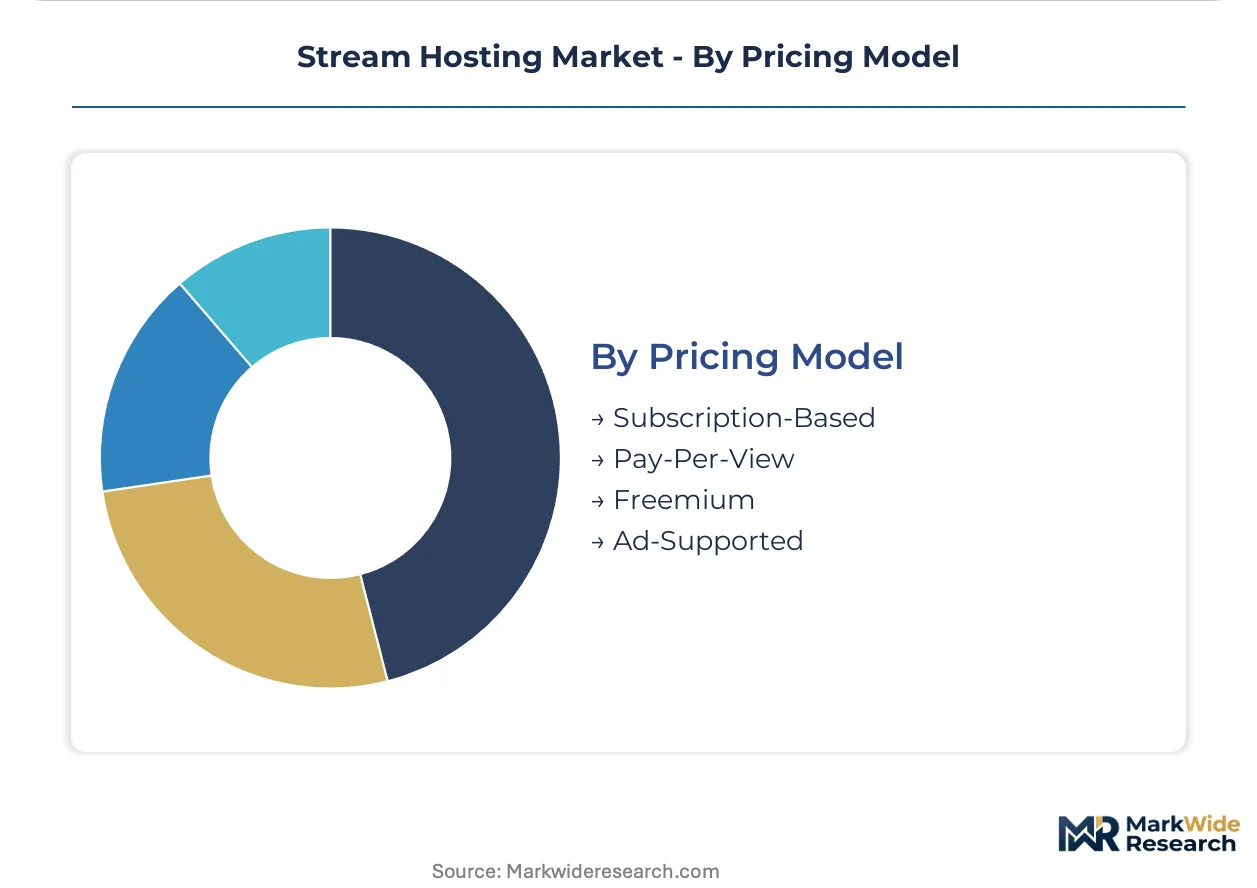
Pricing Model:
Commercial structure selection reflects customer cash flow constraints, content predictability, and monetization confidence.
- Ad-Supported:Zero upfront commitment model with revenue sharing on impressions delivered. Independent creators in the United States are entering the market through this tier as platform competition drives favorable revenue splits.
- Subscription-Based:Predictable monthly fees for committed capacity and feature access. Enterprise procurement committees in Germany favor this structure for budget forecasting certainty.
- Pay-Per-View:Event-based pricing for time-bound content with revenue tied to transaction volume.
- Freemium:Tiered feature gating designed to convert casual users to paid tiers through usage thresholds.
Customer acquisition volume flows through Ad-Supported; Subscription-Based contracts deliver the most stable revenue expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors cloud infrastructure deployment density, with hyperscaler transcoding clusters concentrated in Bay Area data centers serving North American broadcast migration.
United States
Sports rights holders in Los Angeles and New York Metro are abandoning satellite uplinks for elastic cloud clusters during championship audience spikes. FCC net neutrality rulings mandate transparent traffic management disclosures from edge providers. Dallas-Fort Worth hosts the densest concentration of low-latency transcoding nodes serving live event broadcasters.
Germany
Media publishers in Berlin and Munich are migrating entire channel operations to cloud-native stacks, triggering multi-year vendor consolidation contracts. GDPR data localization mandates require viewer analytics storage within sovereign boundaries. Frankfurt's financial district drives enterprise video communications procurement for compliance-heavy internal broadcasts.
Japan
Broadcasters in Tokyo and Osaka continue standardizing on RTMP for camera-to-cloud pipelines due to established hardware ecosystem compatibility. METI cloud security guidelines dictate encryption standards for transcoding node deployments. Nagoya's manufacturing corridor generates specialized industrial video streaming demand for remote equipment monitoring.
India
Subscription platforms in Mumbai and Bengaluru compete aggressively on content discovery algorithm investments. TRAI data localization requirements are fragmenting previously centralized infrastructure strategies across sovereign jurisdictions. Hyderabad's technology cluster hosts emerging ad-supported creator platforms attracting minimal upfront commitment entrants.
United Kingdom
Enterprise procurement committees in London favor subscription-based structures for budget forecasting certainty. Post-Brexit data adequacy negotiations with the EU reshape cross-border analytics storage architectures. Manchester's media production corridor drives specialized monetization tooling demand from independent content creators.
Stream Hosting Market Competitive Landscape
Premium-margin players sit above commodity-margin players across protocol flexibility and edge network density dimensions. The vendor base organizes into three tiers: hyperscaler cloud divisions with global infrastructure footprints, specialized media platform vendors with broadcast workflow expertise, and protocol-focused engineering houses with deep codec customization capabilities. Dominant competitive moves include strategic partnerships between CDN operators and broadcast rights holders, plus vertical integration into AI-driven content moderation pipelines to satisfy emerging regulatory mandates.
Within the hyperscaler tier, Amazon Web Services and Google Cloud Platform occupy positions defined by global edge network scale and enterprise procurement committee relationships. Among specialized media platform vendors, Brightcove and Kaltura exemplify the broadcast workflow specialization archetype, while Wowza Media Systems anchors the protocol engineering house category with deep customization capabilities spanning legacy through emerging standards.
| Leading Market Players |
|---|
| Amazon Web Services |
| Brightcove |
| Vimeo |
| IBM Video Streaming |
| Kaltura |
| Wowza Media Systems |
| Dacast |
| AKAMAI Technologies |
| Google Cloud Platform |
| Others |
Value Network & Pricing Analysis
Certification tier divergence between SOC 2 Type II audited providers and uncertified operators manifests simultaneously in subscription pricing premiums and data center placement strategies. Enterprise procurement committees in Germany and the United States pay thirty to fifty percent above base rates for compliant infrastructure, while providers absorb twelve to eighteen month audit timelines that compress margin recovery windows.
Pricing Analysis
Uptime-based SLA guarantees anchor value-based pricing for live event infrastructure, with 99.99% availability tiers commanding premium positioning against 99.9% standard offerings. Price differentiation rests on transcoding latency floors and edge node density rather than raw storage capacity. Pricing pressure stems from GPU accelerator allocation constraints originating in Taiwan and South Korea foundries. Ad-supported content creators exhibit highest price sensitivity; media companies with sports broadcast rights demonstrate least elasticity due to revenue-at-risk calculations during audience spikes.
Supply Chain Analysis
Intercontinental fiber capacity constraints and last-mile peering agreements determine logistics cost structures for edge node deployment. GPU accelerator supply concentrates in Taiwan, South Korea, and the United States. Transcoding hardware draws from NVIDIA and AMD silicon, specialized encoding ASICs, and high-density server chassis. Single-source vulnerability in Taiwan Semiconductor Manufacturing capacity creates allocation risk during foundry loading peaks. Distribution runs through hyperscaler cloud marketplaces, direct enterprise sales teams, and broadcast systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stream hosting infrastructure is becoming a vertical-integration race as providers pursue captive control over AI-driven content moderation pipelines to satisfy EU AI Act mandates without third-party dependency.
For Market Incumbents: Lock in broadcast rights holder relationships through multi-year capacity reservation contracts before WebRTC-native challengers erode latency advantages. Defend positioning by acquiring specialized FFmpeg engineering teams scarce in Germany and Japan. Prioritize backward integration into sovereign cloud deployments across India and France to preempt regulatory fragmentation. For New Entrants and Emerging Players: Launch via ad-supported creator platforms in Hyderabad and Bengaluru where minimal upfront commitment models attract price-sensitive independents. Target India's sovereign cloud compliance gap before hyperscaler localization completes. Penetrate through WebRTC-first interactive streaming for corporate training applications underserved by legacy RTMP workflows. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler cloud division absorption and broadcast technology conglomerate rollup. Long-term viability favors protocol engineering houses with deep codec customization capabilities over commodity CDN operators. Monitor EU AI Act delegated act finalization as inflection signal for content moderation infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Content Moderation Pipeline Deployment | EU AI Act compliance mandates automated classification infrastructure for live streams above audience thresholds in Germany and France. |
| AV1 Codec Transition Investment | Sports broadcasters in the United States and Japan pilot 4K distribution to reduce egress costs against H.264 legacy infrastructure. |
| Sovereign Cloud Node Localization | India's TRAI data localization requirements fragment centralized strategies and open dedicated deployment opportunities for compliant providers. |
| WebRTC Protocol Stack Acquisition | Browser-native streaming eliminates plugin dependencies and expands addressable device pools for interactive live applications. |
| Multi-CDN Failover Orchestration Layer | Legacy broadcast workflow migration demands complex API integration across incompatible vendor systems for enterprise procurement committees. |
Research Methodology
Document review covered hyperscaler capex disclosures, FCC net neutrality rulings, EU AI Act delegated act drafts, and broadcast technology trade publications, complemented by interviews with infrastructure engineering directors at media companies, cloud procurement officers at North American enterprises, and regulatory compliance leads at European platform operators. Secondary validation drew from ISO certification databases, SOC 2 audit registries, and customs data on GPU accelerator imports. Bottom-up capacity deployment tracking was triangulated against top-down market sizing from subscription platform disclosures.
Cross-referencing historical transcoding node deployment patterns against panel input from broadcast systems integrators shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service type, protocol technology, end user organization, and pricing model, with sovereign cloud jurisdiction status as an overlay dimension. CAGRs were derived from elasticity modeling of enterprise video communications adoption curves and sports broadcast migration rates. Industry-specific forecast inputs incorporated GPU foundry capacity allocation schedules and GDPR data localization implementation timelines.
EU AI Act technical specification delays, Taiwan foundry loading volatility, and enterprise procurement cycle elongation are the dominant revision risks to deployment assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and silicon supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
United States Online Gambling Market
Digital Media
South Korea Webtoons Market
Digital Media
Africa Animation Market
Digital Media
Digital Music Content Market
Digital Media
Anime Streaming Tool Market
Digital Media
Middle East Media and Entertainment Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Digital Content Locker Market
Digital Media
Wedding Photography Market
Digital Media
Sports Graphics Market
Digital Media
Animation and VFX Market
Digital Media
Online Movie Market
Digital Media
Middle East Gaming Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Anime Derivatives Market
Digital Media
Digital Music Services Market