
 Cyclic Corrosion Test Chamber Market | 2026-2036
Cyclic Corrosion Test Chamber Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclic Corrosion Test Chamber Market Analytics
ASTM B117-compliant specification-tier testing is rotating toward hybrid system architectures that combine salt spray, humidity, and drying cycles in programmable sequences. ESPEC Corp leverages its thermal engineering heritage to dominate large-capacity environmental chamber production for automotive tier-one suppliers. Angelantoni Test Technologies anchors its position in European aerospace certification workflows through precision digital control platforms. Q-Lab Corporation differentiates via extensive global service networks that sustain aftermarket calibration revenue streams.
A cyclic corrosion test chamber is a programmable environmental simulation device that cycles specimens through controlled salt fog, humid, dry, and sometimes UV exposure phases to accelerate corrosion damage assessment; typical units operate within temperature ranges of 15°C to 60°C with humidity control from 50% to 98% RH for metals, coatings, and component validation. Salt spray chambers retain the largest installed base across legacy automotive paint qualification programs, while automated system technology captures the fastest replacement cycle as electronics manufacturers demand remote monitoring and data logging compliance. Environmental chambers command premium pricing in aerospace applications where multi-parameter cycling replicates stratospheric-to-tropical operational profiles.
ISO 9227 and ASTM B117 standards govern test protocol acceptability across North America and Europe, while Japan's JIS Z 2371 framework shapes Pacific Rim equipment procurement specifications for export-oriented manufacturers. The U.S. EPA and OSHA indirectly influence chamber design through effluent handling requirements for corrosive salt solutions and operator exposure limits. Buyers must evaluate whether supplier calibration traceability chains satisfy multiple national metrology institute requirements before committing to long-life capital equipment contracts.
Market Dynamics
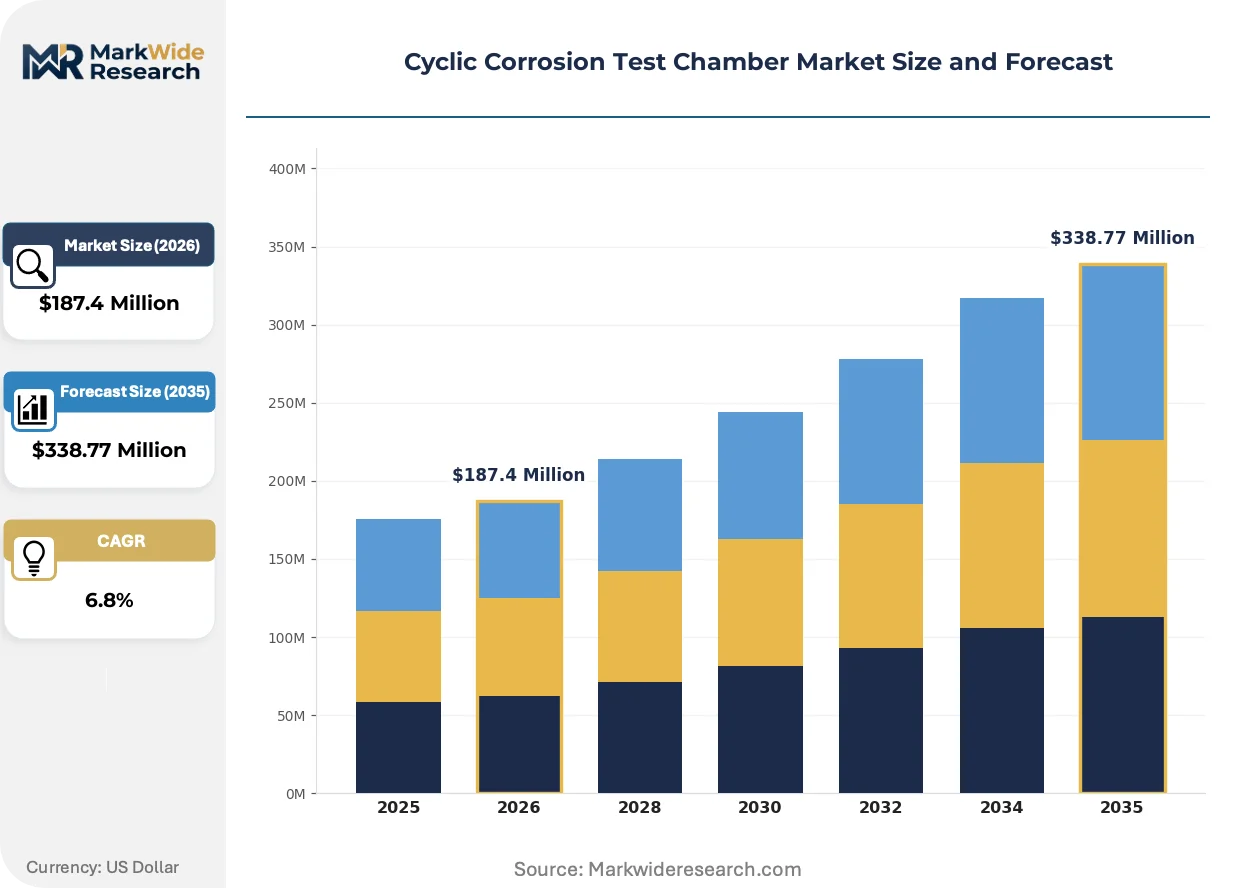
Automotive OEMs in Germany, Japan, and the United States are consolidating materials testing protocols under unified digital platforms, compressing replacement cycles for legacy manual chamber systems and elevating specification requirements for multi-parameter environmental simulation.
Growth Catalysts
- ISO 9227 Protocol Harmonization:European automotive tier-one suppliers are mandating salt spray-to-humidity cycling sequences that exceed legacy ASTM B117 scope, forcing equipment refresh cycles in Germany and France.
- Aerospace Stratospheric Simulation:Defense contractors in the United States require chambers replicating tropical-to-stratospheric thermal profiles for coating validation on next-generation airframes.
- Electronics Remote Monitoring Mandates:Japanese semiconductor manufacturers are specifying Ethernet-enabled data logging as a procurement prerequisite for qualification laboratory equipment.
Market Restraints
- Stainless Steel Input Volatility:Chamber construction relies on 316L-grade stainless for salt fog containment; nickel price swings in Q1-Q2 2024 compressed margins for European fabricators.
- Calibration Metrology Concentration:Traceable humidity sensor calibration chains depend on a narrow base of national metrology institutes in Germany, the United Kingdom, and Japan.
- Effluent Handling Compliance:The U.S. EPA's corrosive solution discharge protocols add capital cost layers for facilities without centralized wastewater neutralization infrastructure.
Strategic Opportunities
- Indian Automotive Export Certification:BIS adoption of harmonized ISO corrosion standards for vehicle component exports is creating first-mover equipment installation demand at Pune and Chennai testing clusters.
- UV-Salt Fog Convergence:Hybrid chambers combining cyclic corrosion with accelerated weathering are capturing specification share in exterior automotive coating programs.
- Service Network Unbundling:Third-party calibration providers are disintermediating OEM service contracts through mobile metrology units targeting multi-site manufacturing campuses.
Industry Challenges
- Multi-Standard Programming Complexity:Laboratory technicians must maintain proficiency across ISO 9227, ASTM B117, and JIS Z 2371 protocol variations, extending training timelines and error rates.
- Legacy System Integration Friction:Digital control retrofits on 15-20 year old salt spray chambers face sensor incompatibility with modern data acquisition architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclic Corrosion Test Chamber Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Spray Chamber, Environmental Chamber, Humidity Chamber, Cyclic Tester End User: Aerospace, Automotive, Electronics, Manufacturing Technology: Digital Control, Manual Control, Automated System, Hybrid System Capacity: Small, Medium, Large, Custom |
| Companies Covered | ESPEC Corp, Angelantoni Test Technologies, Q-Lab Corporation, Ascott Analytical Equipment, Hastest Solutions, Atlas Material Testing Technology, CME Corp, Singleton Corporation, Presto Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclic Corrosion Test Chamber Market Evolving Landscape
Programmable logic controllers with embedded edge computing are displacing standalone PID controllers, enabling real-time cycle adjustment and predictive maintenance alerts that reshape chamber operational economics.
Condensate recycling subsystems with closed-loop desalination are miniaturizing within chamber footprints previously dedicated to external water treatment. Automotive paint qualification laboratories in Stuttgart and Detroit are specifying these integrated modules to eliminate floor space penalties. The technology is compressing total cost of ownership calculations for high-throughput facilities running continuous cycling protocols.
REACH Annex XVII restrictions on hexavalent chromium in corrosion reference standards are forcing coating manufacturers to validate alternative pretreatment chemistries. European aerospace certification bodies are rewriting acceptance criteria for primer systems previously qualified under chromate-based protocols. German and French testing houses are investing in expanded chamber capacity to manage extended validation timelines for compliant coating stacks.
Consolidated procurement by multi-site automotive groups is concentrating purchasing authority at regional technical centers in Michigan, Bavaria, and Aichi Prefecture. Single-source framework agreements with preferred equipment vendors are displacing site-level capital expenditure autonomy. This concentration is visible most acutely in North American OEMs centralizing salt spray qualification under corporate metrology governance structures.
Cyclic Corrosion Test Chamber Market Segmentation
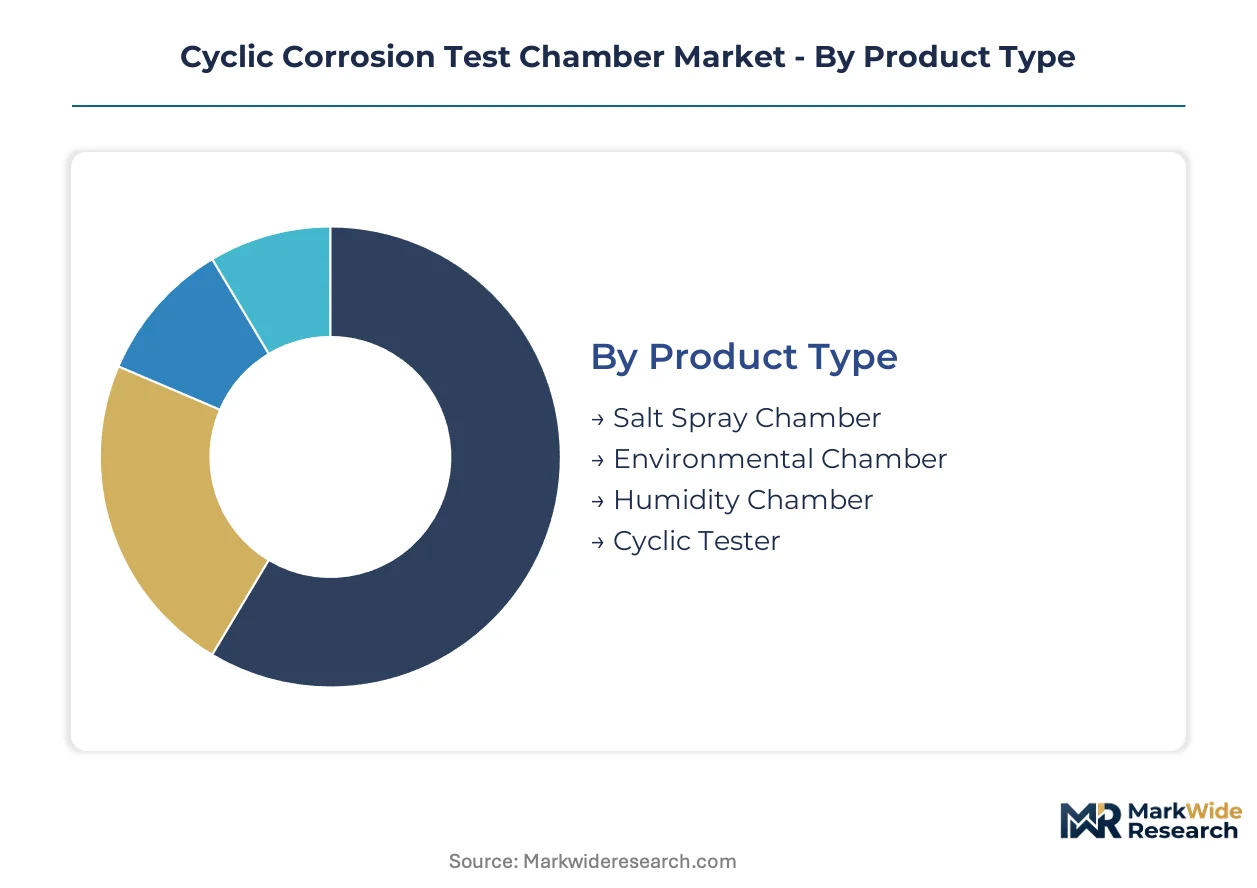
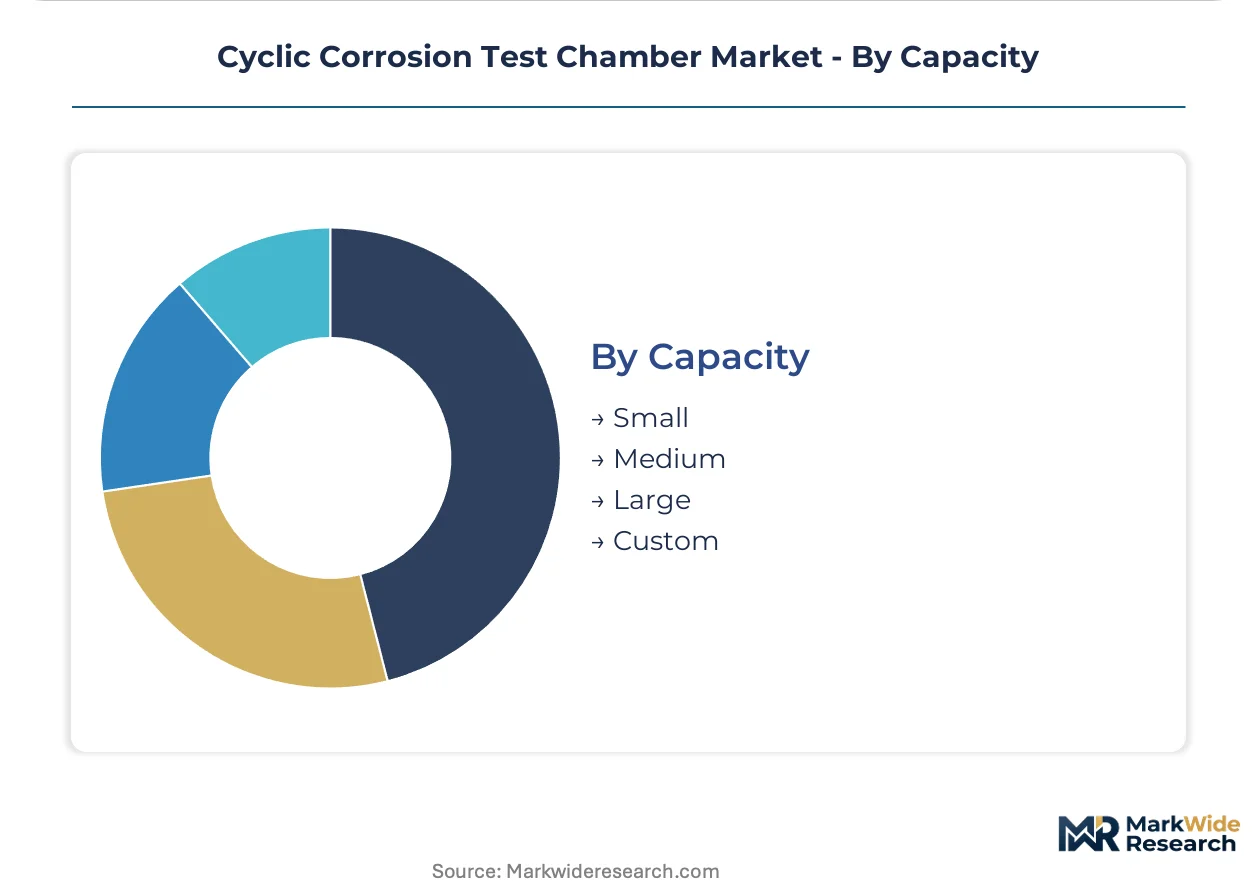
Cyclic corrosion test chamber procurement patterns diverge sharply by product architecture and operational scale. Aerospace contractors prioritize multi-parameter environmental simulation, while automotive tier-one suppliers drive volume through standardized salt spray protocols.
Product Type:
Direct sales channels dominate large-capacity environmental chambers, while distributor networks handle standardized salt spray units for mid-market manufacturing facilities.
- Environmental Chamber:Multi-parameter systems integrate thermal, humidity, and salt fog cycling within programmable sequences. German automotive OEMs and U.S. defense contractors specify these units for stratospheric-to-tropical profile replication, compressing validation timelines for advanced coating stacks.
- Salt Spray Chamber:Single-parameter fog exposure systems retain the largest installed base across legacy automotive paint qualification programs. Japanese and South Korean electronics manufacturers maintain extensive fleets for component-level corrosion screening, though replacement cycles are accelerating toward automated alternatives.
- Humidity Chamber:Standalone moisture cycling units serve specialized electronics stress-testing applications.
- Cyclic Tester:Compact programmable units address R&D laboratory budgets and pilot production lines.
By volume, Salt Spray Chamber leads. By growth pace, Environmental Chamber is ahead.
End User:
Specification authority concentrates at corporate technical centers, with procurement autonomy shifting from plant-level engineers to centralized metrology governance.
- Automotive:Tier-one suppliers in Germany, Japan, and the United States mandate ISO 9227-compliant cycling sequences that exceed legacy ASTM B117 scope, forcing equipment refresh cycles and elevating digital control requirements.
- Aerospace:Defense contractors operate centralized materials testing laboratories where multi-parameter chambers command premium pricing for airframe coating validation.
- Electronics:Semiconductor manufacturers specify Ethernet-enabled data logging as a procurement prerequisite.
- Manufacturing:General industrial users favor standardized salt spray protocols for quality assurance.
Automotive captures the dominant revenue share. Aerospace exhibits the steepest expansion trajectory.
Technology:
Cost tiers separate legacy manual installations from digitally integrated platforms, with hybrid architectures commanding mid-range positioning.
- Automated System:Programmable logic controllers with embedded edge computing enable real-time cycle adjustment and predictive maintenance alerts. Japanese semiconductor manufacturers and German automotive groups specify these platforms for remote monitoring compliance.
- Digital Control:Precision PID-based platforms anchor European aerospace certification workflows through calibration traceability chains.
- Hybrid System:Combines manual override with programmable sequences for flexible R&D applications.
- Manual Control:Basic dial-and-timer units persist in low-throughput facilities with limited capital budgets.
Manual Control retains the largest installed base. Automated System is climbing the fastest.
Capacity:
Facility footprint constraints and test batch economics drive sizing decisions, with custom configurations addressing non-standard specimen geometries.
- Large:Walk-in and chamber-scale systems accommodate full vehicle body panels and airframe sections. ESPEC Corp dominates this tier for automotive tier-one suppliers requiring continuous cycling protocols.
- Medium:Cabinet-style units serve multi-site manufacturing campuses with consolidated procurement frameworks.
- Small:Benchtop chambers address electronics component screening and laboratory R&D budgets.
- Custom:Engineered solutions for non-standard specimen dimensions and specialized cycling profiles.
Medium capacity leads by unit volume. Custom configurations gain share fastest in aerospace applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in Germany, Japan, and the United States, where automotive OEMs and defense contractors operate centralized materials testing laboratories. National metrology institutes in these markets anchor calibration traceability chains that shape procurement specifications. Demand clusters in industrial corridors where coating validation protocols intersect with export certification requirements.
United States
Defense contractors in Texas and California require stratospheric-to-tropical thermal profile replication for airframe coating validation. The EPA's corrosive solution discharge protocols add capital cost layers for facilities without centralized wastewater neutralization infrastructure. Michigan's automotive technical centers are consolidating salt spray qualification under corporate metrology governance structures.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg mandate ISO 9227-compliant cycling sequences that exceed legacy ASTM B117 scope. REACH Annex XVII restrictions on hexavalent chromium are forcing coating manufacturers to validate alternative pretreatment chemistries. Stuttgart testing houses are investing in expanded chamber capacity to manage extended validation timelines.
Japan
Semiconductor manufacturers in the Tokyo-Osaka corridor specify Ethernet-enabled data logging as a procurement prerequisite for qualification laboratory equipment. JIS Z 2371 frameworks shape Pacific Rim equipment procurement specifications for export-oriented manufacturers. Aichi Prefecture automotive groups are centralizing materials testing protocols under unified digital platforms.
India
BIS adoption of harmonized ISO corrosion standards for vehicle component exports is creating first-mover equipment installation demand. The PLI scheme for automotive manufacturing is accelerating testing infrastructure buildout at Pune and Chennai clusters. Domestic fabricators are capturing share in mid-capacity salt spray chamber segments.
South Korea
Electronics manufacturers in Gyeonggi Province maintain extensive fleets for component-level corrosion screening. Korean automotive OEMs are refreshing legacy manual chamber systems to meet European export certification requirements. Busan-Ulsan shipbuilding clusters are specifying multi-parameter environmental simulation for marine coating validation.
Cyclic Corrosion Test Chamber Market Competitive Landscape
Concentration sits with diversified environmental equipment conglomerates and specialized test chamber fabricators. The vendor base spans three tiers: large-capacity system integrators serving automotive OEMs, precision digital control specialists anchoring aerospace certification workflows, and regional fabricators addressing mid-market manufacturing facilities. Strategic moves center on calibration service network expansion and hybrid system architecture development.
Among Japanese diversified manufacturers, ESPEC Corp exemplifies the large-capacity system integrator archetype through its thermal engineering heritage. Angelantoni Test Technologies S.p.A. represents the European precision digital control specialist segment. Q-Lab Corporation anchors the North American service-intensive positioning through aftermarket calibration infrastructure.
| Leading Market Players |
|---|
| ESPEC Corp |
| Angelantoni Test Technologies |
| Q-Lab Corporation |
| Ascott Analytical Equipment |
| Hastest Solutions |
| Atlas Material Testing Technology |
| CME Corp |
| Singleton Corporation |
| Presto Group |
| Others |
Value Network & Pricing Analysis
Large-capacity chamber fabrication at ESPEC Corp's Japanese facilities generates scale economies that compress unit costs for multi-parameter environmental systems while elevating price floors for mid-market competitors lacking comparable throughput. This concentration of thermal engineering capability in Germany, Japan, and the United States simultaneously anchors premium pricing for aerospace-grade certification tiers and squeezes margin structures for European fabricators exposed to nickel price volatility in 316L stainless procurement.
Pricing Analysis
ISO 9227 and ASTM B117 compliance dictates the pricing tier structure across the cyclic corrosion test chamber market, separating premium multi-parameter environmental chambers from standardized salt spray units. Three-tier pricing structure across premium, standard, and economy levels reflects calibration traceability depth, with aerospace certification workflows commanding the highest tier. Cost compression in mid-capacity segments is intensifying because Indian domestic fabricators are capturing share at Pune and Chennai testing clusters. Tier-one automotive suppliers in Germany and Japan exhibit the lowest price sensitivity due to consolidated corporate procurement frameworks, while general manufacturing facilities in emerging clusters remain highly price-sensitive.
Supply Chain Analysis
Nickel price volatility through the LME underwrites margin instability for European chamber fabricators dependent on 316L-grade stainless steel salt fog containment systems. Geographic supply concentration centers on Germany, Japan, and the United States for precision digital control platforms, with China and South Korea expanding presence in mid-capacity segments. Raw material dependencies rest on nickel alloys, humidity sensor components, and programmable logic controller modules. Single-source vulnerability in traceable humidity sensor calibration chains concentrated at national metrology institutes in Germany, the United Kingdom, and Japan creates structural risk. Distribution runs through direct sales channels for large-capacity systems and distributor networks for standardized units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
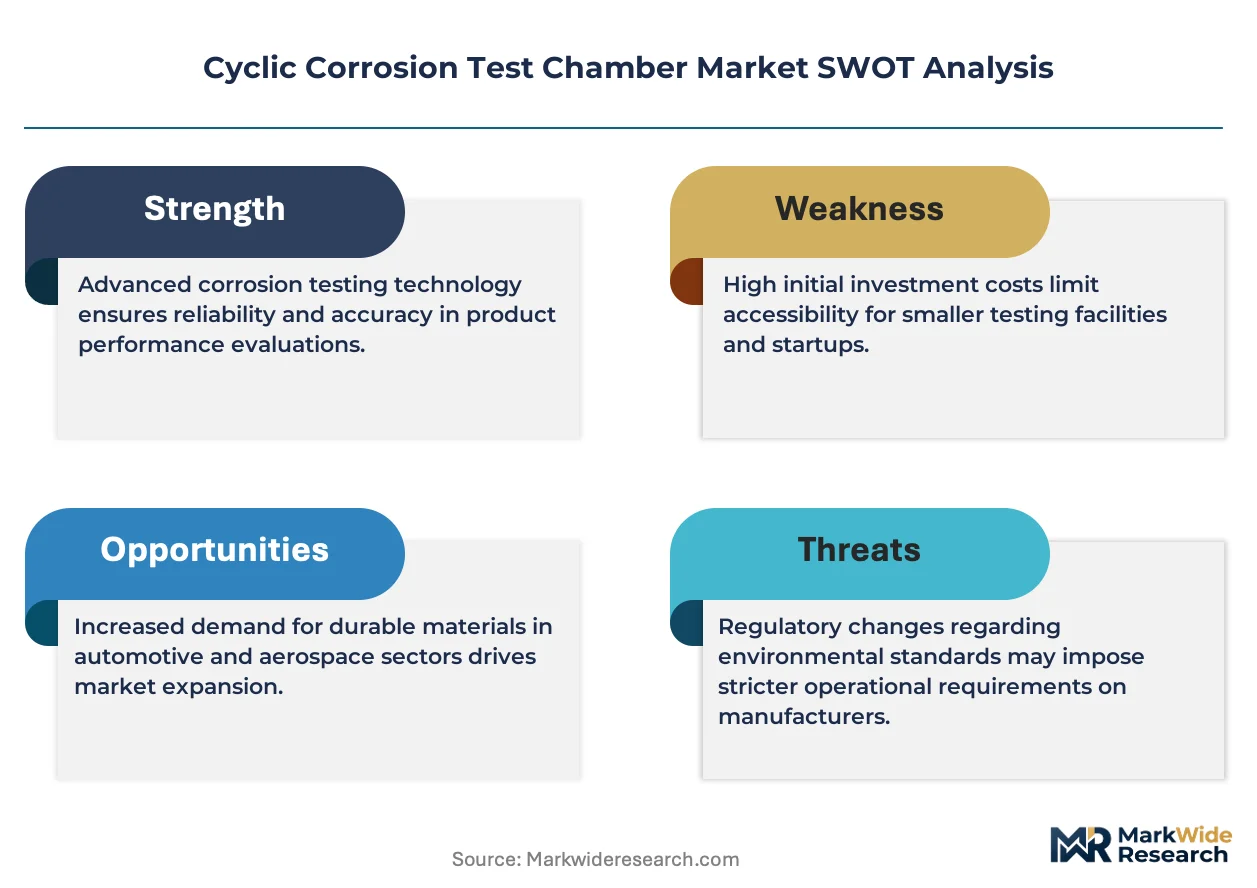
This market functions as a defensive-moat story anchored in regulatory entrenchment: calibration traceability chains and ISO/ASTM certification requirements create switching costs that protect incumbent positions against price-based competition.
For Market Incumbents: Shield market position by deepening backward integration into humidity sensor calibration infrastructure to reduce dependency on national metrology institute bottlenecks. Expand service network density through mobile metrology units targeting multi-site automotive campuses in Michigan and Aichi Prefecture, neutralizing third-party calibration disintermediation threats.
For New Entrants and Emerging Players: Aftermarket calibration service gaps in Indian automotive export corridors present the most penetrable white-space opportunity. Target Pune and Chennai testing clusters with ISO 9227-compliant chamber installations ahead of BIS harmonization completion. Pursue a calibration-first go-to-market angle, using service contracts to secure equipment placement in price-sensitive mid-market facilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision digital control specialists serving aerospace certification workflows, where calibration contracts extend equipment lifecycle value. Long-term viability favors vendors with embedded edge computing platforms and remote monitoring capabilities. Monitor REACH Annex XVII regulatory expansion as the primary signal for coating validation demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calibration Infrastructure | Captive humidity sensor calibration reduces dependency on German and UK national metrology institutes. |
| Mobile Metrology Unit Deployment | On-site calibration services at multi-site automotive campuses in Michigan displace OEM service contracts. |
| Hybrid System Architecture Development | UV-salt fog convergence captures specification share in exterior automotive coating programs at Stuttgart laboratories. |
| Indian Market First-Mover Installation | BIS harmonization at Pune and Chennai clusters creates equipment placement ahead of competitor response. |
| Condensate Recycling Subsystem Integration | Closed-loop desalination modules compress total cost of ownership for high-throughput Detroit facilities. |
Research Methodology
A standing panel of automotive tier-one supplier procurement directors, aerospace materials testing laboratory managers, semiconductor qualification engineers, and aftermarket calibration service heads provided ongoing calibration against secondary data streams. Primary fieldwork combined structured interviews with these stakeholder roles alongside validation against ISO 9227 and ASTM B117 regulatory filings, SEC 10-K disclosures from diversified environmental equipment manufacturers, customs and trade data for 316L stainless steel imports, and national metrology institute calibration protocol documentation. Bottom-up equipment shipment tallies by capacity tier and technology type were triangulated against top-down market sizing derived from automotive OEM capital expenditure disclosures and aerospace defense contractor R&D procurement patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product architecture, end-use industry, control technology tier, and capacity scale alongside regional regulatory cluster differentiation. CAGRs were derived from installed base replacement cycle analysis and new facility buildout trajectories. Industry-specific forecast inputs incorporated REACH Annex XVII coating chemistry transition timelines and BIS harmonization implementation schedules for Indian automotive export certification.
Forecasts assume regulatory continuity in ISO 9227, ASTM B117, and REACH Annex XVII regimes; material policy shifts would require re-modeling of equipment refresh cycle assumptions. Practitioners should keep alternative scenarios live as nickel price volatility and national metrology institute capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Laboratory Accessories Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Global Residue Testing Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Dynamic Light Scattering (DLS) Measure Instrument Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Laboratory Ware Market
Testing Equipment
Viscometer Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
Test Point Hoses Market