
 Dance Shoes Market | 2026-2036
Dance Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Dance Shoes Market Analysis
A shortage of specialized pattern-makers and last-carvers with dance-biomechanics expertise is redrawing competitive boundaries for premium manufacturers. Grishko leverages its vertically controlled St. Petersburg workshop to sustain artisan-grade pointe shoe consistency. Capezio competes through broad SKU coverage across recreational and pre-professional segments. Gaynor Minden differentiates via thermoplastic shank technology that extends product lifespan beyond traditional paste-construction alternatives.
Dance shoes are purpose-built footwear engineered with split-sole or full-sole architectures, suede or leather outsoles calibrated for controlled friction coefficients of 0.3–0.6 on hardwood, and shock-absorbing midsoles to attenuate repetitive impact loads. Their primary commercial purpose is to enable precise articulation, rotational stability, and aesthetic line preservation across choreographed performance. Leather constructions occupy the dominant margin pool in ballet and ballroom categories due to durability premiums and professional certification requirements. Canvas segments lead volume in jazz and training environments where breathability and lower price points drive replacement frequency. Satin materials concentrate in competitive performance sub-segments where visual uniformity under stage lighting commands priority over longevity.
ISO 16181 footwear safety standards, REACH chemical compliance for European-market dyes and adhesives, and U.S. Consumer Product Safety Commission guidelines for children's footwear flammability collectively shape material selection and market access protocols. The EU F-Gas Regulation indirectly affects synthetic sole production through restricted blowing agents in polyurethane midsole formulations. Stakeholders must monitor how evolving biomechanics research and regional chemical compliance timelines reshape raw material sourcing decisions and product development pipelines.
Market Dynamics
Biomechanics research and injury-prevention protocols are compressing replacement cycles across professional dance circuits, forcing manufacturers to accelerate R&D cadences while maintaining artisan-grade construction standards.
Growth Catalysts
- REACH chemical compliance:European-market dye and adhesive standards are filtering out low-grade competitors, creating certification-based demand concentration for compliant suppliers.
- Suede-soled architecture adoption:Competitive ballroom and Latin circuits are standardizing controlled-glide specifications, pulling specialized sole procurement from recreational into performance-grade tiers.
- Brazilian dance school procurement:Samba and forró academies sustain institutional-volume orders that stabilize seasonal demand fluctuations for specialized footwear manufacturers.
Market Restraints
- Artisan skill scarcity:Pattern-makers and last-carvers with dance-biomechanics expertise command wage premiums that compress margin structures for mid-tier producers.
- EU F-Gas Regulation:Restricted blowing agents in polyurethane midsole formulations are forcing reformulation cycles that extend product development timelines.
- Canvas substitution pressure:Breathable synthetic alternatives are capturing jazz and training segment volume, eroding leather's historical dominance in entry-level categories.
Strategic Opportunities
- Pre-professional academy channels:Conservatories and university dance programs represent underpenetrated institutional procurement with multi-year contract potential.
- Thermoplastic shank convergence:Injection-molded polymer technologies are opening lifespan-extension positioning against traditional paste-construction alternatives.
- ISO 16181 safety certification:Standardized impact-load testing protocols are creating differentiation vectors for manufacturers investing in certified laboratory partnerships.
Industry Challenges
- Biomechanics research integration:Translating motion-capture data into last-design specifications requires cross-functional teams that most manufacturers lack.
- Multi-jurisdiction compliance stacking:Simultaneous adherence to U.S. CPSC flammability guidelines, REACH chemical standards, and ISO safety protocols strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dance Shoes Market |
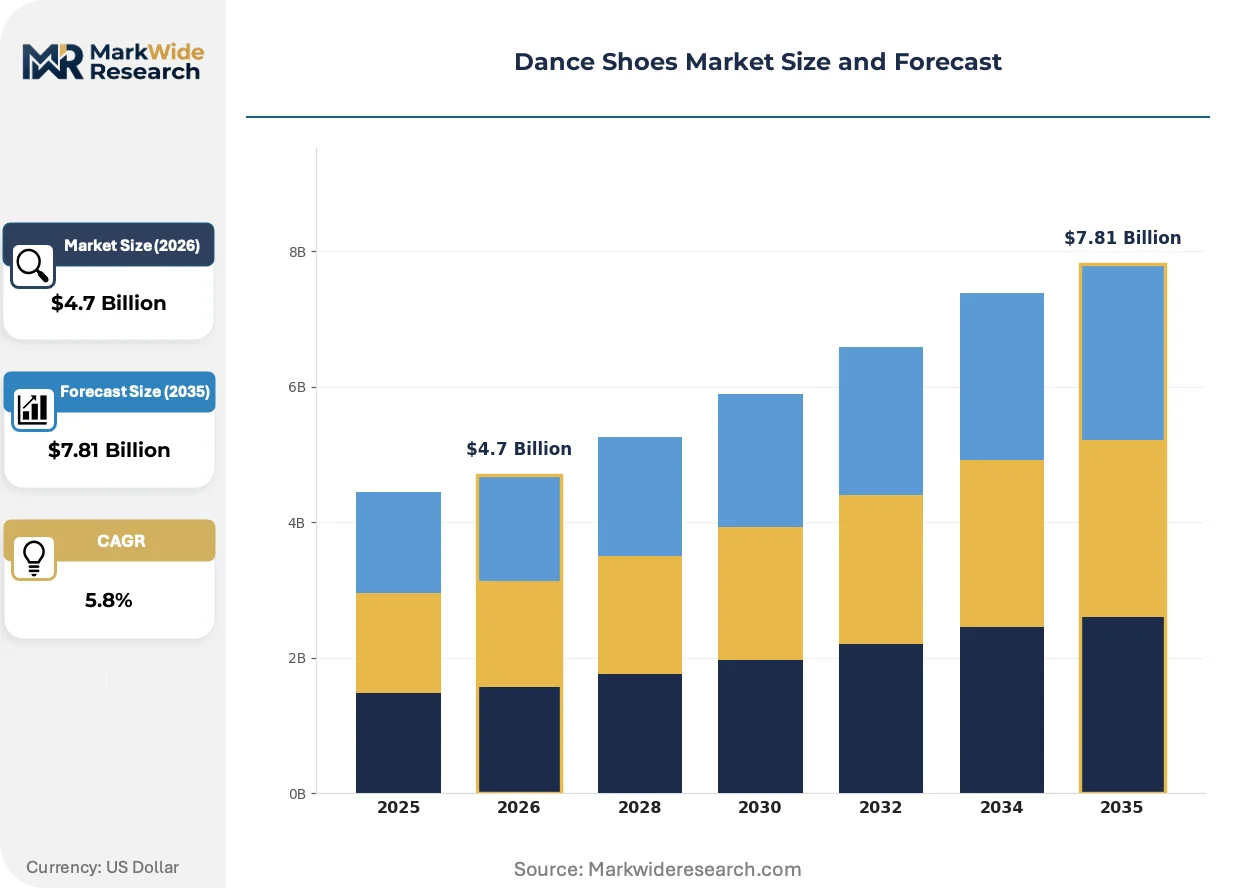
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballroom, Salsa, Jazz, Ballet Material: Leather, Canvas, Satin, Suede End User: Professional Dancers, Recreational Dancers, Dance Schools, Competitions Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Grishko, So Danca, Bloch, Chacott, Gaynor Minden, Capezio, Mirella, Wear Moi, Repetto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dance Shoes Market Emerging Trajectories
Material science and regulatory chemistry are reconfiguring competitive boundaries, separating manufacturers with captive R&D capabilities from assemblers dependent on commoditized inputs.
Thermoplastic shank technology is bifurcating the pointe shoe category. Professional companies are adopting injection-molded polymer cores that extend functional lifespan beyond traditional paste-construction alternatives. This shift is compressing replacement frequency for elite dancers while forcing heritage manufacturers to defend position through vertical control over artisan workshops.
REACH and EU F-Gas Regulation are jointly constraining European-market formulations. Dye and adhesive compliance timelines are accelerating supplier qualification cycles, while restricted blowing agents in polyurethane midsoles are pushing production toward water-based or physical foaming alternatives. Suede-soled ballroom and Latin categories face the steepest reformulation costs given friction-coefficient sensitivity.
Direct-to-academy procurement is displacing traditional retail intermediation. Conservatory and pre-professional program buyers are negotiating institutional contracts that bundle fitting services with volume pricing. Brazil's samba school networks and Russia's state ballet academies represent the most visible manifestations of this channel compression.
Dance Shoes Market Segmentation
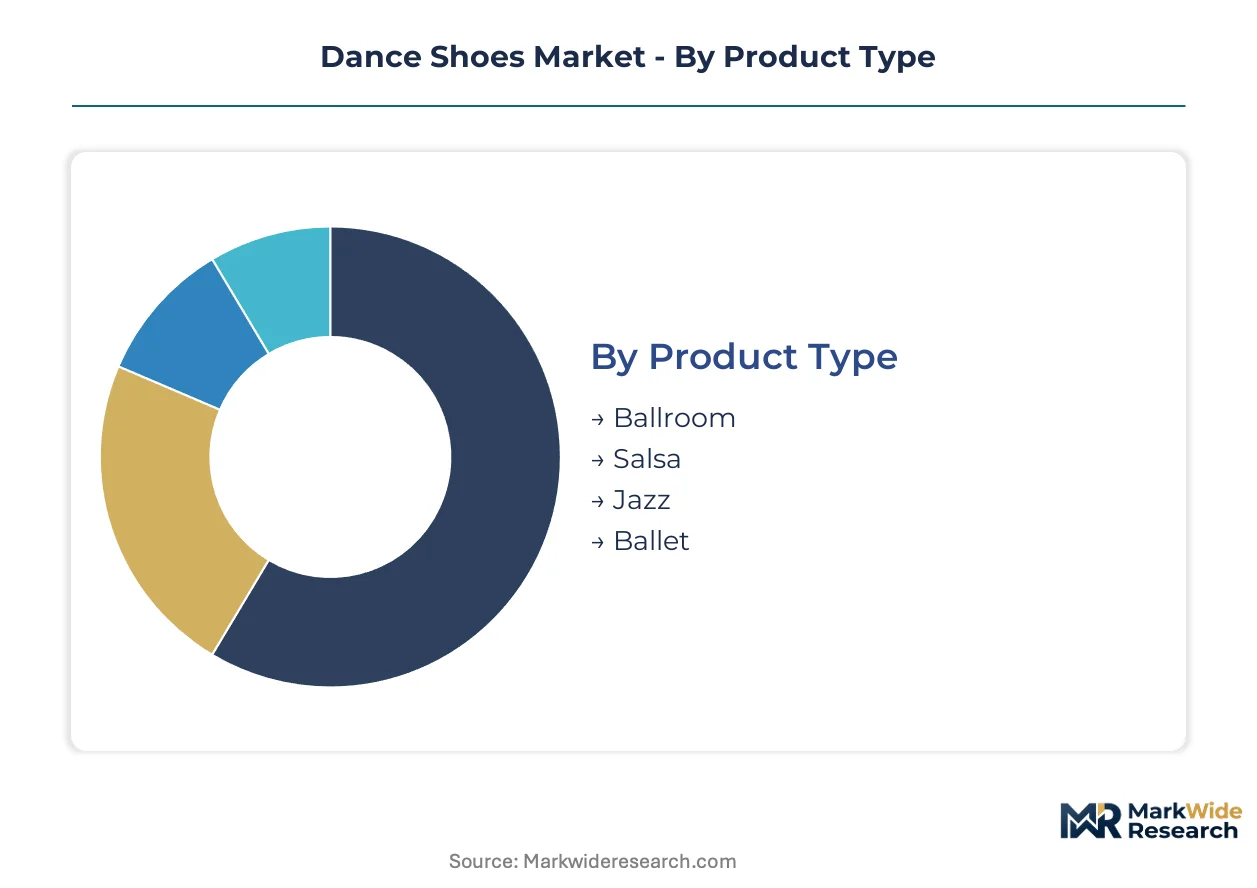
Dance footwear segmentation reveals how material science, biomechanical requirements, and procurement channel evolution fragment demand across specialized use cases. Each dimension carries distinct margin profiles and substitution vulnerabilities that reshape competitive positioning.
Product Type:
Synthetic upper technologies and cross-training footwear are pressuring entry-level Jazz and Recreational Ballroom segments most aggressively, while technical certification requirements protect Professional Ballet and Competitive Salsa categories.
- Ballroom:Full-sole and split-sole constructions with suede outsoles calibrated for 0.3–0.6 friction coefficients on hardwood. Demand concentrates in competitive circuits across Brazil and the United Kingdom where federations mandate standardized footwear for sanctioned events.
- Salsa:Lightweight designs with reinforced lateral support for rapid directional changes. Procurement from Colombian and Puerto Rican social dance academies is accelerating as these institutions professionalize instructor certification programs.
- Jazz:Split-sole or full-sole configurations with rubber or suede outsoles prioritizing floor contact and flexibility. Canvas and synthetic alternatives are capturing volume in studio training environments where breathability outweighs durability premiums.
- Ballet:Pointe shoes and soft slippers with paste-construction or thermoplastic shank architectures. Russian and French state academies sustain concentrated demand for artisan-grade products with professional certification requirements blocking mass-market substitution.
Ballroom retains volume leadership; Salsa holds the steepest expansion curve.
Material:
Cost tier stratification separates premium protein-based constructions from mass-market synthetics, with certification requirements and performance thresholds determining viable substitution at each level.
- Leather:Full-grain and split-grain constructions dominating ballet and ballroom categories. Professional certification bodies in Russia and Italy mandate leather for examination footwear, creating regulatory moats against synthetic alternatives.
- Canvas:Cotton or cotton-blend uppers with reinforced stitching for jazz and training applications. Brazilian and Argentine studio networks are driving replacement frequency through institutional procurement of breathable, lower-cost options.
- Satin:Silk or synthetic silk-faced materials for competitive performance aesthetics. Stage lighting uniformity requirements in United Kingdom and United States competitive circuits sustain demand despite limited durability.
- Suede:Split leather or synthetic suede outsoles providing controlled glide on hardwood surfaces. REACH chemical compliance is filtering European suppliers and concentrating procurement among certified manufacturers with reformulation capabilities.
Canvas commands the broadest volume base; thermoplastic-reinforced Suede formulations are climbing the fastest.
End User:
Customer type determines procurement channel, price sensitivity, and replacement cycle length, with institutional buyers extracting volume discounts that compress margins for mid-tier suppliers.
- Professional Dancers:Athletes requiring injury-prevention designs with biomechanically optimized lasts. Replacement cycles are compressing across Russian and French company rosters as motion-capture research informs footwear specifications.
- Recreational Dancers:Social participants prioritizing comfort and aesthetic over technical performance. Online retail penetration is highest in this segment, with United States and German consumers driving direct-to-consumer brand adoption.
- Dance Schools:Institutional buyers negotiating multi-year contracts with fitting services. Brazilian samba and forró academies represent the most visible concentration of academy-channel procurement stabilizing seasonal demand.
- Competitions:Event organizers and federations mandating standardized footwear for sanctioned participation. United Kingdom and Italian ballroom circuits enforce the strictest technical specifications, creating certification-based supplier concentration.
Dance Schools anchor procurement volume; Competition-organizer contracts are expanding most quickly.
Distribution Channel:
Channel selection reflects customer sophistication, fitting complexity, and urgency requirements, with technical categories resisting disintermediation due to biomechanical customization needs.
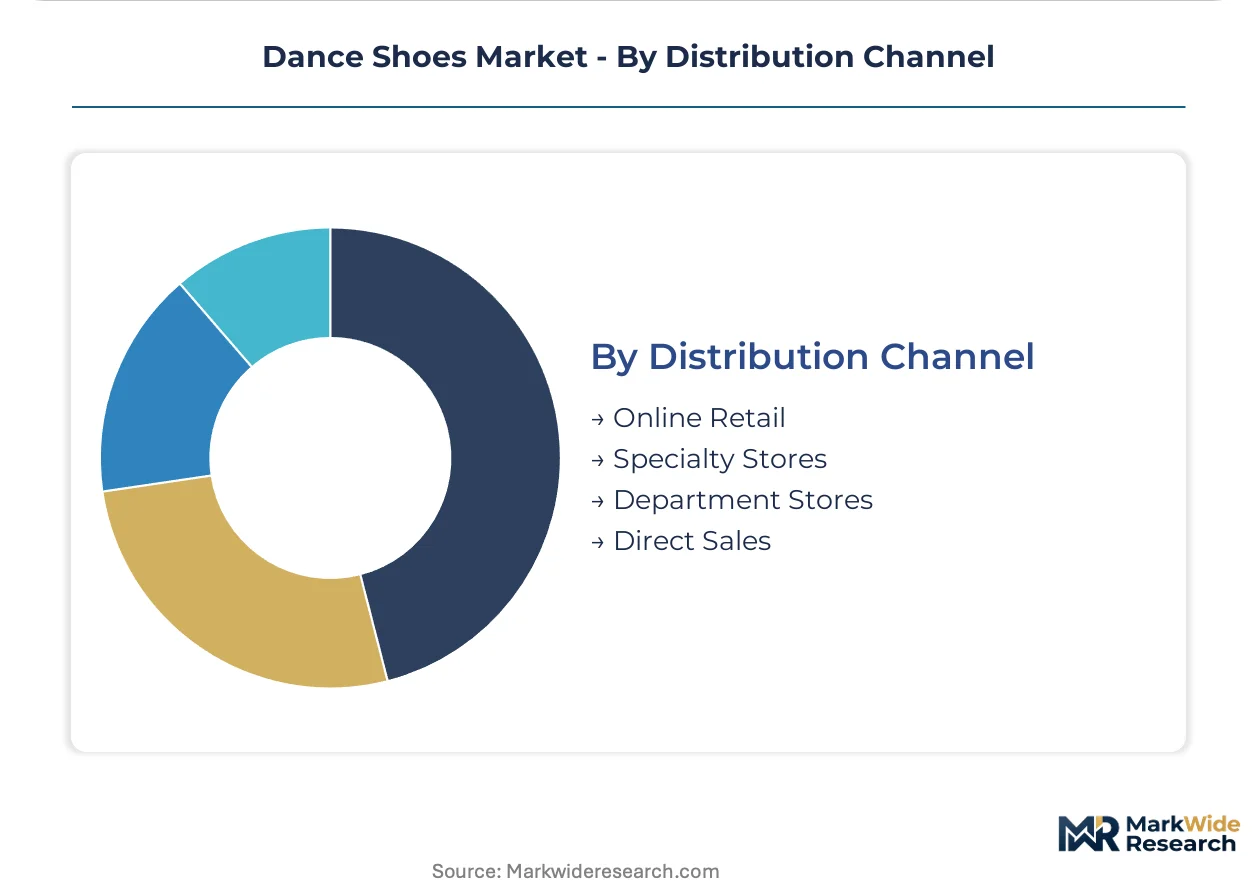
- Online Retail:E-commerce platforms capturing recreational and replacement purchases. German and United States consumers demonstrate highest digital adoption for standardized sizes and repeat purchases.
- Specialty Stores:Fitting-focused retailers with trained staff for pointe shoe and competitive ballroom categories. Russian and French metropolitan markets sustain the densest specialty store networks serving professional segments.
- Department Stores:Mass-market retail for introductory and children's dance footwear. Brazilian and Argentine department store chains capture family-driven seasonal purchasing around academic calendars.
- Direct Sales:Manufacturer-to-academy contracts with embedded fitting services. Conservatory and pre-professional programs in Russia and Brazil are pioneering this channel compression.
Specialty Stores retain the highest margin concentration; Direct Sales is gaining share fastest among institutional buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical compliance anchors European demand concentration, filtering suppliers and reshaping procurement patterns across the continent's competitive dance circuits.
Brazil
Samba and forró academies sustain institutional-volume procurement that stabilizes seasonal demand for specialized footwear manufacturers. ANVISA regulates product safety for children's dance footwear categories. São Paulo's dance school networks concentrate the country's largest academy-channel contracts.
United States
Pre-professional conservatories and university dance programs drive institutional procurement with multi-year contract potential. CPSC flammability guidelines govern children's footwear safety requirements. New York City and Los Angeles metropolitan areas host the densest specialty retail networks serving professional segments.
United Kingdom
Competitive ballroom and Latin circuits enforce strict federation-mandated footwear specifications for sanctioned events. REACH chemical standards filter dye and adhesive suppliers serving the European market. London's competitive dance infrastructure anchors procurement volume for performance-grade categories.
Russia
State ballet academies sustain concentrated demand for artisan-grade products with professional certification requirements. National standards bodies oversee footwear safety protocols for institutional procurement. St. Petersburg's vertically integrated workshops supply heritage manufacturers serving elite company rosters.
France
Professional certification bodies mandate leather constructions for examination footwear, creating regulatory moats against synthetic alternatives. ECHA oversees REACH compliance timelines for chemical formulations. Paris and Lyon metropolitan areas concentrate specialty retail serving conservatory and pre-professional segments.
Dance Shoes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the dance footwear sector. Heritage manufacturers with captive artisan workshops compete against technology-driven challengers with polymer-based construction methods. Two strategic archetypes dominate: vertically controlled heritage producers and materials-science specialists. Competitive moves concentrate on direct-to-academy channel compression and thermoplastic shank technology licensing.
Within the heritage tier, Grishko and Capezio exemplify contrasting approaches to market positioning. Gaynor Minden occupies a position representing materials-science differentiation through polymer-based construction methods. These three anchors illustrate how competitive boundaries redraw around either artisan-grade consistency or technology-driven lifespan extension.
| Leading Market Players |
|---|
| Grishko |
| So Danca |
| Bloch |
| Chacott |
| Gaynor Minden |
| Capezio |
| Mirella |
| Wear Moi |
| Repetto |
| Others |
Supply Flow & Price Mechanics
Direct-to-academy contracts with embedded fitting services lock in multi-year supply access and price visibility for dance footwear manufacturers serving institutional buyers in Brazil and Russia. These arrangements insulate heritage producers from spot-market volatility while compressing margin flexibility for mid-tier competitors dependent on retail intermediation.
Pricing Analysis
Brazil-to-United Kingdom price spreads of 40-60% reflect freight differentials and REACH compliance costs embedded in European-market formulations. Three-tier pricing structure across artisan-grade, pre-professional, and recreational levels segments buyers by certification requirements and replacement frequency. Pricing pressure stems from canvas substitution in jazz training segments where breathability premiums erode leather's historical dominance. Recreational dancers exhibit highest price sensitivity; professional company rosters prioritize injury-prevention specifications over unit cost.
Supply Chain Analysis
Strategic stockpiling of thermoplastic polymer feedstock dominates inventory strategy among pointe shoe specialists, offsetting reformulation delays from EU F-Gas Regulation restrictions. Manufacturing concentrates in Russia, Brazil, and Italy where vertically controlled workshops sustain artisan-grade output. Raw material sourcing draws from Argentine leather tanneries, Chinese synthetic textile mills, and German chemical suppliers for polyurethane midsole formulations. Single-source vulnerability concentrates in specialized last-carving expertise concentrated in St. Petersburg and Paris metropolitan clusters. Distribution runs through specialty retail networks in Moscow and Lyon for professional segments, with direct sales displacing intermediaries for academy-channel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-professional academy channel compression represents early-cycle expansion tailwind as institutional procurement professionalizes across conservative state ballet networks and Brazilian social dance academies.
For Market Incumbents: Secure captive supply of pattern-makers with dance-biomechanics expertise through apprenticeship pipelines in St. Petersburg and Paris workshop clusters. Deepen backward integration into thermoplastic polymer formulation partnerships to defend against Gaynor Minden's lifespan-extension positioning. Certification investment in ISO 16181 laboratory partnerships creates regulatory moats as compliance timelines accelerate. For New Entrants and Emerging Players: Fitting-service gaps in United States university dance programs offer white-space entry where heritage manufacturers under-serve volume procurement with embedded biomechanical assessment. Target pre-professional conservatory segments with subscription-based replacement programs bundling motion-capture informed sizing. Go-to-market angle centers on direct academy contracts bypassing specialty retail margin extraction. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated heritage producers with captive workshop networks and established academy-channel relationships rather than asset-light assemblers. Long-term viability favors manufacturers with reformulation capabilities navigating REACH and F-Gas compliance evolution. Inflection signal to monitor: thermoplastic shank adoption rates crossing threshold penetration in Russian state company rosters.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Shank Licensing | Polymer formulation partnerships with Russian state academies extend product lifespan beyond paste-construction alternatives. |
| Direct-to-Academy Channel Expansion | Embedded fitting services in São Paulo and Rio de Janeiro samba school networks stabilize seasonal demand fluctuations. |
| REACH Compliance Certification | Validated dye and adhesive formulations secure European market access as chemical standards filter low-grade competitors. |
| Artisan Workshop Acquisition | Captive pattern-maker and last-carver expertise in St. Petersburg insulates against wage-premium margin compression. |
| Biomechanics Laboratory Partnership | Motion-capture informed last design differentiates injury-prevention positioning for professional dancer segments. |
Methodological Framework
The analysis maps ballroom, salsa, jazz, and ballet footwear sub-sectors, each validated through primary interviews with conservatory procurement directors, specialty retail fitting specialists, and heritage manufacturer workshop managers. Secondary sources include ANVISA regulatory filings, ECHA REACH compliance databases, and customs records tracking leather and synthetic textile trade flows. Bottom-up academy contract volume estimates triangulate against top-down market sizing from federation membership data.
Consistency checks validated volume and value outputs against external benchmarks from national dance council enrollment statistics and competitive event participation records. The analytical framework segments by product type, material construction, end-user category, and distribution channel across the projection horizon. CAGRs derive from replacement cycle compression rates informed by biomechanics research adoption curves and institutional procurement professionalization timelines. Forecast inputs incorporate REACH reformulation cost pass-through assumptions and thermoplastic shank technology diffusion patterns.
Underlying assumptions cover sustained academy-channel contract professionalization and REACH compliance timeline adherence, with deviation risk concentrated in artisan skill scarcity wage spirals and F-Gas Regulation reformulation delays. Forecasts reflect these conditions with revision triggers tied to regulatory enforcement intensity and substitution technology penetration thresholds. Revision becomes warranted when thermoplastic shank adoption in Russian state company rosters crosses critical mass or when Brazilian academy procurement consolidates beyond current concentration levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Cowboy Boots Market
Footwear
Second Hand Designer Shoes Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
Training Shoes Market
Footwear
Waterproof Sneakers Market
Footwear
Global Men Leather Shoes Market
Footwear
Footwear Testing Services Market
Footwear
Wedge Boots Market
Footwear
Trail Running Shoes Market
Footwear
Sandals Market
Footwear
High Heels Footwear Market
Footwear
Light Up Shoes Market
Footwear
Refurbished Running Shoes Market
Footwear
White Sneakers Market
Footwear
Western Boots Market
Footwear
Leather Sneakers Market