
 Spice Coated Casing Market | 2026-2036
Spice Coated Casing Market Size, Share, and Industry Trends Forecast 2026-2036
Spice Coated Casing Market Analytics
Foodservice distribution is reshaping how spice coated casings reach end users, with direct-supply agreements replacing traditional broker networks. Viscofan leverages its cellulose expertise to sustain flavor-impregnation R&D programs across Iberian facilities. Kalle GmbH anchors Central European supply through its alginate-casing specialization. DAT-Schaub Group competes on natural-casing sourcing depth, while Almol Casing Pty Ltd. differentiates via halal-certified product lines for Middle Eastern export channels.
Spice coated casings are edible or non-edible tubular membranes impregnated with seasoning blends—typically paprika, black pepper, garlic, or smoke extracts—designed to transfer flavor during thermal processing or storage. Pork casings dominate value share due to collagen compatibility with fat-soluble spice matrices, though vegetarian casings from alginate and cellulose are gaining traction among European plant-based processors. Application demand concentrates in sausages, where pre-seasoned casings reduce downstream blending steps and standardize batch flavor profiles for food manufacturers.
FDA food-contact substance notifications govern spice migration limits in U.S. markets, while EFSA evaluates novel seasoning extracts under updated flavoring regulation protocols. The EU Green Deal's packaging sustainability targets are pressuring casing producers to eliminate synthetic flavor carriers and adopt biodegradable substrate formulations. Stakeholders must monitor evolving maximum residue limits for botanical extracts and assess whether in-house spice compounding or outsourced seasoning supply delivers stronger compliance margins.
Market Dynamics
Direct-supply agreements between casing manufacturers and food processors are collapsing traditional broker networks, compressing margin layers and forcing seasoning specialists to develop captive flavor-compounding capabilities or exit the value chain entirely.
Growth Catalysts
- REACH compliance deadlines:European processors accelerate migration to disclosed-ingredient casing formulations ahead of ECHA substance restriction timelines, pulling demand toward certified suppliers.
- Midwest meatpacking corridor expansion:USDA-inspected facilities in Iowa and Nebraska add dedicated spice-impregnation lines to capture premium sausage contract volumes from national retail chains.
- Cellulose substrate R&D:Flavor-encapsulation advances in plant-derived membranes enable clean-label positioning without synthetic carrier systems.
Market Restraints
- Pork collagen input volatility:Swine herd fluctuations in Denmark and the Netherlands transmit directly to casing raw material costs, squeezing processor margins during supply contractions.
- Bavarian processing cluster concentration:Overreliance on southern German sausage manufacturers for premium casing demand creates geographic demand risk during regional production disruptions.
- EFSA novel extract evaluation timelines:Extended safety assessments for botanical seasoning candidates delay product launches by 18-24 months versus established spice matrices.
Strategic Opportunities
- Halal-certified export channels:Untapped demand across Saudi Arabia and UAE foodservice sectors favors suppliers with SAMR-aligned slaughter certification and spice traceability documentation.
- EU Green Deal packaging mandates:Biodegradable substrate requirements position alginate casing specialists for preferential procurement from sustainability-committed European retailers.
- Direct-to-processor digital platforms:B2B ordering systems bypass traditional ingredient distributors, enabling real-time flavor customization and smaller minimum order quantities for craft sausage startups.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in fat-soluble spice migration modeling remains concentrated among retired industry veterans and select German technical universities.
- FDA food-contact notification timelines:Each novel seasoning extract requires individual FCN submission, creating regulatory backlogs that stall product pipeline velocity.
- Legacy blending equipment incompatibility:Pre-seasoned casings demand modified stuffing and linking machinery, forcing capital expenditure decisions at mid-sized processors with depreciated asset bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spice Coated Casing Market |
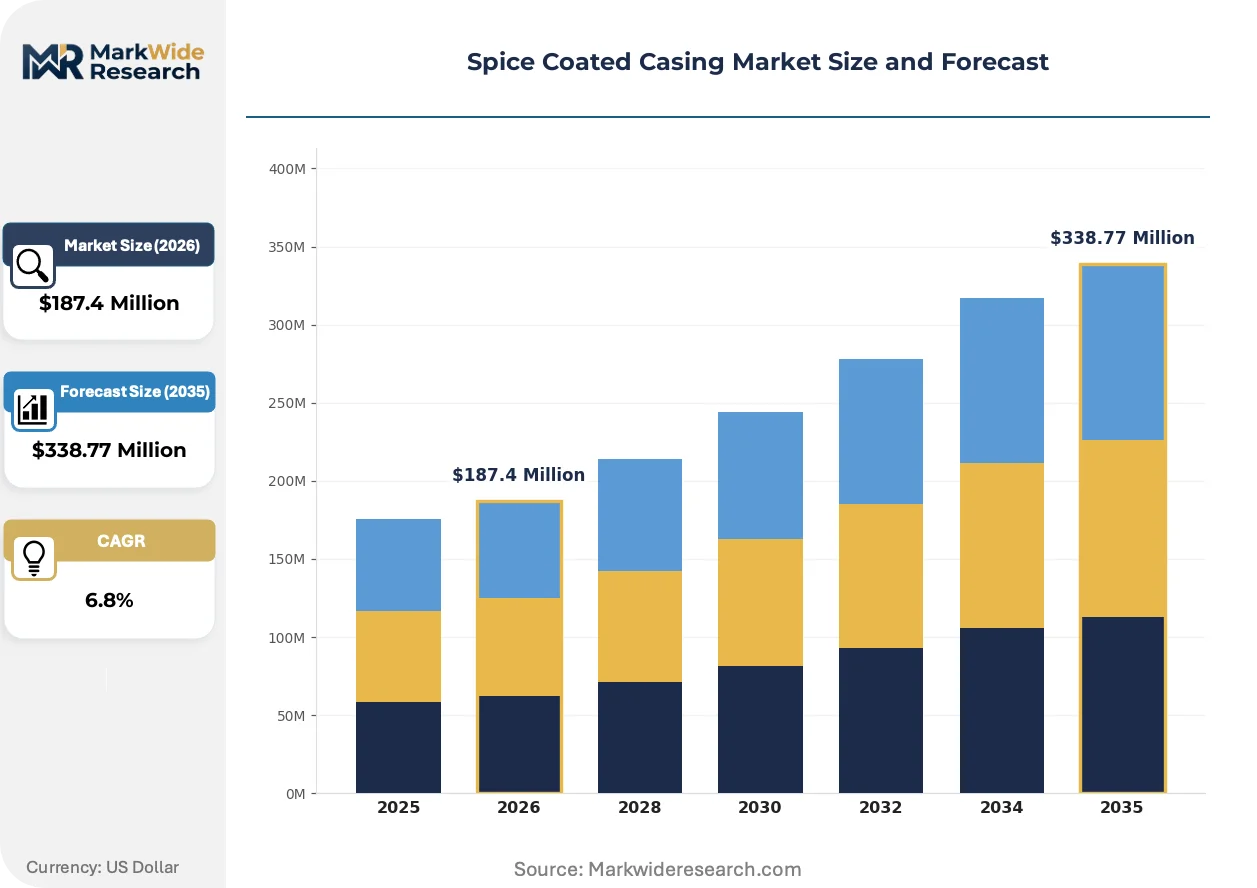
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork Casings, Beef Casings, Chicken Casings, Vegetarian Casings Application: Sausages, Meat Snacks, Deli Meats, Soups Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice End User: Restaurants, Food Manufacturers, Catering Services, Retail Consumers |
| Companies Covered | Almol Casing Pty Ltd., MCJ Casings Ltd., Viskase Companies, Viscofan, World Casings Corporation, Kalle GmbH, DAT-Schaub Group, Natural Casings Company, Walsroder Casings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spice Coated Casing Market Evolving Landscape
Active migration toward disclosed-ingredient systems and biodegradable substrates is reconfiguring supplier qualification criteria, while digital procurement platforms compress traditional distribution hierarchies.
Encapsulation technology for smoke and spice extracts is migrating from synthetic carrier systems to alginate and cellulose matrices. Clean-label sausage processors in Germany and the United States adopt these substrates at accelerating pace. The shift enables flavor standardization without EFSA scrutiny of artificial additive categories, compressing regulatory approval pathways for new product introductions.
EFSA updated flavoring regulation protocols now mandate expanded toxicological data for botanical extracts used in food-contact applications. This industrial consequence extends development timelines and increases compliance costs for seasoning compounders. Small and mid-sized casing suppliers without in-house regulatory affairs functions outsource dossier preparation, creating dependency on specialized consulting firms.
Food manufacturers consolidate casing procurement through direct supplier contracts rather than ingredient broker networks. National retail sausage programs in the United States Midwest specify approved casing vendor lists, displacing distributor intermediaries. This concentration is most visible among USDA-inspected facilities seeking volume-based pricing and dedicated technical service support.
Spice Coated Casing Market Segmentation
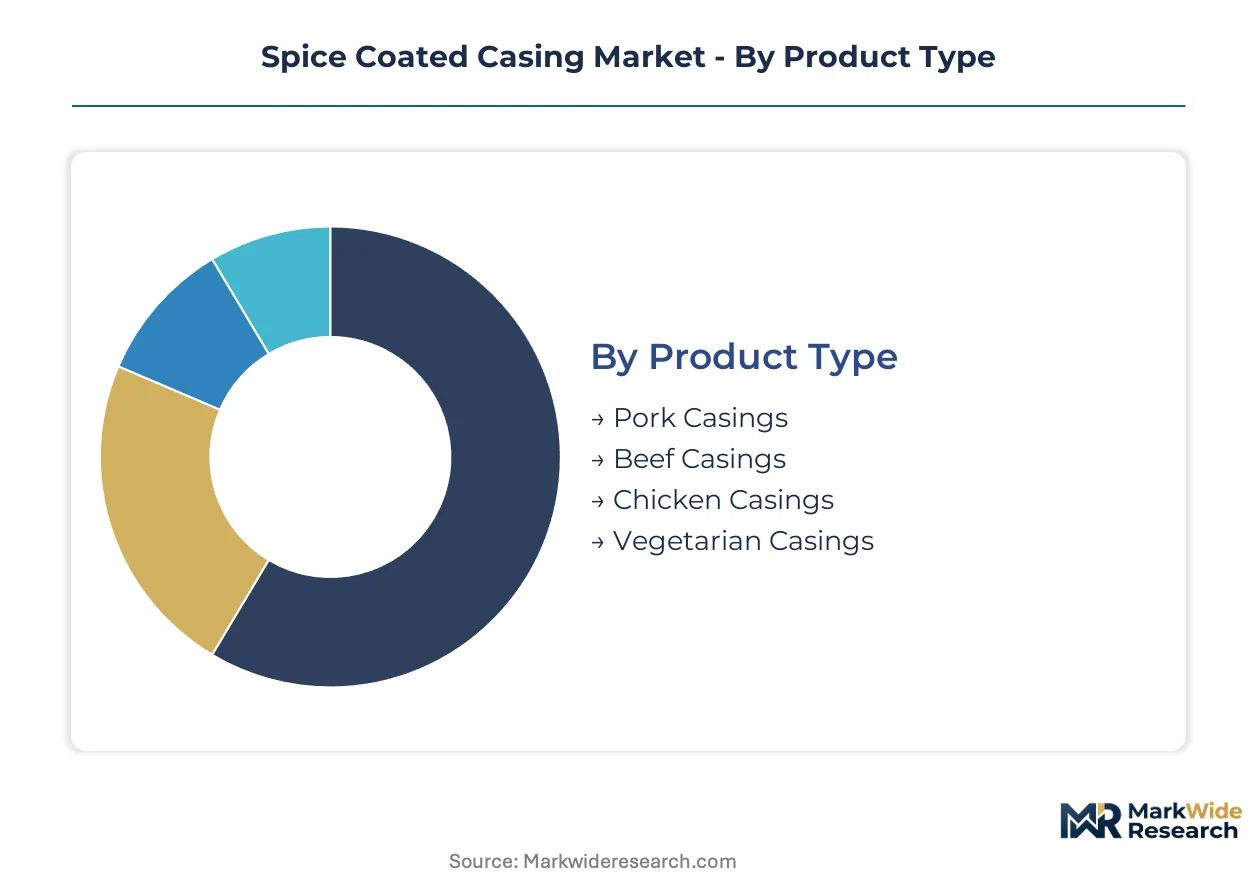
Segmentation in spice coated casings reveals how substrate chemistry, thermal processing requirements, and procurement channel preferences fragment demand across distinct customer workflows. Manufacturers configure production lines around these divides.
Product Type:
Mature collagen-based formats anchor volume, while emerging plant-derived alternatives reshape supplier qualification criteria.
- Pork Casings:Collagen-dense membranes from swine intestines deliver optimal fat-soluble spice adhesion and smoke penetration during thermal processing. German Bavarian processors and U.S. Midwest meatpacking facilities specify these for premium bratwurst and kielbasa lines where traditional bite and snap define quality benchmarks.
- Vegetarian Casings:Alginate and cellulose matrices now achieve flavor-impregnation parity with synthetic carriers eliminated, enabling clean-label positioning for European plant-based sausage startups. EFSA scrutiny of artificial additive categories compresses regulatory pathways for these substrates relative to petroleum-derived alternatives.
- Beef Casings:Larger diameter collagen tubes serve dry-cured salami and summer sausage applications requiring extended aging periods.
- Chicken Casings:Thinner, more delicate membranes suit poultry-based breakfast links and halal-certified product lines for Middle Eastern export channels.
Pork casings handle the majority of throughput; vegetarian casings are expanding most quickly on share.
Application:
Cost tier stratification separates commodity volume plays from margin-rich specialty positioning.
- Sausages:Fresh, smoked, and dried tubular meat products represent the core demand reservoir, with pre-seasoned casings eliminating downstream blending steps. USDA-inspected facilities in Iowa and Nebraska add dedicated spice-impregnation lines specifically to capture national retail chain contracts in this segment.
- Meat Snacks:Portable, shelf-stable products like pepperoni sticks and jerky strips require casing formulations with controlled moisture transmission rates.
- Deli Meats:Sliced luncheon products employ spice coated casings for surface seasoning rather than full matrix impregnation.
- Soups:Edible casing fragments dissolve during thermal preparation to release seasoning into broth bases.
Sausages dominate absolute volume; meat snacks climb fastest on margin contribution per kilogram.
Distribution Channel:
Customer type determines whether procurement flows through specification-driven institutional contracts or impulse-responsive retail pathways.
- Foodservice:Direct-supply agreements between casing manufacturers and restaurant chains or industrial processors displace traditional broker networks. National retail sausage programs specify approved vendor lists, concentrating procurement among certified suppliers with dedicated technical service capabilities.
- Supermarkets:Mass-market retail chains demand standardized flavor profiles and consistent supply security for private-label programs.
- Specialty Stores:Artisan butchers and ethnic food retailers source halal-certified and small-batch seasoned casings.
- Online Retail:Digital B2B platforms enable real-time flavor customization and reduced minimum order quantities for craft sausage startups.
Foodservice channels command the largest contract values; online retail gains share fastest among emerging processors.
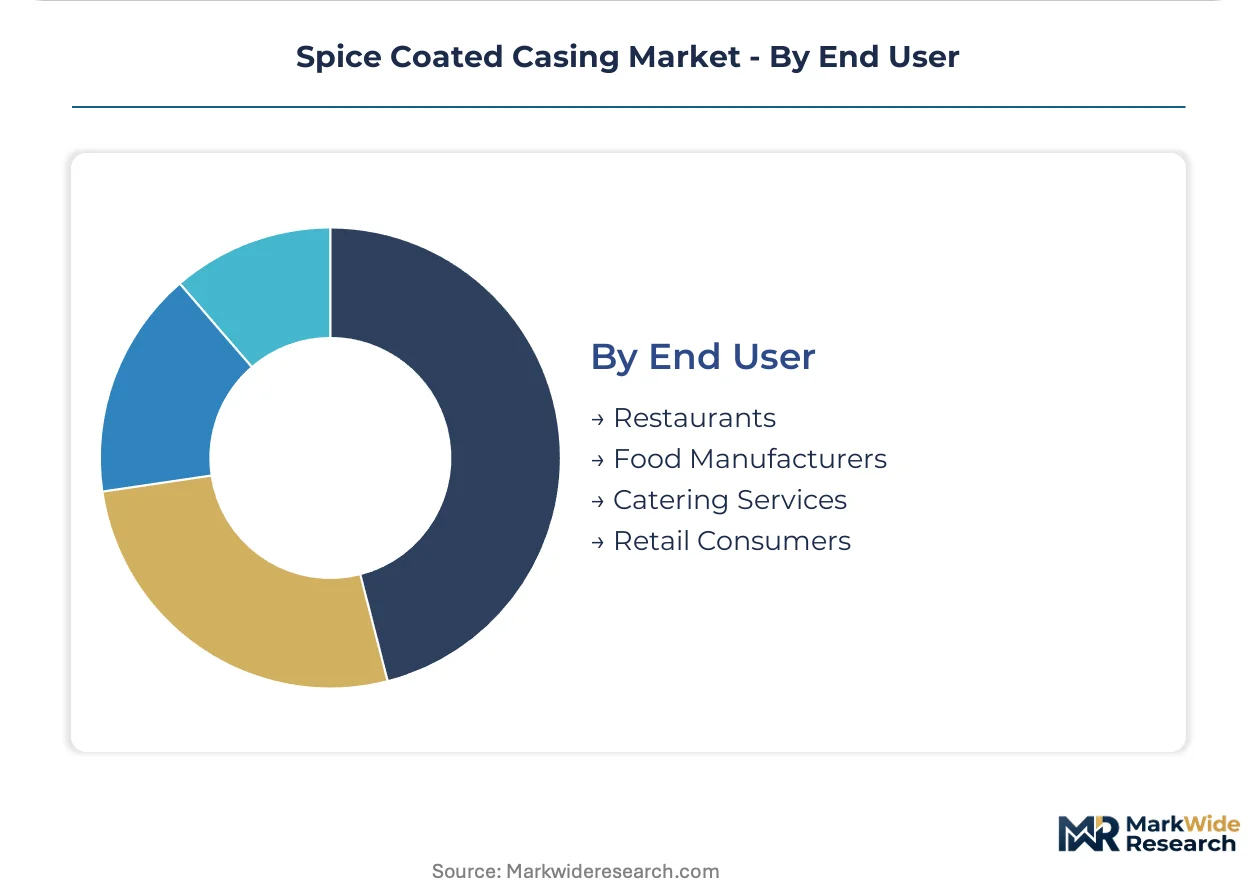
End User:
Supply concentration in food manufacturing contrasts with geographic dispersion across foodservice and retail endpoints.
- Food Manufacturers:Industrial processors in Germany's Bavarian cluster and the U.S. Midwest corridor drive specification-setting for the entire value chain. REACH compliance deadlines accelerate their migration toward disclosed-ingredient formulations ahead of ECHA substance restriction timelines.
- Restaurants:Casual dining and quick-service chains specify pre-seasoned casings to standardize menu item preparation across franchise locations.
- Catering Services:Event and institutional food providers prioritize batch consistency and labor reduction over flavor customization.
- Retail Consumers:Home sausage makers purchase small-format casing packs through specialty retailers and e-commerce platforms.
Food manufacturers absorb the bulk of production volume; restaurants show the steepest expansion trajectory in premium segment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's refrigerated cargo terminals anchor Central European casing distribution, while the Union Pacific rail corridor links Nebraska meatpacking plants to West Coast export gateways. These infrastructure assets concentrate procurement flows for spice-impregnated membranes across two dominant manufacturing clusters.
United States
USDA-inspected facilities in Iowa and Nebraska drive casing specification-setting for national retail sausage programs. FDA food-contact substance notifications govern spice migration limits for domestic processors. The Midwest meatpacking corridor now hosts dedicated spice-impregnation lines installed specifically to capture volume contracts from supermarket chains.
Germany
Bavarian sausage manufacturers in the Munich-Augsburg-Nuremberg triangle generate premium casing demand for traditional bratwurst and Weisswurst lines. REACH compliance deadlines from ECHA accelerate migration toward disclosed-ingredient formulations among processors. The southern German cluster concentrates Europe's highest per-capita consumption of collagen-based seasoned casings.
Spain
Iberian cured meat traditions sustain demand for smoke-impregnated cellulose casings in chorizo and salchichón production. EFSA updated flavoring regulation protocols mandate expanded toxicological data for botanical seasoning extracts used in food-contact applications. Viscofan's Navarre facilities anchor flavor-encapsulation R&D programs serving both domestic and export markets.
Saudi Arabia
Foodservice sector expansion across Riyadh and Jeddah creates import demand for halal-certified spice coated casings with full slaughter certification traceability. SAMR-aligned documentation requirements from the Saudi Food and Drug Authority govern entry protocols for Middle Eastern supply channels. Almol Casing's halal-certified product lines occupy a strategic position within this import-dependent market structure.
China
Domestic sausage consumption growth in the Yangtze River Delta and Pearl River Delta regions pulls casing imports through Shanghai and Shenzhen ports. NMPA food-contact material standards and evolving GB standards for food additives create compliance complexity for foreign suppliers. Local processors increasingly specify pre-seasoned casings to standardize flavor profiles across fragmented regional production bases.
Spice Coated Casing Market Competitive Landscape
On the supply side, the industry is moderately consolidated around cellulose and collagen substrate specialists with established regulatory dossier capabilities. Tier-one suppliers compete on REACH certification and FDA notification velocity, while mid-tier players differentiate through halal certification or regional sourcing depth. Two strategic archetypes dominate: integrated substrate-flavor compounders and specialized natural casing sourcers. Competitive moves concentrate on direct-to-processor digital platform deployment and biodegradable substrate formulation partnerships ahead of EU Green Deal packaging mandates.
Among European specialists, Kalle GmbH exemplifies the alginate-casing archetype with its Central European manufacturing footprint, while DAT-Schaub Group occupies a position within natural-casing sourcing depth tiers. Viscofan represents the integrated cellulose-flavor compounder model with its sustained R&D investments across Iberian production assets. These three anchors illustrate how substrate chemistry specialization maps to distinct competitive positioning within procurement channel hierarchies.
| Leading Market Players |
|---|
| Almol Casing Pty Ltd. |
| MCJ Casings Ltd. |
| Viskase Companies |
| Viscofan |
| World Casings Corporation |
| Kalle GmbH |
| DAT-Schaub Group |
| Natural Casings Company |
| Walsroder Casings |
| Others |
Value Network & Pricing Analysis
Undercapacity in European alginate substrate production is tightening supplier leverage and pushing casing manufacturers toward long-term offtake commitments with premium pricing tiers. This utilization squeeze cascades into buyer procurement strategies, forcing food processors to consolidate vendor panels or absorb pass-through cost adjustments from collagen and cellulose specialists.
Pricing Analysis
Volume-discount tiering structures separate national retail contract volumes from craft processor spot purchases, with three-tier pricing stratification across premium REACH-certified, standard FDA-notified, and economy non-certified grades. Price differentiation hinges on certification tier and geographic delivery cost, with EU Green Deal compliance premiums widening spreads. Cost compression in the economy tier is intensifying as Danish pork collagen input volatility transmits downstream. National retail chains show lowest price sensitivity due to specification-lock effects, while craft sausage startups face highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for cellulose substrate imports, compelling casing manufacturers to dual-source from Iberian and Southeast Asian production nodes. Geographic supply concentration centers on Germany, Spain, and the United States for finished casing output, with raw material dependencies spanning Danish pork intestines, Norwegian seaweed for alginate, and wood pulp from Scandinavian forestry operations. Single-source vulnerability in flavor-chemist talent pools amplifies disruption risk. Distribution runs through direct-supply agreements with food manufacturers, bypassing traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards specialized expertise in fat-soluble spice migration modeling and regulatory dossier preparation, assets concentrated among a shrinking cohort of German technical universities and retired industry veterans. This capability scarcity creates durable competitive moats for incumbents while raising entry barriers for newcomers lacking captive R&D infrastructure.
For Market Incumbents: Harden regulatory dossier velocity through in-house EFSA and FDA notification teams, insulating product pipelines from extended safety assessment timelines. Deepen backward integration into alginate sourcing from Norwegian seaweed cooperatives to offset pork collagen volatility. Defend against cellulose substrate specialists by anchoring clean-label positioning through biodegradable formulation partnerships ahead of EU Green Deal packaging mandates. For New Entrants and Emerging Players: Pursue halal-certified export channels into Saudi Arabia and UAE foodservice sectors, where SAMR-aligned documentation requirements filter out incumbent competition lacking slaughter certification traceability. Target Middle Eastern supply white space through digital B2B platforms enabling real-time flavor customization for craft sausage startups. Penetrate via direct-to-processor relationships that bypass established distributor hierarchies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated substrate-flavor compounders with dedicated technical service capabilities and approved vendor status at national retail chains. Long-term viability favors specialists with captive alginate or cellulose R&D programs and REACH certification maintenance infrastructure. Watch for inflection signals in FDA food-contact notification backlogs, which stall product pipeline velocity and compress valuation multiples for seasoning-dependent casing suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Sourcing | Norwegian alginate supply anchors clean-label substrate production for EU Green Deal compliance. |
| Direct-to-Processor Digital Platform Launch | B2B ordering systems bypass broker networks and enable real-time flavor customization at reduced minimums. |
| Halal Certification Investment | SAMR-aligned documentation unlocks Saudi Arabia and UAE foodservice import channels. |
| Regulatory Dossier In-Housing | Captive EFSA and FDA notification teams compress product launch timelines versus outsourced preparation. |
| Biodegradable Substrate Partnership | Alginate and cellulose formulation alliances position suppliers for EU packaging sustainability mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact substance notifications, EFSA flavoring regulation protocols, customs trade data, and SEC filings from publicly traded casing manufacturers. Primary interviews engaged flavor chemists at German technical universities, procurement directors at Bavarian sausage processors, regulatory affairs leads at cellulose substrate specialists, and technical service managers at alginate casing producers. Bottom-up demand modeling from food manufacturer procurement patterns triangulates against top-down supply-side capacity assessments across Iberian and Central European production facilities.
Forecast inputs incorporate substrate chemistry segmentation, thermal processing application requirements, and procurement channel migration patterns across the analysis window. The analytical framework models pork casing, vegetarian casing, beef casing, and chicken casing demand trajectories alongside sausage, meat snack, deli meat, and soup application splits. CAGRs derive from normalized historical shipment data and forward capacity expansion announcements. Industry-specific inputs include ECHA substance restriction timelines and USDA-inspected facility expansion plans in the Midwest meatpacking corridor.
Sensitivities concentrate around EFSA novel extract evaluation delays, Danish swine herd fluctuations, and FDA notification backlog durations. Forecasts embed assumptions regarding REACH compliance adoption rates and EU Green Deal packaging mandate enforcement timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Saffron Market
Spices and Seasonings
South America Spice and Herb Extracts Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Chef Bases Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Thyme Extract Market