
 South America Spice and Herb Extracts Market | 2026-2036
South America Spice and Herb Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
South America Spice and Herb Extracts Market Analytics
Ingredient customization revenue is fragmenting across the South America spice and herb extracts value chain as brand owners internalize basic blending while outsourcing complex extraction. McCormick & Company, Inc. leverages its distribution density to control retail shelf placement in Brazilian metropolitan markets. Givaudan anchors premium fragrance and flavor accounts through captive botanical sourcing relationships in the Andean foothills. Indena S.p.A. specializes in pharmaceutical-grade standardization, navigating ANVISA's stringent purity protocols for active compound verification.
Spice and herb extracts comprise concentrated bioactive preparations obtained through solvent extraction, steam distillation, or supercritical CO2 processing, typically standardized to marker compounds such as piperine, curcumin, or eugenol for consistent functional performance. These extracts serve industrial formulators requiring precise dosing control, extended shelf stability, and reproducible sensory profiles in finished goods. Oils and liquid extracts command the dominant margin pools due to higher processing complexity and transportation economics, while powder formats compete aggressively in nutraceutical contract manufacturing where blend uniformity and flowability determine specification adherence. The organic form segment sustains premium positioning through certified supply chains, though conventional extraction still occupies volume leadership in commodity flavor applications.
ANVISA governs pharmaceutical and nutraceutical extract registrations through Resolution RDC 240/2018, while Brazil's Ministry of Agriculture (MAPA) oversees food-grade botanical safety under IN 15/2014; both frameworks intensify testing documentation burdens for imported raw materials. REACH-equivalent chemical safety obligations in Mercosur alignment discussions are forcing extractors to revalidate solvent residue methodologies ahead of potential regulatory convergence. Stakeholders must monitor pending bioaccessibility study requirements that could bifurcate the market between analytically verified premium suppliers and commodity traders lacking characterization capabilities.
Market Dynamics
ANVISA's evolving botanical ingredient standards are concentrating compliance capabilities among extractors with in-house analytical laboratories, fragmenting the supplier base between certified pharmaceutical-grade processors and commodity traders lacking characterization infrastructure.
Growth Catalysts
- Clean-label formulation mandates:Food additive manufacturers across Brazil's southeastern manufacturing corridor are substituting synthetic preservatives with standardized rosemary and oregano extracts to meet retailer clean-label requirements.
- Resolution RDC 240/2018:ANVISA's pharmaceutical-grade extract registration pathway is creating pull-through demand for analytically verified piperine and curcumin standardizations in nutraceutical contract manufacturing.
- Supercritical CO2 processing:Andean foothills extraction facilities are capturing premium margin pools by replacing solvent-based methods with solvent-free technologies for fragrance and flavor accounts.
Market Restraints
- Raw material import dependency:Brazilian extractors face testing documentation burdens under IN 15/2014 for imported botanical raw materials, elongating procurement cycles for Asian-sourced turmeric and ginger rhizomes.
- Solvent residue methodology revalidation:REACH-equivalent chemical safety obligations in pending Mercosur alignment discussions are forcing capital expenditure on gas chromatography equipment ahead of regulatory convergence.
- Synthetic flavor substitution:Commodity vanilla and citrus flavor applications are experiencing displacement by fermentation-derived alternatives in price-sensitive bakery and confectionery segments.
Strategic Opportunities
- Colombian Andean corridor expansion:Untapped quillaja and boldo extraction capacity in Colombia's highland regions offers captive botanical sourcing relationships for pharmaceutical standardization specialists.
- MAPA organic certification pathways:Brazil's Ministry of Agriculture expanding organic equivalency agreements with EU and US regulators is opening premium positioning for certified supply chain operators in export markets.
- Direct-to-flavor-house distribution:São Paulo-based procurement consortia are consolidating volumes to bypass traditional importer-distributor markups, compressing channel economics for mid-tier extractors.
Industry Challenges
- Marker compound analytical talent scarcity:HPLC and mass spectrometry technicians capable of curcuminoid and piperine quantification per ANVISA protocols command wage premiums that strain mid-cap extraction facilities.
- Batch-to-batch bioaccessibility variability:Pending bioaccessibility study requirements threaten to bifurcate the market between suppliers with clinical validation capabilities and commodity traders lacking pharmacokinetic characterization infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Spice and Herb Extracts Market |
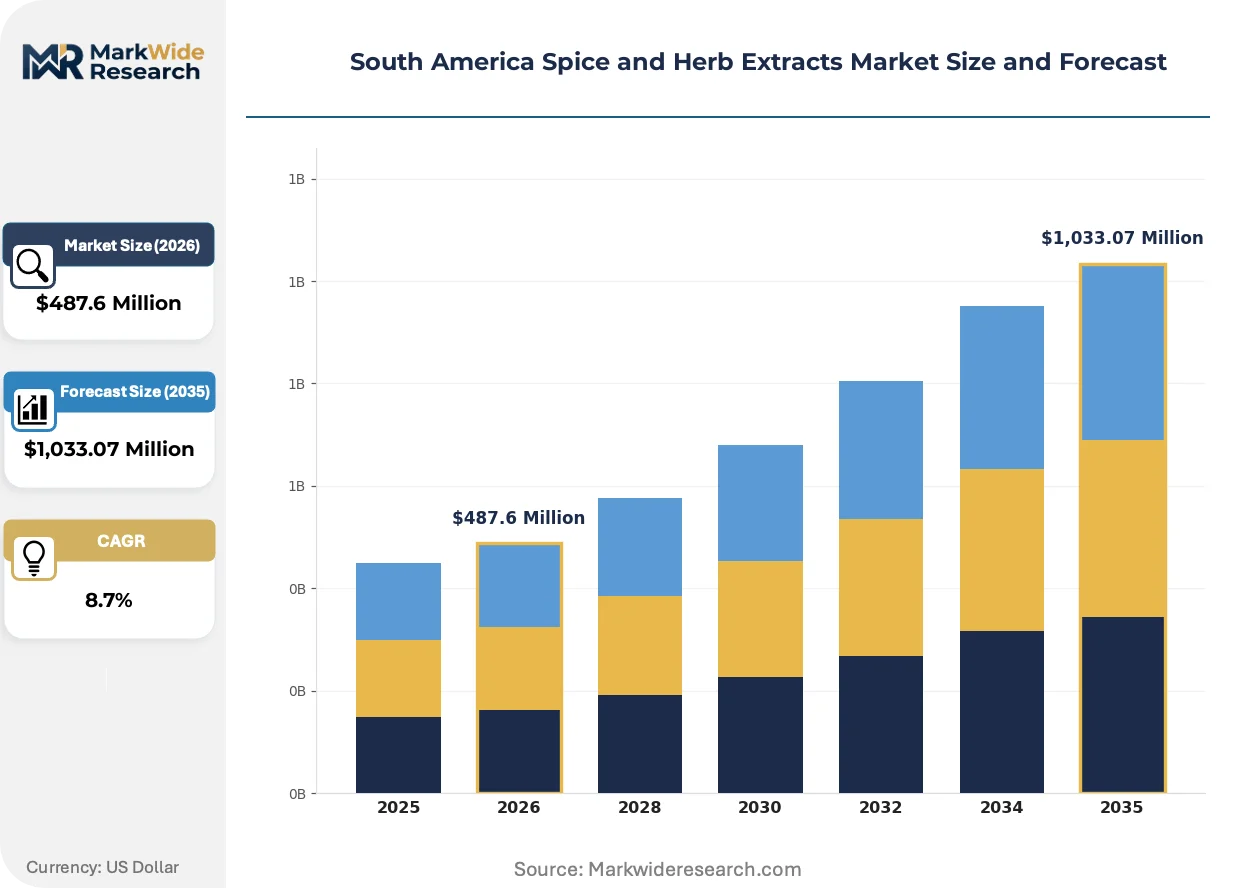
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Powders, Pastes, Liquid Extracts Application: Food Additives, Cosmetics, Nutraceuticals, Pharmaceuticals Form: Organic, Conventional, Freeze-Dried, Dehydrated Delivery Mode: Bottled, Sachets, Bulk, Spray |
| Companies Covered | Döhler GmbH, Firmenich, Givaudan, Merck KGaA, Synthite Industries Ltd, McCormick & Company, Inc., Naturex SA, Indena S.p.A., Plantextrakt GmbH & Co. KG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Spice and Herb Extracts Market Evolving Landscape
Extraction technology convergence with pharmaceutical-grade analytical standards is collapsing traditional boundaries between food, fragrance, and nutraceutical supply chains across the Andean foothills and Brazilian manufacturing corridors.
Supercritical CO2 extraction systems with integrated inline spectroscopic monitoring are collapsing the historical separation between processing and quality verification stages. São Paulo-based flavor houses are adopting these integrated platforms to compress batch release timelines from weeks to days. The technology is collapsing margin structures for standalone toll processors lacking captive analytical capabilities.
ANVISA's pending bioaccessibility study requirements for botanical extract registrations are compressing the supplier base toward vertically integrated operators with clinical research partnerships. Pharmaceutical-grade standardization specialists are investing in dissolution testing infrastructure to preempt compliance deadlines. Nutraceutical contract manufacturers in Brazil's southeastern corridor face the steepest adaptation costs.
Brand owners are internalizing basic dry blending operations while outsourcing complex extraction to Andean foothills processors with captive organic certification. Procurement patterns are consolidating around São Paulo-based flavor houses with direct sourcing relationships, displacing traditional importer-distributor networks. Argentine pharmaceutical formulators exhibit the most aggressive backward integration into extraction capabilities.
South America Spice and Herb Extracts Market Segmentation
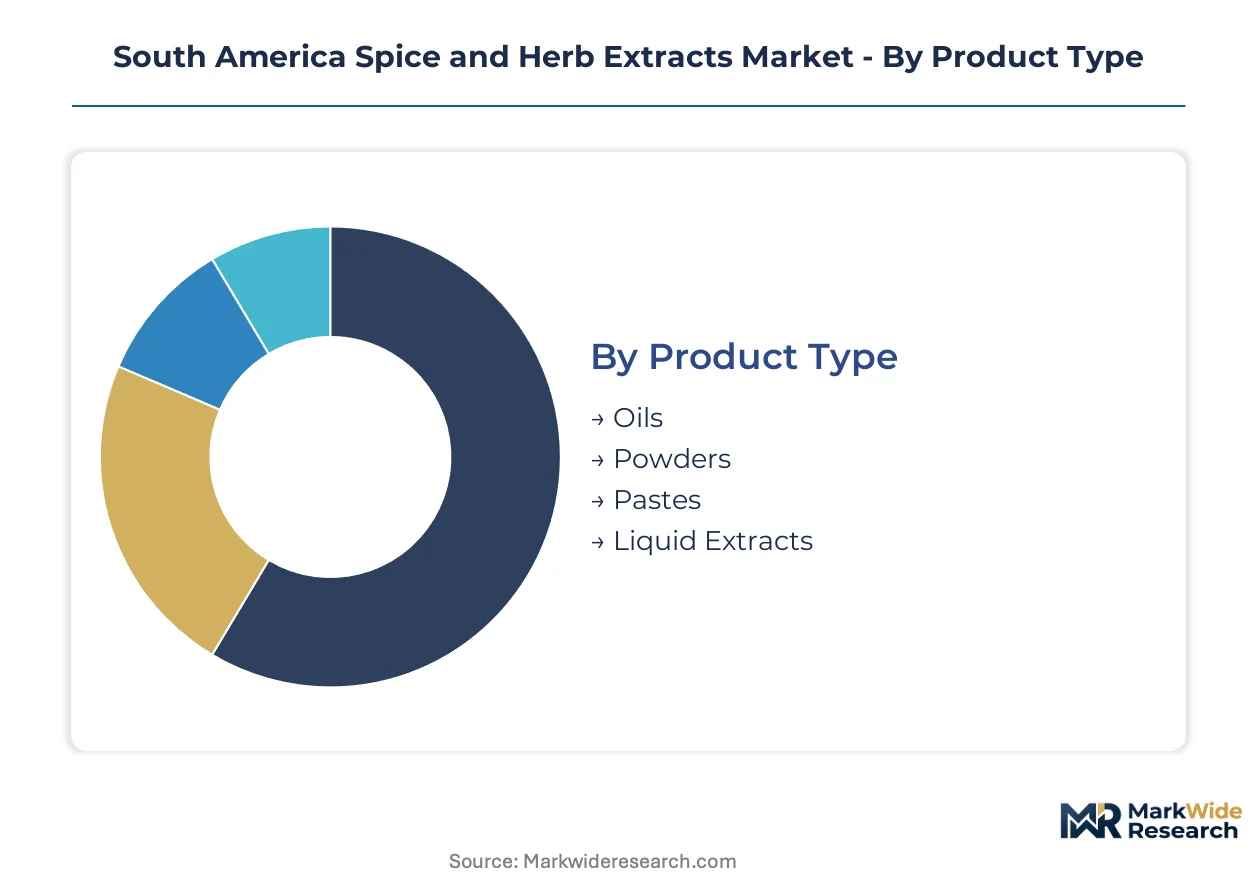
Segmentation in the South America spice and herb extracts market reveals divergent margin structures and regulatory exposure across product formats and end-use channels. Procurement patterns in Brazil's southeastern corridor favor suppliers capable of navigating ANVISA's pharmaceutical-grade protocols while maintaining food-grade MAPA compliance.
Product Type:
Oils and liquid extracts turn inventory fastest in São Paulo-based flavor house procurement cycles, while powder formats sit longer in nutraceutical contract manufacturing queues awaiting blend uniformity verification.
- Oils:Concentrated lipophilic preparations standardized to volatile compound profiles, typically delivered in drum or tote configurations for industrial formulators. São Paulo metropolitan flavor houses anchor procurement volumes for premium fragrance and flavor accounts requiring extended shelf stability.
- Liquid Extracts:Hydroalcoholic or glyceritic solutions with defined marker compound concentrations, favored for precise dosing control in beverage and sauce applications. Brazil's southeastern manufacturing corridor concentrates demand for clean-label rosemary and oregano liquid preparations replacing synthetic preservatives.
- Powders:Spray-dried or carrier-bound formats optimized for blend uniformity in nutraceutical tableting operations.
- Pastes:High-viscosity concentrates serving ethnic food manufacturers and artisanal bakery segments.
Oils anchor the volume base while liquid extracts gain share at the steepest rate.
Application:
Food additive manufacturers command the shortest procurement cycles, while pharmaceutical registrations under ANVISA Resolution RDC 240/2018 elongate validation timelines for nutraceutical and drug-grade suppliers.
- Food Additives:Standardized extracts for flavor enhancement, color stabilization, and natural preservation in processed foods. Brazil's southeastern manufacturing corridor drives substitution of synthetic additives with rosemary and oregano extracts meeting retailer clean-label mandates.
- Pharmaceuticals:Active pharmaceutical ingredients and excipients requiring ANVISA-verified purity protocols and marker compound quantification. Indena S.p.A. and comparable specialists navigate stringent HPLC and mass spectrometry documentation burdens for piperine and curcumin standardizations.
- Nutraceuticals:Dietary supplement ingredients facing pending bioaccessibility study requirements that threaten to bifurcate the supplier base.
- Cosmetics:Fragrance and functional botanicals for personal care formulations, with Andean foothills extraction facilities capturing premium positioning through supercritical CO2 processing.
Food additives generate the highest throughput velocity while pharmaceuticals command the steepest margin expansion trajectory.
Form:
Conventional extraction occupies volume leadership with compressed production cycles, while organic certification introduces procurement elongation through supply chain traceability documentation.
- Conventional:Solvent-extracted or steam-distilled preparations from non-certified agricultural sources, dominating commodity flavor applications where price sensitivity prevails. Brazilian extractors leverage conventional sourcing for vanilla and citrus substitutes facing fermentation-derived displacement pressure.
- Organic:Certified supply chain preparations meeting MAPA equivalency agreements with EU and US regulators for export market access. Premium positioning sustains through São Paulo-based procurement consortia consolidating volumes for certified rosemary, oregano, and turmeric extracts.
- Freeze-Dried:Low-temperature dehydration preserving volatile aromatic profiles for premium culinary applications.
- Dehydrated:Conventional thermal drying for cost-sensitive industrial ingredient markets.
Conventional forms anchor procurement volumes while organic certification captures the steepest pricing premium expansion.
Delivery Mode:
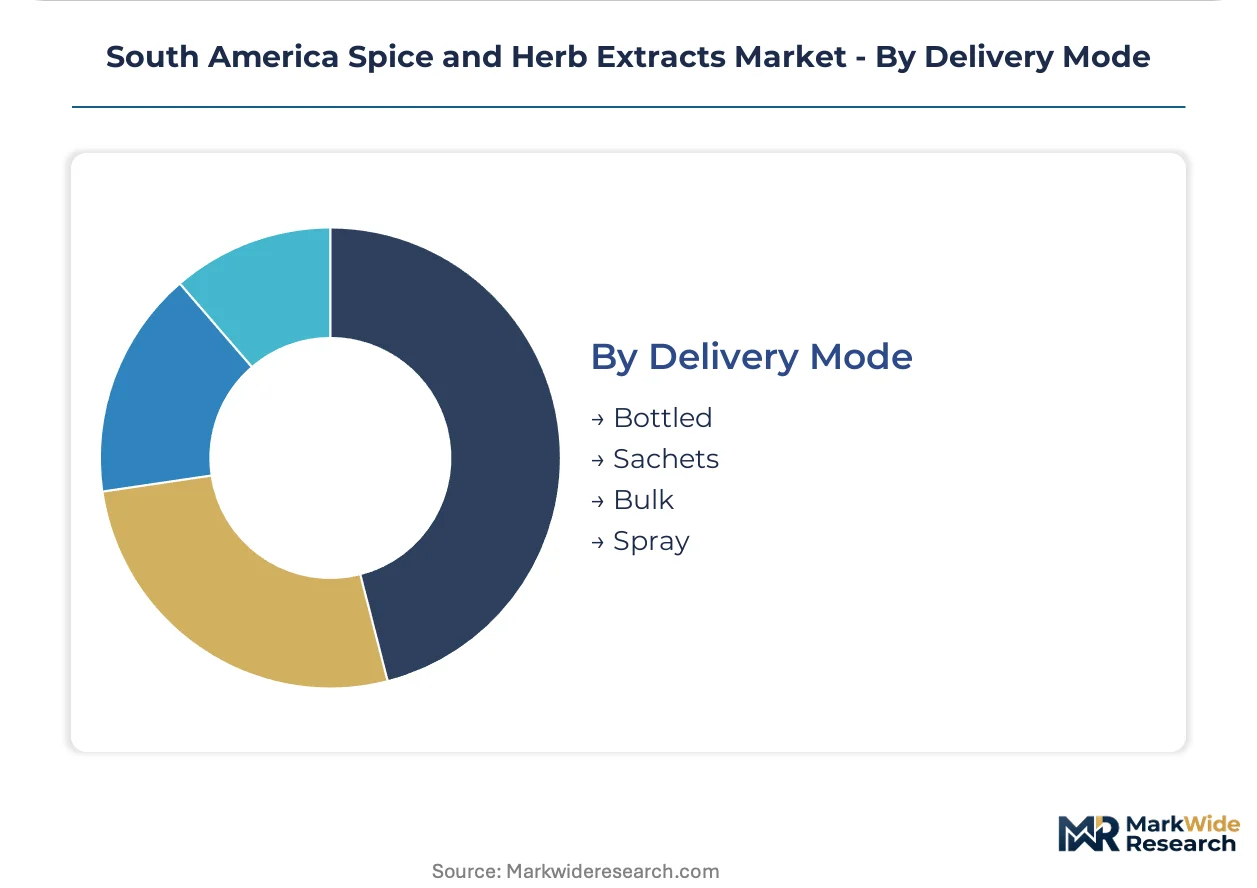
Bulk shipments dominate manufacturing corridor procurement with minimal handling overhead, while bottled and sachet formats introduce packaging cycle complexity for retail-facing distribution.
- Bulk:Drum, tote, and tanker configurations for industrial formulators requiring high-volume, low-unit-cost inputs. São Paulo-based flavor houses and pharmaceutical contract manufacturers consolidate bulk procurement to bypass traditional importer-distributor markups.
- Bottled:Retail and foodservice packaging for culinary herb oils and specialty extracts.
- Sachets:Single-serve portions for hospitality and institutional foodservice channels.
- Spray:Aerosolized delivery systems for topical cosmetic and culinary applications.
Bulk delivery commands procurement volume leadership while spray formats expand most quickly in cosmetic application segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil absorbs the majority of South American extract volumes for food additive and pharmaceutical applications, while Colombia and Argentina concentrate on premium fragrance and cosmetic-grade botanical sourcing with distinct processing capabilities.
Brazil
São Paulo-based flavor houses anchor procurement volumes for rosemary and oregano extracts displacing synthetic preservatives. ANVISA's Resolution RDC 240/2018 mandates HPLC-verified marker compound documentation for pharmaceutical-grade registrations. The southeastern manufacturing corridor concentrates extraction demand from nutraceutical contract manufacturers facing pending bioaccessibility study requirements.
Colombia
Andean foothills extraction facilities capture premium margin pools through supercritical CO2 processing for fragrance and flavor accounts. The national pharmaceutical regulator governs botanical ingredient safety standards for export-oriented cosmetic applications. Highland regions around Bogotá sustain captive quillaja and boldo sourcing relationships for pharmaceutical standardization specialists.
Argentina
Pharmaceutical formulators exhibit aggressive backward integration into extraction capabilities for curcumin and piperine standardizations. The country's national food safety authority oversees IN 15/2014-equivalent documentation for imported raw materials. Buenos Aires and Córdoba anchor the pharmaceutical-grade supplier base navigating Mercosur alignment discussions on chemical safety obligations.
Chile
Cosmetic manufacturers drive demand for solvent-free botanical extracts in premium personal care formulations. The national health regulator enforces purity protocols for active compound verification in export markets. Santiago-based procurement consortia consolidate volumes to bypass traditional importer-distributor markups for Andean-sourced materials.
Peru
Organic certification pathways through MAPA-equivalent agreements sustain premium positioning for certified turmeric and ginger extracts in EU and US export markets. The Ministry of Agriculture oversees supply chain traceability documentation elongating procurement cycles. Lima anchors processing infrastructure for Asian-sourced rhizome re-exportation to Brazilian manufacturing corridors.
South America Spice and Herb Extracts Market Competitive Landscape
Capability concentration sits with pharmaceutical-grade standardization specialists; scale advantage sits with flavor and fragrance houses with captive distribution density. The supplier base fragments between certified processors with in-house analytical laboratories and commodity traders lacking characterization infrastructure. Three archetypes dominate: multinational flavor houses controlling retail shelf placement, pharmaceutical-grade specialists navigating ANVISA purity protocols, and Andean foothills processors with organic certification. Competitive moves center on direct-to-flavor-house distribution consolidation and supercritical CO2 capacity expansion.
Among Swiss-origin flavor and fragrance conglomerates, Givaudan exemplifies the premium-tier archetype through Andean foothills captive sourcing relationships. McCormick & Company, Inc. occupies a position representing distribution-density scale players controlling Brazilian metropolitan retail placement. Indena S.p.A. sits within the pharmaceutical-grade standardization tier, navigating ANVISA's stringent HPLC and mass spectrometry documentation burdens for marker compound verification.
| Leading Market Players |
|---|
| Döhler GmbH |
| Firmenich |
| Givaudan |
| Merck KGaA |
| Synthite Industries Ltd |
| McCormick & Company, Inc. |
| Naturex SA |
| Indena S.p.A. |
| Plantextrakt GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
ANVISA's pending bioaccessibility study requirements determine both the widening spread between pharmaceutical-grade and commodity pricing tiers and the consolidation of extraction capacity around São Paulo-based flavor houses with captive analytical infrastructure. Brazilian extractors absorbing testing documentation burdens under IN 15/2014 for Asian-sourced turmeric and ginger rhizomes face procurement cycle elongation that feeds back into premium pricing for verified supply chains.
Pricing Analysis
Long-term offtake contracts between São Paulo-based flavor houses and Andean foothills processors anchor pricing stability for organic-certified rosemary and oregano extracts, while spot market transactions dominate conventional vanilla and citrus substitutes facing fermentation-derived displacement. Price differentiation rests on ANVISA-verified purity protocols versus MAPA baseline compliance, with pharmaceutical-grade standardization commanding the widest premiums. Cost compression in commodity flavor tiers is intensifying because synthetic alternatives erode volume leverage. Nutraceutical contract manufacturers exhibit the sharpest price sensitivity due to pending bioaccessibility compliance investments, whereas fragrance houses with captive sourcing relationships show the least.
Supply Chain Analysis
Extended payment terms from São Paulo-based procurement consortia are squeezing mid-tier Andean foothills processors without integrated analytical capabilities, forcing supply-chain finance facility adoption to bridge working capital gaps. Raw material sourcing draws from Peru for organic turmeric and ginger, India for piperine-rich black pepper, and Colombia for quillaja and boldo. Single-source vulnerability concentrates around Asian rhizome dependencies subject to IN 15/2014 documentation burdens. Distribution runs through direct-to-flavor-house channels consolidating volumes to bypass traditional importer-distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America spice and herb extracts market functions as a service-attach opportunity where analytical verification services and regulatory compliance consulting expand faster than commodity extraction hardware sales. Recurring revenue from ANVISA registration support and marker compound testing protocols sustains margin expansion beyond batch processing fees.
For Market Incumbents: Entrench analytical service capabilities through in-house HPLC and mass spectrometry infrastructure to preempt bioaccessibility study compliance deadlines. Deepen captive sourcing relationships in Colombia's highland regions to secure quillaja and boldo supply chains against emerging pharmaceutical-grade competitors. Certification investment in MAPA organic equivalency agreements anchors export market access against regulatory fragmentation threats.
For New Entrants and Emerging Players: Establish a beachhead in Colombian Andean corridor extraction capacity where supercritical CO2 processing for cosmetic applications remains underdeveloped relative to Brazilian pharmaceutical corridors. Target pharmaceutical standardization specialists seeking captive botanical relationships outside São Paulo's saturated procurement networks. A go-to-market angle emphasizing solvent-free fragrance extraction for Chilean cosmetic manufacturers bypasses incumbent flavor house channel control.
For Investors and Strategic Acquirers: Pharmaceutical-grade standardization specialists with ANVISA-verified purity protocols and clinical research partnerships represent the most defensible acquisition archetype for long-term viability across the projection horizon. Monitor pending Mercosur REACH-equivalent alignment discussions as the critical inflection signal distinguishing vertically integrated operators from commodity traders facing forced solvent residue methodology revalidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Andean foothills processors capture premium cosmetic margins through solvent-free extraction technologies. |
| ANVISA Registration Pathway Investment | Pharmaceutical-grade specialists preempt bioaccessibility compliance deadlines with dissolution testing infrastructure. |
| Direct-to-Flavor-House Distribution Consolidation | São Paulo procurement consortia compress channel economics by bypassing importer-distributor markups. |
| MAPA Organic Certification Pathway Development | Brazilian extractors leverage EU and US equivalency agreements for export market premium positioning. |
| Captive Andean Botanical Sourcing | Colombian highland quillaja and boldo relationships secure supply for pharmaceutical standardization demand. |
Research Methodology
Cross-validation between primary interviews with extraction facility managers, ANVISA regulatory consultants, São Paulo-based flavor house procurement directors, and nutraceutical contract manufacturing executives anchors the qualitative findings against secondary validation from ANVISA Resolution RDC 240/2018 filings, MAPA IN 15/2014 documentation requirements, Mercosur trade alignment position papers, and Andean foothills organic certification registries. Bottom-up volume triangulation from individual extractor capacity disclosures converges with top-down demand modeling across food additive, pharmaceutical, nutraceutical, and cosmetic application segments.
Calibration against historical price realization data for oils, liquid extracts, and powder formats across conventional and organic certification tiers informs the analytical framework across the analysis window. Segmentation dimensions span product type, application channel, form, and delivery mode, with regional regulatory cluster variations modeled separately. CAGRs derive from compound growth trajectory fitting to validated endpoint estimates, incorporating supercritical CO2 processing adoption curves and synthetic flavor substitution elasticities as industry-specific forecast inputs.
Sensitivities concentrate around ANVISA bioaccessibility study implementation timing, Mercosur REACH-equivalent chemical safety obligation convergence, and MAPA organic equivalency agreement expansion. Forecasts reflect documented assumptions regarding clean-label formulation mandate penetration and fermentation-derived flavor substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Dill Oil Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Spice Oils and Oleoresins Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Onion Essential Oil Market