
 Asia-Pacific Fintech Market | 2026-2036
Asia-Pacific Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fintech Market Outlook
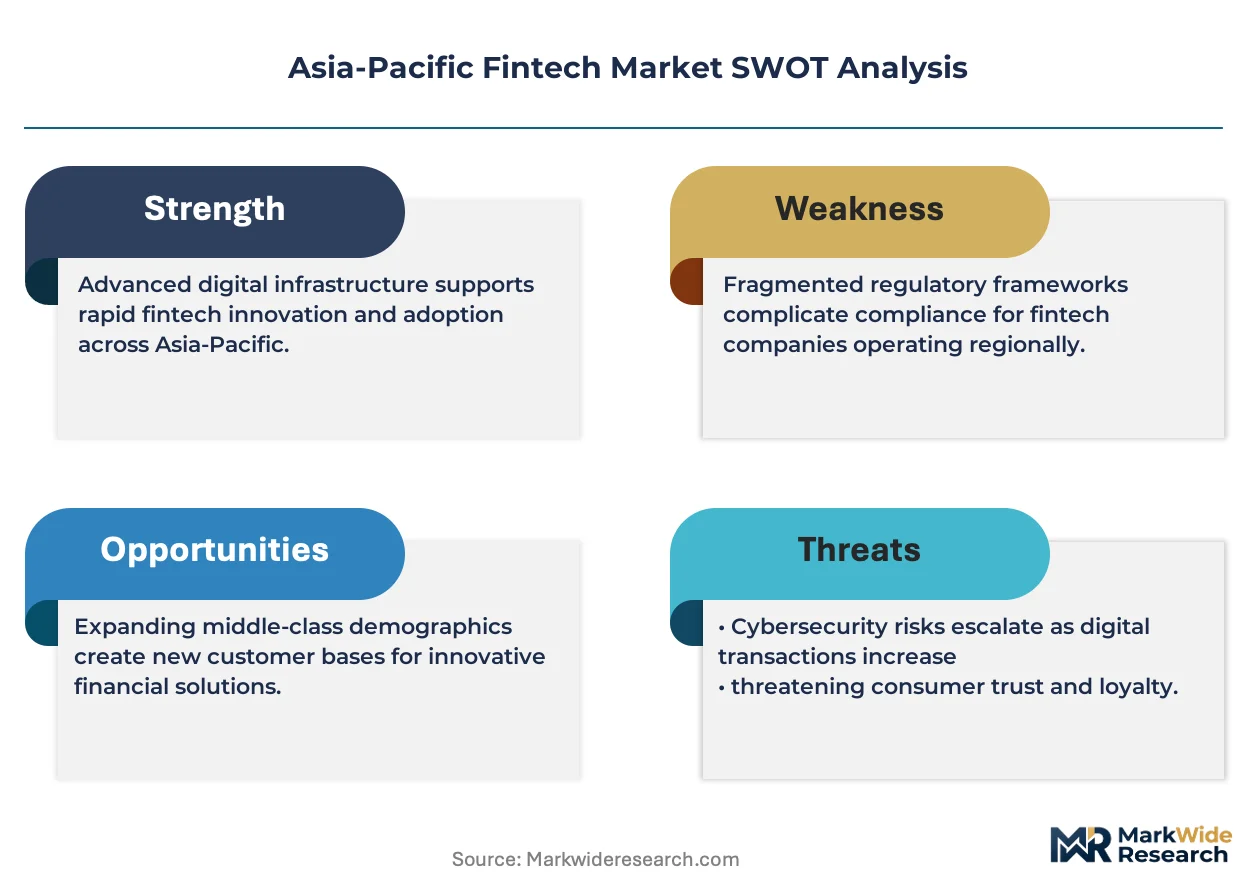
Enterprise-grade API reliability standards are redrawing competitive boundaries in Asia-Pacific fintech. Airwallex leverages cross-border payment infrastructure to anchor its position among regional e-commerce sellers. DBS Bank sustains dominance through in-house blockchain settlement rails that reduce correspondent banking friction. Grab competes by embedding financial services within its super-app ecosystem across Singapore, Indonesia, and Vietnam.
Asia-Pacific fintech encompasses technology-enabled financial services delivered through software platforms, typically operating on cloud-native architectures with sub-second transaction processing latency and multi-layer encryption protocols, designed to disintermediate traditional banking intermediaries and reduce customer acquisition costs. Online payments and digital banking capture the largest transaction volume pools, while blockchain and AI segments attract disproportionate R&D allocation as margin pressure intensifies in commoditized lending. Mobile apps remain the dominant delivery channel, though API integration grows fastest as embedded finance partnerships proliferate among non-financial platforms.
India's RBI mandates multi-factor authentication for digital payments, while Australia's ACCC enforces open banking data-sharing standards that compel incumbent banks to expose customer transaction histories. Singapore's MAS licensing framework for digital banks shapes market access by requiring minimum capital buffers and operational resilience audits. Stakeholders must monitor regulatory divergence across APAC jurisdictions as cross-border service expansion triggers compliance fragmentation that favors regionally diversified operators over single-market specialists.
Market Dynamics
Real-time payment infrastructure deployment across Asia-Pacific is compressing transaction settlement windows from T+2 to sub-second, forcing incumbent banks to rebuild core banking systems around cloud-native architectures or cede retail payment flows to non-bank platforms.
Growth Catalysts
- India's UPI protocol:The Unified Payments Interface mandates interoperable QR codes and instant fund transfers, creating network effects that pull unbanked rural populations into formal financial channels.
- Smartphone penetration curves:Indonesia and Vietnam now exceed 75% mobile ownership, enabling mobile-first neobanks to bypass physical branch buildout entirely.
- Open banking frameworks:Australia's Consumer Data Right compels the four major banks to expose transaction histories via standardized APIs, accelerating third-party fintech product development.
Market Restraints
- Cross-border compliance fragmentation:Singapore's MAS licensing requirements diverge sharply from Indonesia's OJK capital buffers, raising operational costs for regional expansion.
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud dominate data center capacity across Southeast Asia, creating single-point-of-failure risks for payment system uptime.
- Legacy core banking technical debt:Australian and Japanese incumbents run COBOL-based settlement systems that resist API integration, delaying real-time product launches.
Strategic Opportunities
- Rural Philippines financial access:Palawan and Mindanao provinces show sub-30% formal credit penetration, creating white space for agent-based digital lending networks.
- Embedded finance convergence:Ride-hailing and e-commerce platforms in Vietnam and Thailand are integrating buy-now-pay-later APIs directly into checkout flows.
- India's RBI sandbox:The regulatory sandbox permits controlled testing of blockchain-based trade finance instruments, lowering compliance risk for pilot deployments.
Industry Challenges
- Cloud-native engineering talent scarcity:Kubernetes and distributed systems expertise concentrates in Singapore and Bangalore, leaving Jakarta and Manila operations dependent on expensive contractor markets.
- Multi-jurisdiction audit complexity:Digital banks operating across ASEAN must satisfy divergent operational resilience standards from MAS, OJK, and Bank Negara Malaysia simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fintech Market |
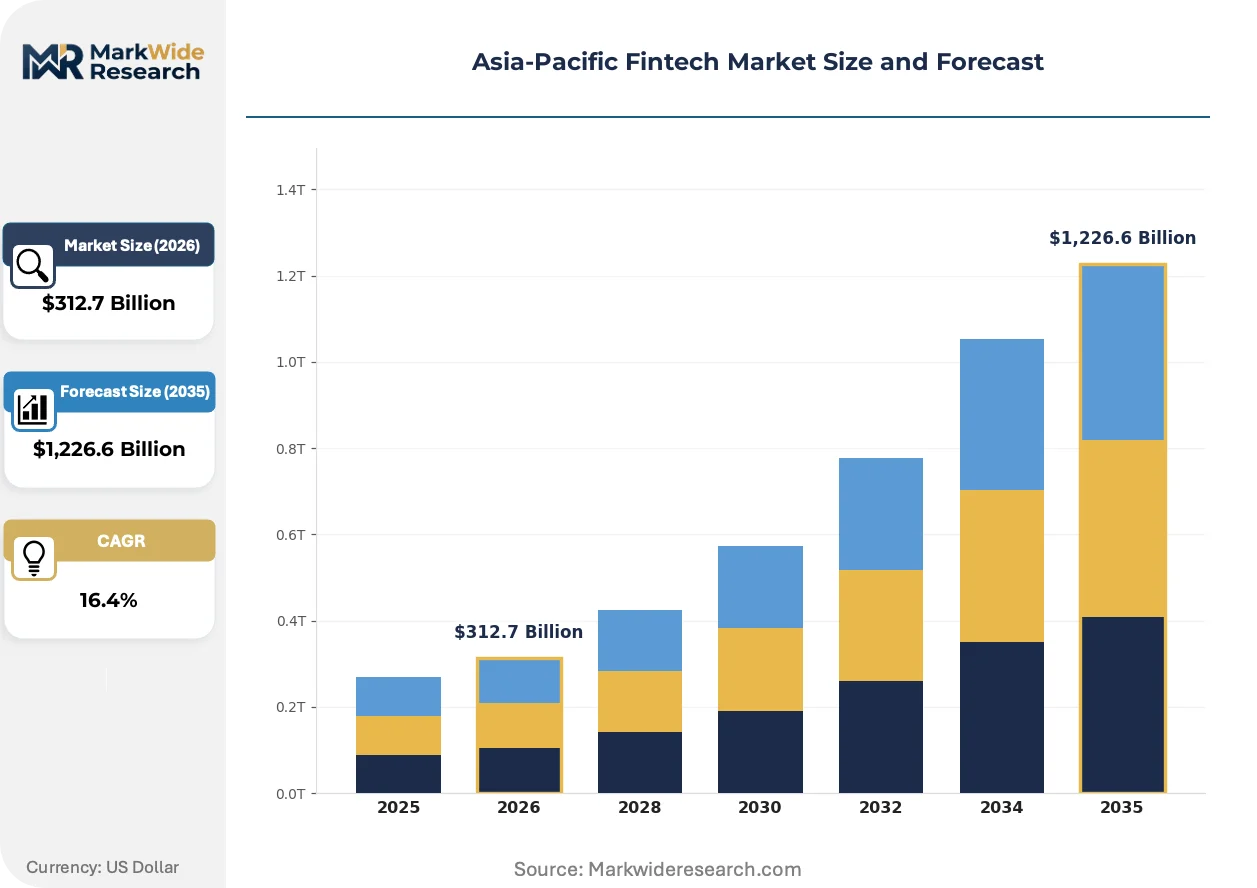
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,226.6 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Online Payments, Lending, Digital Banking, Investment Services Client Type: Individuals, Small Businesses, Corporates, Financial Institutions Technology: Blockchain, AI, Big Data Analytics, Machine Learning Delivery Model: Mobile Apps, Web Platforms, API Integration, SaaS |
| Companies Covered | Airwallex, Aspire, DBS Bank, Bambu, Osome, Commonwealth Bank, Nium, Validus, Grab, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fintech Market Strategic Shifts
Payment infrastructure is fragmenting from monolithic banking cores into modular, API-first service layers that allow non-financial platforms to embed lending, insurance, and wealth management without building captive financial institutions.
Edge computing nodes for transaction processing are miniaturizing into smartphone-integrated secure elements and merchant QR terminals. Indonesian and Vietnamese payment aggregators are deploying these localized processing units to reduce round-trip latency to centralized cloud data centers. This architecture is miniaturizing the physical and temporal footprint of payment authentication, enabling offline-capable transactions in connectivity-poor rural corridors.
Singapore's MAS digital bank licensing framework now mandates operational resilience audits and minimum capital buffers that exceed traditional bank requirements. This regulatory tightening is raising barriers to market entry and forcing applicant consortia to demonstrate multi-year funding commitments before authorization. Neobank hopefuls in Malaysia and Thailand are studying Singapore's precedent to anticipate their own regulator demands.
SMEs across Southeast Asia are unbundling financial services procurement from single banking relationships, instead assembling best-of-breed solutions from specialized providers. Cross-border payment APIs from fintech vendors are displacing correspondent banking relationships for import-export financing. This pattern is most pronounced among Vietnamese manufacturing exporters and Philippine business process outsourcing firms managing multi-currency payrolls.
Asia-Pacific Fintech Market Segmentation
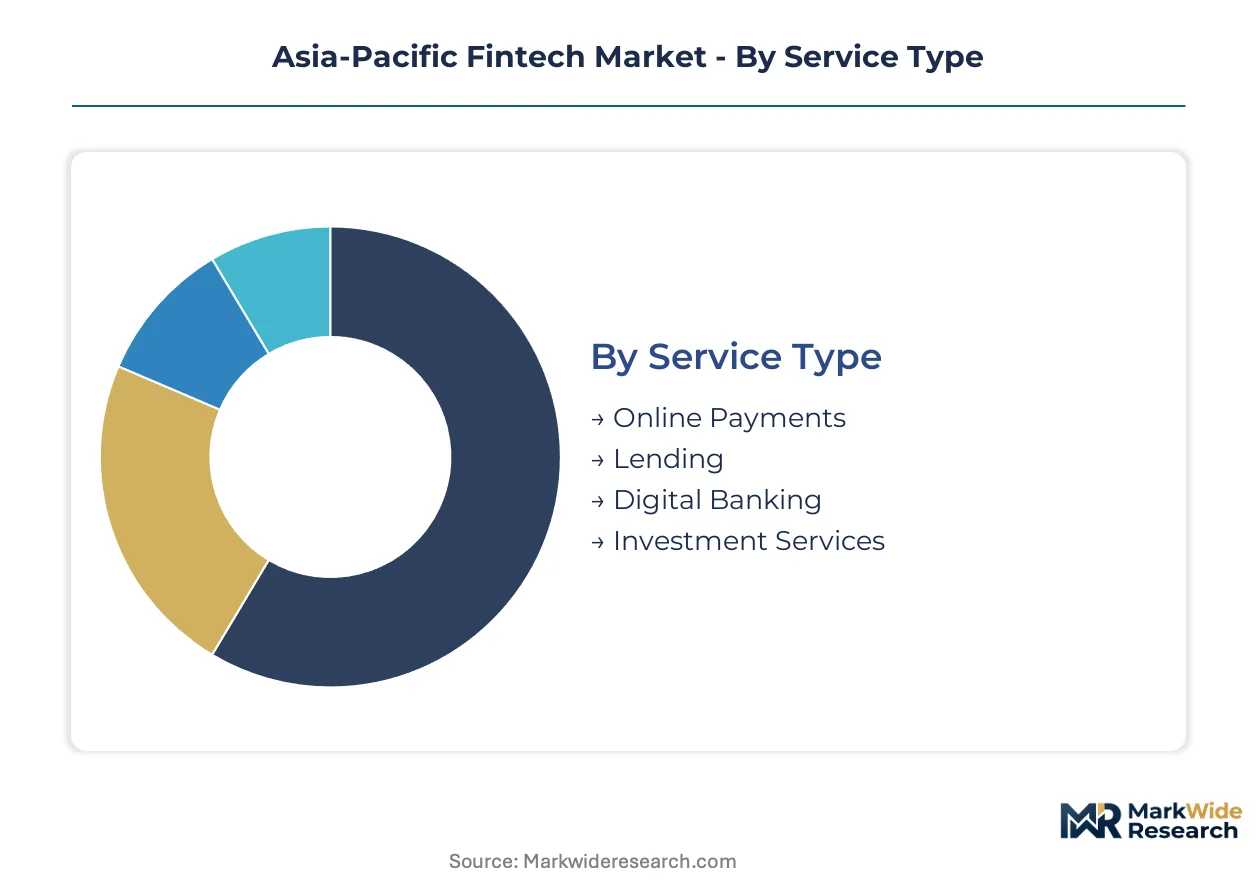
Segmentation reveals how fintech value pools concentrate across service architectures and customer interfaces in Asia-Pacific. Each dimension exposes distinct competitive moats, from regulatory licensing requirements to cloud infrastructure dependencies.
Service Type:
Domestic transaction volume concentrates in payments and lending, while cross-border flows drive investment services expansion.
- Online Payments:Real-time settlement protocols process transactions through interoperable QR networks. India's UPI rails and Singapore's PayNow anchor regional volume, with merchant acquisition costs falling below traditional card networks.
- Lending:Alternative credit scoring models deploy machine learning on non-traditional data streams. Digital platforms displace informal moneylenders across Indonesia's archipelago and Philippine rural corridors where formal credit penetration lags.
- Digital Banking:Neobanks operate on cloud-native cores with API-first architectures. MAS licensing in Singapore and RBI digital bank guidelines in India shape capital and operational requirements.
- Investment Services:Robo-advisory and fractional trading platforms aggregate retail wealth. Australia's superannuation reform creates structural demand for low-cost portfolio management tools.
Online Payments commands the established base. The steepest expansion runs through Lending.
Client Type:
Revenue per user varies fourfold across the client pyramid, with infrastructure economics favoring platform scale over bespoke service.
- Individuals:Smartphone-native consumers access financial services through super-app ecosystems. Grab, Gojek, and Paytm bundle payments, credit, and insurance into single interfaces.
- Small Businesses:Merchant payment acceptance and working capital credit dominate demand. Vietnamese manufacturing SMEs and Philippine BPO firms adopt cross-border payment APIs for multi-currency operations.
- Corporates:Treasury management and trade finance digitization accelerate. Blockchain-based letter-of-credit instruments reduce documentary friction in intra-Asia supply chains.
- Financial Institutions:Incumbent banks procure white-label technology stacks. Core banking modernization and open banking API deployment drive procurement decisions.
Individuals anchor volume scale. Corporates deliver the fastest margin expansion.
Technology:
R&D allocation skews toward AI and blockchain, though operational infrastructure depends on mature analytics stacks.
- Blockchain:Distributed ledger infrastructure supports trade finance and cross-border settlement. Consortia in Singapore and Hong Kong pilot tokenized securities and central bank digital currency interoperability.
- AI:Natural language processing powers customer service automation and fraud detection. Credit underwriting models ingest alternative data from e-commerce and telco behavior patterns.
- Big Data Analytics:Transaction pattern analysis enables merchant cash flow forecasting and targeted product recommendations. Real-time data pipelines process petabyte-scale payment streams.
- Machine Learning:Predictive models optimize payment routing and liquidity management. Dynamic fraud scoring reduces false-positive rates below rule-based systems.
Big Data Analytics underpins current operations. Blockchain attracts the most venture deployment.
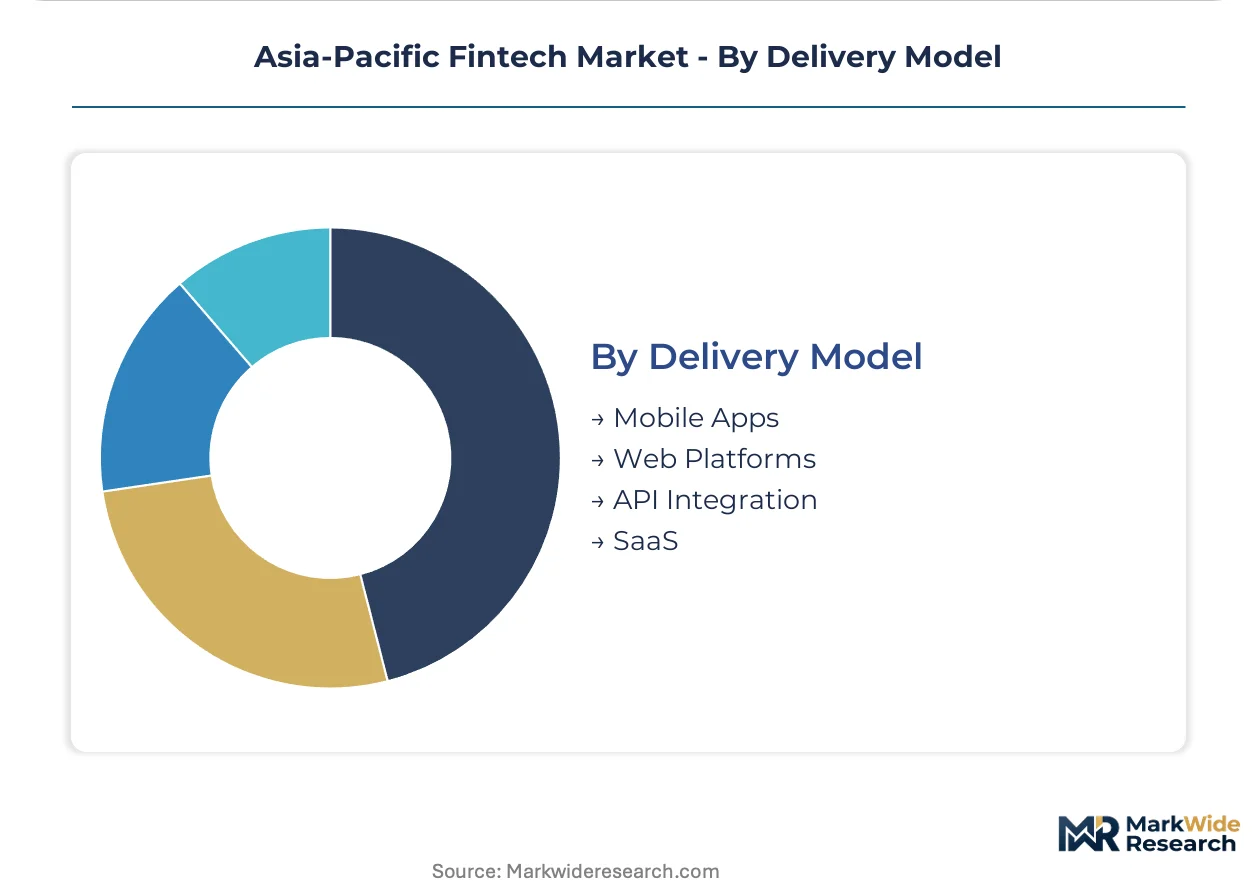
Delivery Model:
Channel strategy determines customer acquisition economics and regulatory exposure across the region.
- Mobile Apps:Native iOS and Android applications dominate consumer-facing distribution. Indonesia and Vietnam exceed 75% smartphone penetration, enabling branchless banking scale.
- Web Platforms:Browser-based access serves corporate treasury users and wealth management clients. Desktop interfaces support complex multi-account workflows.
- API Integration:Embedded finance partnerships allow non-financial platforms to offer banking services. Ride-hailing and e-commerce checkout flows integrate lending and insurance products.
- SaaS:Cloud-delivered software enables financial institutions to modernize without core replacement. Subscription models reduce capital expenditure barriers for regional banks.
Mobile Apps capture consumer engagement. API Integration is climbing the fastest as embedded finance proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border payment flows and digital financial services exports now exceed traditional banking corridors across Asia-Pacific. Import-dependent economies leverage fintech infrastructure to reduce correspondent banking costs, while export-oriented manufacturing hubs adopt embedded finance for supply chain liquidity. The region's regulatory divergence creates compliance arbitrage opportunities for multi-jurisdiction operators.
India
Rural financial inclusion programs and smartphone penetration drive mobile-first banking adoption across tier-2 and tier-3 cities. The Reserve Bank of India's digital bank licensing guidelines mandate minimum capital buffers and operational resilience audits. Mumbai and Bangalore anchor fintech development clusters, with payment infrastructure startups concentrated in the National Capital Region around Delhi.
Singapore
Wealth management digitization and institutional trading infrastructure attract regional headquarters placement from global platforms. The Monetary Authority of Singapore's digital bank licensing framework exceeds traditional bank requirements for operational resilience. The Marina Bay financial district hosts blockchain consortia and central bank digital currency pilot programs.
Australia
Open banking data-sharing mandates and superannuation reform create structural demand for low-cost portfolio management tools. The Australian Competition and Consumer Commission enforces Consumer Data Right standards compelling major banks to expose transaction histories via standardized APIs. Sydney and Melbourne fintech clusters specialize in robo-advisory and fractional trading platform development.
Indonesia
Archipelago logistics and unbanked population segments drive agent-based digital lending network expansion. The Financial Services Authority (OJK) capital buffer requirements diverge from Singapore's MAS framework, raising operational costs for regional expansion. Jakarta anchors payment aggregator development, while Surabaya and Medan host merchant acquisition scale operations.
Vietnam
Manufacturing export financing and multi-currency payroll management accelerate cross-border payment API adoption. The State Bank of Vietnam's regulatory sandbox permits controlled testing of blockchain-based trade finance instruments. Ho Chi Minh City concentrates e-commerce embedded finance development, while Hanoi hosts government-backed digital payment infrastructure pilots.
Asia-Pacific Fintech Market Competitive Environment
Concentration sits with diversified financial conglomerates and specialized payment infrastructure providers rather than single-product challengers. The competitive terrain splits between incumbent banks rebuilding core systems and neobanks launching on cloud-native architectures. Three archetypes dominate: super-app ecosystem bundlers, cross-border payment infrastructure specialists, and API-first embedded finance enablers. Regional expansion and strategic partnerships constitute the primary competitive moves, with M&A activity concentrated in payment aggregation and alternative lending capabilities.
Among Singapore-based operators, Nium and Aspire occupy positions within the cross-border payment infrastructure archetype, while Validus exemplifies the alternative lending specialist model. Australia's Commonwealth Bank represents incumbent bank digital transformation efforts. DBS Bank anchors the diversified financial conglomerate tier with in-house blockchain settlement capabilities. Airwallex sits within the payment infrastructure specialist category, serving regional e-commerce seller networks.
| Leading Market Players |
|---|
| Airwallex |
| Aspire |
| DBS Bank |
| Bambu |
| Osome |
| Commonwealth Bank |
| Nium |
| Validus |
| Grab |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation agreements with cloud infrastructure providers lock in compute access and cost predictability for fintech platforms scaling across ASEAN markets. These multi-year contracts tether pricing stability to data center availability in Singapore, Mumbai, and Sydney, while exposing operators to fixed-cost rigidity when transaction volumes fluctuate seasonally.
Pricing Analysis
Enterprise buyers anchor SaaS-tiered subscription models that stratify across premium API tiers, standard dashboard access, and economy self-serve portals. Pricing differentiation rests on transaction volume thresholds and ISO 27001 certification status, with premium tiers commanding substantial markups for dedicated infrastructure. Cost compression in economy segments is intensifying because neobanks compete aggressively on customer acquisition. Small merchants show highest price sensitivity, while multinational corporates prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Port congestion on the Singapore-Jakarta trade lane elevates inbound logistics costs for hardware security modules and point-of-sale terminal shipments. Cloud infrastructure concentrates in Singapore, India, and Australia, drawing from specialized semiconductor foundries in Taiwan and South Korea. Supply chain risk centers on AWS, Azure, and Google Cloud's dominant data center capacity across Southeast Asia, creating single-point-of-failure exposure for payment system continuity. Distribution runs through API-first platform partnerships and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific fintech represents a high-growth disruption propelled by India's UPI protocol and open banking mandates that compress settlement windows from days to seconds. Regulatory divergence across MAS, RBI, and OJK jurisdictions creates both compliance friction and arbitrage opportunities for agile operators.
For Market Incumbents: Fortify core banking modernization through cloud-native architecture migration and captive API development. DBS Bank's in-house blockchain settlement rails demonstrate how vertical integration into payment infrastructure neutralizes non-bank platform threats. MAS operational resilience audits demand multi-year funding commitments that favor balance-sheet strength over speed-to-market. For New Entrants and Emerging Players: Anchor in rural Philippines and Indonesian archipelago corridors where formal credit penetration lags below 30%. Agent-based digital lending networks and embedded finance partnerships with ride-hailing platforms offer the most penetrable white space. Direct API integration into e-commerce checkout flows bypasses customer acquisition cost barriers that plague standalone banking apps. For Investors and Strategic Acquirers: Capital is best deployed toward cross-border payment infrastructure specialists and alternative credit scoring platforms with proven unit economics in multiple ASEAN markets. Long-term viability hinges on regulatory licensing breadth rather than single-market dominance. Watch for RBI sandbox approvals and MAS digital bank authorizations as inflection signals for scalable compliance architecture.| Strategic Initiative | Industry Significance |
|---|---|
| Core Banking Modernization | Cloud-native architecture migration enables real-time settlement and API-first product deployment. |
| Cross-Border Payment Infrastructure Expansion | Multi-currency corridors reduce correspondent banking friction for Vietnamese manufacturing exporters. |
| Embedded Finance Partnership | Integration into Grab and Gojek super-apps captures smartphone-native consumer segments. |
| Regulatory Sandbox Participation | RBI and State Bank of Vietnam pilots lower compliance risk for blockchain trade finance instruments. |
| Alternative Credit Scoring Development | Machine learning on telco and e-commerce data displaces informal moneylenders in Indonesian rural corridors. |
Study Parameters
Desk research of regulatory filings from MAS, RBI, and OJK preceded structured interviews with neobank CTOs, payment platform engineers, and ASEAN fintech investors. Secondary validation drew from SEC 10-K disclosures, cloud provider capex reports, and UPI transaction volume dashboards. Bottom-up modeling of service-type segments triangulated against top-down macroeconomic projections across the analysis window.
Variance decomposition across service type, client type, technology stack, and delivery model shaped the quantitative framework. Deployment model segmentation captured mobile app, web platform, API integration, and SaaS channels. CAGRs derived from historical adoption curves and smartphone penetration trajectories, with India's UPI volume growth and Australia's open banking API call rates serving as anchor inputs.
Material uncertainties — regulatory licensing delays, cloud infrastructure concentration risk, and cross-border compliance fragmentation — sit outside the modeled envelope. Forecasts assume continued smartphone penetration curves and stable central bank digital currency pilot trajectories. Recalibration cycles align with material shifts in MAS licensing frameworks and RBI operational resilience mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Spend Management Platform Market
FinTech
Wealthtech Solutions Market
FinTech
IT Financial Management Tools Market
FinTech
Smart Lending Platform Market
FinTech
Fintech Crisis Management Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Netherlands AI in Fintech Market
FinTech
Latin America Fintech Market
FinTech
Russia AI in Fintech Market
FinTech
France AI in Fintech Market
FinTech
Asia-Pacific AI in Fintech Market
FinTech
Spain AI in Fintech Market
FinTech
Financial Fraud Detection Software Market
FinTech
Europe Financial Analytics Market
FinTech
United Kingdom AI in Fintech Market
FinTech
Global Cloud Financial Close Solutions Software Market