
 Change Control Management Software Market | 2026-2036
Change Control Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Change Control Management Software Market Outlook
Enterprise software distribution is rewriting how change control platforms reach regulated industries. MasterControl leverages direct field engineering teams to sustain deep relationships with pharmaceutical quality departments. SAP anchors its position through ERP integration capabilities that embed change workflows within broader enterprise systems. Oracle competes by extending cloud infrastructure scale across multi-site manufacturing deployments.
Change control management software comprises digital systems that enforce structured review, approval, and documentation protocols for modifications to validated processes, equipment specifications, or quality systems. These platforms maintain audit trails with timestamps, electronic signatures, and version control to satisfy regulatory inspection requirements. Cloud-based deployment leads expansion as biotechnology firms prioritize remote accessibility and reduced infrastructure overhead, while workflow automation functionality captures margin pools through configurable routing engines that replace manual paper-based approval chains. On-premises installations retain dominance in aerospace segments where air-gapped security mandates restrict external data transmission.
FDA 21 CFR Part 11 and EU Annex 11 shape product design by mandating electronic record integrity and signature authentication, forcing vendors to build compliant architectures from kernel level. EMA inspection guidance and ISO 9001 quality management standards further tighten validation documentation requirements across European and international markets. Stakeholders must monitor how FDA digital health software precertification pilots and evolving EU AI Act risk classifications reshape validation burden for algorithm-driven change prediction tools.
Market Dynamics
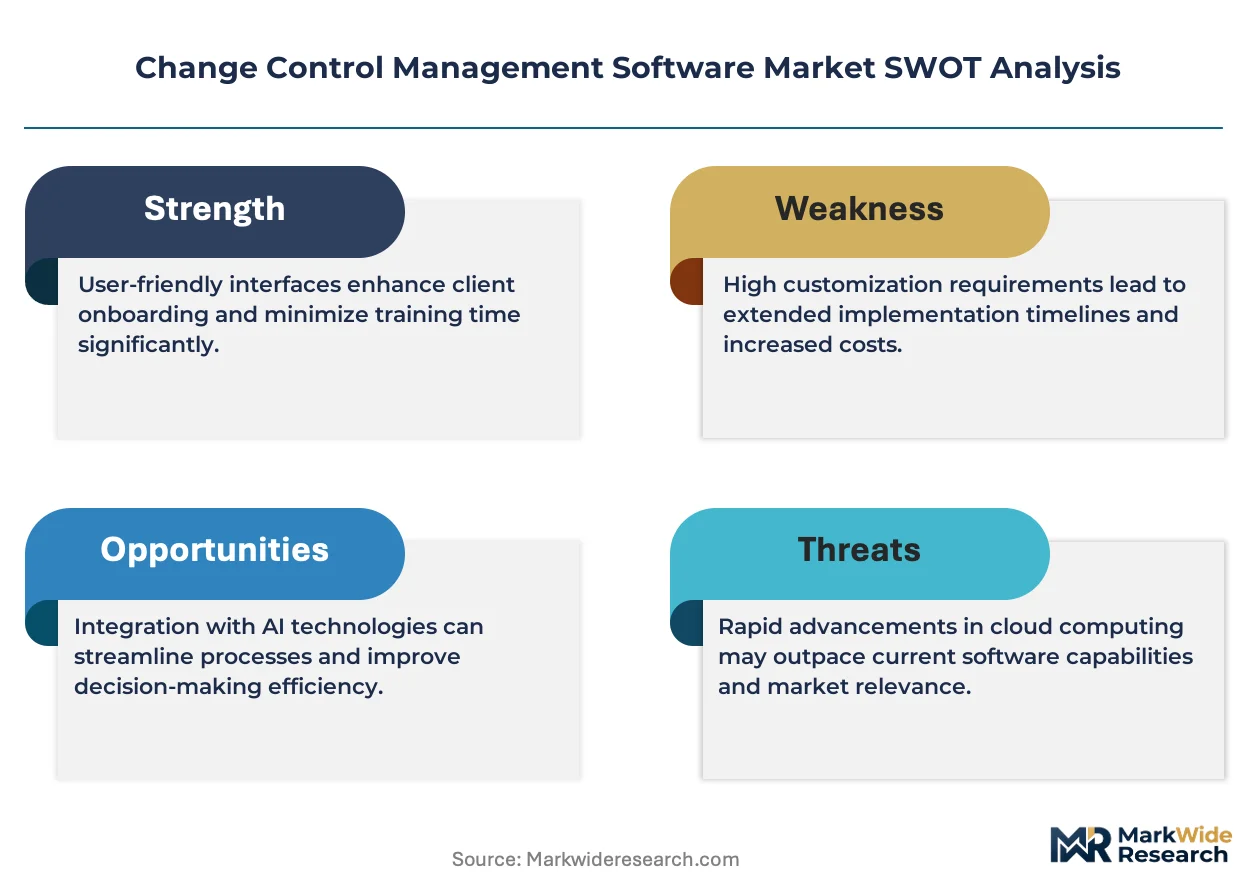
Cloud-native architecture is compressing deployment cycles from quarters to weeks across pharmaceutical quality operations, forcing incumbent vendors to rearchitect legacy codebases or cede mid-market share to agile challengers.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature mandates drive replacement of paper-based change records in US pharmaceutical manufacturing, creating mandatory upgrade cycles for quality management systems.
- Biotechnology workflow automation:Configurable routing engines eliminate manual handoffs between quality assurance and manufacturing departments, compressing approval timelines by half.
- German Mittelstand expansion:Mid-size life sciences firms in Baden-Württemberg and Bavaria prioritize SaaS deployments to avoid capital expenditure on validated data centers.
Market Restraints
- Validation documentation burden:EU Annex 11 requires extensive IQ/OQ/PQ protocols for each software update, freezing vendor release cycles and inflating professional services costs.
- Air-gapped security mandates:Aerospace and defense contractors in classified facilities cannot adopt cloud architectures, fragmenting vendor R&D investment across incompatible deployment models.
- Open-source substitution:Document management modules from Apache and GitLab ecosystems erode pricing power in non-regulated industrial applications.
Strategic Opportunities
- Algorithm-driven change prediction:Machine learning integration with deviation management systems creates preemptive quality intervention capabilities in high-volume biologics manufacturing.
- Indian CDMO market:Contract development and manufacturing organizations in Hyderabad and Bengaluru lack validated change control infrastructure, representing greenfield SaaS adoption potential.
- EU AI Act risk classification:Automated change impact assessment tools fall under high-risk system definitions, creating compliance consulting and validation service revenue streams.
Industry Challenges
- CSV talent scarcity:Computer system validation specialists command premium salaries in Boston and Research Triangle Park, constraining implementation velocity for new deployments.
- Legacy ERP entanglement:SAP and Oracle manufacturing execution systems require custom API development for bidirectional change order synchronization, extending project timelines.
- Multi-site harmonization:Pharmaceutical firms with facilities across Massachusetts, Switzerland, and Singapore struggle to enforce consistent change review standards across divergent national inspectorate expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Change Control Management Software Market |
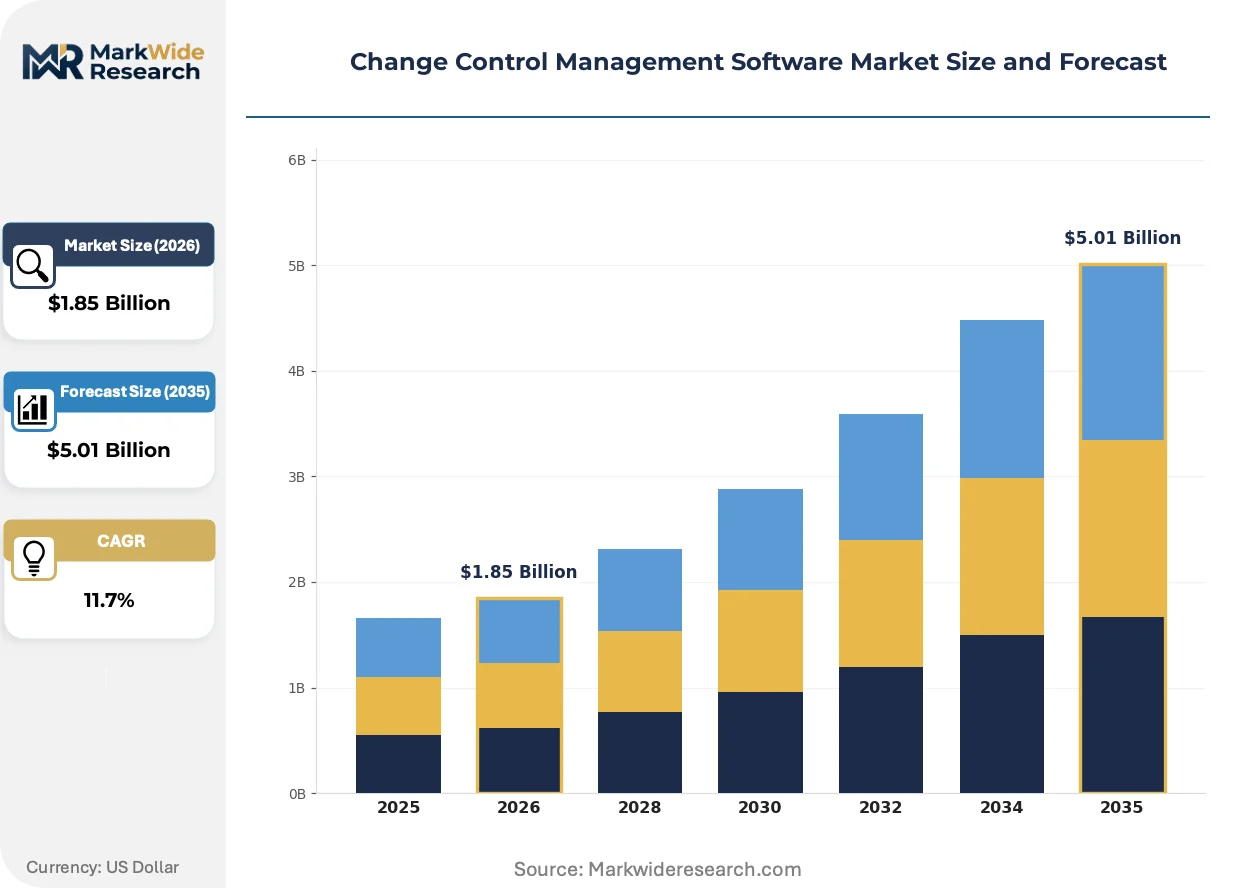
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Pharmaceuticals, Biotechnology, Manufacturing, Aerospace Functionality: Document Management, Workflow Automation, Compliance Tracking, Audit Management Integration Level: API Integration, Standalone, ERP Integration, CRM Integration |
| Companies Covered | MasterControl, Veeva Systems, Oracle, SAP, IBM, Siemens, TrackWise, Greenlight Guru, ComplianceQuest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Change Control Management Software Market Strategic Shifts
Artificial intelligence is penetrating deviation root-cause analysis, compressing investigation timelines from weeks to days and redefining competitive differentiation beyond traditional workflow automation.
Natural language processing engines trained on historical CAPA records now auto-classify change request severity and route approvals based on semantic risk scoring. Large pharmaceutical manufacturers in New Jersey and Basel are piloting these systems for process parameter modifications. This capability is rendering obsolete static rule-based routing matrices that required manual configuration for each product line.
EMA's 2024 revision to Annex 11 guidance explicitly addresses cloud infrastructure qualification, permitting multi-tenant SaaS architectures for GxP applications under specific contractual controls. European biotechnology firms are accelerating migration timelines accordingly. German and Swiss quality departments now demand vendor-provided shared responsibility models that delineate validation burden between software supplier and pharmaceutical operator.
Subscription-based pricing with usage-scaled tiers is displacing perpetual license models among emerging biotechnology firms with variable pipeline throughput. These buyers prioritize operational expenditure flexibility over capital asset ownership. The shift is most pronounced in San Diego and Cambridge, Massachusetts, where venture-backed startups negotiate annual contracts with validation-included service bundles rather than purchasing on-premises installations.
Change Control Management Software Market Segmentation
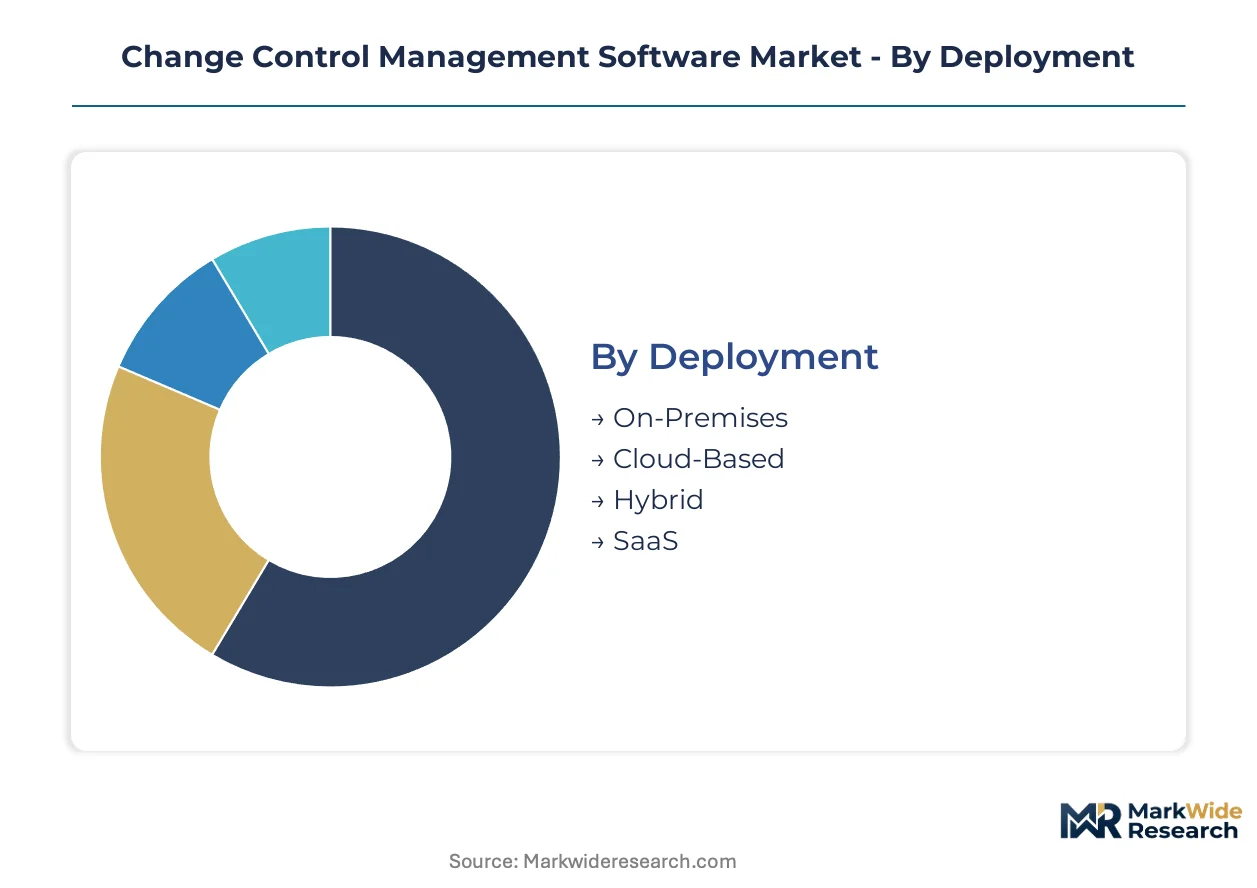
Change control management software segments reflect divergent regulatory tolerance for external infrastructure and varying integration complexity across quality operations. Deployment models and functionality tiers determine capital intensity, while end-user verticals impose distinct validation protocols that reshape product architecture.
Deployment:
Mature on-premises installations coexist with emerging cloud-native architectures as regulatory bodies issue updated qualification guidance.
- On-Premises:Air-gapped installations run on validated hardware within facility-controlled data centers. Aerospace contractors in classified facilities and defense manufacturing sites across the United States and Germany mandate this architecture to satisfy security clearance requirements that prohibit external data transmission.
- Cloud-Based:Multi-tenant SaaS platforms deliver remote accessibility and elastic compute scaling for distributed quality teams. Mid-size biotechnology firms in Cambridge, Massachusetts and Basel prioritize these deployments to eliminate capital expenditure on validated infrastructure while maintaining FDA 21 CFR Part 11 compliance through vendor-managed qualification documentation.
- Hybrid:Split architectures isolate sensitive manufacturing execution data on-premises while routing administrative workflows through cloud interfaces.
- SaaS:Subscription-native platforms embed validation services and continuous compliance updates within recurring fees.
On-Premises handles the majority of throughput in regulated defense applications; Cloud-Based is gaining share fastest as EMA Annex 11 revisions legitimize qualified multi-tenant infrastructure.
End User:
Customer type determines pricing tolerance and implementation complexity based on regulatory exposure and quality system maturity.
- Pharmaceuticals:Large molecule manufacturers and generic drug producers deploy comprehensive change control suites to manage FDA validation protocols for process modifications, equipment transfers, and specification updates across multi-site networks.
- Biotechnology:Cell therapy and gene editing firms in San Diego and Research Triangle Park favor configurable SaaS platforms with rapid deployment cycles to accommodate pipeline volatility and investor-driven milestone pressure.
- Manufacturing:Industrial equipment producers and automotive suppliers apply change control to engineering revision management with lighter validation burdens than life sciences.
- Aerospace:FAA-regulated contractors and EASA-certified suppliers require traceability systems that interface with configuration management databases for airworthiness certification maintenance.
Pharmaceuticals contributes the dominant revenue base; Biotechnology is expanding most quickly on venture-funded infrastructure buildouts.
Functionality:
Feature depth correlates with professional services attachment and renewal pricing power in competitive evaluations.
- Document Management:Centralized repositories with version control, metadata tagging, and retention scheduling form the foundational layer for electronic quality records. Pharmaceutical quality departments in New Jersey and Basel demand these capabilities to satisfy FDA inspection readiness requirements for deviation investigation files.
- Workflow Automation:Configurable routing engines with conditional logic and escalation timers replace manual approval chains. Biotechnology operations managers prioritize these tools to compress change request cycle times from weeks to days during critical manufacturing campaigns.
- Compliance Tracking:Real-time dashboards monitor open change orders against regulatory deadlines and training completion status.
- Audit Management:Structured inspection response modules with evidence linking and corrective action tracking streamline regulatory encounters.
Document Management anchors installed base retention; Workflow Automation shows the steepest expansion trajectory on operational efficiency mandates.
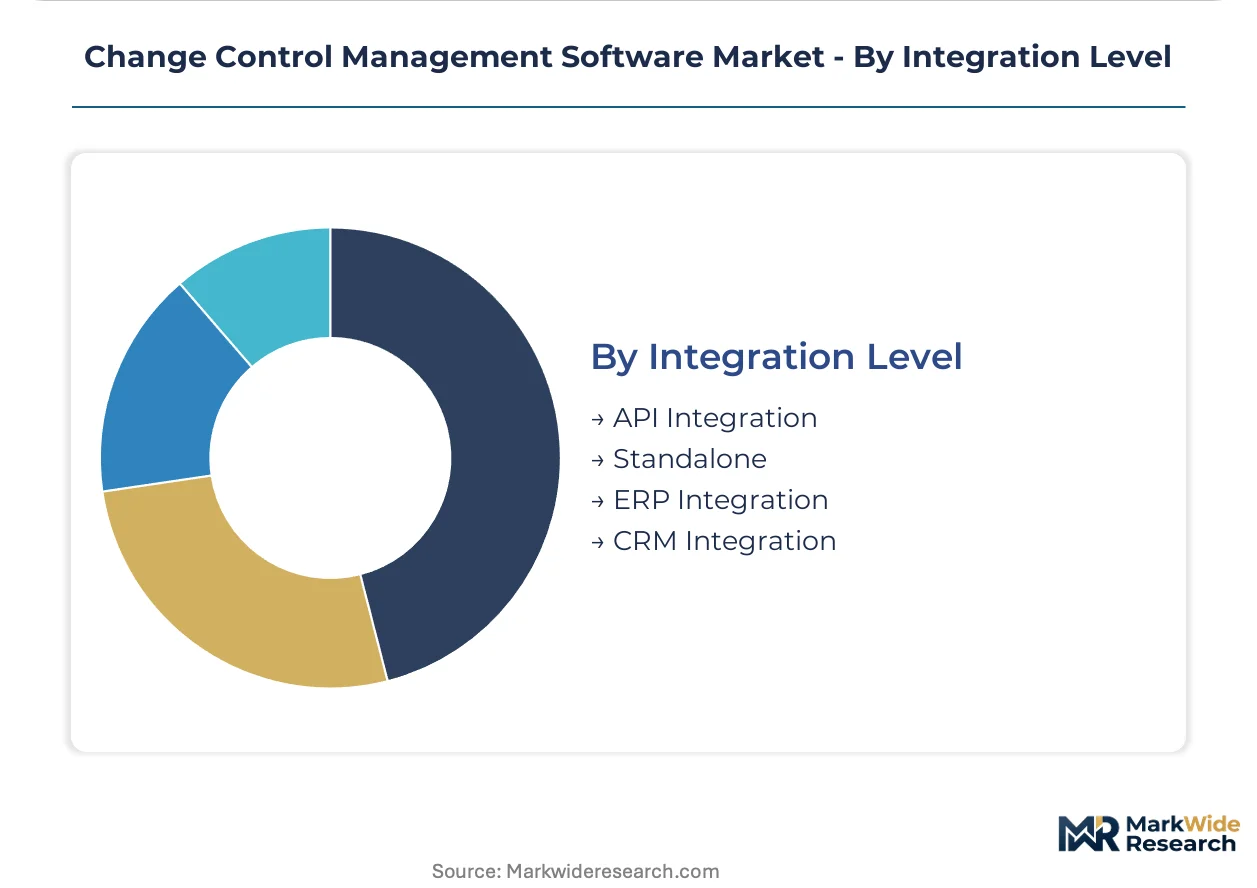
Integration Level:
Connectivity depth determines implementation timeline and total cost of ownership in enterprise environments.
- API Integration:RESTful and SOAP interfaces enable bidirectional data exchange with laboratory information management systems and manufacturing execution platforms. Quality informatics teams at Swiss and German pharmaceutical sites favor this approach to preserve existing system investments while layering modern change control capabilities.
- ERP Integration:Native connectors to SAP and Oracle manufacturing modules synchronize change orders with production scheduling and inventory allocation. Large pharmaceutical manufacturers with complex supply chains require this tight coupling to prevent specification mismatches across global distribution networks.
- Standalone:Self-contained deployments operate without external system dependencies for smaller quality departments.
- CRM Integration:Customer-facing change notification pipelines link quality decisions to field service and complaint handling workflows.
ERP Integration commands premium pricing in enterprise accounts; API Integration is climbing fastest on interoperability demands from digitally mature quality organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA validation protocols anchor demand concentration in the United States, while EMA Annex 11 revisions and German Mittelstand expansion reshape European adoption curves. Cloud migration accelerates across Swiss pharmaceutical clusters and Indian CDMO corridors as regulatory guidance clarifies qualified infrastructure requirements.
United States
Pharmaceutical manufacturers in New Jersey and Massachusetts drive enterprise deployments to satisfy FDA 21 CFR Part 11 electronic signature mandates. The FDA's digital health precertification pilots create compliance uncertainty for algorithm-driven change prediction tools. San Diego and Cambridge biotechnology clusters prioritize SaaS platforms with rapid deployment cycles to accommodate pipeline volatility.
Germany
Mid-size life sciences firms in Baden-Württemberg and Bavaria accelerate SaaS adoption to avoid capital expenditure on validated data centers. EMA Annex 11 revisions legitimize qualified multi-tenant infrastructure for GxP applications. Stuttgart and Munich quality departments demand vendor-provided shared responsibility models delineating validation burden.
Switzerland
Basel pharmaceutical headquarters require ERP-integrated change control to synchronize multi-site manufacturing specifications across global distribution networks. Swissmedic inspection guidance tightens documentation requirements for electronic quality records. The Basel biotech corridor pilots natural language processing engines for automated change request severity classification.
India
Contract development and manufacturing organizations in Hyderabad and Bengaluru lack validated change control infrastructure, representing greenfield SaaS adoption potential. CDSCO regulations increasingly align with ICH Q10 quality system guidelines. The Genome Valley and Bengaluru biotech clusters negotiate validation-included service bundles rather than capital-intensive on-premises installations.
United Kingdom
London and Cambridge life sciences firms navigate post-Brexit divergence between MHRA and EMA qualification requirements. The UK regulator's software as a medical device guidance creates compliance complexity for change control platforms with predictive analytics modules. The Golden Triangle research corridor sustains demand for workflow automation compressing approval timelines.
Change Control Management Software Market Competitive Environment
Enterprise software incumbents and specialized quality management vendors split the market into distinct capability tiers. Consolidation pressure intensifies as cloud-native challengers compress deployment cycles from quarters to weeks. Two strategic archetypes dominate: ERP-integrated platform providers embedding change workflows within broader enterprise systems, and standalone quality specialists offering purpose-built validation documentation suites. Competitive moves concentrate on M&A to acquire computer system validation expertise and strategic partnerships with biotechnology contract manufacturers.
Within the enterprise software tier, Oracle and SAP exemplify platform providers leveraging cloud infrastructure scale and native ERP connectors to anchor multi-site pharmaceutical deployments. MasterControl occupies a position representing specialized quality management vendors with deep field engineering relationships sustaining incumbent retention in FDA-regulated environments.
| Leading Market Players |
|---|
| MasterControl |
| Veeva Systems |
| Oracle |
| SAP |
| IBM |
| Siemens |
| TrackWise |
| Greenlight Guru |
| ComplianceQuest |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in cloud infrastructure across Germany and the United States is compressing SaaS margins for change control vendors while simultaneously expanding buyer negotiating leverage. This utilization dynamic forces suppliers to bundle validation services into subscription tiers and drives pharmaceutical quality departments toward multi-year contracts with price protection clauses.
Pricing Analysis
Geographic price spreads between North American and Indian deployments reach three-to-one multiples for equivalent functionality tiers. The dominant pricing model is subscription-based SaaS with validation-included service bundles, where price differentiation rests on FDA 21 CFR Part 11 certification grade and after-sales support depth. Cost compression in mid-market biotechnology tiers is intensifying because open-source document management alternatives erode pricing power for basic workflow modules. Emerging venture-backed firms in San Diego and Cambridge demonstrate highest price sensitivity, while Basel pharmaceutical headquarters show lowest sensitivity due to ERP integration complexity.
Supply Chain Analysis
Export control regimes under ITAR and EAR restrictions limit cloud infrastructure flows to aerospace contractors in classified United States facilities, fragmenting vendor architecture roadmaps. Software development concentrates in the United States, Germany, and India, with Indian CDMO corridors drawing from domestic engineering talent pools and German quality consulting expertise. Single-source vulnerability in computer system validation talent constrains implementation velocity across Boston and Research Triangle Park. Distribution runs through direct field engineering teams for enterprise pharmaceutical accounts and channel partners for mid-size biotechnology deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in change control management software are inflecting toward ecosystem orchestration as FDA digital health precertification pilots and EU AI Act risk classifications demand interoperability between quality systems and algorithmic prediction tools.
For Market Incumbents: Build data-network moats by embedding machine learning engines within deviation management workflows to capture proprietary CAPA pattern libraries. Incumbents should acquire computer system validation specialists in Boston and Research Triangle Park to address CSV talent scarcity, while anchoring multi-site deployments through SAP and Oracle ERP integration to defend against cloud-native challengers compressing deployment cycles. For New Entrants and Emerging Players: Hyderabad and Bengaluru CDMO underpenetration offers greenfield SaaS adoption potential where validated infrastructure is absent. New entrants should target biotechnology workflow automation in Indian contract manufacturing with validation-included pricing bundles, leveraging API-first architectures to bypass legacy ERP entanglement that slows incumbent implementations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as subscription pricing displaces perpetual licenses. Long-term viability favors vendors with embedded compliance consulting revenue streams; acquisition targets should demonstrate shared responsibility models for EU Annex 11 validation. The signal to watch is EMA guidance evolution on multi-tenant SaaS qualification, which would accelerate European biotechnology migration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ERP connectors to SAP manufacturing modules prevent specification mismatches across global pharmaceutical distribution networks. |
| Acquisition of Specialist Firm | Computer system validation boutiques in Boston command premium valuations due to talent scarcity constraining implementation velocity. |
| Strategic Partnership | Biotechnology contract manufacturers in Genome Valley negotiate validation-included service bundles reducing capital expenditure barriers. |
| Geographic Expansion | Indian CDMO corridors in Hyderabad lack qualified change control infrastructure, representing uncaptured SaaS subscription potential. |
| Product Launch | Natural language processing engines for automated severity classification render static rule-based routing matrices obsolete in Basel pilot programs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA inspection guidance documents, and ISO 9001 certification databases. Quality assurance directors, regulatory affairs leads at pharmaceutical manufacturers, CSV specialists, and biotechnology operations managers provided structured input across the United States, Germany, Switzerland, and India. Bottom-up deployment counts triangulate against top-down enterprise software expenditure estimates from SEC 10-K disclosures and European industry association reports.
Forecast inputs span deployment model adoption curves, functionality tier penetration rates, and vertical end-user growth differentials across the projection horizon. Segmentation dimensions include cloud versus on-premises architecture, organization size tier, integration complexity level, and regional regulatory cluster. CAGRs derive from fitted adoption curves benchmarked against comparable enterprise software transitions, with specific weighting for FDA 21 CFR Part 11 compliance upgrade cycles and EU AI Act implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native challengers or hyperscaler platform entrants would shift outcomes. Material shifts in EMA Annex 11 qualification guidance or FDA digital health precertification scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mining Simulation Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Packaged Software Market
Software & Services
API Design Software Market
Software & Services
Global Embedded Database Management Systems Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Global Diagram Software Market
Software & Services
ID Photo Software Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Global UIUX Software Market
Software & Services
HVAC Solution Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
Digital Customer Onboarding Software Market
Software & Services
Sports Production Software Market
Software & Services
Asia-Pacific Text to Speech (TTS) Software Market