
 Dog Vest Market | 2026-2036
Dog Vest Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Vest Market Analytics
Subscription-based replacement programs for tactical K9 gear is restructuring how law enforcement and military buyers budget for protective equipment. Ruffwear Inc. leverages direct-to-consumer channels to sustain premium positioning in the recreational trail segment. Julius-K9 dominates the European working-dog sector through specialized harness-vest hybrids engineered for patrol and service applications. Hurtta Oy anchors Nordic markets with thermal designs suited to subarctic training conditions.
A dog vest is a fitted torso covering for canines, typically constructed from woven nylon or polyester with adjustable strap systems and rated load-bearing points, designed to provide weather protection, visibility enhancement, ballistic defense, or equipment carriage. Insulated vests lead cold-climate revenue pools due to material density and seasonal replacement cycles, while tactical vests command the highest unit margins through ballistic panel integration and custom fitting protocols. Reflective vests represent the fastest-growing functional category as urban leash-law enforcement expands and nighttime visibility mandates tighten across municipalities.
The US Consumer Product Safety Commission monitors textile flammability in pet apparel, while the EU REACH framework restricts hazardous substance migration from coated fabrics into animal dermal contact zones. The FDA's Center for Veterinary Medicine evaluates claims tied to therapeutic or anxiety-reducing vest designs that blur into medical device territory. Stakeholders must monitor how diverging chemical safety thresholds between North American and European jurisdictions reshape material sourcing and cross-border product certification requirements.
Market Dynamics
The EU REACH chemical safety standards are forcing manufacturers to reformulate flame-retardant coatings across nylon-based pet apparel, triggering material substitution cycles and cross-border certification complexity for suppliers serving multiple jurisdictions.
Growth Catalysts
- Working dog procurement:Military and search-and-rescue programs sustain demand for ballistic-rated tactical vests with standardized load-bearing specifications.
- REACH compliance migration:European chemical safety rules are accelerating adoption of bio-based polymer alternatives in coated fabric production.
- Urban visibility mandates:Municipal leash-law enforcement is tightening nighttime safety requirements for recreational canines in densely populated districts.
Market Restraints
- Ballistic panel input costs:Aramid fiber and ceramic plate supply concentration in specialty chemical producers creates margin pressure for tactical vest assemblers.
- Cross-jurisdiction certification friction:Diverging flammability standards between the US Consumer Product Safety Commission and EU authorities multiply testing burdens.
- Human-grade wearable substitution:Adapted infant carriers and modified outdoor gear compete at the economy tier of the recreational segment.
Strategic Opportunities
- Subscription replacement models:Law enforcement agencies are adopting recurring procurement contracts for K9 gear refresh cycles rather than capital-intensive bulk purchases.
- Therapeutic anxiety vest claims:Designs incorporating pressure-distribution engineering are approaching FDA Center for Veterinary Medicine medical device classification pathways.
- Direct-to-consumer channel expansion:Premium recreational brands are bypassing specialty retail to capture margin through owned digital storefronts.
Industry Challenges
- Custom fitting protocols:Tactical vest orders require individualized canine measurement workflows that resist mass-production economics.
- Ballistic certification timelines:NIJ-rated panel validation extends product development cycles for law enforcement suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Vest Market |
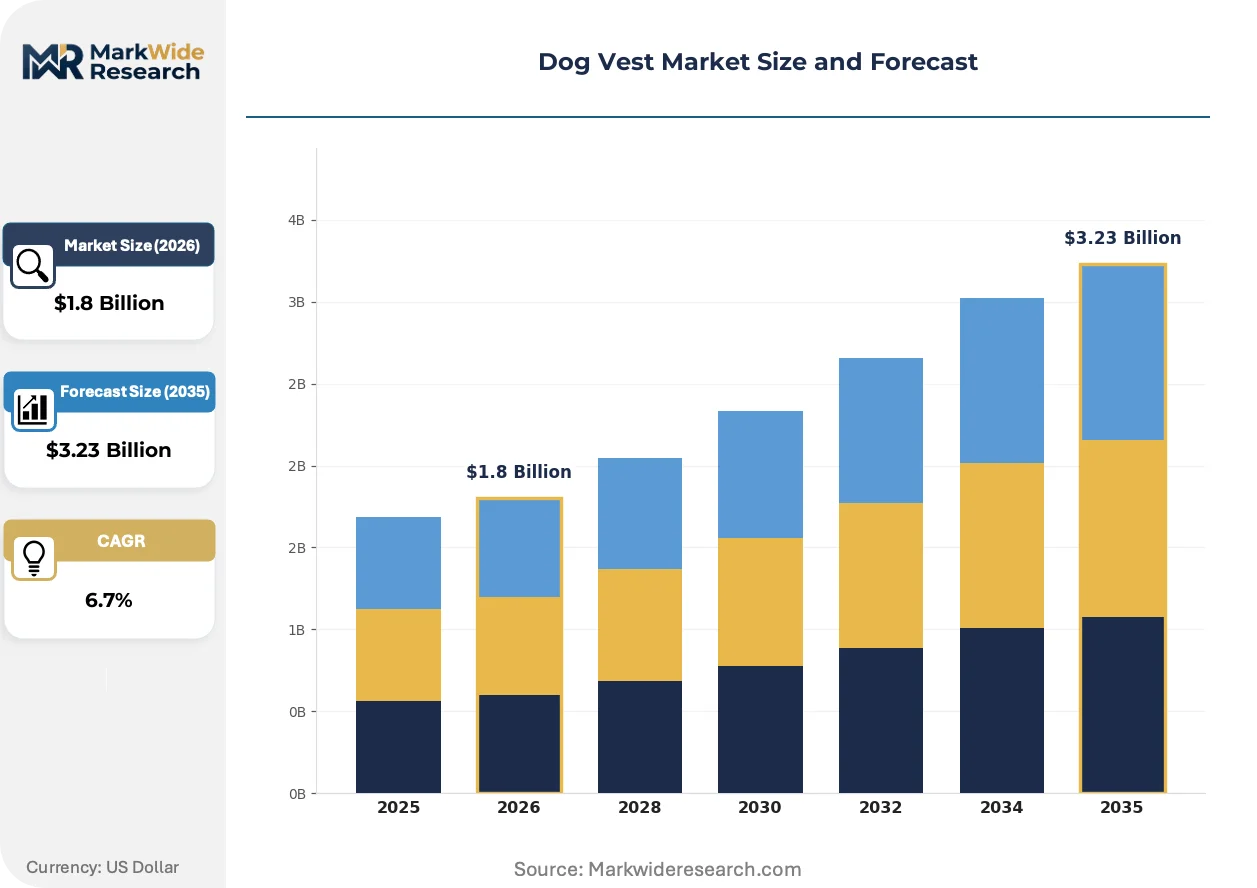
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight Vest, Insulated Vest, Reflective Vest, Tactical Vest Size: X-Small, Small, Medium, Large Material: Nylon, Polyester, Fleece, Cotton Functionality: Waterproof, Warmth, Safety, Fashion |
| Companies Covered | Ruffwear Inc., Hurtta Oy, Kurgo, Julius-K9, PetSafe, RC Pets, Gooby Pet Fashion, TRIXIE Heimtierbedarf GmbH & Co. KG, Illumiseen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Vest Market Evolving Landscape
Material science advances and procurement model restructuring are converging to reshape competitive positioning across protective, recreational, and therapeutic vest categories.
Smart textile technology is integrating conductive thread networks for biometric monitoring into working dog vests. Military K9 handlers and search-and-rescue coordinators are piloting these systems for real-time canine vital sign tracking during extended deployments. The technology is integrating physiological data transmission into standard tactical load-bearing platforms, compressing the distinction between protective gear and mobile health infrastructure.
REACH chemical safety enforcement is restricting halogenated flame retardants in coated nylon fabrics across European markets. Manufacturers serving EU jurisdictions must reformulate polymer treatments or source alternative chemistries from compliant suppliers. The restriction most affects insulated cold-climate designs where thermal protection historically relied on legacy coating systems.
Recreational buyers are consolidating purchases through veterinary clinic and trainer-affiliated channels rather than independent pet retailers. Premium vest brands are establishing professional endorsement networks that displace traditional specialty store distribution. This channel rotation is most visible in the United States, where direct relationships with canine behaviorists and sporting dog trainers now drive high-margin insulated and trail-oriented product selection.
Dog Vest Market Segmentation
Dog vest procurement patterns diverge sharply between institutional buyers managing equipment refresh cycles and recreational owners responding to seasonal triggers. Understanding these replacement rhythms clarifies where manufacturers must align production capacity with predictable demand windows.
Product Type:
Upgrade cycles vary dramatically by use intensity, with working dog programs operating on fixed replacement schedules while recreational buyers respond to wear patterns and climate shifts.
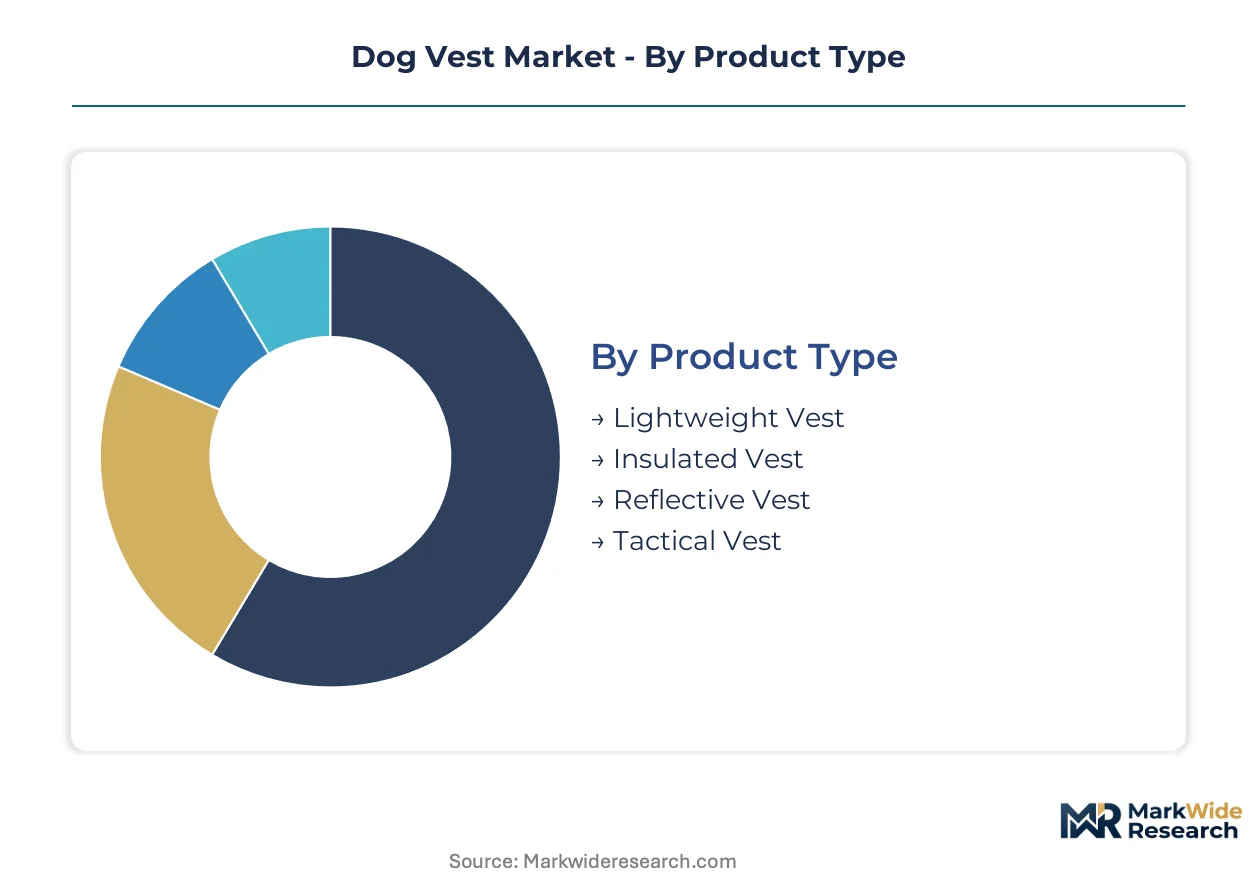
- Tactical Vest:Ballistic-rated construction integrates aramid fiber panels and modular load-bearing points for military and law enforcement K9 units. Procurement concentrates in the United States where federal K9 program funding sustains standardized acquisition protocols and recurring replacement contracts.
- Insulated Vest:Dense synthetic fill or fleece-lined designs address cold-climate working conditions and recreational winter activity. Nordic markets and subarctic training regions drive seasonal volume spikes tied to temperature thresholds rather than calendar replacement.
- Lightweight Vest:Minimal coverage designs prioritize breathability and unrestricted movement for temperate conditions.
- Reflective Vest:High-visibility striping and phosphorescent materials target urban leash-law compliance and nighttime safety mandates.
Tactical vest sits at the top of the volume ranking, with reflective vest climbing the fastest.
Size:
Canine morphology varies substantially across breed populations, forcing inventory breadth that strains mass-production economics.
- Large:Reinforced construction and expanded load-bearing capacity serve German Shepherds, Belgian Malinois, and other working breeds dominant in military and search-and-rescue programs. United States K9 unit procurement standardizes around these dimensions, creating volume concentration that rewards dedicated tooling investments.
- Medium:Adjustable strap systems accommodate the broadest breed cross-section including Labradors, Border Collies, and mixed working breeds. Veterinary clinic channels in the United States increasingly steer recreational buyers toward this mid-range inventory to minimize fit-related returns.
- Small:Reduced-scale hardware and lighter materials address terrier breeds and companion animals.
- X-Small:Miniaturized construction targets toy breeds with proportionally different weight distribution challenges.
Large size dominates institutional procurement volume, with medium size expanding most quickly through veterinary-affiliated retail channels.
Material:
REACH chemical safety enforcement is restructuring material sourcing decisions, particularly for coated fabrics previously reliant on restricted flame-retardant chemistries.
- Nylon:Woven polyamide construction delivers abrasion resistance and tensile strength for tactical and trail applications. EU manufacturers must now reformulate legacy coating systems or source compliant alternatives, adding certification overhead for cross-border suppliers.
- Polyester:Hydrophobic fiber properties and dye stability support high-visibility applications and extended outdoor exposure. United States recreational buyers favor this material for cost efficiency in seasonal replacement purchases.
- Fleece:Synthetic pile construction traps thermal layers in cold-climate designs.
- Cotton:Natural fiber content appeals to sustainability-conscious segments despite moisture retention limitations.
Nylon commands the highest share in working-dog applications, with polyester gaining ground fastest in price-sensitive recreational segments.
Functionality:
Performance claims are drawing heightened regulatory scrutiny where therapeutic or medical-adjacent benefits blur into device classification territory.
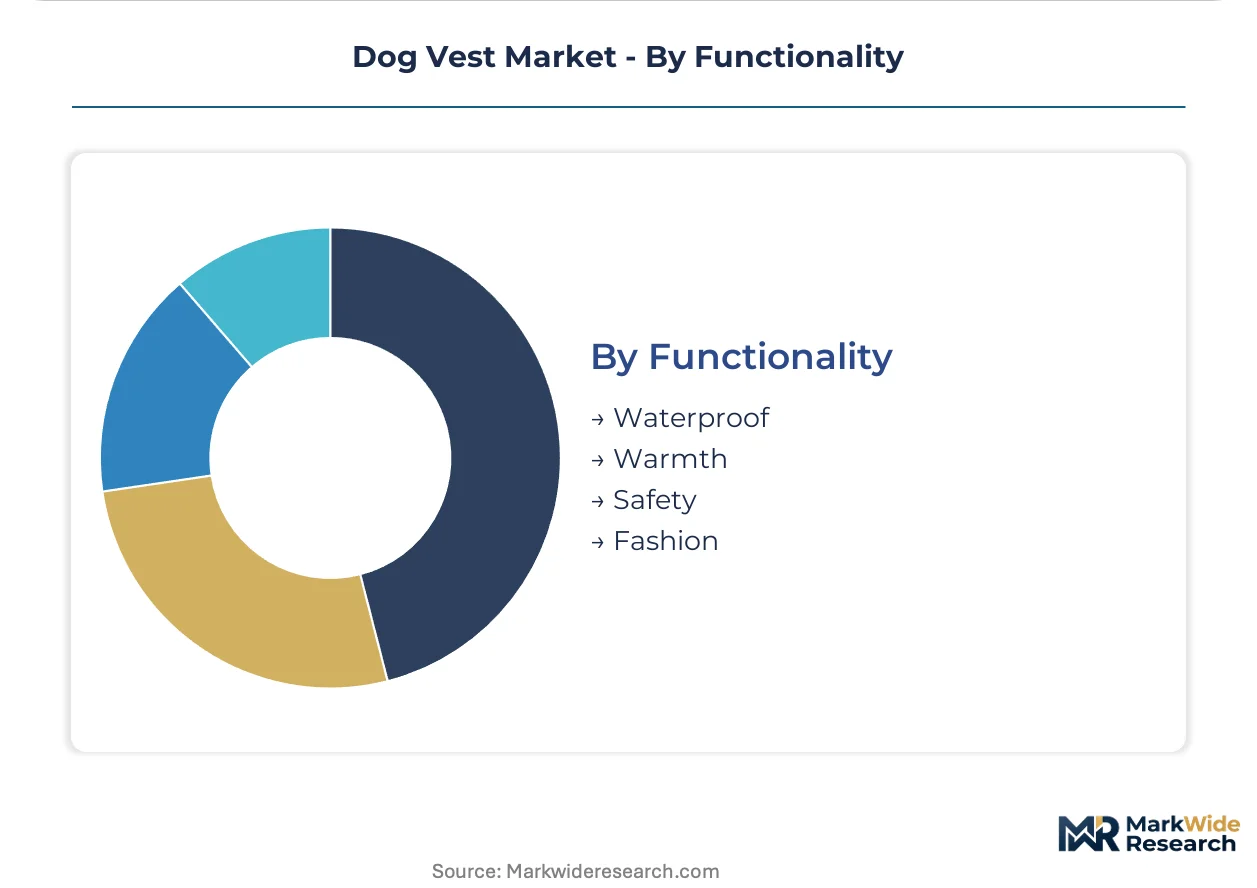
- Safety:Visibility enhancement and protective coverage address collision risk and environmental hazards. Municipal nighttime leash-law enforcement in United States urban districts is tightening compliance requirements that mandate reflective or illuminated elements.
- Warmth:Thermal retention engineering targets cold-stress prevention in working deployments and recreational winter activity. Subarctic training conditions in Nordic regions sustain premium pricing for designs validated at temperature extremes.
- Waterproof:Membrane or coating-based moisture barriers protect underlying insulation and reduce drying time.
- Fashion:Aesthetic-driven designs prioritize colorways and styling over technical performance specifications.
Safety functionality leads institutional procurement volume, with warmth applications showing steepest expansion trajectory in cold-climate recreational markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States K9 program funding dwarfs comparable working-dog procurement in Germany, yet both markets are tightening chemical safety standards that reshape material sourcing across their supplier bases.
United States
Federal K9 unit appropriations and municipal police department gear refresh cycles sustain institutional demand for ballistic-rated tactical vests. The Consumer Product Safety Commission monitors textile flammability standards for pet apparel sold across state lines. Manufacturing clusters in the Pacific Northwest and Southeast concentrate recreational vest production for direct-to-consumer brands.
Germany
Patrol dog programs within federal and state police forces drive standardized harness-vest hybrid procurement. ECHA enforces REACH chemical safety restrictions on halogenated flame retardants in coated nylon fabrics. Industrial concentration in Bavaria and Baden-Württemberg hosts specialized textile finishing operations serving adjacent European markets.
United Kingdom
Search-and-rescue charity networks and private security canine units generate working-dog vest demand outside formal police procurement. The UK's post-EU chemical regulatory framework maintains alignment with REACH substance restrictions while operating independent enforcement mechanisms. Manufacturing activity clusters in the Midlands and North England around legacy textile engineering capabilities.
Finland
Subarctic military and border patrol dog training conditions create specialized demand for thermal retention engineering in extreme cold. Finnish chemical safety authorities apply EU REACH standards with additional national notification requirements for polymer coatings. The Helsinki-Tampere corridor anchors Nordic design studios developing cold-climate recreational products for export.
Australia
Working dog programs in mining security and rural pest control sustain demand for durable load-bearing vest designs. The Therapeutic Goods Administration evaluates claims for anxiety-reducing pressure vests that approach medical device classification. Manufacturing concentrates in Victoria and New South Wales with supply chains oriented toward Asia-Pacific export markets.
Dog Vest Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium recreational labels capturing margin through owned digital channels while tactical suppliers depend on institutional procurement relationships. The vendor base organizes around three archetypes: direct-to-consumer lifestyle brands, working-dog equipment specialists, and private-label contract assemblers serving mass retail. Geographic expansion and portfolio diversification represent the dominant competitive moves as participants seek insulation from seasonal demand fluctuations.
Within the working-dog equipment tier, Julius-K9 and Hurtta Oy exemplify regional specialists that have extended influence beyond their home European markets. Ruffwear Inc. occupies a position on the premium recreational vector, demonstrating how direct-to-consumer channel control sustains pricing power in trail and outdoor lifestyle segments. These three anchors illustrate divergent strategic paths: harness-vest hybrid engineering for institutional buyers, thermal specialization for climate-extreme conditions, and lifestyle brand building for discretionary pet owners.
| Leading Market Players |
|---|
| Ruffwear Inc. |
| Hurtta Oy |
| Kurgo |
| Julius-K9 |
| PetSafe |
| RC Pets |
| Gooby Pet Fashion |
| TRIXIE Heimtierbedarf GmbH & Co. KG |
| Illumiseen |
| Others |
Value Network & Pricing Analysis
Specialized textile finishing labor concentrates in Bavaria and Baden-Württemberg, where REACH-compliant coating expertise commands wage premiums that widen spreads between European-manufactured tactical vests and Asian-assembled recreational alternatives.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for polyester-based recreational vests, compressing margins for mid-tier assemblers. Three-tier pricing structure across premium, standard, and economy levels separates NIJ-certified tactical platforms from veterinary-channel insulated designs and mass-retail reflective accessories. Pricing pressure stems from aramid fiber supply concentration among specialty chemical producers. Recreational buyers exhibit highest price sensitivity, while law enforcement procurement tolerates premium positioning for ballistic-rated configurations.
Supply Chain Analysis
Direct-to-consumer channels handle premium recreational brand demand, while institutional procurement flows through specialized working-dog equipment distributors. Manufacturing concentrates in China, Vietnam, and Germany, with raw material dependencies spanning woven nylon from Zhejiang province, aramid fibers from DuPont-dominated supply channels, and REACH-compliant polymer coatings from Bavarian chemical finishers. Single-source vulnerability in ballistic panel substrates creates disruption exposure. Distribution runs through veterinary clinic networks, direct digital storefronts, and law enforcement equipment contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: European chemical compliance costs elevate production economics there, while Asian manufacturing maintains cost advantages for non-regulated recreational tiers.
For Market Incumbents: Anticipate REACH regulatory expansion into additional coating chemistries by securing bio-based polymer supplier relationships ahead of reformulation mandates. Deepen backward integration into textile finishing capabilities to defend margin position against specialty chemical producer pricing power. Prioritize subscription-based K9 gear replacement contracts to lock institutional procurement relationships against emerging contract manufacturers.
For New Entrants and Emerging Players: Launch via veterinary clinic endorsement networks to bypass saturated specialty retail channels and capture recreational buyer trust through professional recommendation. Target medium-size insulated vest segments where adjustable-fit designs minimize inventory complexity and return rates. Exploit white-space in therapeutic anxiety vest categories approaching FDA Center for Veterinary Medicine classification pathways.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers serving mass retail without owned brand equity or certification infrastructure. Five-to-ten year viability favors participants with institutional procurement relationships and REACH-compliant material sourcing locked in. Monitor ECHA substance restriction proposals as inflection indicators for material substitution investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | Bio-based polymer adoption satisfies ECHA restrictions while opening premium positioning in EU markets. |
| Subscription Replacement Program Launch | Recurring K9 gear contracts transform capital purchases into predictable operational budgets for agencies. |
| Direct-to-Consumer Channel Expansion | Owned digital storefronts capture margin otherwise surrendered to specialty pet retail intermediaries. |
| Smart Textile Biometric Integration | Conductive thread networks for canine vital sign monitoring compress protective gear and health infrastructure boundaries. |
| Veterinary Clinic Distribution Partnership | Professional endorsement networks displace independent pet retailers in premium recreational vest selection. |
Research Methodology
Multiple input streams — K9 program procurement officers, textile finishing plant managers, veterinary clinic buyers, and specialty pet retail category managers — were reconciled against customs trade records, ECHA substance restriction databases, and SEC filings from listed apparel manufacturers. Bottom-up unit economics from individual product categories were triangulated against top-down market sizing derived from federal K9 appropriations and pet industry association shipment data.
Data-stream reconciliation across product type, size tier, material composition, and functional application dimensions anchored volume and value projections across the analysis window. CAGRs were derived from fitted growth curves applied to segment-specific replacement cycle frequencies and procurement pattern shifts. Forecast inputs incorporated REACH compliance migration timelines, smart textile adoption curves in military pilot programs, and channel rotation toward veterinary-affiliated distribution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA substance bans or aramid fiber supply disruptions. Projections reflect assumptions regarding sustained federal K9 funding levels and gradual REACH regulatory expansion without retroactive inventory obsolescence triggers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
France Pet Food Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Global Pet Companion Robots Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
Aquarium Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
Pet Pens Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Pet Car Seat Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
UK Pet Training Services Market